
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Butyraldehyde market Size 2024 | USD 324.97Million |
| Butyraldehyde market, CAGR | 4.28% |
| Butyraldehyde market Size 2032 | USD 465.80 Million |
Market Overview
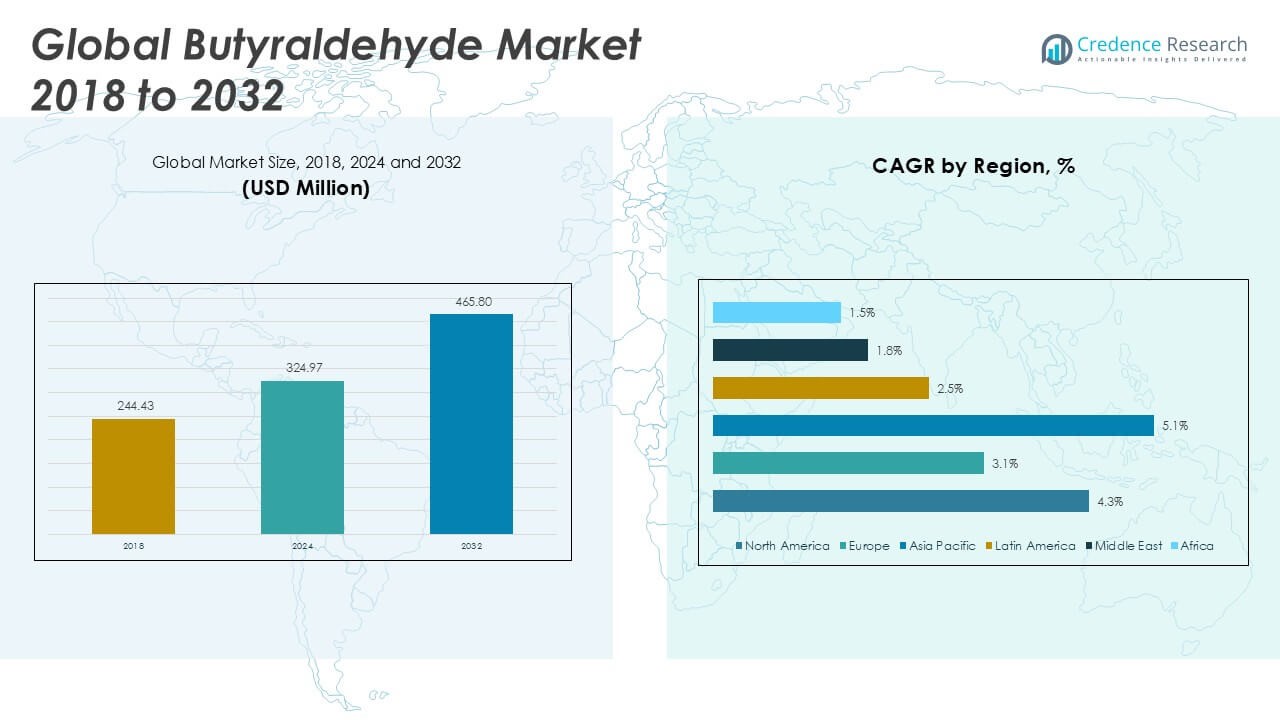
The Butyraldehyde market size was valued at USD 244.43 million in 2018 and increased to USD 324.97 million in 2024. It is anticipated to reach USD 465.80 million by 2032, growing at a CAGR of 4.28% during the forecast period.
The Butyraldehyde market is led by key players such as BASF SE, Mitsubishi Chemical Corporation, KH Neochem Co., Ltd., Eastman Chemical Company, and Dow Chemical Company, which collectively hold a significant share of the global market through their integrated production capacities, broad product portfolios, and strategic investments. These companies focus on technological innovation and expansion in high-demand sectors like plasticizers, coatings, and agrochemicals. Regionally, Asia Pacific dominates the Butyraldehyde market, accounting for 43.7% of the global market share in 2024, driven by rapid industrialization, infrastructure development, and strong demand in China and India. North America and Europe follow, supported by robust manufacturing and chemical sectors.
Market Insights
- The global Butyraldehyde market was valued at USD 324.97 million in 2024 and is projected to reach USD 465.80 million by 2032, growing at a CAGR of 4.28% during the forecast period.
- Rising demand for plasticizers, especially 2-Ethylhexanol (2EH), and growth in construction, automotive, and agrochemical sectors are major drivers fueling market expansion.
- A noticeable trend is the increasing shift toward sustainable and bio-based chemical production, along with expanding use in coatings and pharmaceutical intermediates.
- The market is moderately consolidated with key players like BASF SE, Mitsubishi Chemical Corporation, and Dow Chemical Company focusing on innovation, regional expansion, and capacity enhancement.
- Asia Pacific led with 43.7% market share in 2024, followed by North America (29.3%) and Europe (18.7%). 2-Ethylhexanol dominated by product type, while Paints and Coatings held the highest share by application, supported by growing infrastructure and industrial activities.
Market Segmentation Analysis:
By Product Type
In the Butyraldehyde market, 2-Ethylhexanol (2EH) emerged as the dominant sub-segment, accounting for the largest market share in 2024. Its wide application in plasticizer manufacturing, particularly dioctyl phthalate (DOP), drives its demand in the production of flexible PVC used in construction and automotive sectors. The rising need for high-performance lubricants and coatings further supports the growth of this sub-segment. N-Butanol and Polyvinyl Butyral (PVB) also contribute significantly, with PVB gaining traction due to its role in laminated safety glass for automotive and construction applications.
- For instance, OQ Chemicals (formerly OXEA GmbH) operates a 60,000-ton-per-year 2-EH production facility in Marl, Germany, demonstrating its strong focus on this key derivative.
By Application Paints and Coatings held the largest share in the Butyraldehyde market by application in 2024. The increasing construction and infrastructure development activities across emerging economies, coupled with growing demand for protective and decorative coatings, have bolstered this segment. Butyraldehyde derivatives like 2EH and N-Butanol are essential intermediates in coating formulations, enhancing performance characteristics such as durability and adhesion. Agrochemicals followed closely, driven by rising agricultural output and the need for improved crop protection solutions, especially in Asia-Pacific and Latin America.
- For instance, BASF SE operates a N-Butanol plant in Ludwigshafen with an annual capacity of 290,000 metric tons, primarily supporting the coatings and agrochemical industries.
By Distribution Channel The Building and Construction segment led the market by distribution channel in 2024, capturing the highest share due to its high consumption of butyraldehyde-based products such as plasticizers, paints, and adhesives. Rapid urbanization, infrastructure investment, and real estate expansion globally continue to drive product demand. The Automotive sector also registered notable growth, benefiting from the increasing use of laminated safety glass and specialty coatings. Meanwhile, healthcare and agriculture sectors are witnessing moderate but steady growth, supported by pharmaceutical manufacturing and modern farming techniques.
Key Growth Drivers
Expanding Demand from the Plasticizer Industry
The growing consumption of plasticizers, particularly dioctyl phthalate (DOP), is a major driver for the Butyraldehyde market. Butyraldehyde serves as a key precursor for 2-Ethylhexanol (2EH), which is essential in plasticizer production. With increasing demand for flexible PVC in construction, automotive, and consumer goods, the use of DOP and related plasticizers is rising steadily. This has led to a surge in butyraldehyde production to support downstream applications, particularly in Asia-Pacific where infrastructure and industrial growth remain strong.
- For instance, LG Chem’s 2EH unit in Yeosu, South Korea, has a production capacity of 160,000 metric tons annually, reflecting the scale required to meet rising regional demand.
Rising Applications in Paints and Coatings
Butyraldehyde-based derivatives, such as N-Butanol and 2EH, are integral to the paints and coatings sector, which is witnessing robust growth globally. Expanding urbanization, infrastructure projects, and housing developments are fueling the demand for architectural and industrial coatings. These coatings rely on high-performance solvents and intermediates that butyraldehyde derivatives provide. Emerging economies are especially contributing to this demand due to increased construction activity and supportive government initiatives aimed at urban expansion and industrial modernization.
- For instance, Eastman Chemical Company’s Kingsport site produces over 120,000 metric tons of N-Butanol annually, much of which is used in coatings and industrial applications.
Growth in Automotive and Construction Sectors
The Butyraldehyde market benefits from the growth of the automotive and construction sectors, where its derivatives are used in products such as laminated glass, adhesives, and coatings. The push for lightweight, durable materials in automotive design and stringent safety standards has raised the need for Polyvinyl Butyral (PVB), a butyraldehyde-based product. Simultaneously, the construction sector requires durable, flexible, and weather-resistant materials, further driving demand. The dual growth in these industries strengthens the market outlook across developed and emerging regions.
Key Trends & Opportunities
Shift Toward Bio-based Butyraldehyde Production
A noticeable trend in the Butyraldehyde market is the transition toward bio-based production methods to reduce dependence on petrochemical feedstocks. Growing environmental regulations and sustainability goals are encouraging manufacturers to explore renewable sources and green chemistry approaches. Investments in R&D for cost-effective, eco-friendly production technologies present a significant opportunity. This shift not only aligns with global decarbonization efforts but also caters to the preferences of environmentally conscious consumers and industries.
- For instance, BASF SE has developed a process to produce butyraldehyde using bio-based synthesis gas derived from agricultural residues, with its pilot plant in Ludwigshafen capable of processing 4,000 metric tons of biomass feedstock annually into syngas for chemical intermediates.
Emerging Opportunities in Asia-Pacific Markets
Asia-Pacific continues to present vast opportunities for the Butyraldehyde market due to its rapid industrialization, population growth, and urban infrastructure expansion. Countries like China and India are investing heavily in construction, automotive manufacturing, and agriculture-all key application areas of butyraldehyde derivatives. The region’s relatively low production costs and growing chemical manufacturing base make it an attractive hub for global producers seeking to scale operations and meet increasing demand locally and internationally.
- For instance, KH Neochem Co., Ltd. operates a plant in Yokkaichi, Japan, with a butyraldehyde production capacity of 150,000 metric tons annually, primarily serving the Asia-Pacific market.
Key Challenges
Volatility in Raw Material Prices
The Butyraldehyde market faces significant challenges from fluctuating raw material prices, particularly propylene, a key feedstock. Global supply chain disruptions, geopolitical tensions, and crude oil price swings impact the cost structure of butyraldehyde production. This volatility affects profit margins and pricing strategies, compelling manufacturers to either absorb costs or pass them on to consumers, potentially reducing competitiveness.
Environmental and Regulatory Pressures
Stringent environmental regulations regarding emissions, waste disposal, and the use of hazardous chemicals pose compliance challenges for butyraldehyde manufacturers. Regulatory agencies in Europe and North America enforce rigorous safety standards and environmental policies, which increase operational costs. Companies must invest in cleaner technologies and adopt sustainable practices to align with these regulations, which may require significant capital and technological shifts.
Health and Safety Concerns in Handling
Butyraldehyde is a volatile organic compound with potential health and safety risks, including respiratory irritation and flammability. Managing its storage, handling, and transportation requires strict safety protocols and regulatory adherence. These concerns can limit its widespread adoption, especially in regions with less developed industrial infrastructure or limited enforcement of occupational health standards, thus constraining market growth.
Regional Analysis
Asia Pacific
Asia Pacific dominated the Butyraldehyde market in 2024 with a market size of USD 142.13 million, representing a 43.7% share of the global market. The region is projected to reach USD 216.60 million by 2032, growing at the fastest CAGR of 5.1%. In 2018, it accounted for USD 102.96 million. Rapid industrialization, strong growth in construction and automotive sectors, and expanding agrochemical production in countries like China, India, and South Korea continue to fuel demand for butyraldehyde and its derivatives. Government infrastructure investments and increasing consumer demand for durable goods further support market growth in the region.
North America
North America held the second-largest share in the Butyraldehyde market in 2024, reaching USD 95.15 million and accounting for 29.3% of the global market. With a CAGR of 4.3%, the regional market is expected to grow to USD 136.95 million by 2032, up from USD 72.68 million in 2018. The U.S. leads regional demand, supported by high consumption of plasticizers, coatings, and agrochemical intermediates. Technological advancements and the presence of major chemical manufacturers enhance production capabilities, while a stable construction sector and growing pharmaceutical applications help sustain long-term growth.
Europe
Europe contributed USD 60.84 million to the Butyraldehyde market in 2024, securing a 18.7% market share. It is projected to reach USD 79.76 million by 2032, growing at a CAGR of 3.1%, up from USD 48.26 million in 2018. Germany, France, and the UK are key contributors, with demand driven by the region’s strong automotive and coatings industries. Environmental regulations are encouraging the shift toward more sustainable butyraldehyde-based products, and investments in bio-based chemicals are shaping the market landscape. However, slower industrial output in some areas could moderate future growth.
Latin America
Latin America accounted for USD 13.57 million in 2024, with a 4.2% share of the global Butyraldehyde market. The region is expected to reach USD 16.95 million by 2032, growing at a CAGR of 2.5%, compared to USD 10.35 million in 2018. Brazil and Mexico lead regional consumption, driven by developments in the agriculture sector and rising demand for agrochemicals and flexible packaging. Limited industrial infrastructure poses challenges, but ongoing urbanization and regional trade development may open new opportunities for market expansion in niche segments.
Middle East
The Middle East Butyraldehyde market reached USD 7.45 million in 2024, holding a 2.3% share globally. It is expected to rise to USD 8.82 million by 2032 at a CAGR of 1.8%, up from USD 6.19 million in 2018. The market in this region is supported by downstream demand in construction and chemical processing sectors. However, overall growth remains modest due to limited domestic production capacity and dependency on imports. Strategic investments in industrial diversification and infrastructure may enhance future consumption of butyraldehyde derivatives.
Africa
Africa contributed the smallest share to the Butyraldehyde market in 2024, valued at USD 5.82 million and representing 1.8% of the global market. It is projected to reach USD 6.72 million by 2032, growing at a CAGR of 1.5% from USD 3.98 million in 2018. Market growth is restrained by underdeveloped industrial infrastructure and limited awareness of product applications. However, rising construction activity, improving healthcare access, and growth in agriculture across key economies like South Africa and Nigeria offer potential for gradual market development over the forecast period.
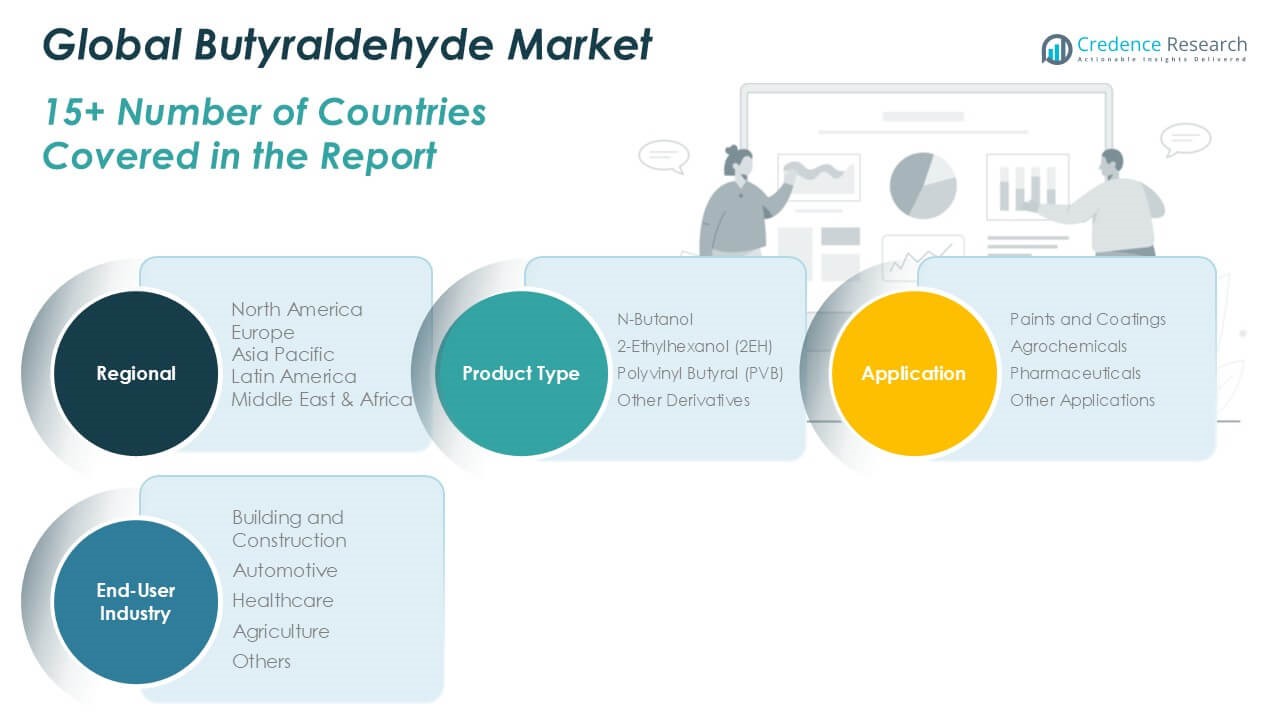
Market Segmentations:
By Product Type
- N-Butanol
- 2-Ethylhexanol (2EH)
- Polyvinyl Butyral (PVB)
- Other Derivatives
By Application
- Paints and Coatings
- Agrochemicals
- Pharmaceuticals
- Other Applications
By Distribution Channel
- Building and Construction
- Automotive
- Healthcare
- Agriculture
- Others
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Competitive Landscape
The competitive landscape of the Butyraldehyde market is characterized by the presence of several global and regional players focusing on product innovation, capacity expansion, and strategic partnerships. Leading companies such as BASF SE, Mitsubishi Chemical Corporation, Eastman Chemical Company, and Dow Chemical Company maintain a strong market position through integrated production capabilities and extensive distribution networks. Firms like KH Neochem Co., Ltd., OXEA GmbH, and Perstorp Holding AB are investing in technological advancements and environmentally sustainable production processes to meet evolving regulatory standards and consumer preferences. Smaller players, including Tokyo Chemical Industry Co., Ltd. and Loba Chemie Pvt Ltd, contribute by catering to niche markets and research-based applications. Key strategies include mergers, acquisitions, and joint ventures aimed at strengthening global reach and enhancing supply chain efficiency. The market remains moderately consolidated, with leading firms emphasizing cost competitiveness, product customization, and expansion in high-growth regions such as Asia Pacific to gain a competitive edge.
Key Player Analysis
- BASF SE
- Mitsubishi Chemical Corporation
- KH Neochem Co., Ltd.
- Eastman Chemical Company
- Tokyo Chemical Industry Co., Ltd.
- Dow Chemical Company
- OXEA GmbH
- Perstorp Holding AB
- Alfa Aesar
- Merck KGaA
- Thermo Fisher Scientific
- Loba Chemie Pvt Ltd
Recent Developments
- In January 2025, Perstorp announced a global price increase for butyraldehyde in response to rising feedstock costs. This move is expected to impact downstream industries by increasing production costs and potentially shifting market dynamics.
- In October 2024, Thermo Fisher Scientific is highlighted as a supplier in the butyraldehyde market, specifically for research and specialty applications. This recognition stems from their broad portfolio of chemicals and services used in various scientific fields, including pharmaceuticals and agrochemicals.
- In 2024, Eastman expanded its 2-Ethylhexanol (2-EH) production capacity at its Texas facility by 20,000 metric tons. This expansion was directly linked to the increased production of butyraldehyde derivatives. The expansion at the Longview, Texas site included a 25,000 metric ton increase in butyraldehyde capacity to support the 2-EH growth.
- In March 2023, BASF initiated a significant investment in a new butyraldehyde production facility in Germany, emphasizing the integration of cutting-edge technologies and optimized processes to improve efficiency and sustainability.
- In June 2022, Mitsubishi Chemical Corporation acquired Tokyo Chemical Industry's butyraldehyde business. This acquisition strengthened Mitsubishi Chemical Corporation's position and capacity in the butyraldehyde market. Butyraldehyde, also known as butanal, is an organic compound with the formula CH₃(CH₂)₂CHO. It is a colorless, flammable liquid with an unpleasant odor.
Market Concentration & Characteristics
The Butyraldehyde market exhibits a moderately concentrated structure, with a few key global players holding significant market shares. Companies such as BASF SE, Dow Chemical Company, and Mitsubishi Chemical Corporation dominate through vertically integrated operations and established distribution networks. It remains highly product-driven, with demand centered on derivatives like 2-Ethylhexanol and N-Butanol, which are widely used in plasticizers, coatings, and agrochemicals. The market is characterized by strong competition, with players focusing on capacity expansions, product innovation, and regional diversification to maintain their positions. It also reflects sensitivity to feedstock pricing and environmental regulations, especially in developed regions. Demand remains regionally skewed, with Asia Pacific accounting for the largest share due to its industrial growth and expanding end-user sectors.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Butyraldehyde market will continue expanding steadily, driven by growing demand for plasticizers in construction and automotive industries.
- Asia Pacific will remain the dominant regional market due to increasing industrialization and infrastructure development.
- 2-Ethylhexanol will retain its position as the leading product type due to its widespread use in flexible PVC applications.
- Rising consumption of coatings and paints will strengthen demand for butyraldehyde derivatives globally.
- Pharmaceutical and agrochemical industries will offer consistent growth opportunities through expanded chemical synthesis applications.
- Market players will invest in green chemistry and bio-based production to meet sustainability goals.
- Strategic mergers and acquisitions will shape competitive positioning and expand global reach.
- Technological advancements will improve production efficiency and reduce environmental impact.
- Regulatory compliance and environmental concerns will drive product innovation and process optimization.
- Growth in emerging economies will create new opportunities for manufacturers and distributors in the market.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Demand from the Plasticizer Industry
Butyraldehyde is a key precursor for 2-Ethylhexanol, which is essential in the production of plasticizers like dioctyl phthalate (DOP). The rising use of flexible PVC in construction, automotive, and consumer goods is driving up demand for butyraldehyde-based plasticizers, especially in rapidly industrializing regions.
Growth in Paints and Coatings Sector
Butyraldehyde derivatives such as N-Butanol and 2EH are vital intermediates in high-performance paints and coatings. The surge in construction and infrastructure projects, particularly in emerging economies, is fueling demand for durable and protective coatings, thereby boosting butyraldehyde consumption.
Rising Applications in Automotive and Construction
The automotive and construction industries utilize butyraldehyde derivatives in products like laminated safety glass, adhesives, and specialty coatings. Increasing safety standards and the push for lightweight, durable materials are expanding the use of butyraldehyde-based products in these sectors.
Shift Toward Bio-based and Sustainable Production
Environmental regulations and sustainability goals are prompting manufacturers to invest in bio-based butyraldehyde production methods. This trend is opening new market opportunities and aligning with global decarbonization efforts, attracting customers seeking greener chemical solutions.
Industrialization and Infrastructure Growth in Asia Pacific
Rapid industrialization, urbanization, and infrastructure development in countries like China and India are significantly increasing the demand for butyraldehyde and its derivatives. The region's expanding manufacturing base and lower production costs make it a key growth engine for the global market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Butyraldehyde Market?
What factors are driving the growth of the Butyraldehyde Market?
What are the key segments within the Butyraldehyde Market?
What are some challenges faced by the Butyraldehyde Market?
Who are the major players in the Butyraldehyde Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Paints and Coatings
- 1.2.2 Agrochemicals
- 1.2.3 Pharmaceuticals
- 1.2.4 Other Applications
- 1.3 By Product Type
- 1.3.1 N-Butanol
- 1.3.2 2-Ethylhexanol (2EH)
- 1.3.3 Polyvinyl Butyral (PVB)
- 1.3.4 Other Derivatives
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 324.97 million → 2032: USD 465.80 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Butyraldehyde Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Butyraldehyde Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Butyraldehyde Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Butyraldehyde Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Butyraldehyde Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Butyraldehyde Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Butyraldehyde Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Butyraldehyde Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 324.97 million → 2032: USD 465.80 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Butyraldehyde Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Paints and Coatings
- 12.3.7.2 Agrochemicals
- 12.3.7.3 Pharmaceuticals
- 12.3.7.4 Other Applications
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 N-Butanol
- 12.4.7.2 2-Ethylhexanol (2EH)
- 12.4.7.3 Polyvinyl Butyral (PVB)
- 12.4.7.4 Other Derivatives
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Butyraldehyde End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Butyraldehyde Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Butyraldehyde Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Butyraldehyde Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mitsubishi Chemical Corporation
- 18.4 KH Neochem Co., Ltd.
- 18.5 Eastman Chemical Company
- 18.6 Dow Chemical Company
- 18.7 OXEA GmbH
- 18.8 Perstorp Holding AB
- 18.9 Tokyo Chemical Industry Co., Ltd.
- 18.10 Loba Chemie Pvt Ltd
- 18.11 Thermo Fisher Scientific
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
