
Caproic Acid Market Overview:
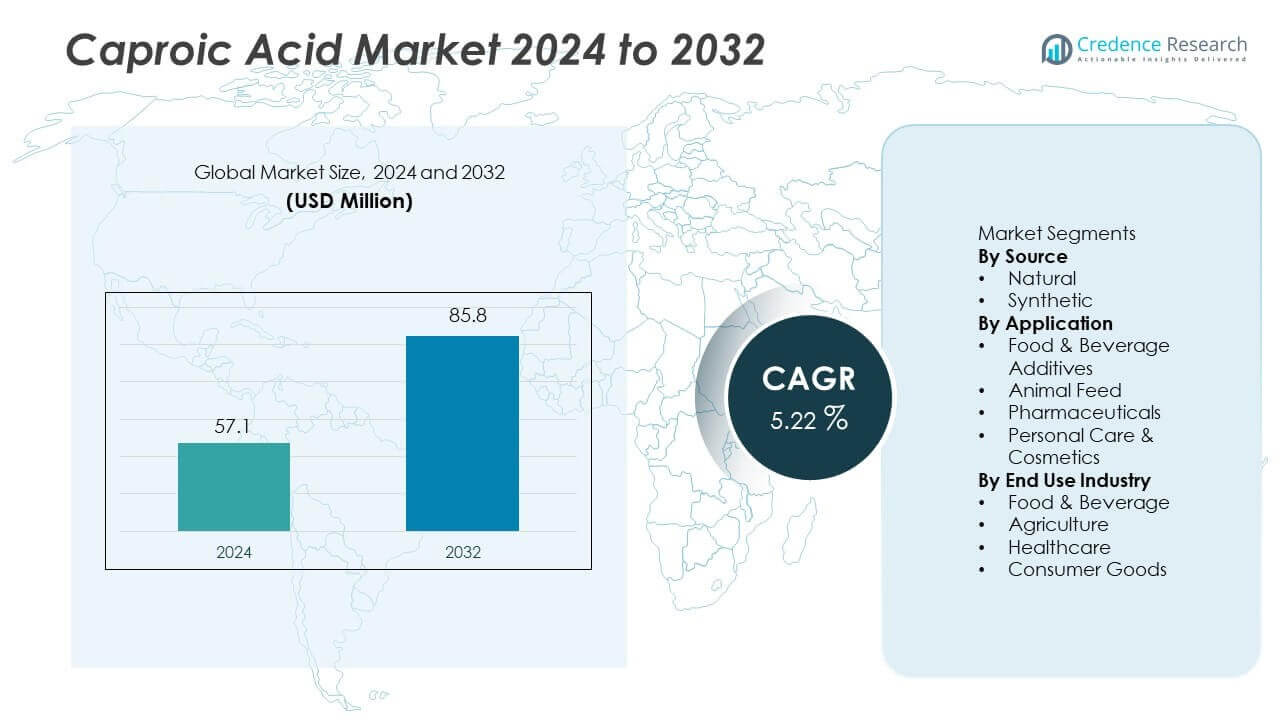
Caproic Acid market size was valued at USD 57.1 million in 2024 and is projected to reach USD 85.8 million by 2032, reflecting a CAGR of 5.22% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Caproic Acid Market Size 2024 | USD 57.1 million |
| Caproic Acid Market, CAGR | 5.22% |
| Caproic Acid Market Size 2032 | USD 85.8 million |
Caproic Acid Market Insights
- Demand rises due to strong use in food and beverage additives, animal feed nutrition, pharmaceuticals, and personal care, driven by clean-label trends and natural ingredient adoption.
- Natural source leads the segment with 58% share as manufacturers shift toward plant-based and sustainable fatty acids for flavor, health, and formulation benefits across industries.
- Asia Pacific holds 35% share and leads due to strong food processing and livestock production, while North America follows with 32% share supported by personal care and pharmaceutical demand.
- Growth is limited by pricing volatility, raw material dependency, and regulatory constraints, though major players enhance capability through new product development, supply optimization, and sustainability initiatives to strengthen competitive advantage.
Caproic Acid Market Segmentation Analysis:
By Source:
Natural caproic acid leads the source segment with 58% share, driven by rising preference for plant-based and biologically derived fatty acids across food, pharmaceutical, and personal care applications. Demand strengthens as manufacturers shift toward sustainable ingredient sourcing and clean-label formulations to align with consumer expectations and regulatory standards. Synthetic caproic acid continues to serve bulk industrial needs due to cost efficiency and consistent purity, although growth remains slower than natural variants. Increasing production efficiency, expanding feedstock availability, and broader use in flavor and fragrance formulations reinforce the dominance of natural caproic acid.
- For instance, Oleon N.V. operates oleochemical units that convert natural fats and oils into fatty acids across Europe.
By Application:
Food and beverage additives dominate the application segment with 41% share, supported by rising demand for flavor enhancers, emulsifiers, and preservative functions across processed foods and beverages. Animal feed follows due to caproic acid’s antimicrobial properties and digestive support benefits, helping improve livestock health and feed utilization. Pharmaceuticals gain momentum from expanding use in drug formulation and fatty acid-based therapeutics, while personal care and cosmetics benefit from caproic acid’s stability and odor-modifying properties. Growth in food and beverage reflects evolving taste profiles and increased processed food consumption globally.
- For instance, Wilmar International supplies high-purity caproic acid derived from sustainable palm oil, which serves as a critical raw material for food-grade flavor compounds produced at their global oleochemical manufacturing facilities.
By End Use Industry:
The food and beverage industry holds the largest end-use share at 43%, driven by expanding use of caproic acid in flavor compounds, specialty fats, and nutritional blends. Agriculture follows with strong application in feed additives, supporting animal performance and disease resistance. Healthcare benefits from caproic acid’s role in metabolic and therapeutic formulations, while consumer goods leverage its use in soaps, detergents, and fragrance products. Market growth in food and beverage reflects rising product development activity, wider acceptance of functional ingredients, and stronger demand for flavor enhancement across global markets.
Key Growth Drivers
Rising Demand in Food and Beverage Processing
The caproic acid market grows as food and beverage manufacturers increase reliance on fatty acid derivatives for flavor enhancement, aroma development, and textural improvement. Demand rises across bakery, dairy, confectionery, and beverage categories, supported by expanding processed food consumption and changing dietary habits. Clean-label initiatives and consumer preference for natural ingredients further reinforce adoption. Manufacturers integrate caproic acid into specialty flavor systems to meet evolving taste preferences, boosting commercial value.
- For instance, Eastman Chemical Company produces organic acid-based intermediates used in ester synthesis at specialized manufacturing facilities.
Expanding Use in Animal Feed and Agricultural Nutrition
Agriculture drives significant growth as caproic acid supports gut health, feed efficiency, and antimicrobial defense in livestock. Rising focus on animal welfare and disease prevention fuels adoption across poultry, swine, and cattle operations. Producers seek natural alternatives to synthetic additives, strengthening market use. Growing demand for protein consumption and livestock productivity reinforces long-term application potential.
- For instance, IOI Corporation Berhad supplies fatty-acid-derived feed additives produced through its advanced esterification lines.
Growing Applications in Pharmaceuticals and Personal Care
The pharmaceutical and personal care sectors increase caproic acid use due to beneficial solubility, stability, and bioactive properties. It supports drug formulation, topical treatments, and cosmetic blends, offering conditioning and odor-balancing effects. Expanding skincare and wellness trends drive product development. Manufacturers benefit from broader formulation flexibility and rising consumer interest in fatty acid–based personal care ingredients.
Key Trends & Opportunities
Shift Toward Natural and Sustainable Ingredient Sources
Manufacturers emphasize natural caproic acid derived from renewable feedstocks such as coconut and palm oils. Growing environmental awareness and regulatory pressure accelerate demand for plant-based alternatives. This trend supports new product launches and supply chain investments.
- For instance, Ecogreen Oleochemicals operates integrated bio-refinery units that process natural oils to produce various fatty acids and fatty alcohols.
Advances in Fatty Acid Processing and Specialty Formulations
Innovations in extraction, purification, and blending technologies enhance product performance across food, healthcare, and consumer goods. Specialty formulations offer new commercial opportunities linked to improved purity and functional properties.
- For instance, Kao Corporation runs high-vacuum distillation systems achieving caproic acid purity levels below 5 ppm residual impurities in personal care grades.
Key Challenges
Fluctuating Raw Material Supply and Pricing Volatility
Caproic acid production depends on variable agricultural feedstocks that face climate risk and trade disruption. Price fluctuations challenge cost management and margin stability, especially for smaller producers.
Regulatory and Quality Compliance Requirements
Strict safety and purity standards apply across food, pharmaceutical, and cosmetic applications. Meeting these requirements increases testing, certification, and documentation costs, slowing new product adoption in regulated regions.
Regional Analysis
North America
North America holds 32% share, supported by strong use of caproic acid in food and beverage flavor systems, personal care formulations, and pharmaceutical applications. The region benefits from advanced processing technologies, strong consumer demand for specialty food products, and growing preference for natural ingredients. Expanding livestock and animal feed industries add value through rising use of fatty acid additives to support nutrition and health. Innovation in clean-label and functional product development continues driving demand. Regulatory frameworks promote product safety and quality, reinforcing long-term market stability across high-value end-use industries.
Europe
Europe accounts for 29% share, driven by strong demand in processed foods, dairy applications, and personal care products. Countries such as Germany, France, and the UK lead consumption due to established flavor and fragrance industries. Sustainability commitments support growth in natural caproic acid sourcing and feedstock diversification. Increasing focus on animal welfare and low-chemical farming strengthens agricultural adoption. Pharmaceutical and cosmetic manufacturers continue expanding product portfolios featuring fatty acid-based ingredients. Regulatory standards ensure purity and traceability, positioning Europe as a high-quality production and innovation hub.
Asia Pacific
Asia Pacific leads with 35% share, driven by expanding food processing capacity, rising personal care consumption, and growing livestock production in China, India, Japan, and Southeast Asia. Manufacturers benefit from cost-efficient production, growing consumer spending, and wider ingredient availability. Demand for flavor additives and functional food blends rises due to changing taste preferences and urbanization. Strong agricultural output increases adoption in feed additives and livestock nutrition. Expanding pharmaceutical manufacturing and cosmetic adoption also support regional growth. Local supply advantages reinforce Asia Pacific as the fastest-growing market.
Latin America
Latin America holds 3% share, supported by growing food processing activity and increasing livestock production in Brazil, Mexico, and Argentina. Adoption rises due to expanding animal feed applications and growing interest in functional food ingredients. Import reliance and economic fluctuations limit faster expansion, but long-term opportunities remain strong. Rising consumer interest in dairy and processed foods strengthens demand for flavor-based additives. Personal care adoption increases as product portfolios diversify. Regional manufacturing investment continues to support supply consistency.
Middle East & Africa
The Middle East & Africa account for 1% share, influenced by growing consumer markets for packaged foods, personal care products, and livestock nutrition. Adoption increases as awareness of functional fatty acids expands across food and agriculture sectors. Limited local production and supply chain challenges restrict growth, but rising investment in food processing and feed manufacturing supports future development. Emerging demand for value-added dairy and bakery products adds momentum. Regional market growth remains gradual but stable due to improving industrial capacity and changing consumer preferences.
Caproic Acid Market Segmentations:
By Source
- Natural
- Synthetic
By Application
- Food & Beverage Additives
- Animal Feed
- Pharmaceuticals
- Personal Care & Cosmetics
By End Use Industry
- Food & Beverage
- Agriculture
- Healthcare
- Consumer Goods
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The caproic acid market features active competition among key companies such as Oleon N.V., KLK OLEO, Wilmar International, Solvay S.A., Eastman Chemical Company, IOI Corporation Berhad, Kao Corporation, Ecogreen Oleochemicals, Pacific Oleochemicals, and Acme-Hardesty Co. These players strengthen market presence through integrated oleochemical production, diversified product portfolios, and strong distribution networks across food, pharmaceutical, animal feed, and personal care sectors. Companies focus on natural sourcing and sustainable feedstock utilization to align with clean-label and environmental expectations. Ongoing R&D supports improved purity, odor stability, and performance enhancements for flavor, fragrance, and formulation applications. Strategic investments in capacity expansion, raw material security, and regional supply partnerships ensure cost efficiency and market continuity. Competitive differentiation also reflects technical support, product innovation, and regulatory compliance capabilities. With rising global demand for natural fatty acids, market competition will remain driven by quality, traceability, and application development advantages.
Key Player Analysis
- Oleon N.V.
- KLK OLEO
- Wilmar International
- Solvay S.A.
- Eastman Chemical Company
- IOI Corporation Berhad
- Kao Corporation
- Ecogreen Oleochemicals
- Pacific Oleochemicals
- Acme-Hardesty Co.
Recent Developments
- In October 2025, KLK OLEO showcased plant-based oleochemical innovation at K 2025.
- In March 2025, Kao Corporation signed a supply agreement for palm-oil-alternative feedstocks.
- In June 2024, Ecogreen Oleochemicals published updated Sustainability Commitments for responsible sourcing.
Report Coverage
The research report offers an in-depth analysis based on Source, Application, End Use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise for natural caproic acid sourced from renewable feedstocks.
- Food and beverage manufacturers will expand usage in flavor and texture enhancement.
- Animal feed applications will grow due to rising focus on gut health and productivity.
- Personal care and cosmetic formulations will adopt more fatty acid ingredients.
- Pharmaceutical applications will expand as research advances therapeutic use.
- Asia Pacific will remain the fastest-growing regional market.
- Supply chain investments will improve availability and pricing stability.
- Sustainability goals will drive innovation in processing and feedstock sourcing.
- Market players will strengthen relationships through regional expansion and partnerships.
- Product differentiation and purity enhancement will shape competitive strategies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Caproic Acid market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Caproic Acid market projected to grow between 2024 and 2032?
Which Caproic Acid market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Caproic Acid market?
Who are the leading companies in the Caproic Acid market?
Which region commanded the largest share of the Caproic Acid market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 57.1 million → 2032: USD 85.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Caproic Acid Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Caproic Acid Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Caproic Acid Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Caproic Acid Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Caproic Acid Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Caproic Acid Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Caproic Acid Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Caproic Acid Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 57.1 million → 2032: USD 85.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Caproic Acid Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Caproic Acid Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Caproic Acid Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Caproic Acid Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

