
Coatings and synthesis work keep solvent purchases steady
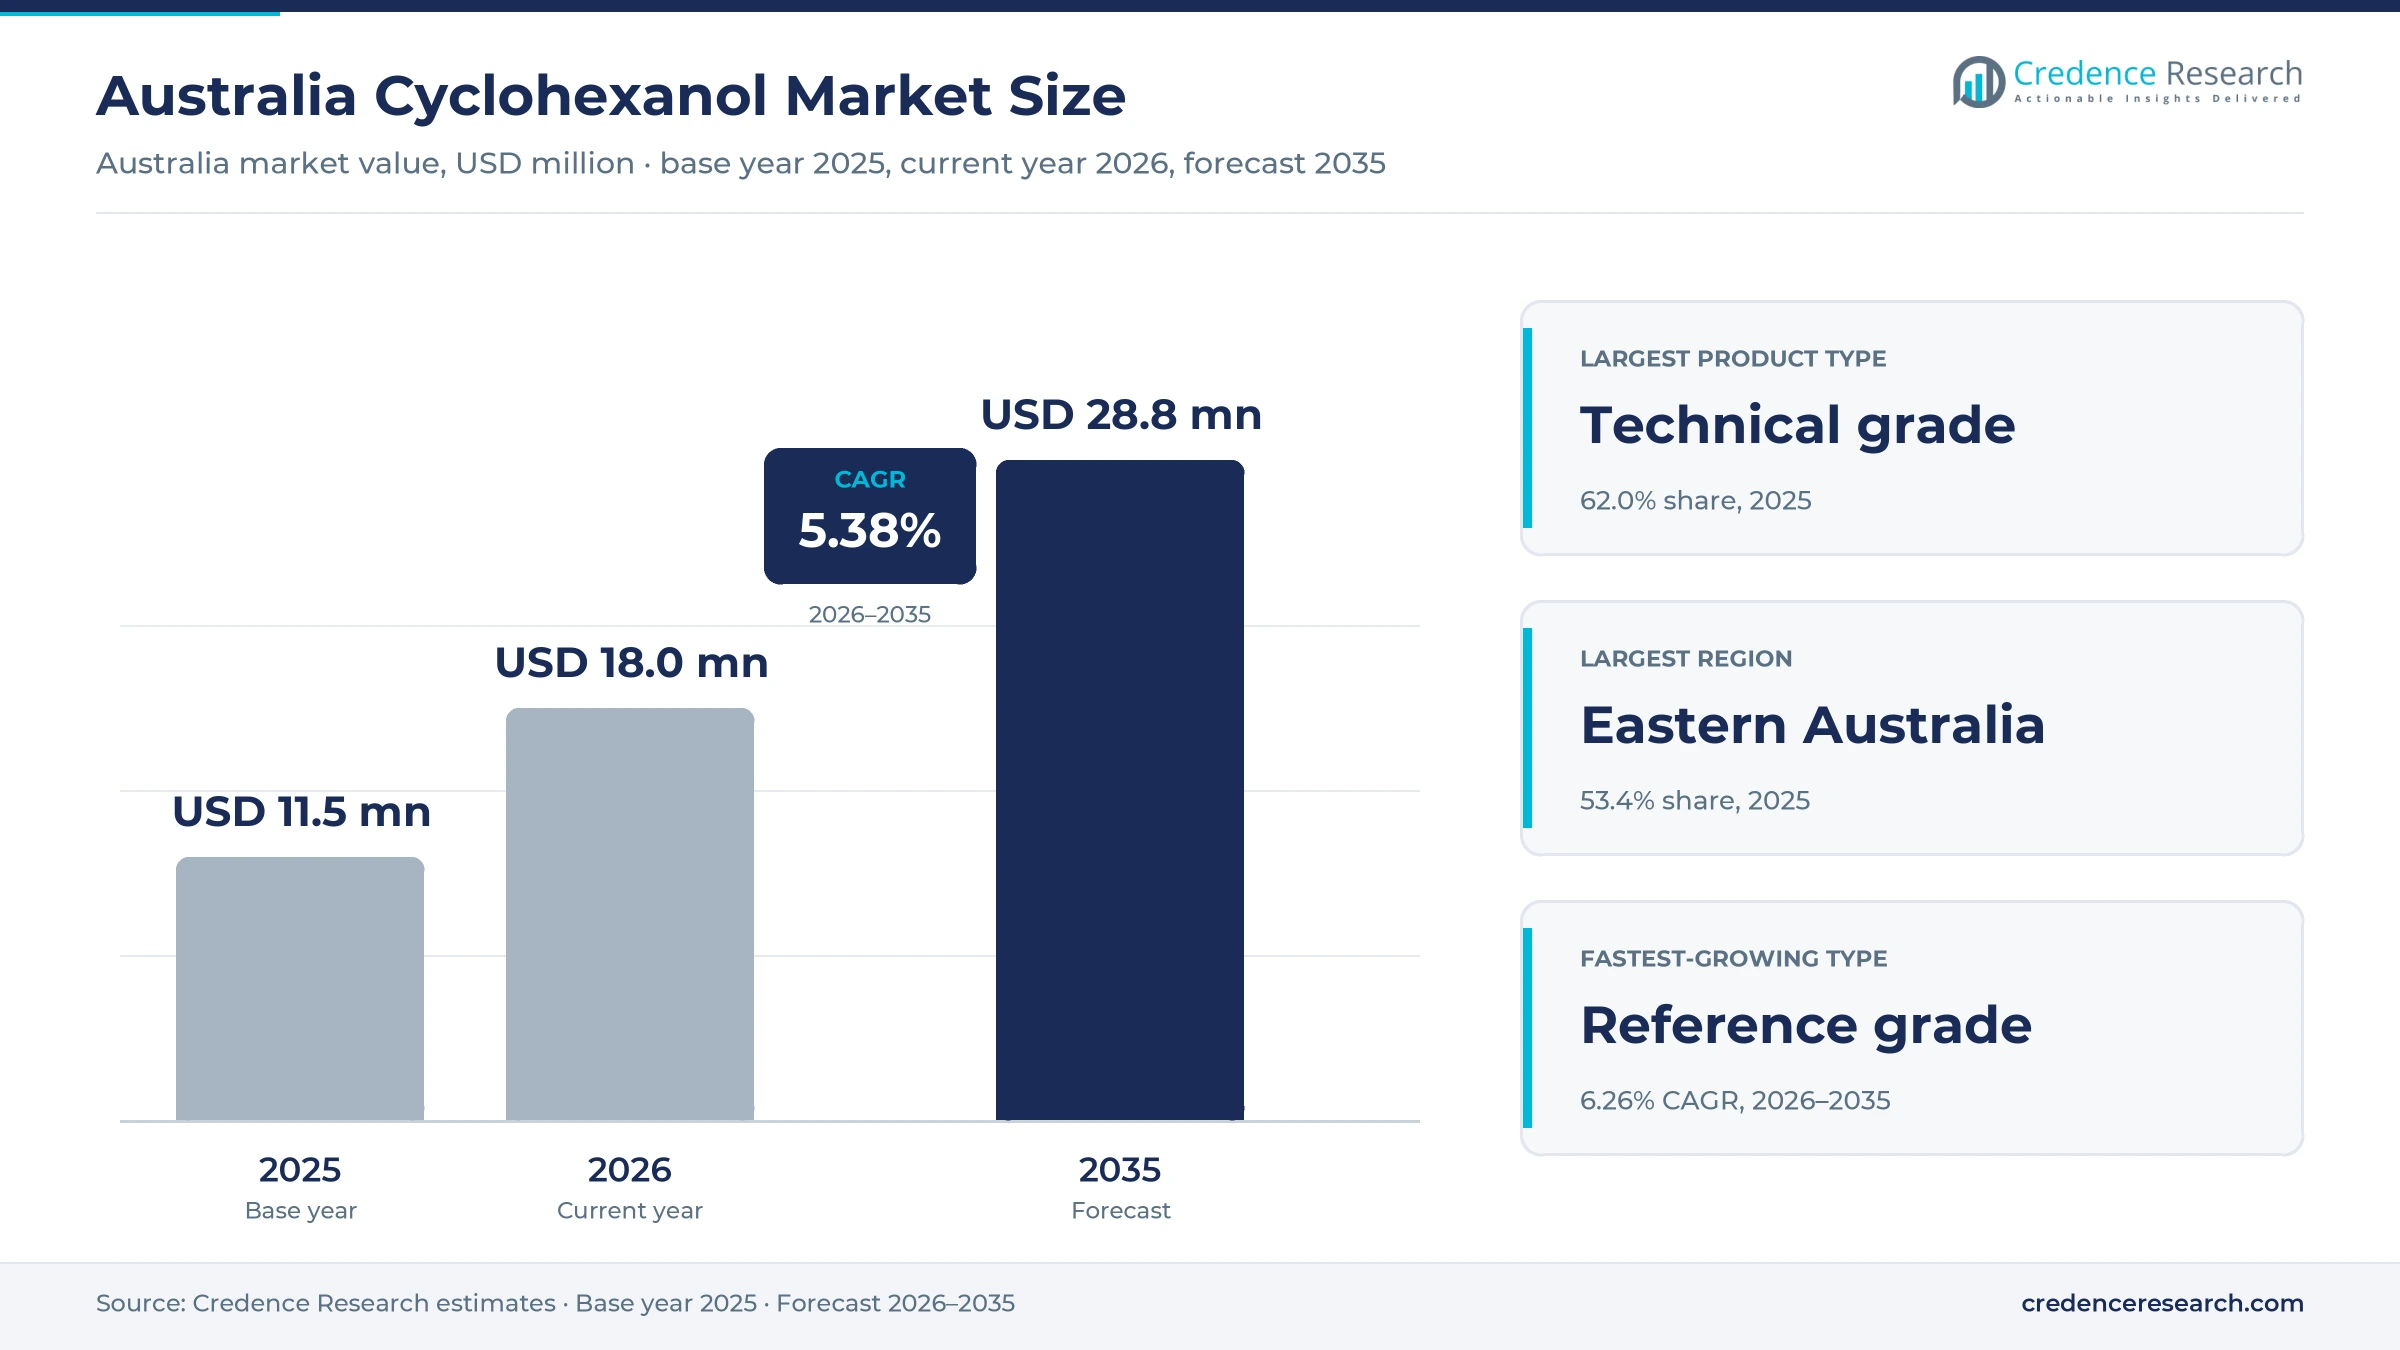
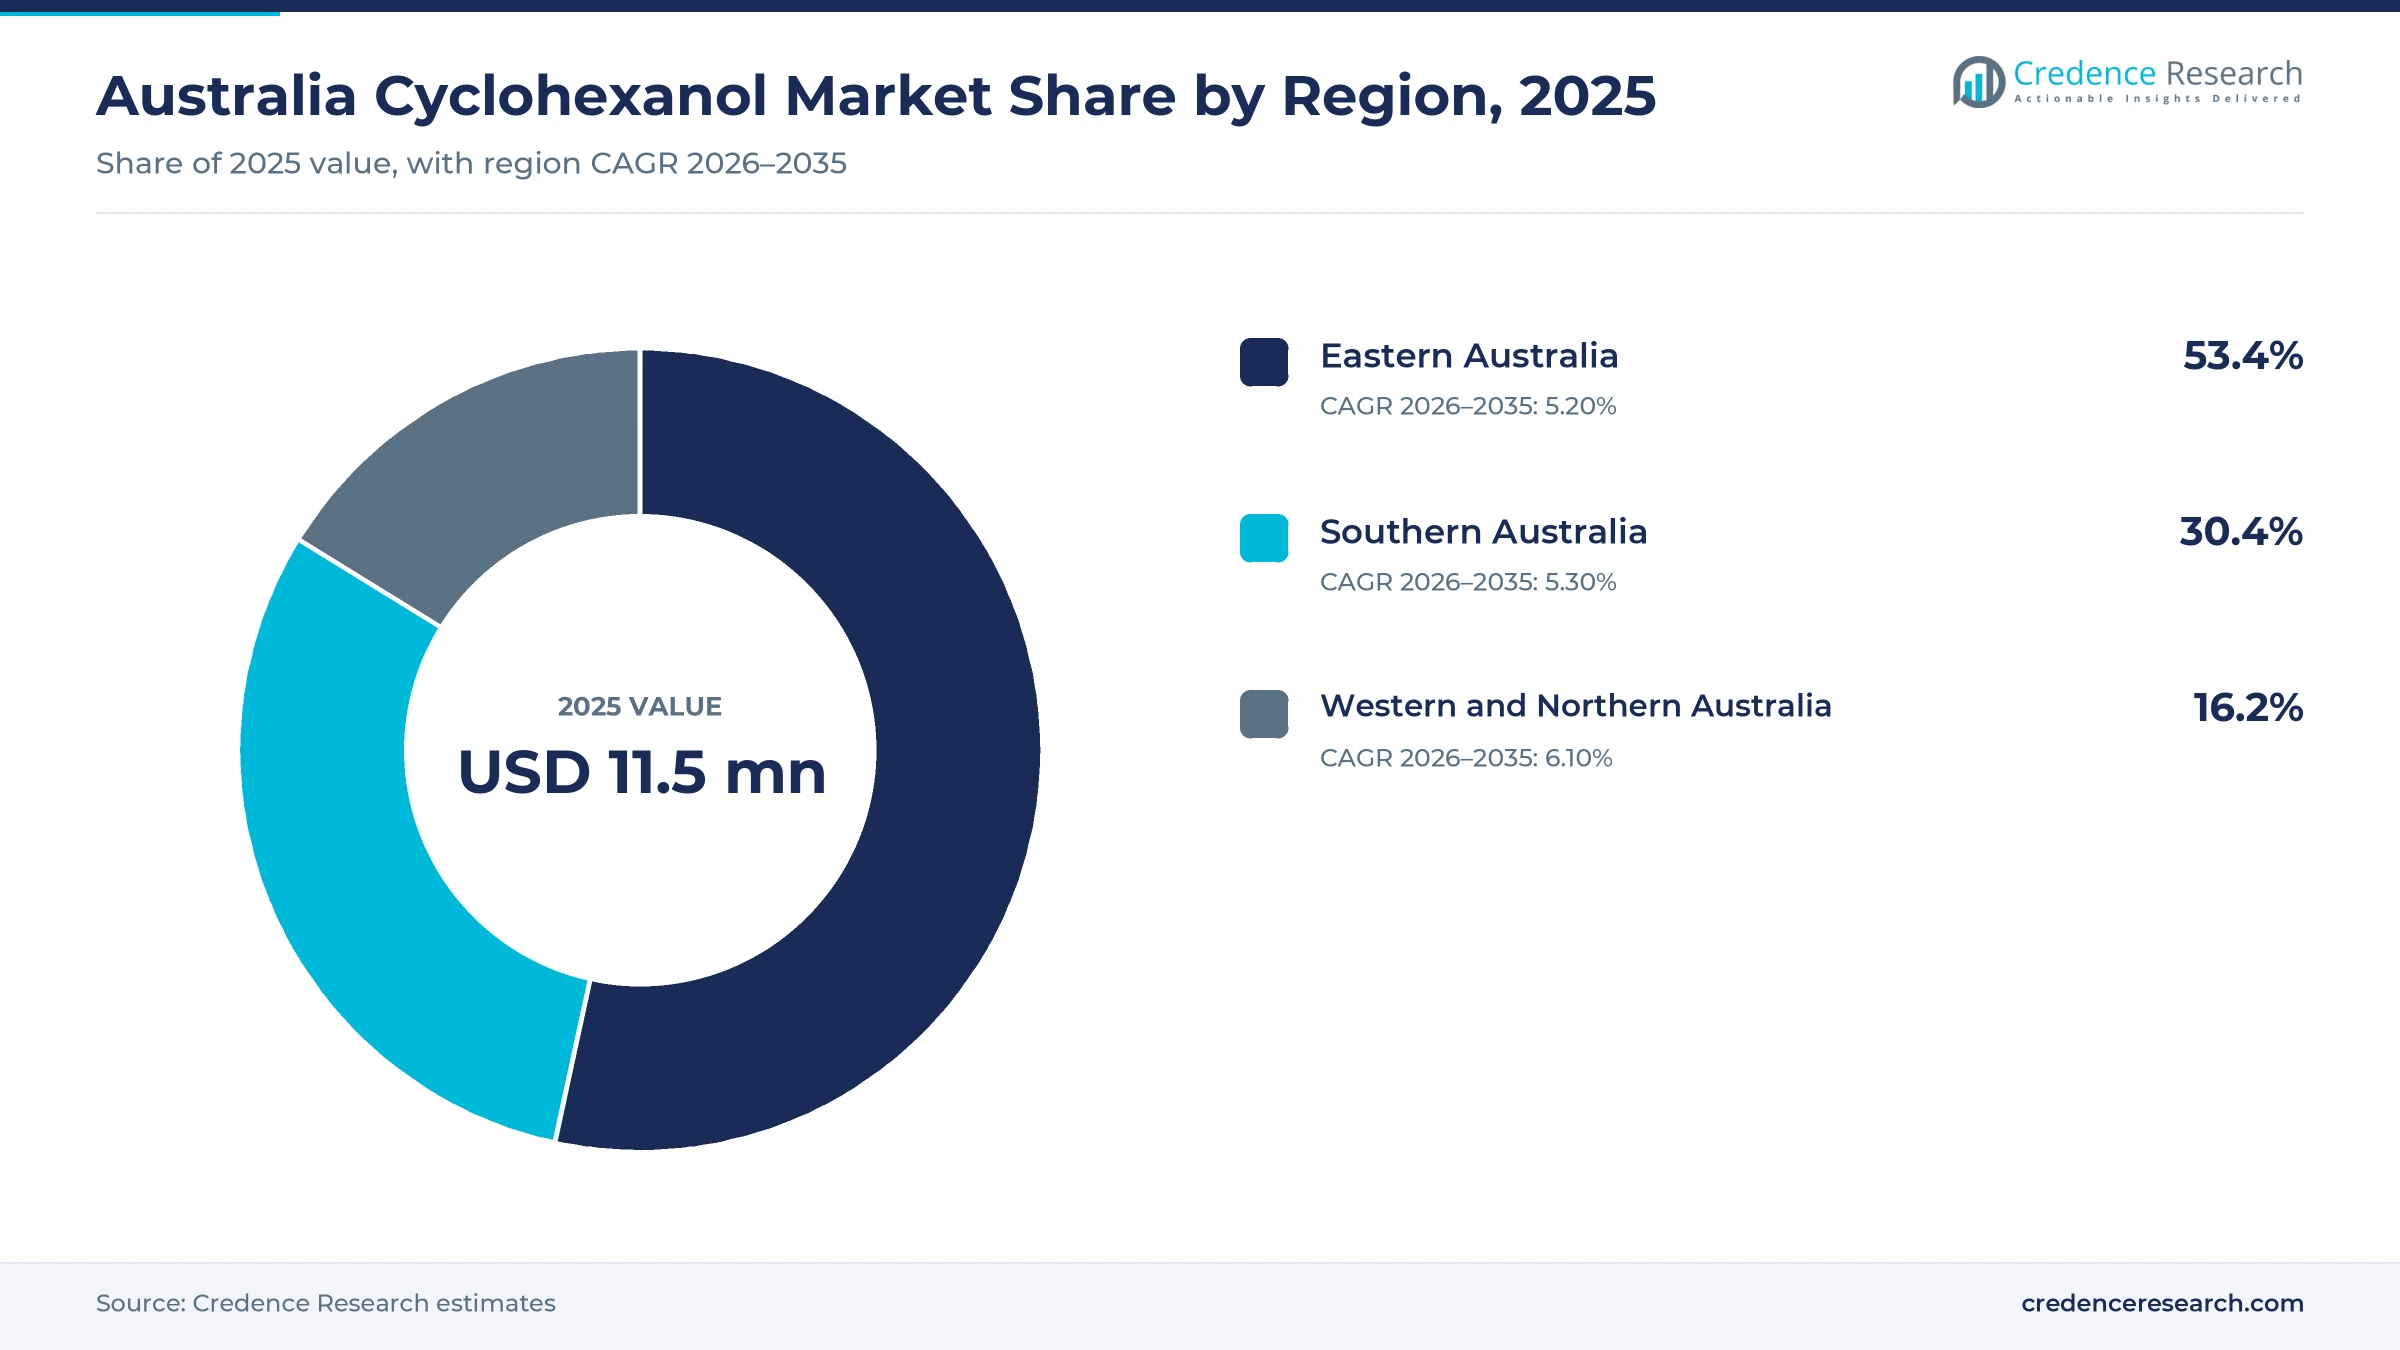
The Australia cyclohexanol market was valued at USD 11.5 million in 2025 and is projected to increase from USD 18.0 million in 2026 to USD 28.8 million by 2035, registering a CAGR of 5.38% during 2026–2035. Demand comes from coatings and resin formulators, pharmaceutical and fine chemical plants, cleaning product makers, fragrance and agrochemical synthesis sites, and university and contract laboratories that buy drummed and bottled material. Eastern Australia held the largest regional share, 53.4% in 2025, because the largest formulation plants, distributor warehouses and research campuses sit between Sydney and Brisbane. Western and Northern Australia is the fastest-growing region at 6.10% a year, as mining-linked laboratories and maintenance coatings work expand. In turn, new workplace exposure limits that apply from Dec. 1, 2026 are pushing buyers toward suppliers that provide full safety documentation with every delivery.
Which grades, pack sizes and uses are counted?
The estimate measures spending in Australia on cyclohexanol, the cyclic alcohol registered under CAS number 108-93-0, across technical, reagent and reference grades. It counts drums, cans and bottles bought for use as a process solvent, as a reaction feedstock and as an analytical material in testing and teaching laboratories. Values are stated in USD million at current prices and exclude goods and services tax.
The estimate excludes cyclohexanone, adipic acid, caprolactam and other downstream products made from the alcohol overseas, together with finished paints and cleaning products that contain it. The value chain runs from overseas producers through importers, chemical distributors, repackers and laboratory supply houses to formulators, synthesis plants and laboratories in every state.
Australia Cyclohexanol Market Insights
- The Australia cyclohexanol market was valued at USD 11.5 million in 2025 and is projected to reach USD 28.8 million by 2035, at a 5.38% CAGR during 2026–2035.
- Eastern Australia held the largest regional position in 2025 and grows at 5.20% a year during 2026–2035, led by coating and specialty plants between Sydney and Brisbane.
- Technical grade led product types with a 62.0% share of 2025 value, because process solvent work consumes the largest volumes.
- Australia imported 16,242 kilograms of this alcohol and its methyl homologues during 2023, worth USD 59.55 thousand, mainly from China and the United Kingdom.
- Reference grade grows fastest at 6.26% a year during 2026–2035, as laboratories buy certified material for method validation.
Technical grade leads while reference grade gains fastest
Why does technical grade carry the largest volume?
Based on product type, the market is categorized into technical grade, reagent grade and reference grade. Technical grade led with a 62.0% share of 2025 value, because formulators buy in drums where trace impurities do not affect performance. Reference grade grows fastest at 6.26% a year, as testing laboratories need certified material with stated purity, moisture and identity data for every lot.
Which plants place the steadiest orders?
Based on end-use industry, the market is categorized into coatings formulation, pharmaceutical and specialty synthesis, cleaning formulation and fragrance and agrochemical synthesis. Coatings formulation led with a 38.0% share of 2025 value, because the alcohol dissolves resins and controls flow in coating systems. Pharmaceutical and specialty synthesis grows fastest at 6.13% a year, as fine chemical work expands at contract sites.
Solvent duty, feedstock duty or analysis?
Based on application, the market is categorized into process solvent, reaction feedstock and analytical use. Process solvent led with a 55.0% share of 2025 value, because the alcohol is mostly bought to dissolve, carry or plasticize other materials. Analytical use grows fastest at 5.96% a year, as laboratories run more validation, calibration and teaching work with documented reference material.
Distributors, laboratory houses or direct import?
Based on sales channel, the market is categorized into chemical distribution, laboratory supply and direct import procurement. Chemical distribution led with a 57.0% share of 2025 value, because distributors hold stock, dangerous goods storage and safety documents for many customers at once. Direct import procurement grows fastest at 5.83% a year, as larger plants import container loads directly against annual contracts.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Technical grade | 62.0% | Reference grade | 6.26% |
| By End-Use Industry | Coatings formulation | 38.0% | Pharmaceutical and specialty synthesis | 6.13% |
| By Application | Process solvent | 55.0% | Analytical use | 5.96% |
| By Sales Channel | Chemical distribution | 57.0% | Direct import procurement | 5.83% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Formulation work, laboratory buying and audits drive orders
How does qualified formulation demand lift orders?
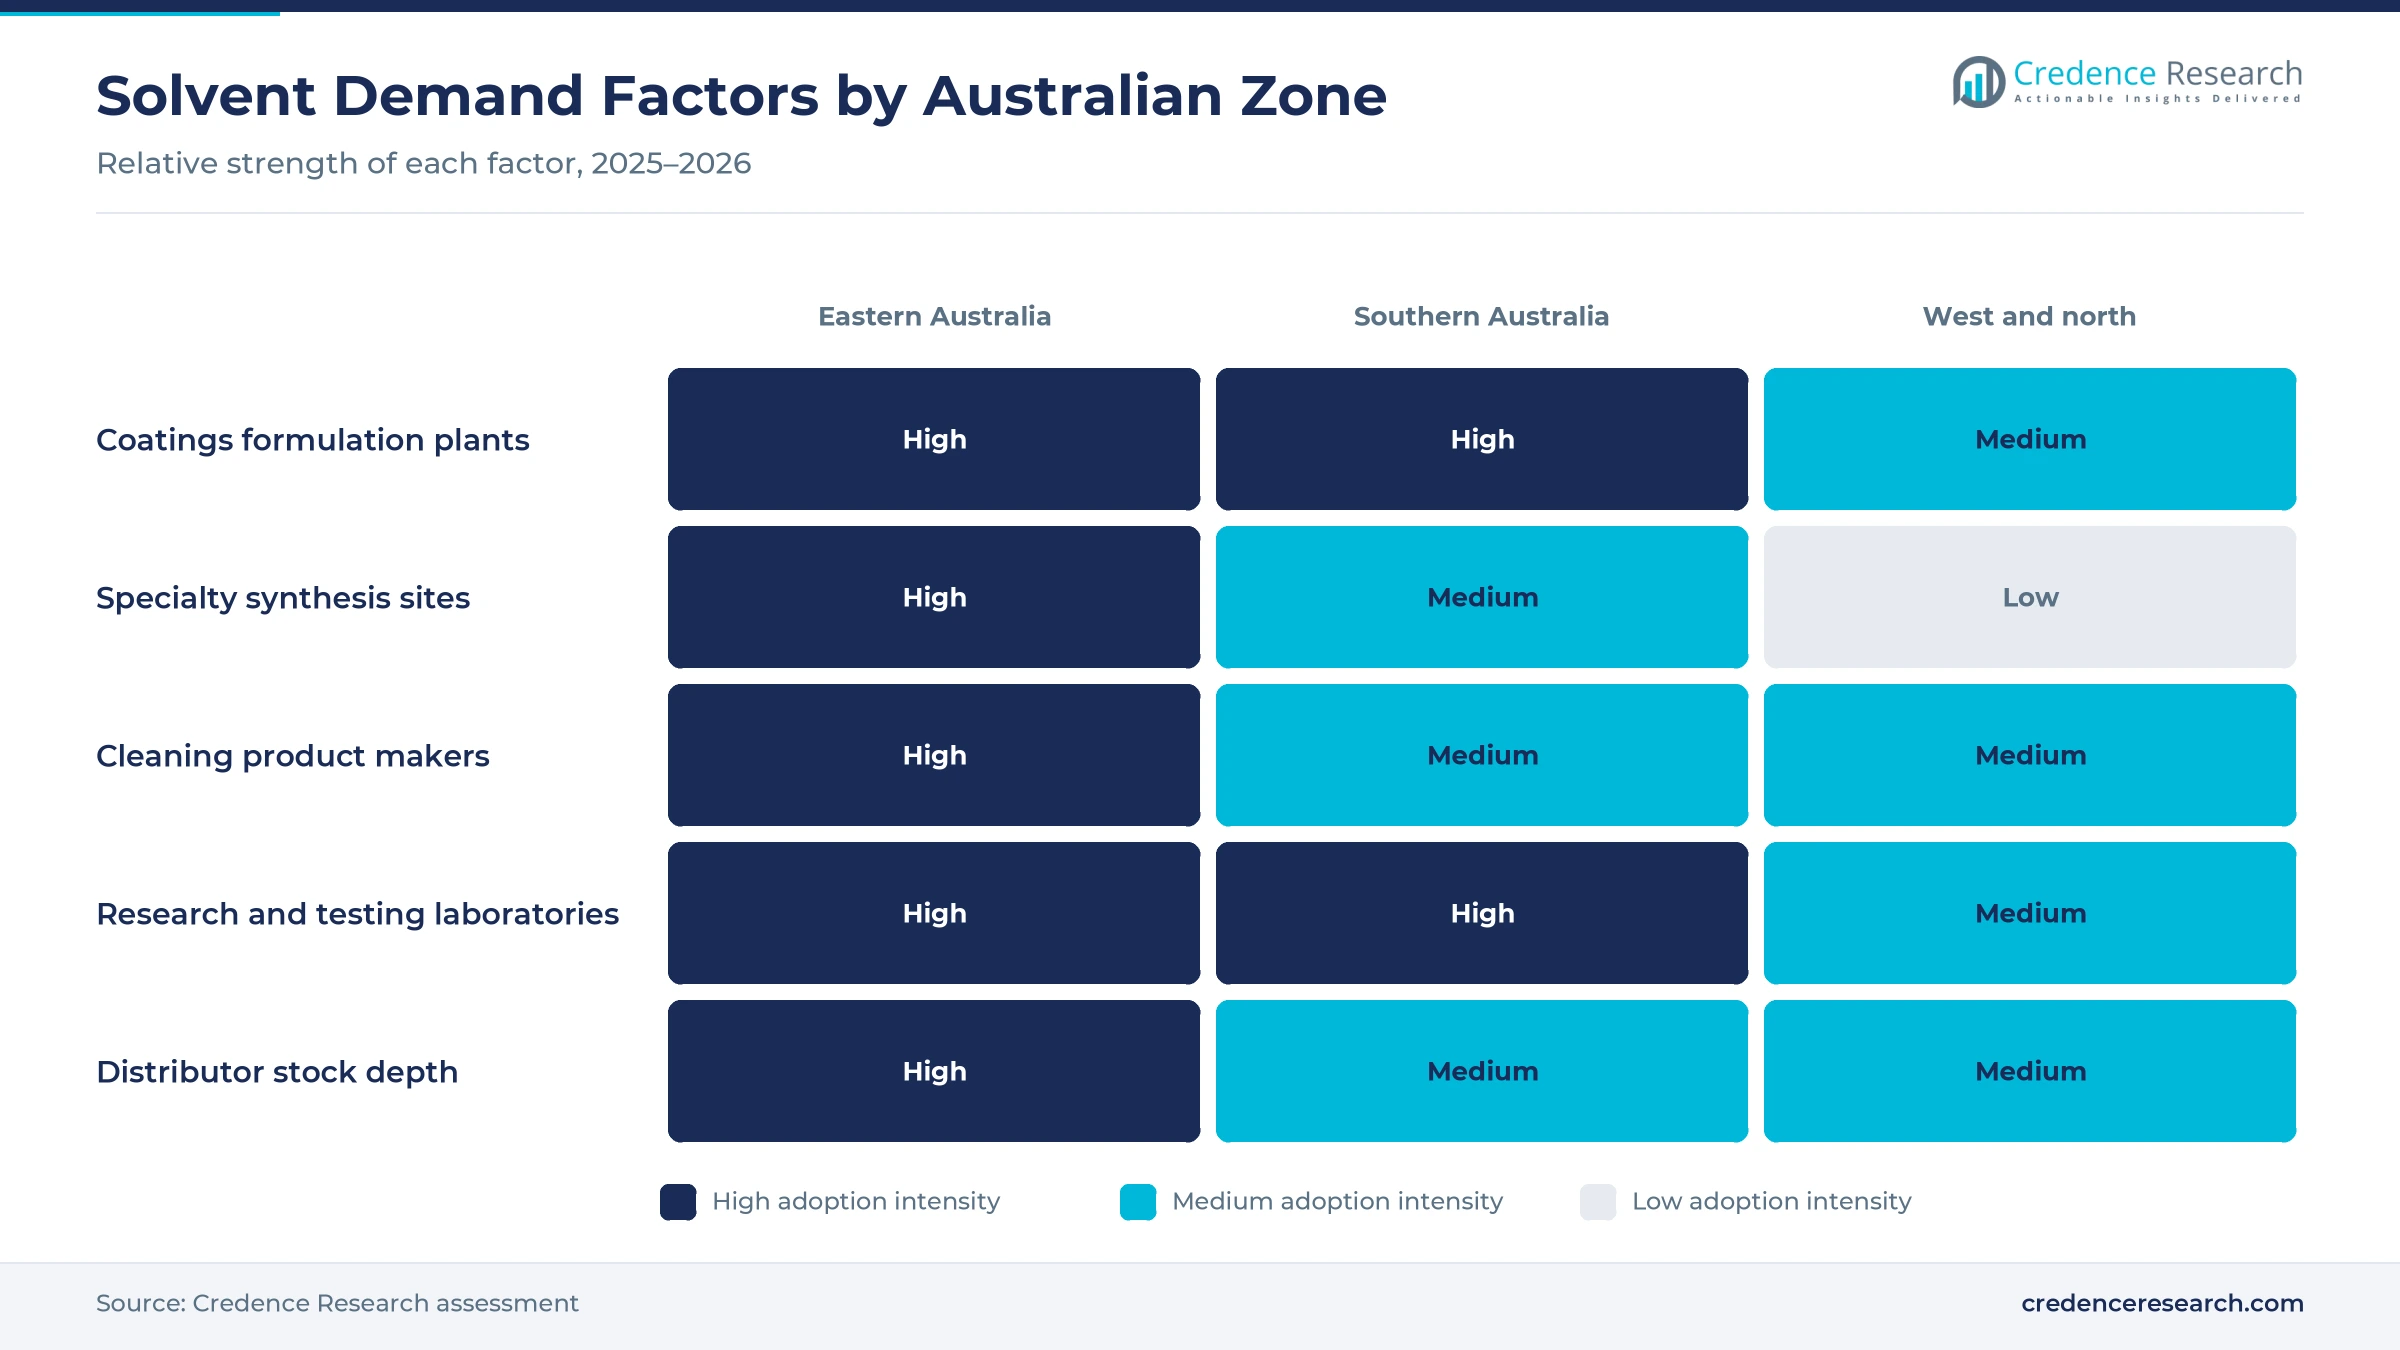
Qualified formulation demand lifts Australia cyclohexanol orders, because coating, adhesive and cleaning recipes name an approved solvent that cannot be swapped without retesting. Redox lists this alcohol under CAS number 108-93-0 for coatings, detergents and textile and leather customers, and it serves Australia from its own warehouses, according to the distributor product listing. Imported volumes are small and highly specified, with 16,242 kilograms arriving during 2023. Because requalification costs time and laboratory work, formulators keep buying the same grade from the same source. As a result, coatings formulation holds the largest end-use share at 38.0%, and protective finishes remain the anchor demand base.
Why does documented laboratory procurement add volume?
Documented laboratory procurement adds volume, because testing houses, universities and contract research sites must buy material with stated purity and traceability. ChemSupply Australia lists a 98% product under CAS number 108-93-0 in its online catalogue, with grade and pack size options, according to the supplier catalogue entry. Import records show United Kingdom shipments of only 760 kilograms worth USD 28.09 thousand during 2023, which works out near USD 37 a kilogram and points to small certified packs. Chinese shipments of 15,482 kilograms cost about USD 2 a kilogram over the same period. Consequently, analytical use grows fastest among applications at 5.96% a year through 2035.
How do compliance duties keep suppliers in place?
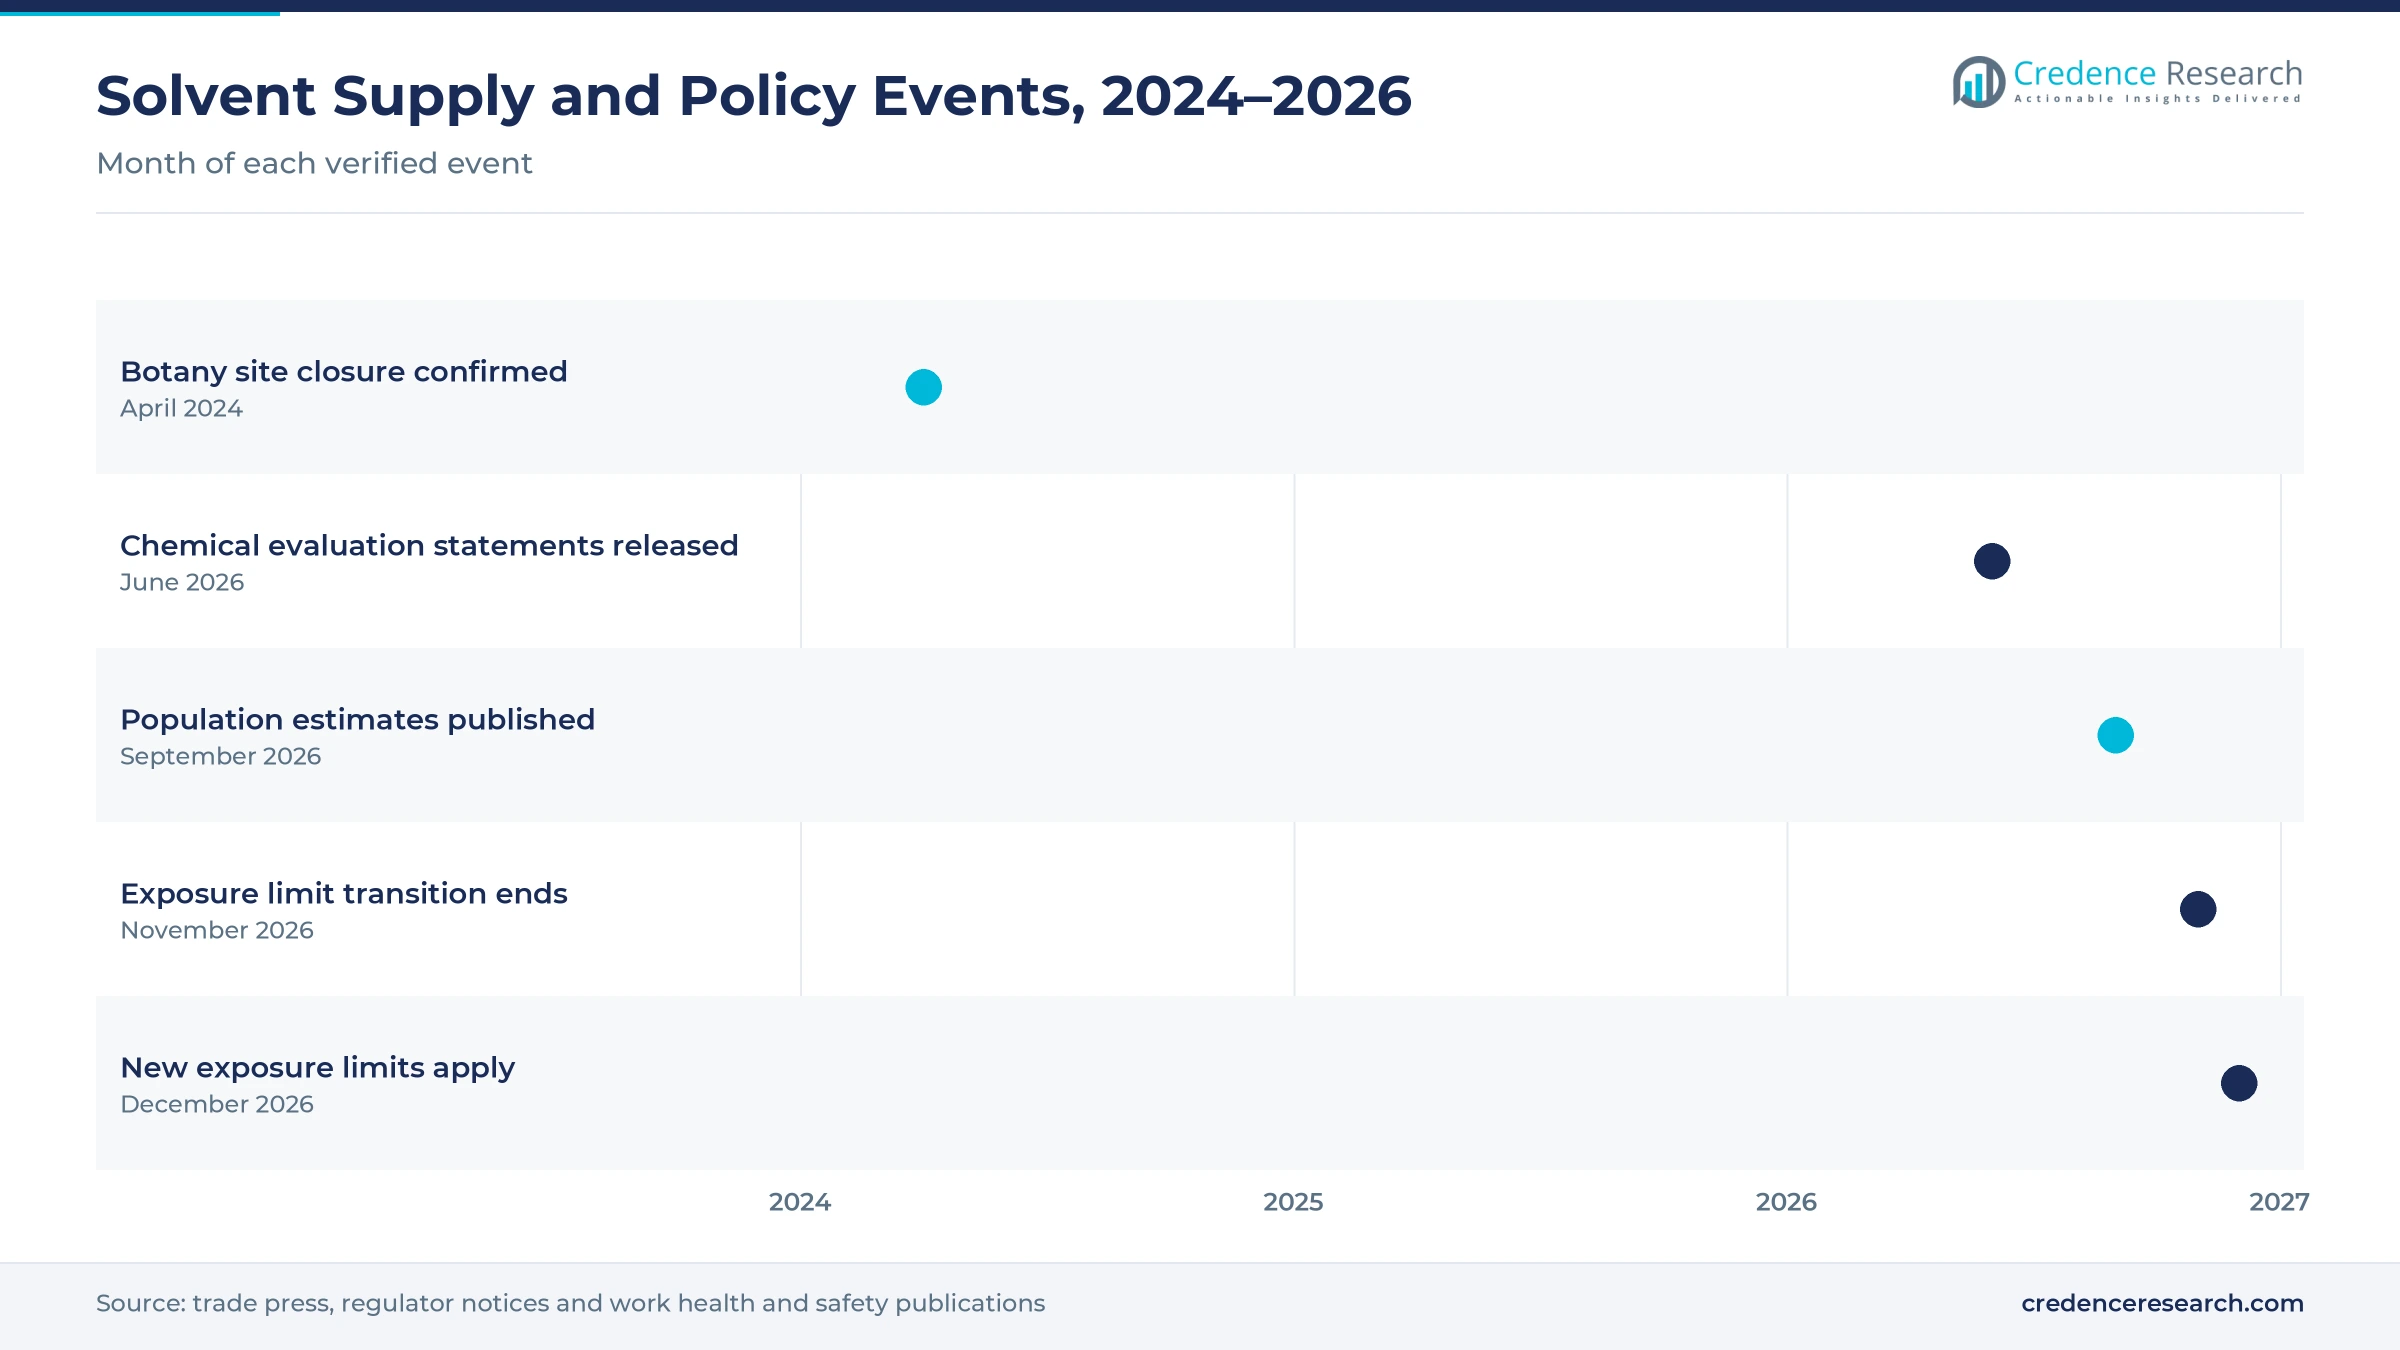
Compliance duties keep suppliers in place, because buyers need safety data, labels and storage advice that match current rules. New workplace exposure limits apply from Dec. 1, 2026 and replace the earlier exposure standards, with a harmonised transition period ending Nov. 30, 2026, according to the national work health and safety body. Nine substances were held back from that update for further impact analysis, while 33 airborne contaminants remain under review. Because every change must reach the shop floor through revised documents, buyers favor suppliers with local regulatory staff. In turn, chemical distribution keeps a 57.0% share of value.
Why does import-led supply shape purchasing patterns?
Import-led supply shapes purchasing patterns, because no Australian plant makes this alcohol at scale today. Recorded imports reached only USD 59.55 thousand during 2023, and China and the United Kingdom supplied all of that trade, according to reported customs data. Local chemical manufacturing has also narrowed since Qenos announced in April 2024 that its Botany site would not restart. Distributors answer by holding stocked original packs, repacking into smaller cans and arranging indent shipments for annual contracts. As a result, direct import procurement grows fastest among channels at 5.83% a year, led by plants that buy intermediate feedstocks in volume.
Documented sourcing and compliance support reshape supply
How is the shift toward documented sourcing changing supply?
The shift toward documented sourcing is changing supply, because auditors now ask for certificates of analysis, origin records and exposure advice on every solvent. In June 2026 the industrial chemicals regulator announced eleven final evaluation statements covering substances used in solvent and materials work. Buyers reading those statements expect their suppliers to track each outcome and reissue documents quickly. Recorded imports during 2023 came from two countries only, 15,482 kilograms from China and 760 kilograms from the United Kingdom, so provenance is easy to state. New workplace exposure limits also apply from Dec. 1, 2026. In turn, process solvent duty keeps a 55.0% share of value, while laboratory reagents sold with full paperwork command firmer prices than undocumented stock.
Why is specialty synthesis demand rising at contract sites?
Specialty synthesis demand is rising at contract sites, because fine chemical and pharmaceutical work pays for small volumes of well-characterized intermediates. Pharmaceutical and specialty synthesis grows at 6.13% a year through 2035 in this assessment. The alcohol serves as a starting point for oxidation and esterification steps that feed acid intermediates made overseas. United Kingdom imports priced near USD 37 a kilogram during 2023 show that buyers already pay a premium for certified lots. Because approval files name exact grades, synthesis customers rarely change supplier once a route is validated, which supports steady repeat orders.
Can repacking and local stock widen the customer base?
Repacking and local stock offer a clear opening, because many buyers need cans rather than drums. Redox holds warehouse capacity at Minto in Sydney, Laverton North in Melbourne, Richlands in Brisbane, Dry Creek in Adelaide and Bibra Lake in Perth, which puts stock near most industrial centers. ChemSupply Australia already offers the alcohol under CAS number 108-93-0 in catalogue pack sizes for laboratory and pilot work. Technical grade holds a 62.0% share of 2025 value, and total imports of 16,242 kilograms during 2023 arrived in drums, so even small conversions into cans reach a wide base. Consequently, suppliers that pair local stock with same-week delivery can win work from indent-only competitors across every state.
Is there room for compliance services alongside supply?
Compliance services alongside supply offer room to grow, because the exposure limit change lands on every workplace that stores solvents. The new limits replace standards that had applied for decades, and the transition period ends on Nov. 30, 2026, with the new limits applying from Dec. 1, 2026. Reference grade is also the fastest-growing product type at 6.26% a year, which reflects more testing and verification work. An exposure standards review in 2019 deferred this alcohol to a later release, and nine substances were again held back from the 2026 update, so many sites still rely on supplier advice. As a result, distributors that offer training, labeling support and storage audits can charge for services rather than discount the product.
No local production, small volumes and freight raise costs
Why does the absence of local production raise cost?
The absence of local production raises cost, because every kilogram of Australia cyclohexanol supply must be imported, cleared and stored before use. Recorded trade during 2023 came only from China and the United Kingdom, which leaves buyers exposed to freight schedules and currency moves. Local chemical manufacturing has also narrowed since the Botany petrochemical site stopped operating, a closure confirmed in April 2024 by trade press reporting. As a result, lead times stretch and minimum order quantities rise for specialty grades. Distributors respond by carrying buffer stock and by grouping orders from several customers into single shipments.
How do small volumes limit supplier interest?
Small volumes limit supplier interest, because annual Australia cyclohexanol trade is measured in metric tons rather than tankers. Imports of 16,242 kilograms during 2023 would fit in a single container, so few producers chase the account. Consequently, buyers face narrow source choice and little price competition for certified lots. Laboratory houses respond by listing the material through partner brands rather than importing it themselves. Distributors also bundle it with related solvents so that one shipment can serve many order lines at an acceptable landed cost.
Why do handling and storage rules add workload?
Handling and storage rules add workload, because the alcohol is combustible and irritating in use. Workplaces must manage ventilation, personal protection and dangerous goods storage under state regulations. New exposure limits take effect on Dec. 1, 2026, so safety documents, signage and air monitoring plans all need review. In turn, small laboratories and workshops carry administrative cost that large plants absorb more easily. Suppliers respond with current safety data sheets, labeled packs and written storage guidance for each customer site.
Can buyers manage freight across long distances?
Long freight distances limit margins, because industrial demand sits in separate coastal clusters thousands of kilometers apart. Dangerous goods road and rail movement carries extra cost, paperwork and transit time to Perth, Darwin and regional sites. As a result, remote buyers pay more per can than customers near a distribution warehouse. Suppliers respond by stocking state branches, using local repackers and consolidating deliveries with other chemical lines so that freight is shared across many products.
Sydney and Melbourne buyers lead, the west grows fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Eastern Australia | 6.1 | 53.4% | 5.20% |
| Southern Australia | 3.5 | 30.4% | 5.30% |
| Western and Northern Australia | 1.9 | 16.2% | 6.10% |
Sydney and Brisbane plants keep the east ahead
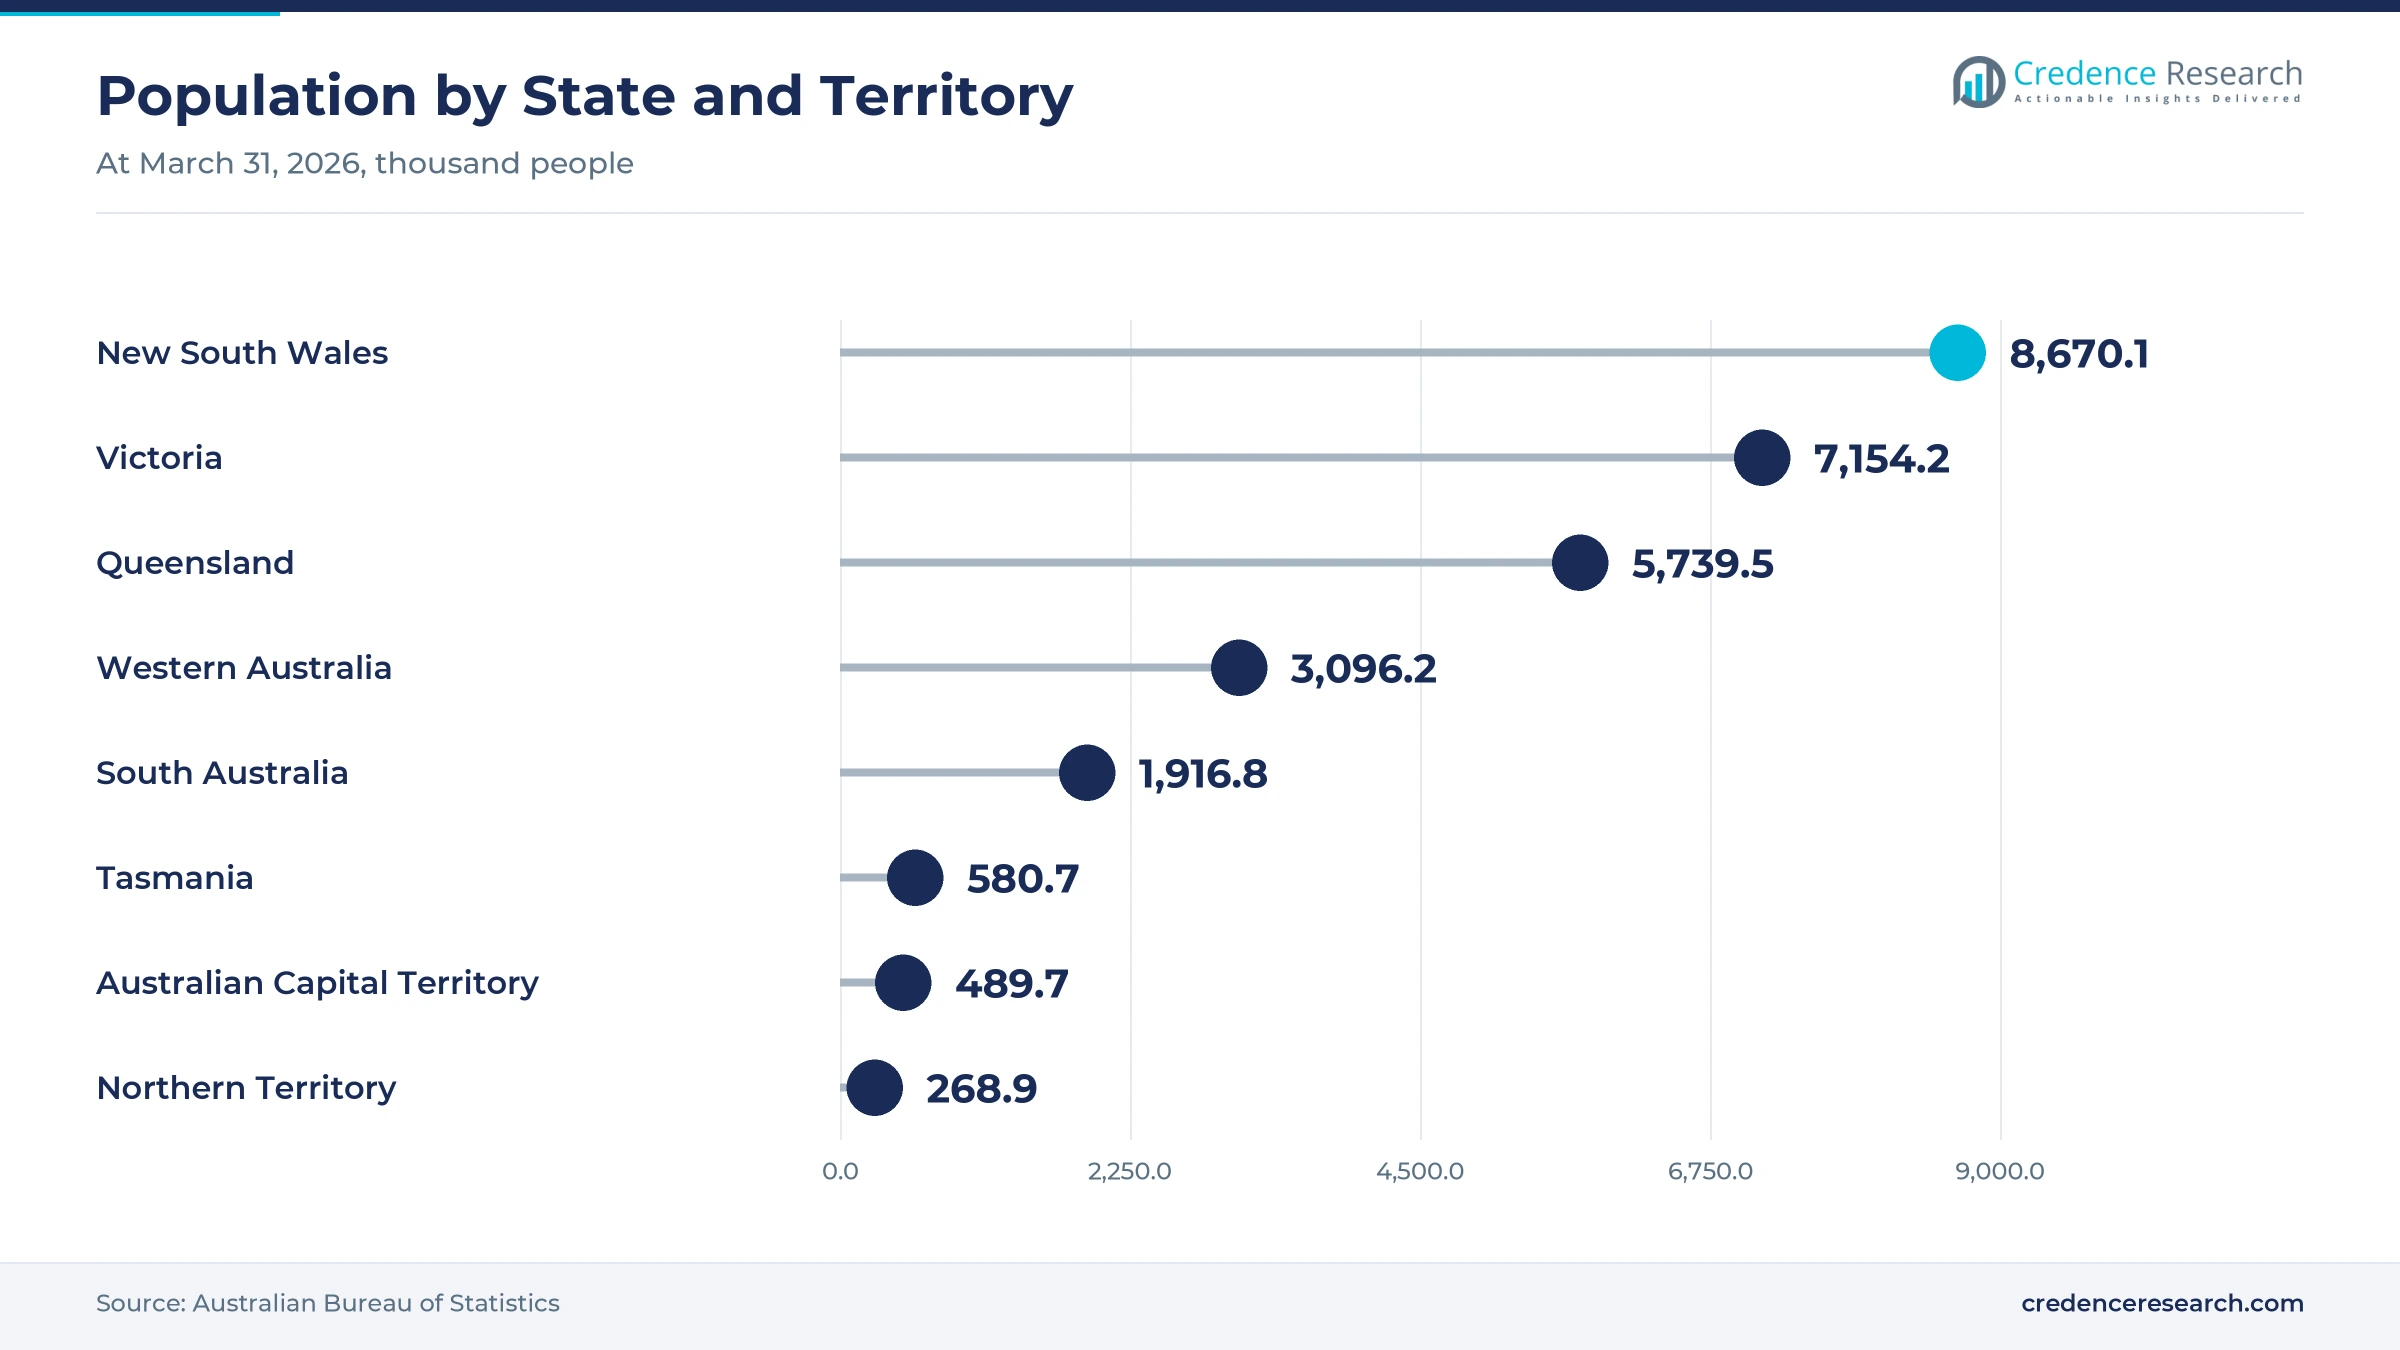
Eastern Australia held a 53.4% share of 2025 value and grows at 5.20% a year. New South Wales and Queensland together had more than 14.4 million residents at March 31, 2026, which supports the largest base of coating, cleaning and specialty plants. Redox runs warehouse capacity at Minto in south-west Sydney and at Richlands in Brisbane. As a result, the zone combines formulation demand, laboratory activity and the deepest distributor stock in the country.
Melbourne and Adelaide formulators anchor the south
Southern Australia held a 30.4% share of 2025 value and grows at 5.30% a year. Victoria had 7.15 million residents and South Australia 1.92 million at March 31, 2026, with Tasmania adding 580,700 more. Redox holds sites at Laverton North in Melbourne and Dry Creek in Adelaide, which places stock near manufacturing estates. Consequently, demand leans toward coatings, cleaning and food-adjacent formulation plants that order drummed material against annual recipes.
Why do the west and north grow fastest?
Western and Northern Australia held a 16.2% share of 2025 value and grow fastest at 6.10% a year. Western Australia recorded the fastest population growth of any state at 2.1% in the year to March 2026, with 3.10 million residents. Redox operates a warehouse at Bibra Lake in Perth, while the Northern Territory adds 268,900 residents. In turn, mining laboratories, maintenance coatings and remote testing work lift orders faster than in the eastern states.
Plant closures, chemical reviews and limits, 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In April 2024, Qenos announced that its Botany petrochemical site would not restart after entering voluntary administration. | Narrows local chemical manufacturing |
| In June 2026, the industrial chemicals regulator announced eleven final evaluation statements for chemicals used in solvent work. | Raises documentation expectations |
| In December 2026, Australian jurisdictions introduce new workplace exposure limits in place of the earlier standards. | Forces fresh safety documentation |
| In September 2026, the national statistics office published population estimates of 27.92 million residents. | Signals the industrial demand base |
Technical, reagent and reference grades serve distinct uses
- Technical grade serves drummed solvent duty in coatings, cleaning and textile work where trace impurities do not affect performance.
- Reagent grade suits synthesis and quality control work that needs stated assay, moisture and identity figures on each container.
- Reference grade carries certified values for calibration and method validation, and it commands the highest price per kilogram.
- Local repacking converts imported drums into cans and bottles so that laboratories and pilot plants can buy small quantities quickly.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Distributors and laboratory suppliers compete on service
Competition combines bulk chemical distribution with laboratory supply houses that list the material through partner brands. Redox publishes a product page for the alcohol under CAS number 108-93-0, names coatings, detergents and textile and leather as served industries, and holds warehouse capacity in Sydney, Melbourne, Brisbane, Adelaide and Perth. ChemSupply Australia offers a 98% product in catalogue pack sizes through its online shop, with grade and packaging choices shown at the order step. Merck Life Science, Thermo Fisher Scientific, Rowe Scientific, Southern Cross Science, Science Essentials, Australian Scientific, Novachem and LGC Standards also serve laboratory buyers, although their current Australian listings for this alcohol were not verified for this report. Companies compete on stock depth, pack range, documentation quality, delivery speed and landed price.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Redox Limited | Chemical distributor | Lists the alcohol for coatings, detergent and textile customers |
| ChemSupply Australia | Laboratory and industrial supplier | 98% product in catalogue pack sizes online |
| Merck Life Science | Laboratory supplier | Reagent and reference chemistry for research buyers |
| Thermo Fisher Scientific | Laboratory supplier | Research and analytical chemical ranges in Australia |
Credence Research sees documented supply setting the pace
Credence Research's view is that Australian demand for this alcohol will grow steadily through 2035, as coatings formulation, specialty synthesis and laboratory testing all expand from a small base. Technical grade should keep the largest product share, while reference grade gains most on validation work. Eastern Australia will remain the largest zone, although the west and north add demand fastest. However, the absence of local production, small annual volumes and freight across long distances will reward suppliers that hold state stock, repack locally and keep safety documentation current.
Import flows and formulation intensity anchor the model
The report uses 2025 as the base year, with values in USD million at current prices. Market values come from the Credence Research model, which combines recorded import flows, solvent intensity in coatings and synthesis work, laboratory purchasing patterns and grade price tiers. The three regional zones and their 2025 shares follow the client brief, while regional growth and the splits by product type, end-use industry, application and sales channel are Credence Research estimates. Sources used are official trade and population statistics, work health and safety publications, regulator notices, distributor and supplier catalogue pages and trade press reports, and no interviews or surveys were used.
Coatings, synthesis and audits shape demand to 2035
The market is expected to reach USD 28.8 million by 2035, a 5.38% CAGR during 2026–2035, as formulation work, synthesis projects and testing volumes keep demand rising. Spending is projected to rise from USD 18.0 million in 2026 as buyers rebuild stock positions. Growth should be strongest in reference grade, analytical use and the west and north, while Eastern Australia keeps the largest share. In contrast, import dependence, small order sizes and dangerous goods freight could slow purchases in some years.
Frequently Asked Questions
How big is the Australia cyclohexanol market?
Which region leads demand?
Which region grows fastest?
Which product type holds the largest share?
Which product type grows fastest?
How much does Australia import?
Who are the leading companies in this market?
What are the main risks to growth?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Technical grade
- 1.2.2 Reagent grade
- 1.2.3 Reference grade
- 1.3 By End-Use Industry
- 1.3.1 Coatings formulation
- 1.3.2 Pharmaceutical and specialty synthesis
- 1.3.3 Cleaning formulation
- 1.3.4 Fragrance and agrochemical synthesis
- 1.4 By Application
- 1.4.1 Process solvent
- 1.4.2 Reaction feedstock
- 1.4.3 Analytical use
- 1.5 By Sales Channel
- 1.5.1 Chemical distribution
- 1.5.2 Laboratory supply
- 1.5.3 Direct import procurement
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 11.5 million → 2035: USD 28.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Cyclohexanol Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Cyclohexanol Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Cyclohexanol Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Cyclohexanol Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Cyclohexanol Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Cyclohexanol Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Cyclohexanol Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Cyclohexanol Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 11.5 million → 2035: USD 28.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Cyclohexanol Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Technical grade
- 12.3.7.2 Reagent grade
- 12.3.7.3 Reference grade
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Coatings formulation
- 12.4.7.2 Pharmaceutical and specialty synthesis
- 12.4.7.3 Cleaning formulation
- 12.4.7.4 Fragrance and agrochemical synthesis
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Process solvent
- 12.5.7.2 Reaction feedstock
- 12.5.7.3 Analytical use
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Chemical distribution
- 12.6.7.2 Laboratory supply
- 12.6.7.3 Direct import procurement
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Cyclohexanol End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Cyclohexanol Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Cyclohexanol Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Cyclohexanol Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Redox Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Merck Life Science
- 18.4 Thermo Fisher Scientific
- 18.5 ChemSupply Australia
- 18.6 Rowe Scientific
- 18.7 Southern Cross Science
- 18.8 Science Essentials
- 18.9 Australian Scientific
- 18.10 Novachem
- 18.11 LGC Standards
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

