
Market Overview
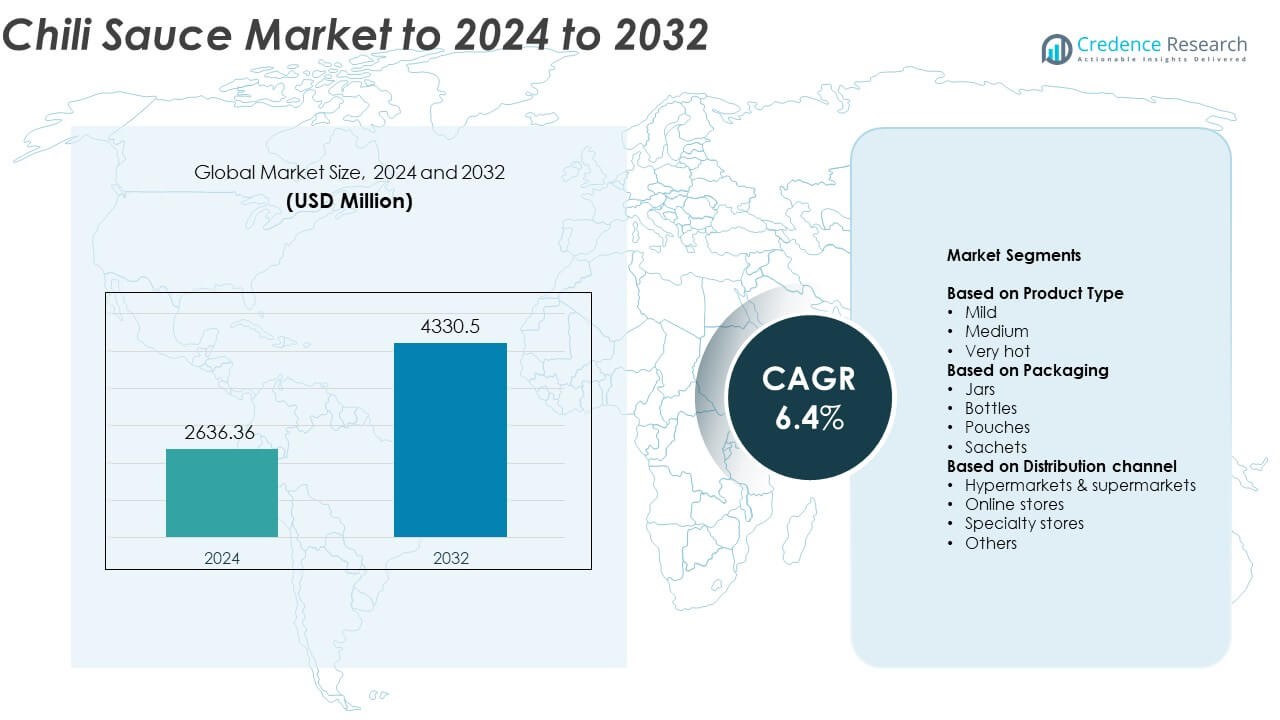
The Chili Sauce Market size was valued at USD 2636.36 million in 2024 and is anticipated to reach USD 4330.5 million by 2032, at a CAGR of 6.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Chili Sauce Market Size 2024 | USD 2636.36 Million |
| Chili Sauce Market, CAGR | 6.4% |
| Chili Sauce Market Size 2032 | USD 4330.5 Million |
The Chili Sauce Market is led by prominent players including Kraft Heinz, Huy Fong Foods, Nando’s, Lee Kum Kee, Cholula Hot Sauce, Laoganma, Lingham & Sons, MegaMex Foods, ThaiTheparos, Chung Jung One, and Real Thai (Thai Foods). These companies dominate through extensive product portfolios, strong regional distribution, and innovation in flavor diversity. North America leads the global market with a 36% share in 2024, supported by the high demand for spicy condiments and well-established retail networks. Europe follows with 27% share, driven by growing interest in ethnic cuisines and premium sauces, while Asia Pacific captures 24%, fueled by traditional consumption and expanding export demand.
Market Insights
- The chili sauce market was valued at USD 2636.36 million in 2024 and is projected to reach USD 4330.5 million by 2032, expanding at a CAGR of 6.4%. • Rising global preference for spicy and bold flavors, along with increasing use of sauces in fast food and ready meals, drives consistent market growth. • Product innovation with natural ingredients, organic variants, and sustainable packaging trends are reshaping consumer demand across premium and mainstream segments. • The market is highly competitive, with established global and regional brands focusing on new flavor launches and strategic retail partnerships to strengthen market share. • North America leads with 36% share, followed by Europe at 27% and Asia Pacific at 24%, while the medium chili sauce segment dominates globally with 47% share due to balanced heat levels and wide consumer acceptance.
Market Segmentation Analysis:
By Product Type
The medium chili sauce segment dominates the market, holding nearly 47% share in 2024. Its balance between heat and flavor makes it the most preferred choice among consumers globally. Medium sauces cater to a wide range of taste preferences, driving strong demand in both household and foodservice applications. Increasing product innovation with natural ingredients, low-sodium variants, and ethnic flavor blends continues to support growth. Expanding international cuisines and rising consumption of ready-to-eat foods further strengthen the segment’s leadership across major markets.
- For instance, Cholula launched a total of 11 new products in May 2025, and the launch included both medium-heat and mild-heat options. The new product lineup of 11 items included one mild seasoning mix (Pork Carnitas Mild Seasoning Mix), one medium seasoning mix (Original Fajita Medium Seasoning Mix), and other items with varying heat levels like cooking sauces with mild to medium heat, cremosa sauces, and a chili crisp.
By Packaging
The bottles segment leads the chili sauce market with approximately 52% share in 2024. Bottled packaging ensures convenience, portion control, and extended shelf life, which are key preferences among retail consumers. Manufacturers are introducing sustainable bottle materials and smart labeling to attract eco-conscious buyers. The growing demand from restaurants, catering services, and home users enhances this segment’s dominance. Transparency in glass bottles also promotes brand visibility and product appeal, making bottles the most widely adopted packaging format in both premium and mass-market categories.
- For instance, Heinz introduced a 100% recyclable squeezy cap for bottles in 2021.
By Distribution Channel
The hypermarkets and supermarkets segment dominates the chili sauce market with around 43% share in 2024. Wide product availability, frequent promotional discounts, and strong visibility of multiple brands drive consumer preference for offline retail formats. These outlets allow customers to compare flavors, packaging, and prices directly, enhancing purchase confidence. Growing expansion of organized retail chains in Asia-Pacific and Europe continues to support this segment’s leadership. However, online stores are showing rapid growth due to the rising popularity of e-commerce and doorstep delivery services.
Key Growth Drivers
Rising Global Demand for Spicy Flavors
The growing consumer preference for spicy and bold flavors is driving strong demand for chili sauces worldwide. Changing eating habits and the increasing popularity of Asian, Latin American, and African cuisines are expanding the market base. Food manufacturers are incorporating chili-based condiments into diverse products to meet evolving taste preferences. This widespread acceptance of spicy flavors across restaurant chains, fast food outlets, and home cooking continues to strengthen market growth.
- For instance, TABASCO Original Red measures 2,500–5,000 Scoville Heat Units.
Expansion of Foodservice and Quick-Service Restaurants
Rapid growth in the global foodservice and quick-service restaurant sectors significantly boosts chili sauce consumption. Restaurants and fast-food chains use chili sauces as key flavor enhancers, sauces, and condiments in multiple dishes. The rising trend of dining out and takeaway culture further increases bulk demand from commercial kitchens. Product partnerships between condiment producers and QSR brands enhance supply chains, supporting consistent growth across urban and semi-urban markets.
- For instance, McDonald’s reports over 44,000 locations in 100+ countries worldwide.
Innovation in Product Formulation and Packaging
Continuous product innovation through new flavors, organic ingredients, and sustainable packaging fuels market expansion. Manufacturers are investing in cleaner labels, additive-free options, and environment-friendly packaging to attract health-conscious consumers. Portable packaging formats such as squeezable bottles and single-serve sachets are improving convenience and shelf appeal. These developments not only enhance brand differentiation but also expand the consumer base across multiple demographics and retail channels.
Key Trends & Opportunities
Growing Popularity of Ethnic and Fusion Cuisines
The global rise of ethnic and fusion cuisines offers major growth opportunities for chili sauce manufacturers. Consumers are increasingly experimenting with cross-cultural flavors, blending traditional chili sauces into new culinary experiences. Food producers are capitalizing on this trend by introducing regional spice blends and premium artisanal products. This shift toward authentic and experimental food experiences is creating fresh avenues for premiumization and brand expansion.
- For instance, Lao Gan Ma produces more than 3 million bottles of hot sauce daily, thanks to automated and smart manufacturing processes, supporting global fusion use.
Rising Adoption of E-commerce and Direct-to-Consumer Channels
The rapid expansion of online retailing has emerged as a key opportunity for chili sauce brands. E-commerce platforms offer extensive product reach, ease of comparison, and personalized marketing options. Direct-to-consumer models allow brands to engage customers with subscription services and customized flavor assortments. Growing internet penetration and digital marketing strategies are reshaping purchasing behavior, accelerating sales across developed and emerging markets.
- For instance, TRUFF produced a three-part docuseries titled "The Secret to Selling 100 million dollars worth of hot sauce," which was released on their YouTube channel in January and February 2023.
Key Challenges
Volatility in Raw Material Prices
Fluctuations in the prices of raw materials such as chili, vinegar, and packaging components remain a major concern. Weather uncertainties, supply disruptions, and rising transportation costs affect production stability and profitability. Manufacturers face challenges in maintaining consistent product pricing while ensuring quality and availability. Long-term supply contracts and regional sourcing strategies are increasingly vital to counter this volatility and stabilize production costs.
Intense Market Competition and Product Imitation
The chili sauce market faces high competition from numerous global and regional players offering similar products. Price-based rivalry and imitation of successful formulations reduce differentiation and brand loyalty. Maintaining innovation, flavor authenticity, and marketing consistency becomes essential for sustained growth. Smaller brands often struggle to compete with large multinational companies with stronger distribution networks and promotional budgets.
Regional Analysis
North America
North America holds the largest share of the chili sauce market, accounting for nearly 36% in 2024. The region’s dominance is driven by the high consumption of spicy foods and the widespread use of chili sauces in fast food and casual dining chains. Product innovation featuring cleaner ingredients and regional flavors supports strong demand. The United States leads the market with a strong retail presence and robust foodservice sector. Increasing Hispanic population influence and the popularity of ethnic cuisines continue to expand the market in both the U.S. and Canada.
Europe
Europe accounts for around 27% share of the chili sauce market in 2024, supported by growing consumer interest in international cuisines. The United Kingdom, Germany, and France dominate the regional demand with a strong preference for Asian and Latin American flavors. Rising popularity of gourmet condiments and premium chili sauces is reshaping the market landscape. Manufacturers are focusing on low-sugar and organic formulations to align with health-conscious trends. Expanding retail distribution networks and increased multicultural dining habits further drive consistent market growth across major European economies.
Asia Pacific
Asia Pacific represents about 24% of the chili sauce market in 2024, fueled by the region’s rich culinary diversity and growing urbanization. Countries such as China, Thailand, and India are major contributors, driven by the long-standing use of chili sauces in traditional dishes. Rapid expansion of food processing industries and international restaurant chains supports strong demand. Rising disposable incomes and exposure to global cuisine trends are encouraging premium product adoption. Local manufacturers are also innovating with unique flavor profiles to appeal to a broad range of consumers.
Latin America
Latin America holds nearly 8% share of the chili sauce market in 2024, with strong cultural integration of chili-based condiments in daily meals. Mexico and Brazil lead the regional demand due to high consumption of spicy sauces in local cuisines. Expanding retail penetration and growing exports of regional hot sauce brands are boosting overall sales. The region’s increasing tourism and popularity of Latin flavors in international markets enhance brand visibility. However, limited product standardization and fragmented distribution networks remain minor challenges to faster growth.
Middle East and Africa
The Middle East and Africa region accounts for around 5% share of the chili sauce market in 2024. Rising demand for spicy condiments in countries such as South Africa, the UAE, and Saudi Arabia drives market expansion. The influence of Asian and Mediterranean cuisines is shaping local flavor preferences. Growing urban populations and expanding modern retail channels are creating new sales opportunities. However, economic fluctuations and varying consumer spending patterns slightly restrict rapid penetration. Increasing investments by international brands are expected to strengthen market presence across emerging economies.
Market Segmentations:
By Product Type
- Mild
- Medium
- Very hot
By Packaging
- Jars
- Bottles
- Pouches
- Sachets
By Distribution channel
- Hypermarkets & supermarkets
- Online stores
- Specialty stores
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the chili sauce market features leading players such as Kraft Heinz, Huy Fong Foods, Nando’s, Lee Kum Kee, Cholula Hot Sauce, Laoganma, Lingham & Sons, MegaMex Foods, ThaiTheparos, Chung Jung One, and Real Thai (Thai Foods). The market is characterized by intense competition, driven by strong brand positioning, product diversification, and expanding global distribution networks. Companies focus on flavor innovation, regional spice blends, and clean-label formulations to attract broader consumer segments. Many manufacturers are investing in automation and sustainable packaging to enhance production efficiency and reduce environmental impact. Strategic collaborations with restaurants, retailers, and e-commerce platforms strengthen brand visibility and sales channels. Increasing marketing investments in digital promotions and influencer campaigns also play a key role in driving consumer engagement. The overall competitive environment is expected to remain dynamic, with rising demand for premium, health-oriented, and regionally inspired chili sauce variants.
Key Player Analysis
- Kraft Heinz
- Huy Fong Foods
- Nando’s
- Lee Kum Kee
- Cholula Hot Sauce
- Laoganma
- Lingham & Sons
- MegaMex Foods
- ThaiTheparos
- Chung Jung One
- Real Thai (Thai Foods)
Recent Developments
- In 2025, Cholula Hot Sauce Launched Cholula Extra Hot, a hotter version of its iconic sauce to meet fan demand with extra spicy heat and authentic Mexican flavor.
- In 2023, Kraft Heinz launched the Heinz Hot Varieties line, which includes three new spicy ketchups-Chipotle, Jalapeño, and Habanero-along with a new Heinz Hot 57 Sauce, a twist on their classic 57 Sauce
- In 2023, MegaMex Foods, operating under its HERDEZ® brand, launched a new Habanero Hot Sauce made with real habanero peppers to meet consumer demand for spicier flavor profiles.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Packaging, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Growing global appetite for spicy and ethnic flavors will continue driving market expansion.
- Increasing demand for clean-label and natural ingredient formulations will shape product innovation.
- Sustainable and recyclable packaging solutions will gain stronger adoption among manufacturers.
- E-commerce and direct-to-consumer channels will become key sales growth drivers.
- Partnerships with quick-service restaurants will strengthen supply chains and brand visibility.
- Premium and artisanal chili sauces will gain popularity among urban consumers.
- Emerging markets in Asia and Latin America will offer high-growth potential for producers.
- Technological advancements in processing will improve flavor consistency and shelf life.
- Health-oriented product variants with low sodium and sugar will see rising demand.
- Intense competition will push companies toward continuous innovation and strategic acquisitions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Chili Sauce Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Chili Sauce Market projected to grow between 2025 and 2032?
Which Chili Sauce Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Chili Sauce Market?
Who are the leading companies in the Chili Sauce Market?
Which region commanded the largest share of the Chili Sauce Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Chili Sauce Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Chili Sauce Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2636.36 million → 2032: USD 4330.5 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Chili Sauce Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Chili Sauce Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Chili Sauce Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Chili Sauce Market Drivers
- 3.3 Chili Sauce Market Restraints & Challenges
- 3.4 Chili Sauce Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Chili Sauce Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Chili Sauce Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Chili Sauce category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Chili Sauce Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Chili Sauce Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Chili Sauce. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Chili Sauce Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Chili Sauce Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Chili Sauce Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Chili Sauce (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Chili Sauce
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Chili Sauce Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Chili Sauce Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Chili Sauce Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Chili Sauce Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Chili Sauce Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Chili Sauce Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Chili Sauce Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Chili Sauce Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
