
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cytology Brushes Market Size 2024 | USD 466 million |
| Cytology Brushes Market, CAGR | 6.7% |
| Cytology Brushes Market Size 2032 | USD 782.89 million |
Market Overview:
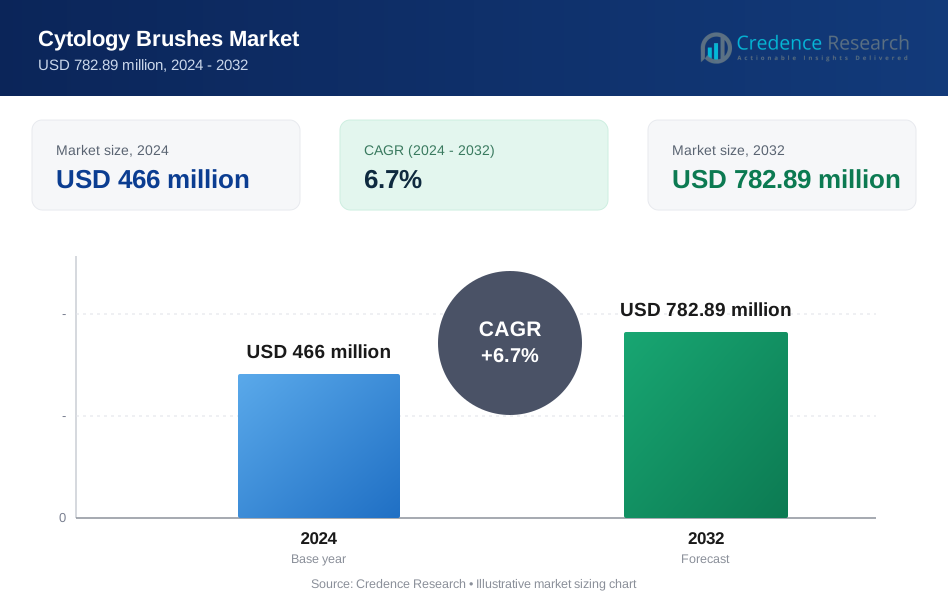
The Cytology Brushes Market is projected to grow from USD 466 million in 2024 to an estimated USD 782.89 million by 2032, with a compound annual growth rate (CAGR) of 6.7% from 2024 to 2032.
Key drivers propelling the Cytology Brushes Market include the rising incidence of cancers and other diseases that require cytological testing, such as cervical cancer, lung cancer, and bile duct conditions. The growing demand for early and accurate diagnostic methods is prompting healthcare providers to adopt advanced cytology techniques that rely heavily on specialized brushes. Innovations in brush design-offering improved flexibility, cellular yield, and compatibility with liquid-based cytology methods-are making these tools more effective and clinician-friendly. Additionally, the increasing use of disposable cytology brushes, driven by infection control protocols and single-use mandates, is boosting sales, especially in post-pandemic healthcare environments. Government-led screening programs and rising awareness about cancer prevention are also playing a significant role in market growth. Furthermore, favorable reimbursement policies in developed nations, along with expanding diagnostic infrastructure in emerging economies, are enhancing accessibility and encouraging broader adoption of cytology brushes globally.
Regionally, North America dominates the Cytology Brushes Market due to its well-established screening programs, advanced healthcare infrastructure, and favorable insurance frameworks. The region continues to see high utilization in gynecological, bronchial, and gastrointestinal procedures. Europe follows closely, particularly Western European countries like Germany, the UK, and France, where preventive healthcare is prioritized. The Asia-Pacific region is projected to witness the fastest growth, fueled by large population bases, rising cancer incidence, expanding healthcare investment, and increasing awareness about early diagnosis. Countries such as China, India, and Japan are at the forefront of this regional momentum, supported by improving access to diagnostic services and growing adoption of modern medical technologies. Meanwhile, Latin America and the Middle East & Africa represent emerging markets with promising growth potential, driven by government healthcare reforms and international investment in diagnostic infrastructure. Collectively, these regional dynamics underscore a globally expanding market with diverse growth opportunities across both mature and developing economies.
Market Insights:
- The Cytology Brushes Market is projected to grow from USD 466 million in 2024 to an estimated USD 782.89 million by 2032, registering a CAGR of 6.7% during the forecast period due to rising demand for early cancer diagnosis tools.
- Increasing incidence of cancers such as cervical, lung, and bile duct conditions is significantly driving demand for cytological testing, positioning cytology brushes as critical diagnostic tools in both developed and emerging markets.
- Growing preference for minimally invasive diagnostic procedures is enhancing the adoption of cytology brushes across various specialties, particularly in outpatient, ambulatory, and preventive care settings.
- Innovations in brush design-such as improved flexibility, better grip, and compatibility with liquid-based cytology-are enhancing diagnostic accuracy and expanding clinical applications, supporting consistent product development.
- Demand for single-use disposable brushes is accelerating due to heightened infection control measures and safety protocols, especially in post-pandemic hospital environments and oncology departments.
- Limited awareness of preventive diagnostics and inadequate access to healthcare in low-income and rural areas continues to restrict market penetration, despite ongoing government screening initiatives and infrastructure investments.
- North America leads the global Cytology Brushes Market, followed by Europe, while the Asia-Pacific region is expected to grow the fastest, driven by rising cancer incidence, growing healthcare spending, and expanding diagnostic capabilities.
Market Drivers:
Rising Prevalence of Cancer Driving Diagnostic Demand:
The growing global incidence of cancers such as cervical, lung, and gastrointestinal malignancies has increased demand for early and reliable diagnostic tools. Cytology brushes are critical in collecting high-quality cellular samples for cytological evaluations, particularly in minimally invasive procedures. Governments and health organizations are expanding screening programs targeting high-risk populations, especially in low- and middle-income countries. These initiatives fuel the need for accessible and efficient sampling tools, positioning cytology brushes as essential components in early detection protocols. It supports improved patient outcomes by enabling quicker diagnosis and timely treatment. The [Cytology Brushes Market] benefits directly from this widespread emphasis on early cancer detection and preventive care.
- For example, WHO's Global Strategy to Accelerate the Elimination of Cervical Cancer aims for 70% of women to be screened with a high-performance test by age 35 and again by 45, leading to the deployment of cytology-based screening tools in over 100 countries by 2024.
Shift Toward Minimally Invasive Procedures Enhancing Adoption:
Healthcare providers and patients increasingly prefer minimally invasive diagnostic methods due to their reduced recovery time, lower risk of complications, and improved comfort. Cytology brushes align with these preferences, offering a non-surgical solution for sample collection across a variety of body systems. Their application in procedures such as bronchoscopy, endoscopy, and colposcopy makes them valuable tools in diagnostic workflows. It encourages medical institutions to expand their adoption of cytology brushes across different specialties. The demand is particularly high in outpatient and ambulatory settings where efficiency and patient experience are prioritized. This growing shift is contributing to strong market uptake across regions.
- For example, In the United States, the Centers for Disease Control and Prevention (CDC) reported that over 15 million endoscopic procedures-many involving cytology brush sampling-are performed annually, reflecting the scale of minimally invasive diagnostics in routine care.
Technological Advancements Improving Brush Performance and Sample Quality:
Continuous innovation in brush design and material composition has significantly improved cytology brush effectiveness. Manufacturers are developing products with enhanced flexibility, better grip, and improved sample retention, which contributes to higher diagnostic accuracy. Brushes compatible with liquid-based cytology and molecular testing further strengthen their value in modern diagnostic environments. It increases clinical confidence and leads to broader usage among specialists. Product improvements are also expanding the range of diagnostic applications, including rare and complex conditions requiring precise sampling. These innovations are elevating the overall standard of cytological diagnostics, reinforcing market growth.
Infection Control Priorities Boosting Disposable Brush Segment:
The healthcare sector’s focus on infection control and safety standards is driving strong demand for single-use, disposable cytology brushes. These products reduce the risk of cross-contamination and align with strict hospital protocols and regulatory guidelines. It encourages medical facilities to shift from reusable to disposable brushes, particularly in oncology and respiratory departments. The disposable segment is also favored for its convenience and ease of handling during high-volume diagnostic procedures. Hospitals and diagnostic labs are increasingly investing in bulk supplies of disposable brushes to meet safety and efficiency goals. This trend is expanding the market’s revenue potential and shaping purchasing behaviors globally.
Market Trends:
Increasing Integration of Cytology Brushes in Cancer Screening Programs:
Governments and healthcare providers are prioritizing national cancer screening initiatives, which increasingly include cytology brush usage for early detection. Cervical and lung cancer programs, in particular, rely on brush-based cytology to collect reliable samples for analysis. The emphasis on preventive healthcare in both developed and developing countries has led to a higher demand for accurate, non-invasive diagnostic tools. The [Cytology Brushes Market] is responding with products tailored for compatibility with standardized screening workflows. It supports expanded deployment across public health systems and private clinics alike. This trend reinforces the brush’s role in front-line diagnostics and contributes to higher procedure volumes.
- For instance, the U.S. National Cancer Institute notes that over 60% of cervical cancer screenings utilize brush-based cytology techniques, and similar trends are observed in lung and gastrointestinal cancer programs.
Product Customization and Innovation Expanding Application Scope:
Manufacturers are introducing cytology brushes with specialized designs to address a wider range of clinical needs. These include variations in brush diameter, handle ergonomics, and flexibility to match different anatomical sites and procedural requirements. Customization efforts are helping improve patient comfort, sample adequacy, and clinician efficiency. It supports the growing demand from diverse specialties including pulmonology, gastroenterology, and gynecology. Some brushes are now engineered for enhanced compatibility with liquid-based cytology and molecular testing platforms. This trend is expanding the clinical utility of cytology brushes and positioning them as integral tools in multidisciplinary diagnostics.
- For example, Boston Scientific and Olympus have developed brushes with variable diameters and enhanced ergonomics, reporting improved sample adequacy rates in clinical evaluations.
Adoption of Single-Use Devices Driven by Safety and Compliance:
Hospitals and diagnostic centers are increasingly shifting toward single-use cytology brushes to meet infection control standards and regulatory requirements. Disposable brushes offer consistent sterility, reduce contamination risk, and support high procedural turnover. It aligns with hospital safety protocols, particularly in high-risk departments such as oncology, pulmonology, and critical care. The COVID-19 pandemic further accelerated this transition, emphasizing the importance of infection prevention in diagnostic procedures. The market is seeing growing production and distribution of single-use variants tailored for specific clinical scenarios. This trend is influencing procurement practices and shaping product development pipelines.
Growth of Emerging Markets Accelerating Global Market Expansion:
Developing regions across Asia-Pacific, Latin America, and parts of Africa are witnessing rising demand for cytological diagnostics due to increased healthcare access. Public and private investment in medical infrastructure and cancer screening programs is supporting broader adoption of diagnostic tools, including cytology brushes. The [Cytology Brushes Market] is expanding its footprint in these regions by targeting cost-effective products and localized distribution models. It benefits from rising disease awareness, growing diagnostic capacity, and favorable government health initiatives. Market players are entering partnerships with local suppliers and institutions to strengthen reach. This trend is creating new revenue streams and supporting long-term global market growth.
Market Challenges Analysis:
Limited Awareness and Access in Low-Income Regions Restricting Market Penetration:
A major challenge in the [Cytology Brushes Market] is the limited awareness of cytological screening procedures in low-income and rural areas. Many patients in these regions remain unaware of preventive diagnostics, leading to delayed disease detection and lower utilization of cytology brushes. Inadequate healthcare infrastructure, a shortage of trained personnel, and limited availability of diagnostic equipment further reduce market reach. It affects early cancer detection rates and slows the adoption of routine cytological examinations. Government programs in some countries are expanding access, but uneven implementation continues to hinder widespread uptake. Bridging this awareness and access gap remains a critical barrier to inclusive market growth.
Stringent Regulatory Requirements and Pricing Pressure Impacting Manufacturers:
Cytology brush manufacturers must navigate complex and evolving regulatory frameworks across multiple regions, which can delay product approvals and market entry. Compliance with safety standards, sterilization protocols, and labeling regulations often requires significant investment in testing and documentation. The [Cytology Brushes Market] also faces pricing pressure due to competitive bidding processes in public health systems and cost-sensitive purchasing behavior in emerging economies. It challenges manufacturers to balance product quality with affordability while maintaining margins. Rising material and logistics costs further strain profitability. These factors create a difficult environment for smaller players and limit the pace of innovation in lower-cost product segments.
Market Opportunities:
Rising Demand for Early Cancer Detection Creating Growth Potential:
The growing emphasis on preventive healthcare and early cancer detection presents strong growth opportunities for the [Cytology Brushes Market]. Government-led screening programs and awareness campaigns are encouraging routine cytological testing, especially for cervical and lung cancers. It opens the door for higher product adoption across both public and private healthcare settings. Expansion of national health insurance in emerging markets further supports access to diagnostic tools like cytology brushes. Increasing preference for minimally invasive procedures enhances their relevance in outpatient and ambulatory care. These developments create a favorable environment for manufacturers to scale production and expand their reach.
Technological Innovation and Customization Unlocking New Applications:
Ongoing innovation in brush design and compatibility with advanced diagnostic platforms is broadening the clinical utility of cytology brushes. Tailored products for specific anatomical sites or sampling needs offer new revenue channels for manufacturers. The [Cytology Brushes Market] benefits from the growing integration of cytology with molecular diagnostics and liquid-based cytology systems. It strengthens demand from specialized fields such as oncology, gastroenterology, and pulmonology. Digital pathology and telemedicine trends also support market expansion by connecting underserved areas to expert diagnostic interpretation. These advancements provide strategic opportunities to introduce differentiated, high-value products across global markets.
Market Segmentation Analysis:
By Product Type
Plastic cytology brushes dominate the market due to their enhanced flexibility, improved patient comfort, and superior sample collection efficiency. They are widely adopted across diverse diagnostic procedures. Metal brushes, while durable, are less preferred in sensitive anatomical areas. The shift toward patient-centric tools and compatibility with modern diagnostic systems supports the growing demand for plastic variants.
- For instance, company reports indicate that plastic variants account for over 80% of cytology brush sales globally, reflecting their widespread adoption across diagnostic procedures.
By Application
Gynecological applications hold a substantial share, driven by widespread cervical cancer screening programs. Respiratory tract and gastrointestinal applications also account for a significant portion of the [Cytology Brushes Market], with rising lung and digestive tract cancer cases contributing to adoption. Urinary and oral applications represent emerging areas, supported by growing awareness of oral and bladder cancers. Oncology-focused use cases continue to expand, reflecting broader cancer diagnostic needs across specialties.
- For instance, According to WHO, over 100 million women are screened for cervical cancer annually using cytology-based methods, with brushes being the primary collection tool in most programs.
By End-User
Hospitals are the primary end users due to their comprehensive diagnostic capabilities and high patient volumes. Diagnostic centers follow closely, especially in urban regions where outpatient cytological testing is growing. The expansion of specialized labs and cancer care facilities supports demand in both segments.
Segmentation:
By Product Type
- Metal Cytology Brushes
- Plastic Cytology Brushes
- Respiratory Tract Applications
- Gastrointestinal Applications
- Gynecological Applications
- Urinary Tract Applications
- Oral Applications
- Oncology Applications
- Hospitals
- Diagnostic Centers
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Holds the Leading Market Position
North America accounts for the largest share of the Cytology Brushes Market, contributing approximately 38% of the global revenue. This dominance is supported by well-established screening programs, particularly for cervical and lung cancer, across the United States and Canada. Strong reimbursement systems, advanced diagnostic infrastructure, and widespread adoption of minimally invasive procedures continue to drive market growth. High awareness levels among patients and practitioners further reinforce demand across hospitals and diagnostic centers. The presence of leading manufacturers and a favorable regulatory landscape support ongoing product innovation and early adoption. It remains the benchmark region for clinical best practices and technology integration in cytological diagnostics.
Europe Maintains Strong Demand Across Developed Nations
Europe holds around 27% of the global Cytology Brushes Market, with demand concentrated in countries such as Germany, the United Kingdom, France, and Italy. National cancer screening programs and a proactive approach to preventive healthcare fuel demand for cytological tools. Governments across Western Europe invest in public health infrastructure, ensuring access to routine diagnostics in both public and private sectors. Regulatory alignment and high clinical standards promote the adoption of disposable and technologically advanced brushes. The aging population and growing cancer burden across the region further support market expansion. It benefits from a mature but steadily advancing diagnostic ecosystem focused on quality and efficiency.
Asia-Pacific Emerges as the Fastest-Growing Region
The Asia-Pacific region is projected to expand at the highest CAGR and currently holds about 21% of the global market share. Growth is driven by rising cancer incidence, increasing healthcare expenditure, and expanding access to diagnostic services in China, India, and Southeast Asia. Government-led health initiatives and cancer screening campaigns are improving early detection efforts, particularly in urban centers. Rapid infrastructure development and a large patient base present strong opportunities for both global and local manufacturers. It continues to attract investment in laboratory capacity and healthcare technology. The remaining share is distributed across Latin America, the Middle East, and Africa, where adoption is growing due to policy reforms and international support for diagnostic advancements.
Key Player Analysis:
- Boston Scientific Corporation
- Cook Group
- CONMED Corporation
- Olympus Corporation / Olympus America
- Telemed Systems Inc.
- Medi-Globe GmbH
- Cosmomed SA
- McKesson Medical-Surgical Inc.
- Henry Schein Medical
- EndoChoice
- Hobbs Medical
- US Endoscopy
- Advin Health Care
- Narang Medical Limited
- Puritan Medical Products
- Copan Italia
- Diapath
- L. Medical
- Gyneas
- Medgyn
Competitive Analysis:
The Cytology Brushes Market is characterized by the presence of both global medical device leaders and specialized manufacturers. Companies such as Boston Scientific, Olympus Corporation, and Cook Group maintain strong market positions through broad product portfolios, advanced technology, and extensive distribution networks. It remains competitive due to continuous innovation in brush design, focus on patient safety, and responsiveness to clinical demands. Mid-sized players like Medi-Globe GmbH, CONMED Corporation, and US Endoscopy contribute to product diversification and regional expansion. Emerging manufacturers from Asia and Europe are strengthening their presence through cost-effective solutions and strategic partnerships. Market participants focus on product quality, regulatory compliance, and clinical performance to maintain their positions. The competitive landscape reflects a mix of established brands and agile newcomers, all striving to address rising diagnostic needs and regulatory requirements across global markets. The Cytology Brushes Market continues to evolve with increasing emphasis on customization, disposability, and clinical efficacy.
Recent Developments:
- In February 2025, Boston Scientific Corporation introduced an advanced disposable cytology brush in Europe. This new product enhances sample collection efficiency and improves diagnostic accuracy during cervical screenings, reflecting the company’s ongoing commitment to innovation and patient safety.
- In June 2025, CONMED Corporation made its 2025 first-quarter financial results public, reporting a 3.8% year-over-year increase in sales to USD 321.3 million Though not a product-specific announcement, this financial milestone underscores CONMED’s strong performance, suggesting sustained investment capacity in core portfolios, including cytology brushes.
Market Concentration & Characteristics:
The Cytology Brushes Market displays a moderately fragmented structure with a mix of multinational corporations and regional manufacturers competing across segments. It features a balance between innovation-driven global leaders and price-competitive suppliers targeting emerging markets. Leading players focus on technological advancements, disposable product lines, and compliance with evolving clinical standards. It is characterized by low product differentiation but high regulatory oversight, which creates entry barriers for new participants. Demand is volume-driven, influenced by national screening programs and hospital procurement contracts. The market relies on B2B distribution models, with procurement centralized through hospitals, diagnostic labs, and government agencies. The Cytology Brushes Market remains sensitive to price, quality, and clinical utility.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type, By Application, By End-User and By Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising global cancer burden will continue to drive demand for cytology-based diagnostics.
- Advancements in brush design will support higher accuracy and broader clinical utility.
- Increased preference for disposable brushes will reshape procurement practices and manufacturing priorities.
- Integration with liquid-based cytology and molecular diagnostics will expand application scope.
- Emerging markets in Asia-Pacific and Latin America will offer high-growth opportunities through improved healthcare access.
- Strategic collaborations between device manufacturers and diagnostic labs will enhance product adoption.
- Regulatory emphasis on safety and quality will influence product development and market entry.
- Public health initiatives and screening campaigns will sustain long-term volume demand.
- Digital pathology and AI-enabled cytology analysis will complement market expansion.
- Competitive pricing and localized manufacturing will be key for penetrating cost-sensitive regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Cytology Brushes Market?
What factors are driving the growth of the Cytology Brushes Market?
What are the key segments within the Cytology Brushes Market?
Who are the major players in the Cytology Brushes Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 466 million → 2032: USD 782.89 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cytology Brushes Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cytology Brushes Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cytology Brushes Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cytology Brushes Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cytology Brushes Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cytology Brushes Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cytology Brushes Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cytology Brushes Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 466 million → 2032: USD 782.89 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cytology Brushes Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cytology Brushes Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cytology Brushes Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cytology Brushes Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
