
Hospital platforms and national apps shape EHR spending
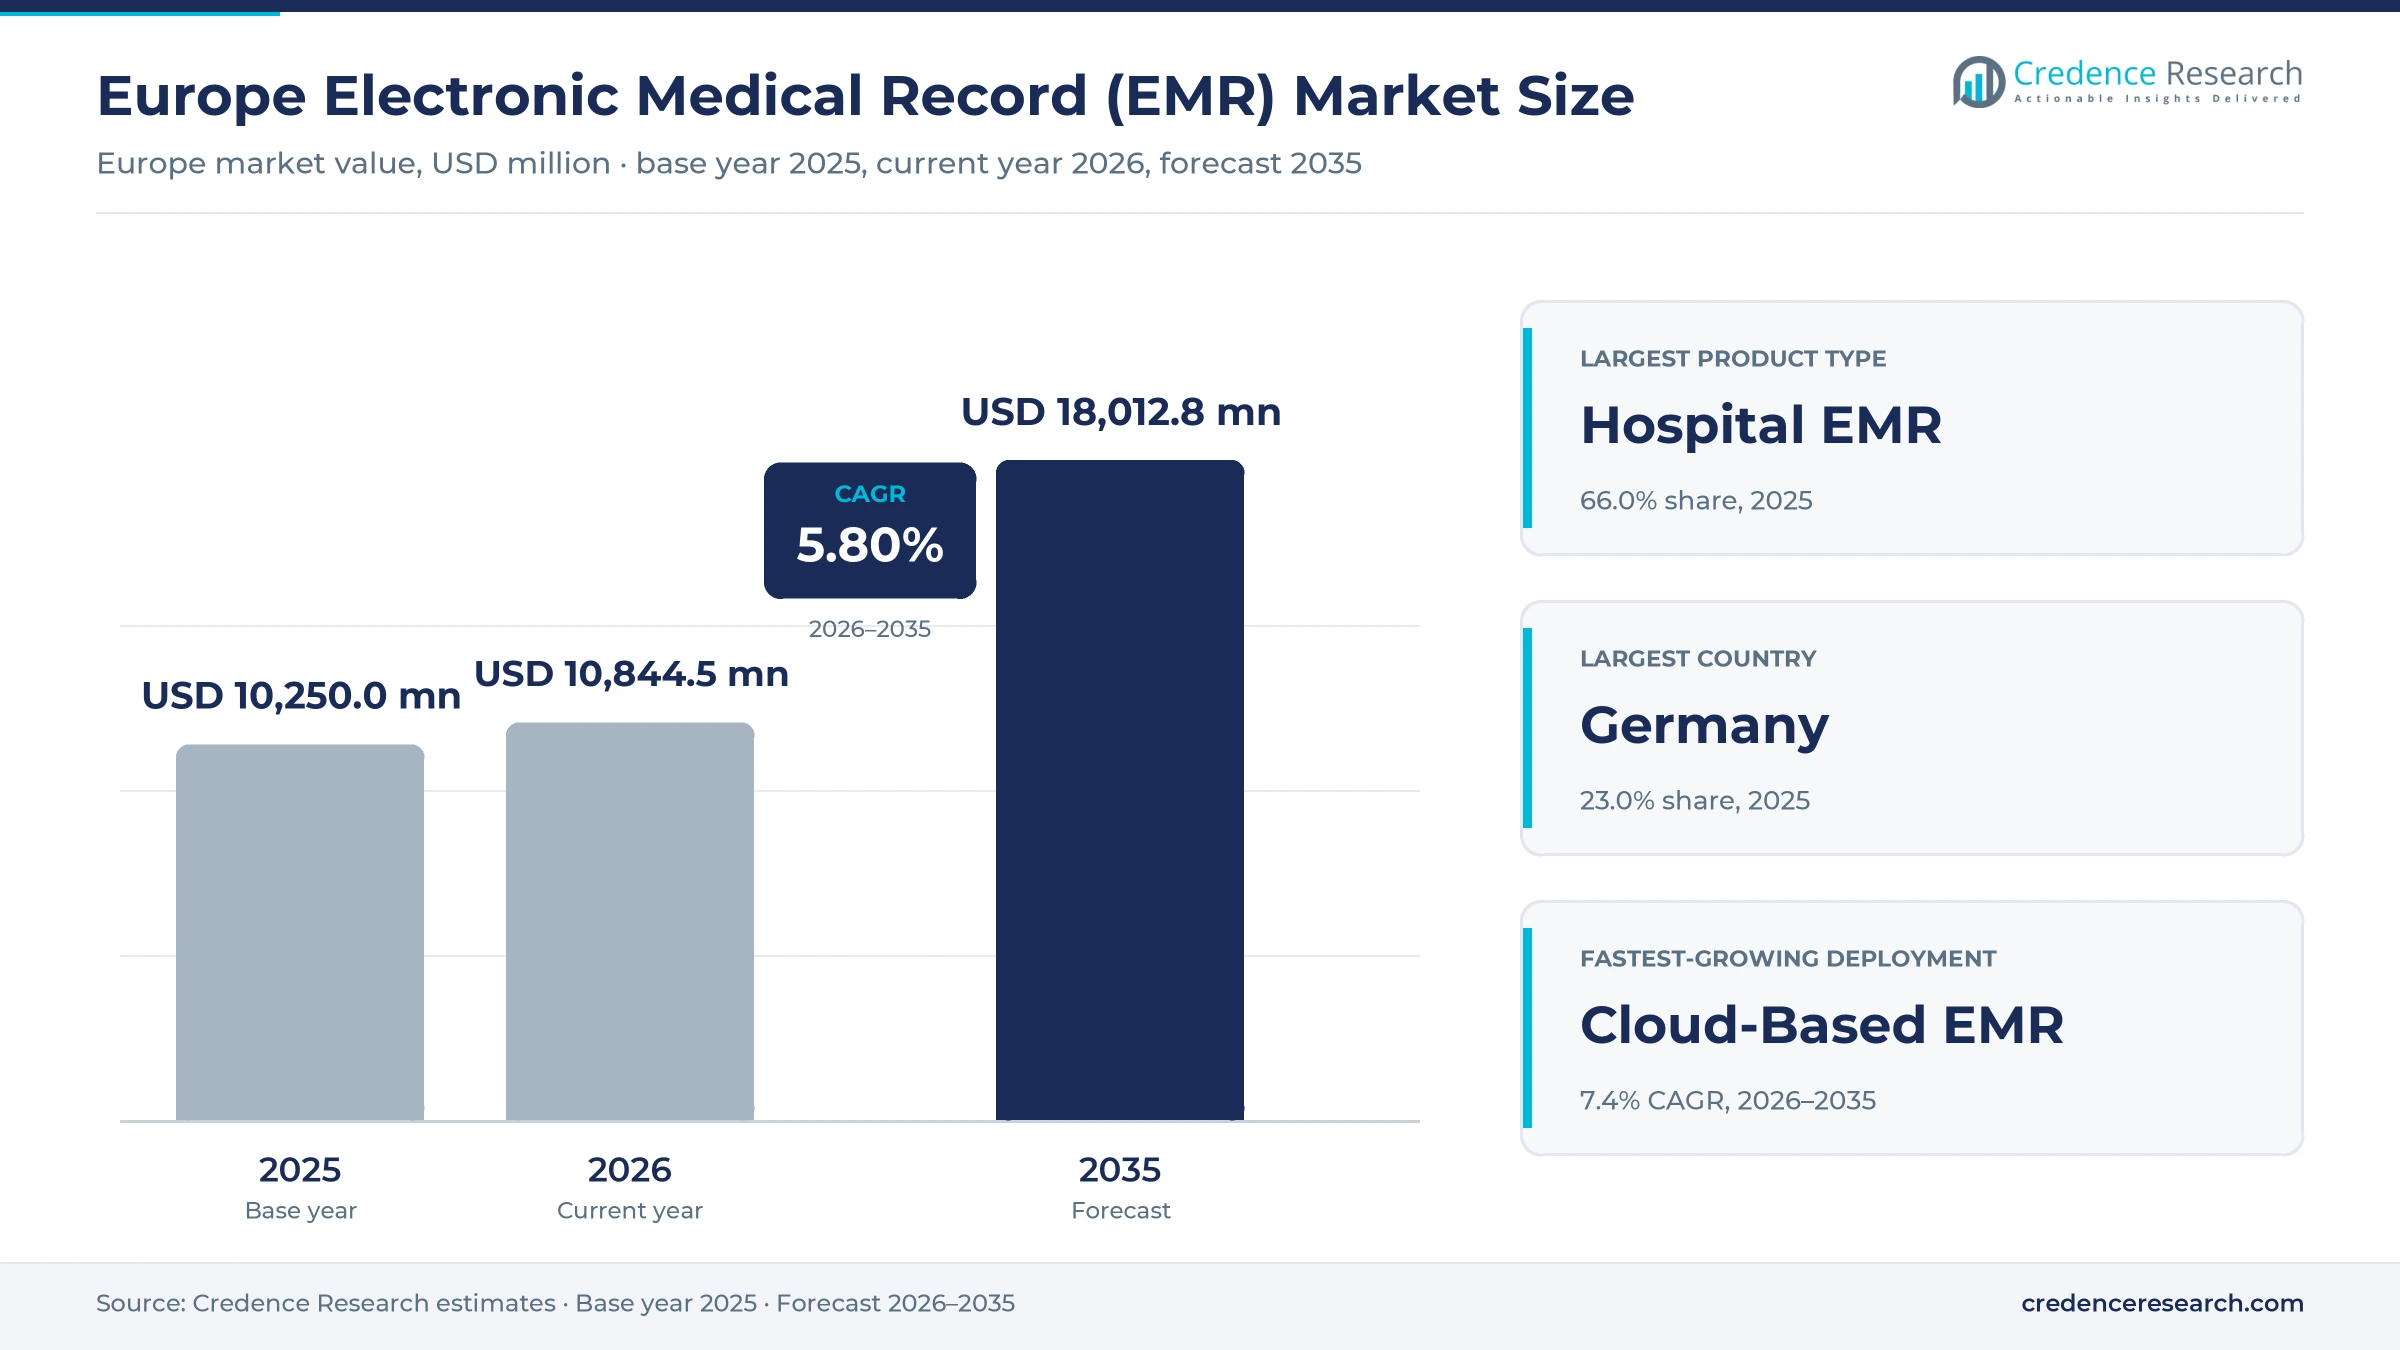
The Europe electronic medical record (EMR) market was valued at USD 10.25 billion in 2025 and is projected to increase from USD 10.84 billion in 2026 to USD 18.01 billion by 2035, registering a CAGR of 5.80% during 2026–2035. Demand comes from acute hospitals that replace or extend enterprise record platforms, from general practices and specialist clinics that need certified office software, and from regional health services that must feed national patient records. Germany held the largest country share, 23.0% in 2025, because hospital penalty rules and the mandatory national ePA push spending in both inpatient and office care. Italy is the fastest-growing country at 6.6% a year, as regions finish recovery-plan work on the national health file. Regulation is the main change in buyer behavior, since the European Health Data Space entered into force in March 2025 and requires certified systems to exchange patient summaries and ePrescriptions across borders by March 2029.
Hospital platforms and practice software make up the spend
The market counts what European hospitals, clinics and physician practices pay for software that creates, stores and shares patient medical records, including hospital EMR platforms, ambulatory practice systems, implementation, training, hosting and support. Value is measured at the contract or subscription price paid by the provider or the public health service that buys for it.
The count excludes national patient apps and portals run by governments or insurers, standalone imaging archives, laboratory systems bought separately, and general hospital IT hardware. Value flows from software suppliers and their implementation partners to hospitals and practices, which then feed national records such as the ePA in Germany and the health file in Italy.
Europe Electronic Medical Record (EMR) Market Insights
- The Europe electronic medical record (EMR) market rises from USD 10.25 billion in 2025 to USD 18.01 billion by 2035, a 5.80% CAGR during 2026–2035, as EHDS certification and hospital replacements sustain spending.
- Germany held 23.0% of 2025 value, and more than 100 million documents had been uploaded to its national ePA by June 2026, according to gematik figures cited by AOK.
- Hospital EMR held 66.0% of 2025 value, as acute trusts and university hospitals sign multi-year enterprise contracts covering licenses, hosting and implementation.
- The European Health Data Space entered into force on March 26, 2025, and patient summaries and ePrescriptions must be exchanged across all member states by March 2029.
- Private equity now controls Nexus and holds a large stake in CompuGroup Medical, after TA Associates and CVC completed tender offers in January and June 2025.
Hospital records and licensed software hold most value
Hospital EMR leads as cloud vendors enter practices
Based on product type, the market is categorized into hospital EMR and ambulatory EMR. Hospital EMR led with 66.0% of 2025 value because acute hospitals buy enterprise platforms that bundle licenses, hosting and multi-year implementation, and shared regional awards, such as the Epic contract that four Somerset and Dorset NHS trusts signed in March 2026, now bundle several hospitals onto one platform. Ambulatory EMR grows fastest at 6.4% a year as cloud vendors enter office care, and Doctolib, which serves 520,000 health professionals, now competes with Cegedim and CompuGroup Medical in French practice software, Siècle Digital reported in May 2026. Incumbent practice software suppliers now face a well-funded cloud rival in their home market.
Software leads while large rollouts lift services
Based on component, the market is categorized into EMR software and EMR services. EMR Software led with 55.0% of 2025 value because licenses and subscriptions recur at every installed site, and German penalty rules give digital nursing and treatment documentation the largest weight, up to 0.6 points of the hospital deduction in 2025 and 2026. EMR Services grow fastest at 6.2% a year as large replacements need years of build and training, and Charité Berlin's planned Epic project, priced in the table below, runs implementation support through 2029, HTN reported. Implementation partners with German-speaking staff gain the most from that work.
On-site servers lead as hosted records gain
Based on deployment, the market is categorized into client server setup EMR, hybrid server setup EMR, and cloud-based EMR. Client Server Setup EMR led with 47.0% of 2025 value because most hospitals still run records in their own data centers, and Västra Götaland extended its existing Melior record for eight years when it dropped its replacement project in August 2026. Cloud-Based EMR grows fastest at 7.4% a year as hosting moves to healthcare cloud infrastructure, and Hospital Universitario Son Espases in Palma became the first Spanish hospital to move its record to Oracle Cloud Infrastructure in February 2026, Portal ERP reported.
Hospitals lead while GP practices grow fastest
Based on end user, the market is categorized into hospitals, specialized clinics, ambulatory surgical centers, general physician clinics and others. Hospitals led with 61.0% of 2025 value because the record sits at the center of each hospital information system, and two Essex trusts awarded Oracle Health a 65 million pound contract in December 2024 for go-live in 2026 and 2027. General Physician Clinics grow fastest at 6.7% a year as Germany made ePA use mandatory for doctors from Oct. 1, 2025, and more than 93,000 practices now open the ePA each week, according to gematik.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Hospital EMR | 66.0% | Ambulatory EMR | 6.4% |
| By Component | EMR Software | 55.0% | EMR Services | 6.2% |
| By Deployment | Client Server Setup EMR | 47.0% | Cloud-Based EMR | 7.4% |
| By End User | Hospitals | 61.0% | General Physician Clinics | 6.7% |
Multi-year hospital contracts set EHR pricing
Hospital record systems are bought through public tenders as multi-year contracts that bundle software licenses or subscriptions, hosting, implementation staff and support, so the headline value reflects scope and duration more than a unit price. Contract size rises with the number of sites, beds and modules, and with how much legacy data must be migrated. Shared regional awards spread fixed build costs across several trusts. Office software works differently, with monthly fees per physician that compete on billing links and ease of use. Penalty rules in Germany shift part of the cost of not buying onto hospital budgets, which strengthens supplier pricing for documentation modules.
| Contract or offer | Typical price or fee | Basis |
|---|---|---|
| Epic EHR, four Somerset and Dorset NHS trusts | 222 million pounds contract | Verdict, March 2026 |
| Oracle Health EPR, two Essex NHS trusts | 65 million pounds contract | Mid and South Essex NHS FT, December 2024 |
| Epic EHR, Charité Berlin | About 200 million euros financial plan incl. licenses and implementation | HTN, December 2025 |
| AI modules for Sergas IANUS 5 record, Galicia | 8.57 million euros for 36 months, up to 13 million with extensions | El Español, August 2026 |
| German hospitals missing required digital services | Deduction of up to 2% of each inpatient invoice | Rödl & Partner, September 2025 |
| Doctolib practice software at launch, France | 135 euros per month per doctor | Caducée, March 2021 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
EU deadlines and national funds drive record upgrades
EHDS deadlines force EHR upgrades across member states
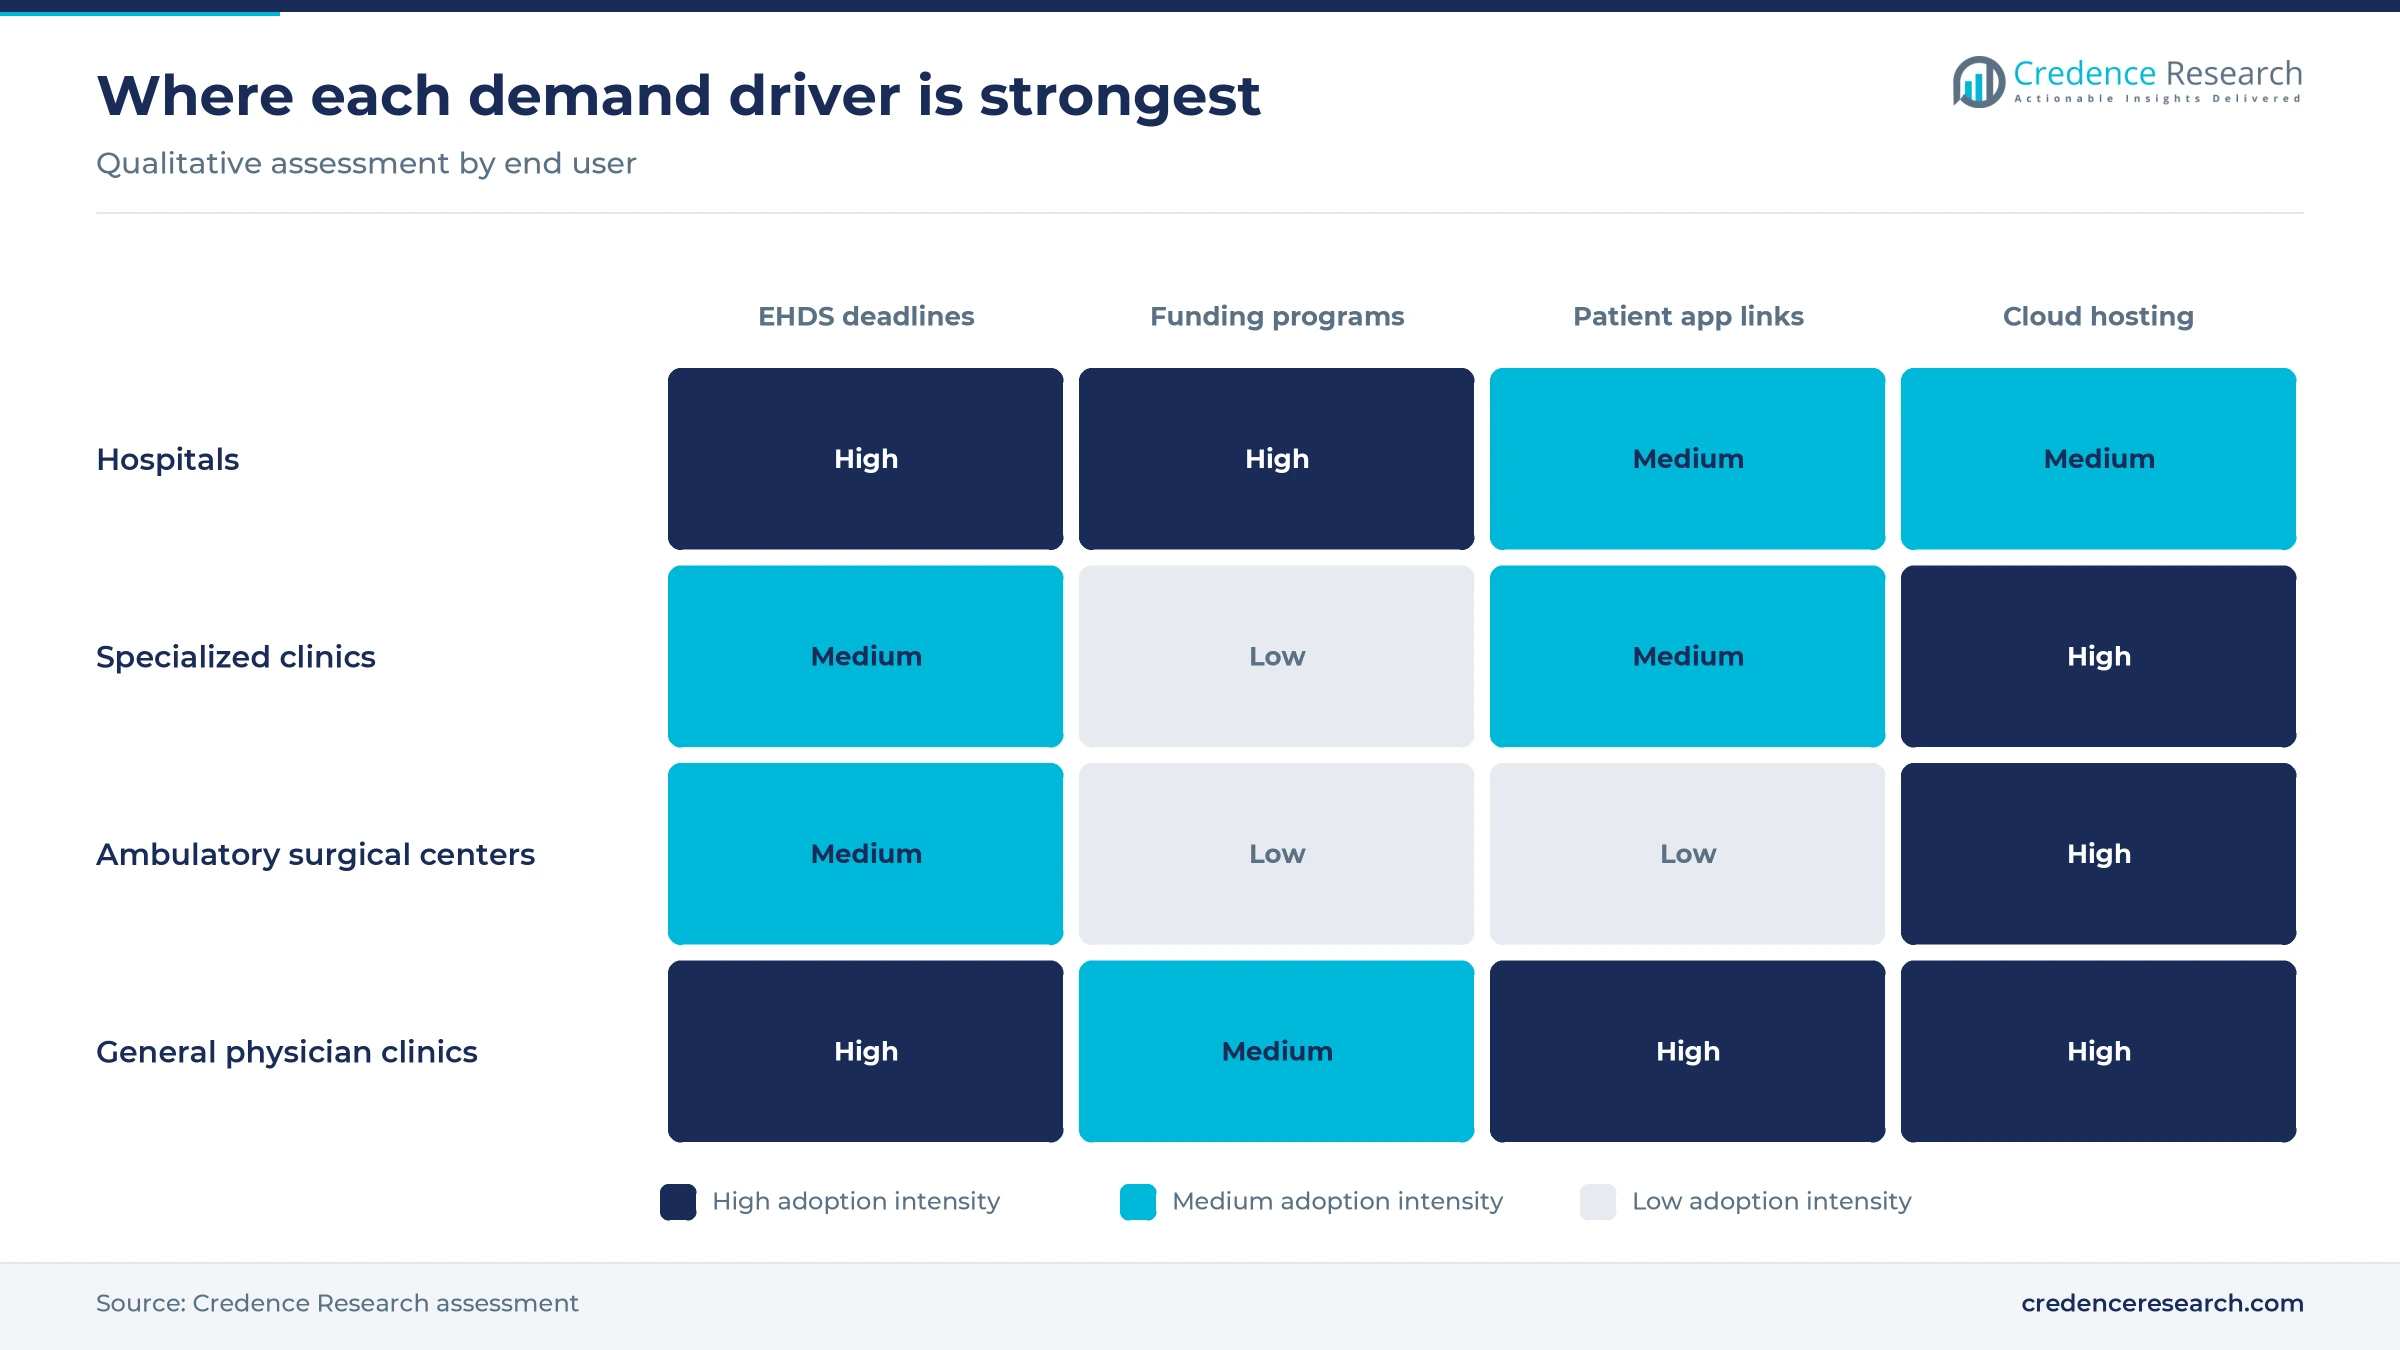
The European Health Data Space turns interoperability from a procurement preference into a legal duty, which pushes hospitals and practices to replace or upgrade record systems that cannot export standard data. The regulation entered into force on March 26, 2025, according to the European Commission, and patient summaries and ePrescriptions must flow across all member states by March 2029. Medical images, laboratory results and hospital discharge reports follow by March 2031. Makers of EHR systems must also certify that their products meet the regulation's security and interoperability criteria. The heaviest upgrade bills before the 2029 cutoff fall on buyers running heavily customized local systems, which hands certified vendors a replacement pipeline.
German hospital penalties reward digital documentation
German hospitals now lose income when core digital services are missing, which converts record modules from optional projects into revenue protection. The Hospital Future Fund holds 4.3 billion euros, 3 billion from the federal government and 1.3 billion from the states and other payers, paid as grants for hospital digitization. Since January 2025, hospitals that do not offer the required services face a deduction of up to 2% of each inpatient invoice, according to Rödl & Partner. Through 2026 only availability is assessed, but usage is measured from the end of 2027 and carries 80% of the weighting by 2031. Hospitals that bought software but never rolled it out to wards carry the most risk, and that gap gives suppliers of nursing documentation, medication management and patient portal modules a steady flow of rollout work.
NHS digitization closes the last EPR gaps in England
The NHS in England is completing its electronic patient record coverage, so hospital spending stays high even where most trusts already run a system. NHS England board papers listed 19 trusts without an EPR in March 2025, all procuring or implementing one, and said 96% of trusts were on track to have an EPR by March 2026, HTN reported. The same papers said 70% of trusts were on track to meet core digital maturity by that date. Highly digitized trusts showed a 13% lower cost per admitted patient episode and a 4.5% shorter inpatient stay. Vendors gain new installs at laggard trusts and optimization work at trusts that so far have only replaced paper.
Italy's recovery funds pay for the national health file
Italy ties recovery-plan payments to measurable health file milestones, which forces regions and their software suppliers to deliver working record feeds rather than pilots. Investment 1.3 of the national recovery plan allocates 1.38 billion euros to health information systems, with most of it aimed at the second-generation Fascicolo Sanitario Elettronico and a national health data ecosystem. The plan set a target of 85% of general practitioners feeding the file by June 2025, and full regional implementation by 2026. Disbursement by the European Commission depends on results rather than spending, so regions that miss milestones risk losing funds. Suppliers that can adapt hospital, laboratory and primary care systems to the national document standards win short, deadline-driven contracts.
Private equity and patient apps reshape supply
Private equity shifts German vendors off the exchange
Ownership of Europe's mid-sized record suppliers is shifting from public markets to private equity, which favors longer product roadmaps and more acquisitions. TA Associates completed its tender for Nexus AG on Jan. 3, 2025, securing 94.95% of the shares at 70 euros each, according to TA. Nexus sells a clinical information system to hospitals, psychiatric clinics and rehabilitation centers from sites in nine European countries. CVC concluded its delisting offer for CompuGroup Medical on June 24, 2025, holding about 27.78% while the founding Gotthardt family retained about 50.12%. Both companies have left the Frankfurt exchange, so buyers now judge them on contract delivery rather than quarterly reports. Hospitals and practices gain vendors with capital for EHDS work, but may face tougher renewal pricing.
Patient apps shift records toward national front doors
Governments are shifting patient access to national apps, which turns the hospital or practice record into a data supplier for a national file. In Germany, more than 100 million documents had been uploaded to the ePA by June 2026, and more than 21 million medication list retrievals take place each week, according to gematik figures cited by AOK. England's 10 Year Health Plan of July 2025 promises a single patient record that patients can view on the NHS App by 2028, subject to legislation, Pulse reported. That record would require GP practices and other providers to make the information they record available. Closed systems lose relevance once the national file becomes the patient's front door, so certified connectors and standard interoperability solutions turn into a condition for winning tenders.
Ireland's national EHR tender opens a greenfield deal
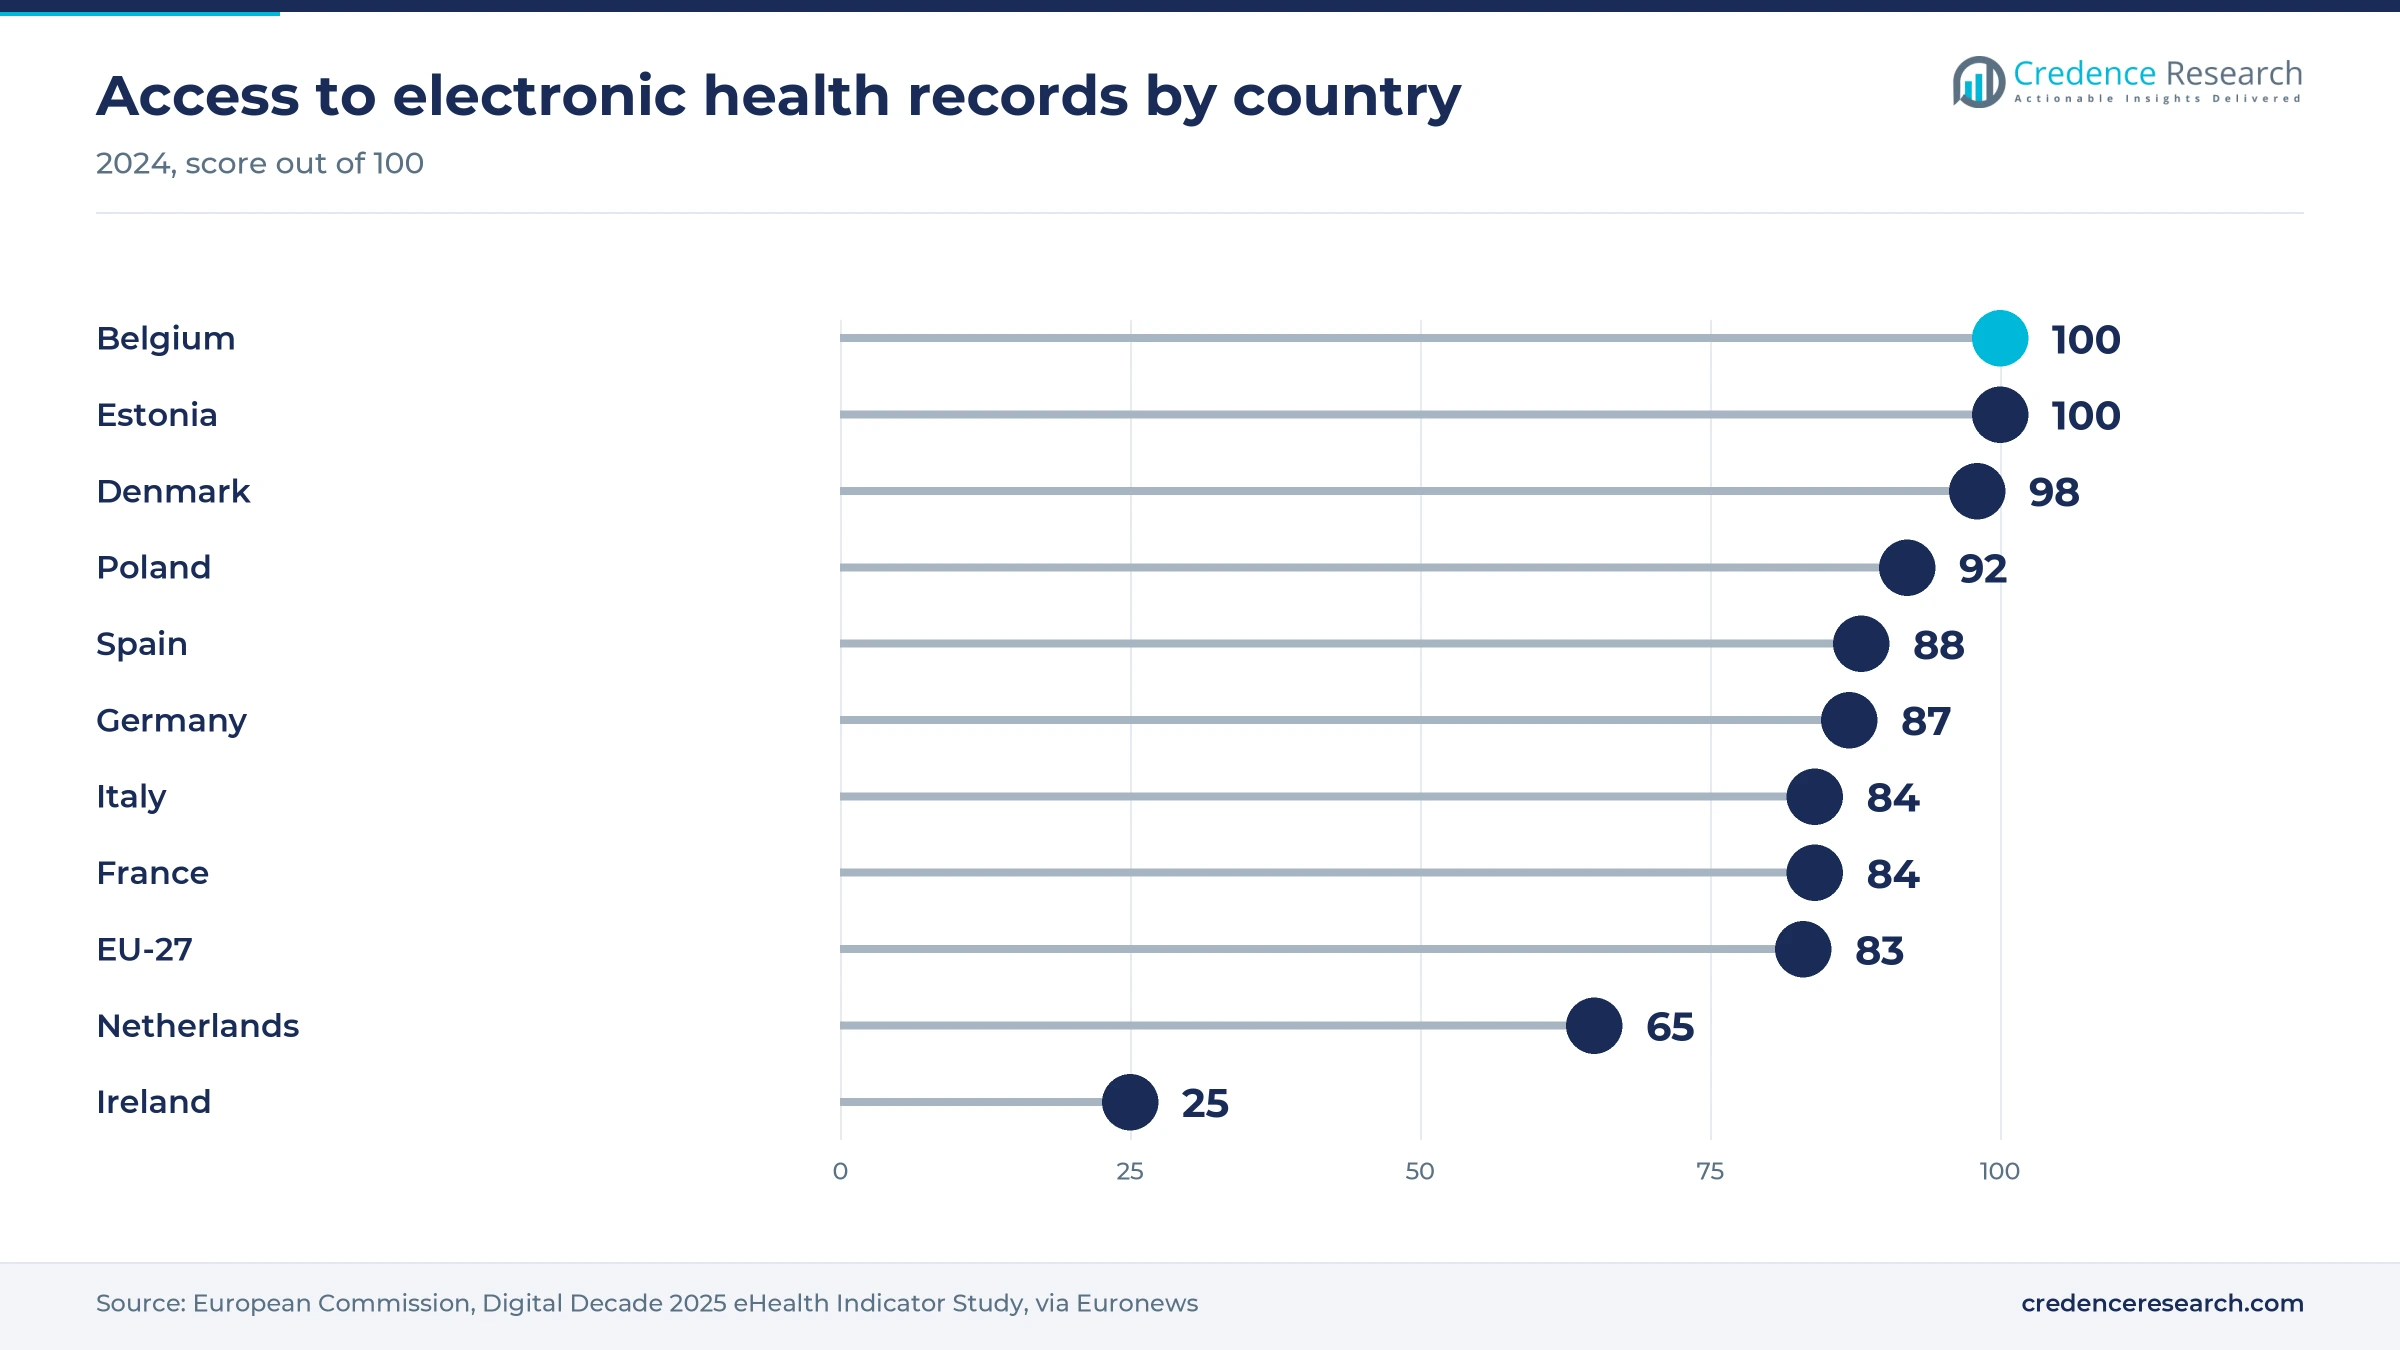
Ireland offers the clearest greenfield opening in Western Europe, because the country still lacks national online access to patient records. The government approved the Health Service Executive's move to procurement for a national electronic health record on Feb. 5, 2026, the Medical Independent reported, with vendor shortlisting next and a phased rollout across all health regions after the tender. Ireland scored 25% on the European Commission's 2024 index of access to electronic health records, against an EU average of 83%, Euronews reported. It was also the only EU country without online access through a portal. A single national award would favor suppliers with large integrated deployments and Irish implementation partners.
AI modules inside existing records create add-on sales
Health services that keep their core record systems are opening separate budgets for AI tools inside them, which creates add-on sales without a full replacement. Galicia's health service Sergas put out an 8.57 million euro tender in August 2026 to add AI tools, genomic data integration and wider telemonitoring to its IANUS 5 record, with offers due by Sept. 4, 2026. With two extensions, the contract could reach 13 million euros, El Español reported. In Germany, digital clinical decision support is one of the five services that count toward the hospital deduction, carrying up to 0.2 points of it in 2025 and 2026. Suppliers with certified AI modules can sell into installed bases that are not due for replacement.
Failed rollouts and cyber risk slow new contracts
Failed regional rollouts raise buyer caution
Large single-platform programs can fail late and expensively, which makes Nordic and other public buyers slower to sign comparable deals. Västra Götaland's regional board approved on Aug. 27, 2026, an agreement to end its 2018 Millennium contract with Oracle, paying 657 million Swedish kronor in termination compensation, according to the region. Keeping its older Oracle systems running will add about 40 million kronor a year. Regions with half-finished migrations are most exposed, as are vendors bidding into tenders that now demand modular designs.
Cyberattacks on hospitals raise security costs
Ransomware and other attacks turn every connected record system into an operational risk, which raises security spending before any new clinical module is bought. EU countries reported 309 significant cybersecurity incidents in healthcare in 2023, more than any other critical sector, according to the European Commission. Its action plan of Jan. 15, 2025, extends support to general practices and proposes a pan-European support center for hospitals. Small hospitals and practices without in-house security staff are most exposed, since cloud migration and national connectors widen their attack surface.
Uneven regional adoption delays returns in Italy
Regional gaps in record use limit the value of national investment, because a health file helps clinicians only when documents and consent are in place. As of Sept. 30, 2025, no Italian region offered all 20 document types in the file, with Emilia-Romagna at 17 and Puglia at 11, according to the GIMBE foundation as reported by LaPresse. Only 44% of citizens had consented to clinicians consulting their file, ranging from 2% in Abruzzo and Campania to 92% in Emilia-Romagna. Suppliers in lagging regions face rework and delayed acceptance payments.
EHDS certification adds cost for smaller vendors
Certification under the European Health Data Space adds fixed compliance costs that weigh hardest on small national software houses. Breaches of the regulation can draw fines of up to 20 million euros or 4% of annual worldwide turnover, law firm A&O Shearman notes, and its general provisions apply from March 26, 2027. Small vendors must fund conformity testing, logging and standard exports alongside national certification programs. Single-country practice software suppliers with thin margins are most exposed, and some may sell to larger groups rather than fund compliance alone.
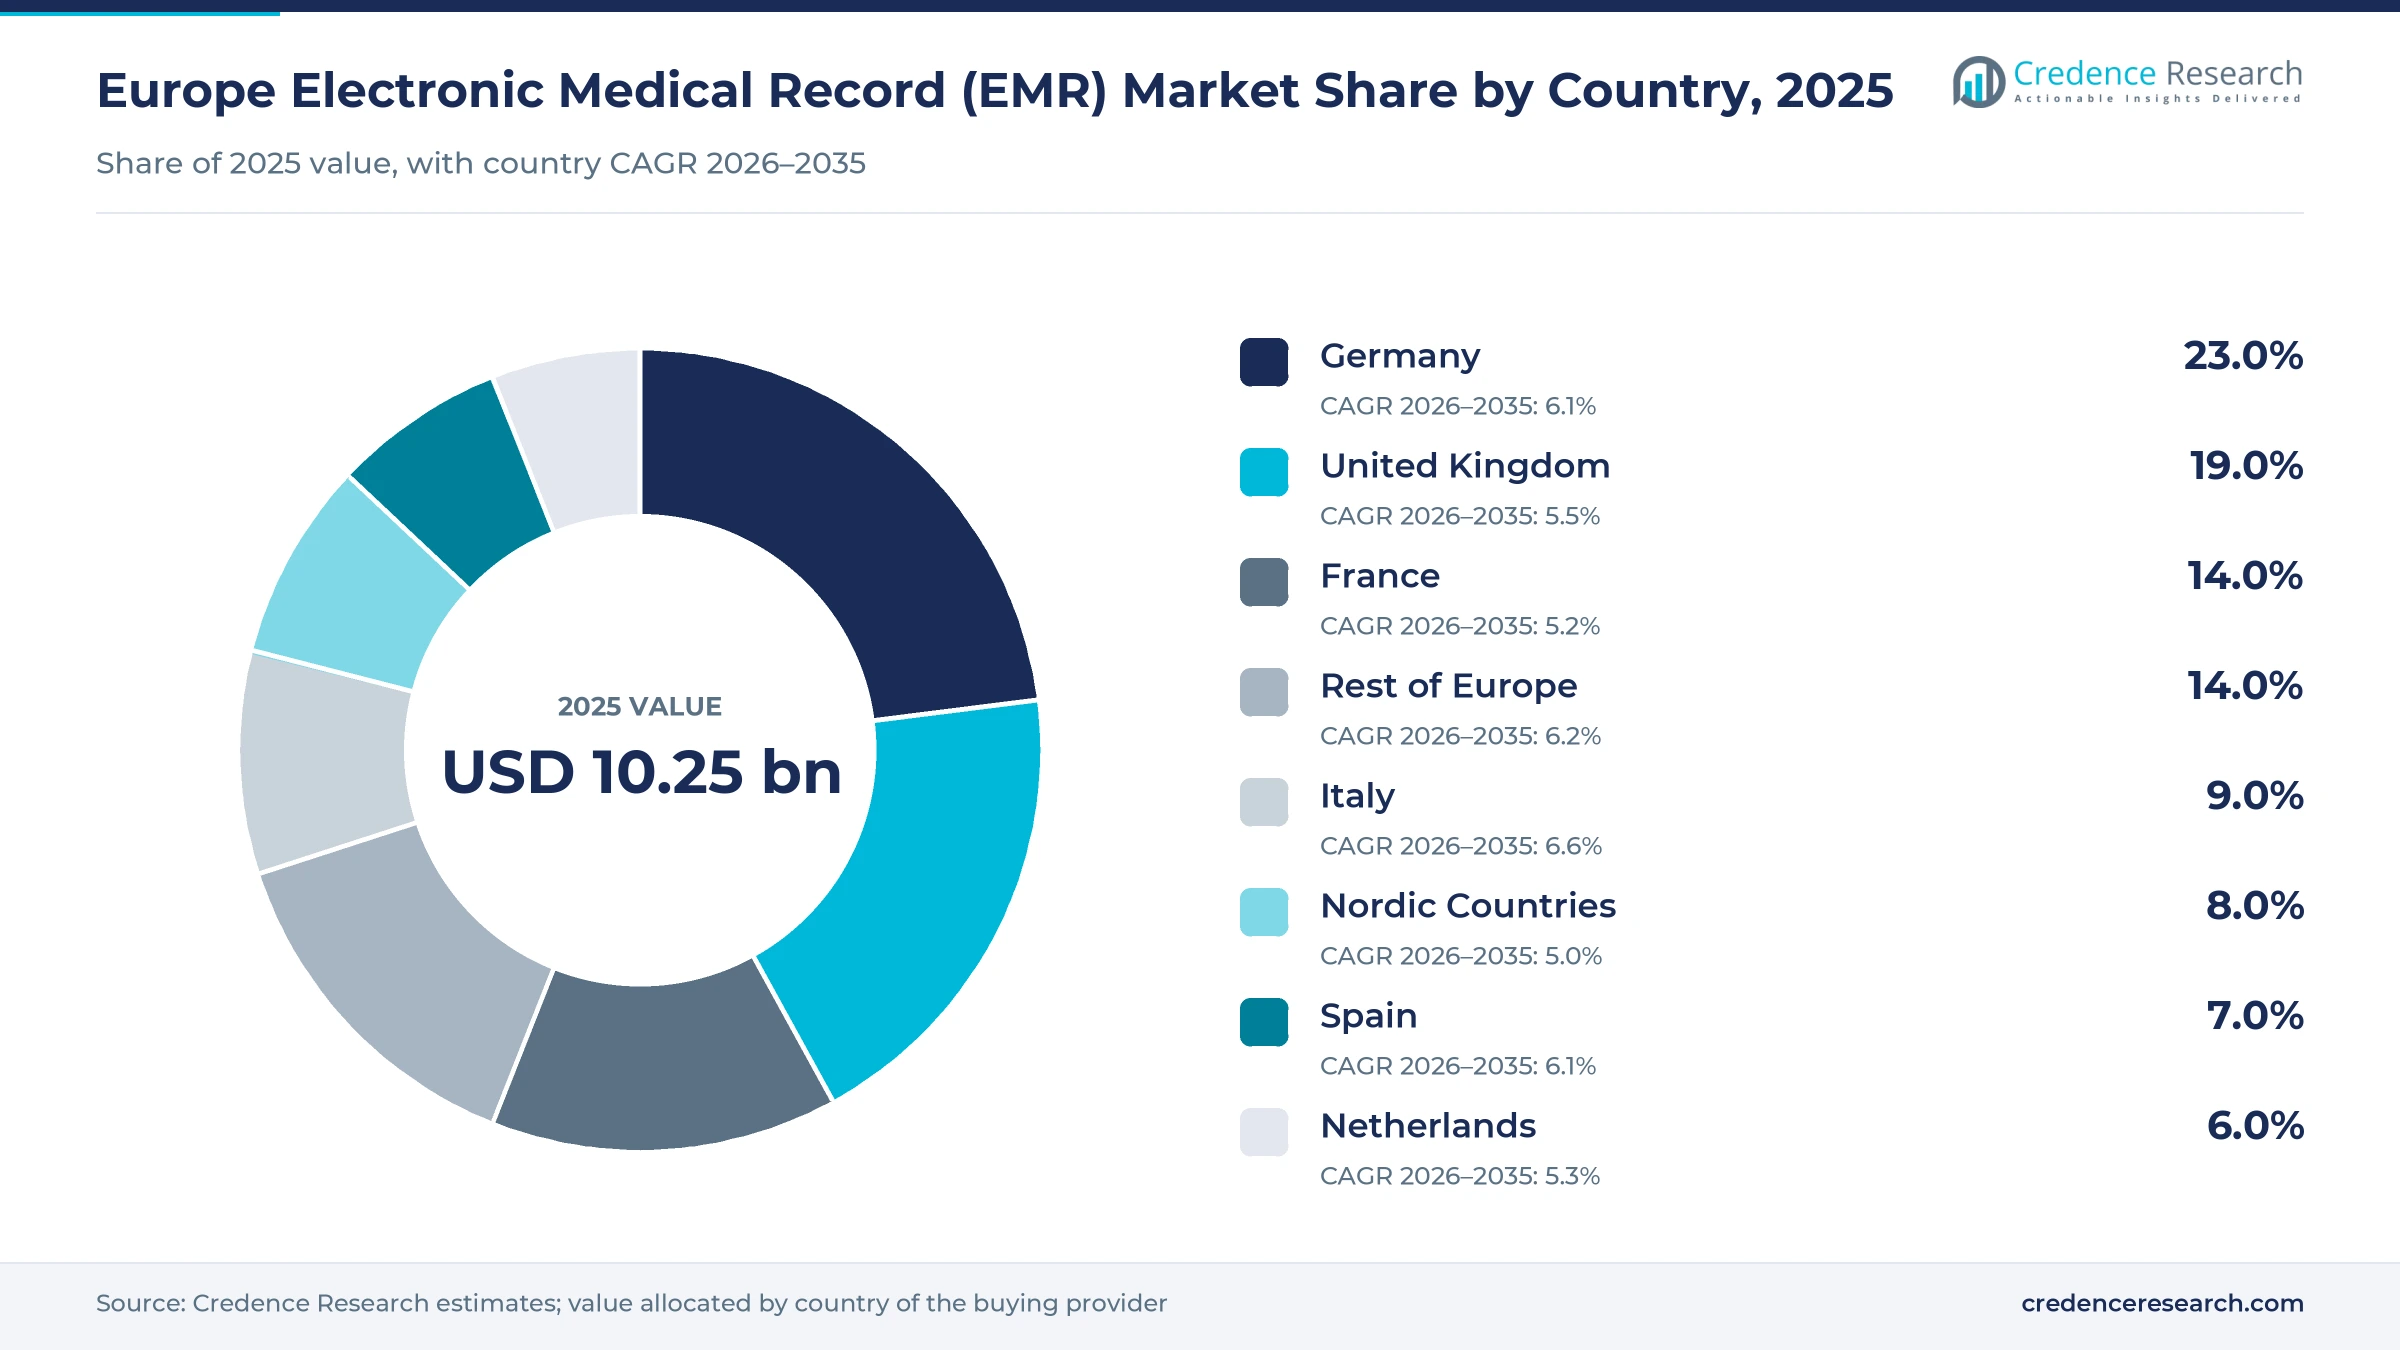
Germany leads while Italy grows fastest
| Country | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Germany | 2.36 | 23.0% | 6.1% |
| United Kingdom | 1.95 | 19.0% | 5.5% |
| France | 1.44 | 14.0% | 5.2% |
| Rest of Europe | 1.44 | 14.0% | 6.2% |
| Italy | 0.92 | 9.0% | 6.6% |
| Nordic Countries | 0.82 | 8.0% | 5.0% |
| Spain | 0.72 | 7.0% | 6.1% |
| Netherlands | 0.61 | 6.0% | 5.3% |
Germany leads on hospital penalties and the ePA
Germany held 23.0% of 2025 value and grows at 6.1% a year, the largest base in the region because hospital penalties and the national ePA push spending in both acute and office care. Active use by patients is still low but rising, as 23.6% of insured people used the ePA actively in April 2026, against 12.5% a year earlier, according to a survey commissioned by Pharma Deutschland. Germany scored 87% on the European Commission's 2024 record access index. Hospital replacements such as the Charité project keep tenders active for Epic, Dedalus and Nexus.
The United Kingdom moves from coverage to replacement
The United Kingdom held 19.0% of 2025 value and grows at 5.5% a year. With most trusts already on an EPR, spending shifts toward replacements, shared regional contracts and optimization, as the Somerset and Dorset award noted above shows. Primary care is opening as well, since NHS England validated the Medicus GP practice software in June 2025, and Doctolib bought Medicus in May 2026 to enter the British market, Siècle Digital reported. EMIS, which supplies more than half of English practices, and TPP now face a cloud entrant with a native NHS App link.
France pays vendors through the Ségur program
France held 14.0% of 2025 value and grows at 5.2% a year, slower than the regional average because much of its state-funded software refresh has already been paid. The Ségur digital health program carries 2 billion euros from the national recovery plan, and about a third of it funds two waves of software updates for health and social care professionals, according to the national digital health agency. France scored 84% on the same European record access index for 2024. Practices drop products that miss a Ségur wave, so certification now decides which vendors keep their installed base.
Italy grows fastest as regions race recovery deadlines
Italy is the fastest-growing country at 6.6% a year and held 9.0% of 2025 value. Public and private facilities faced a March 31, 2026, deadline to adopt the standard data transmission model, and the final recovery-plan reporting date is June 30, 2026, LaPresse reported. Regional health services that are still behind must finish document feeds and consent processes after those dates, so integration work continues to flow to suppliers. That growth rate is a Credence Research estimate, since no national series on record software spending is published.
Spain adds modules to regional records
Spain held 7.0% of 2025 value and grows at 6.1% a year, helped by regional health services that add modules to records they already run. Spain scored 88% on the European Commission's 2024 record access index, above the EU average, according to Euronews. Dedalus said in February 2026 that its ORBIS and Dedalus Care systems lead acute hospital records in the German-speaking countries and Southern Europe, mainly Spain. Galicia's AI tender and the Son Espases cloud move described above show that new spending goes to add-on tools and hosting rather than full replacement.
The Netherlands relies on three hospital suppliers
The Netherlands held 6.0% of 2025 value and grows at 5.3% a year. ChipSoft, Epic and Nexus supplied the record systems chosen by 97% of 75 Dutch hospitals, Consultancy.nl reported in February 2024. That concentration leaves few open tenders, so growth comes from upgrades and patient access work. The country scored only 65% on the European Commission's 2024 record access index, which points to portal and exchange projects rather than new hospital systems.
Nordic Countries favor modular upgrades
The Nordic Countries held 8.0% of 2025 value and grow at 5.0% a year, the slowest pace in the region because most hospitals and municipalities already run mature records. Tietoevry Care's Lifecare is used in 16 Finnish wellbeing services counties covering more than 3 million citizens, and North Karelia and South Savo chose it in October 2025 for deployment during 2025 to 2027. Central Norway runs Epic through its shared Helseplattformen record, and Denmark scored 98% on the 2024 access index. Regions that keep older systems running are now buying modular add-ons rather than single-platform replacements.
The rest of Europe adds Ireland and digital leaders
The rest of Europe held 14.0% of 2025 value and grows at 6.2% a year. Poland scored 92% on the European Commission's 2024 record access index, while Belgium and Estonia reached 100%, according to Euronews. Those high scores rest on national portals, so hospital and clinic software in these countries must keep feeding them. The Irish national tender described in the opportunities above is the largest open procurement in this group and could lift the regional pace once an award is made.
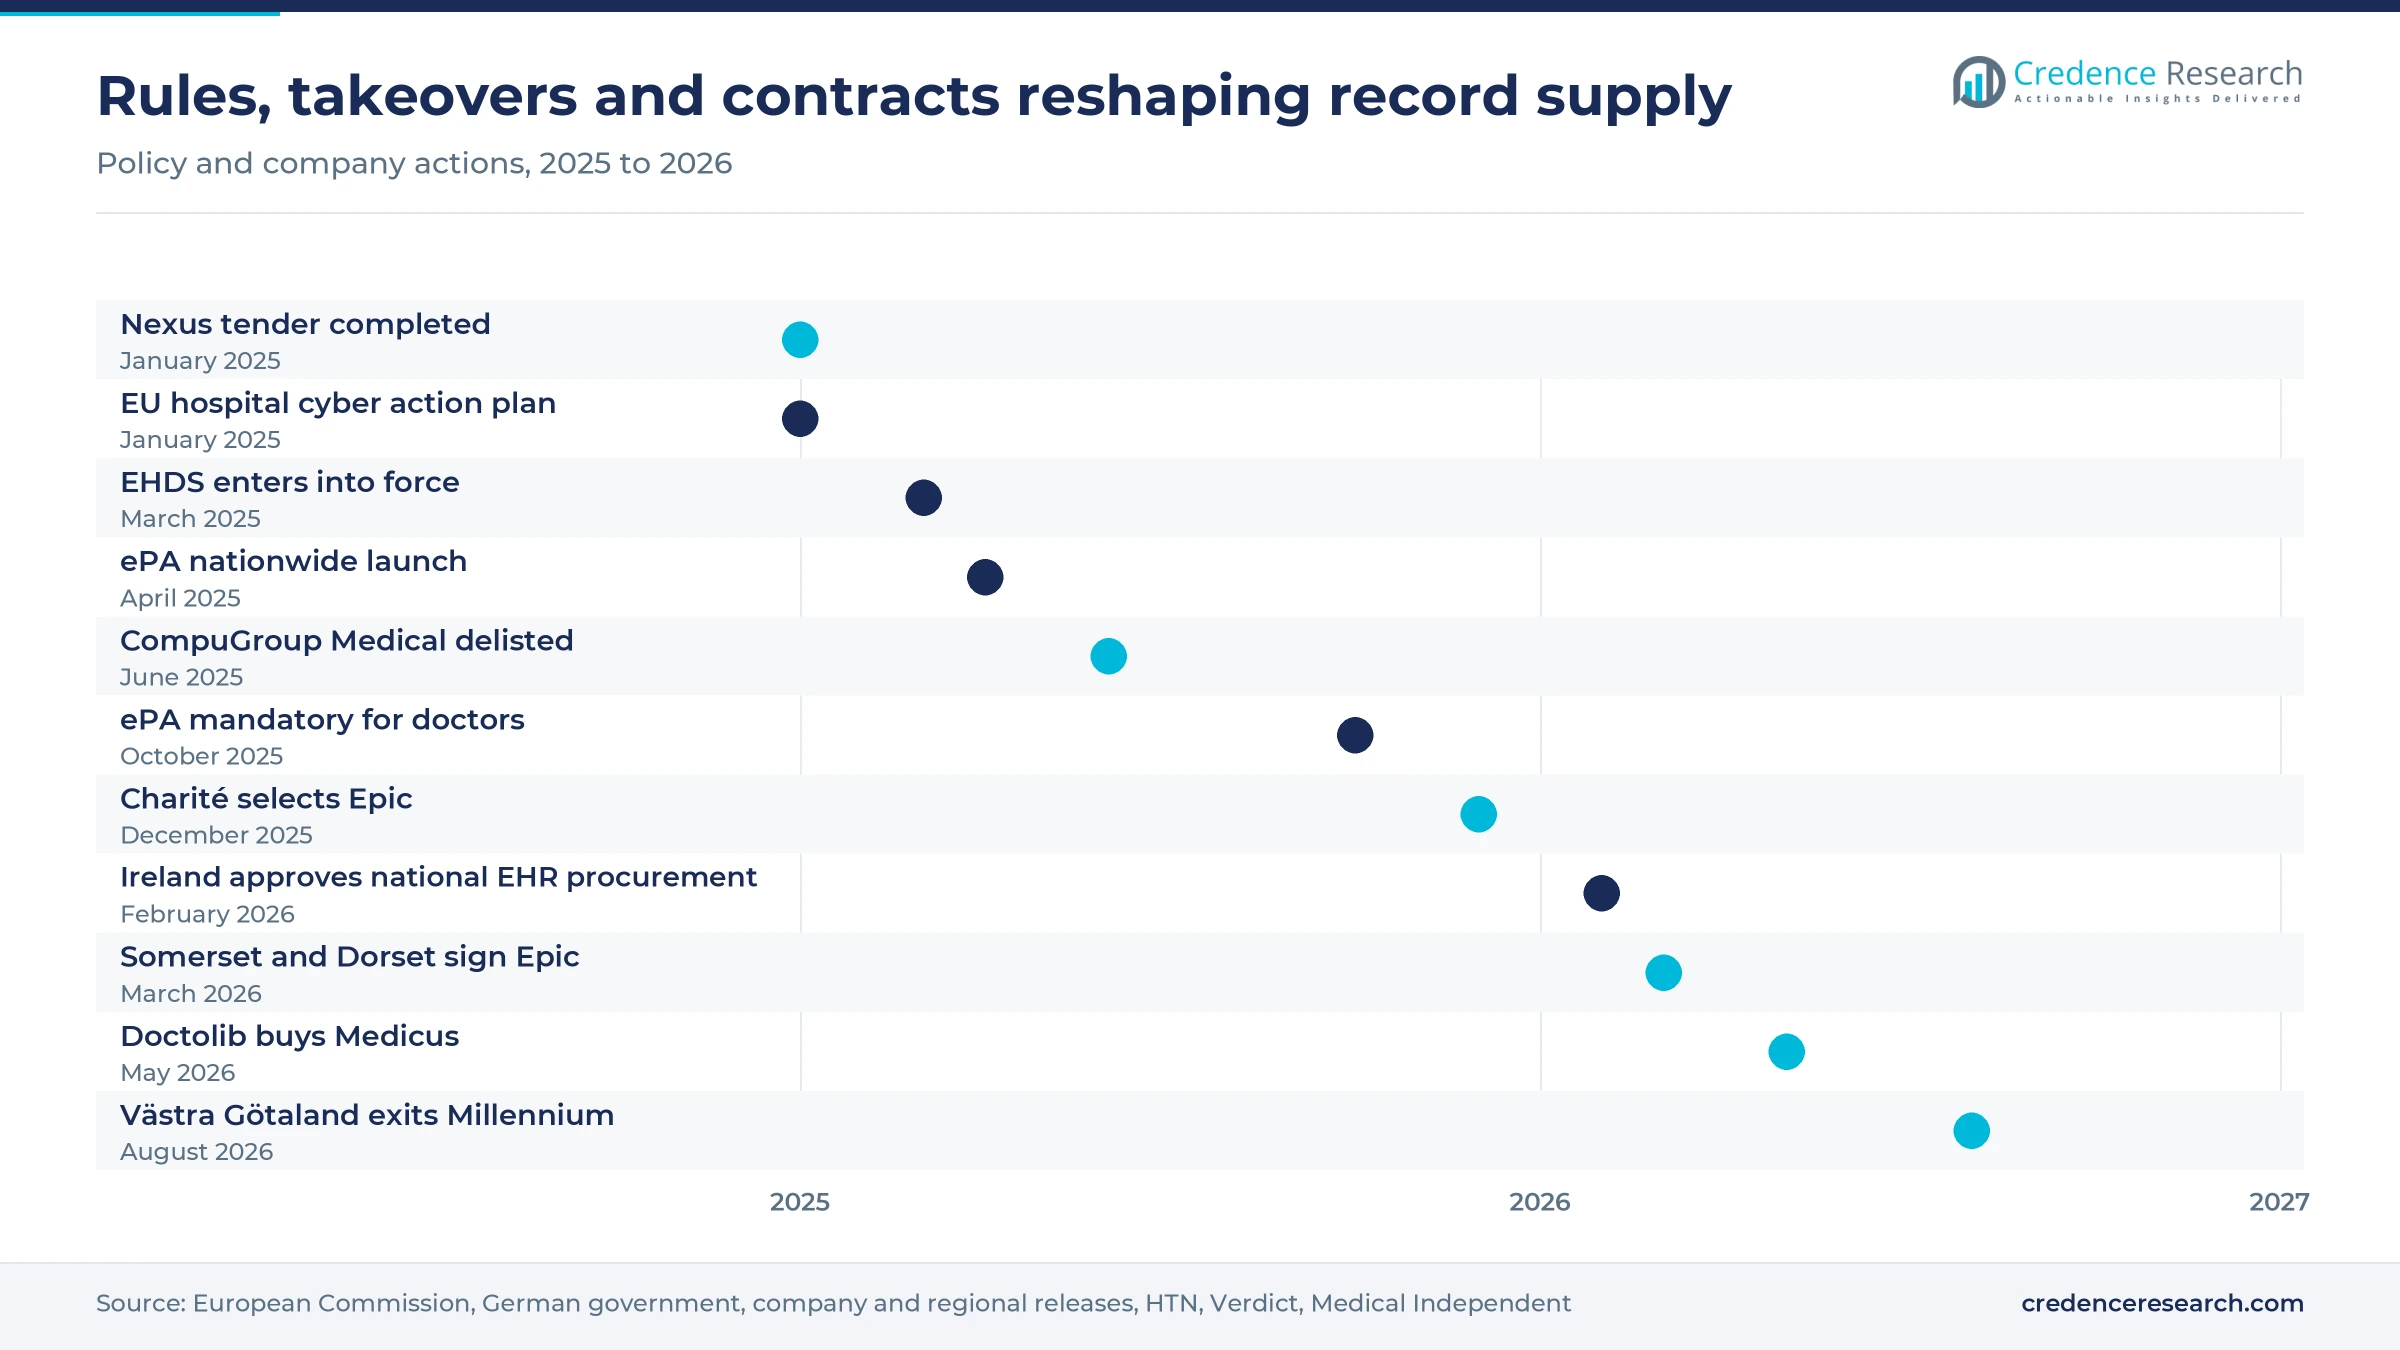
Tenders, takeovers and contract exits, 2025 to 2026
| Development | Status and market relevance |
|---|---|
| In January 2025, TA Associates completed its tender offer for Nexus AG, securing about 95% of the shares. | Completed tender; settlement depended on antitrust and investment clearances. |
| In June 2025, CVC concluded its delisting offer for CompuGroup Medical, ending its Frankfurt Prime Standard listing. | Completed delisting; the founding family keeps a majority. |
| In December 2025, Epic was selected to supply the electronic patient record for Charité Berlin. | Award subject to supervisory board approval; full rollout targeted by the end of 2029. |
| In March 2026, four Somerset and Dorset NHS trusts signed a shared Epic EHR contract. | Signed contract; the four trusts will share one record system. |
| In August 2026, Västra Götaland approved an agreement with Oracle to end its Millennium contract. | Signed termination; the region keeps older Oracle systems and plans a modular setup. |
Standard interfaces and cloud hosting cut upgrade costs
- Standard data interfaces based on HL7 FHIR and openEHR let hospitals export patient summaries and results without custom builds for each national connector.
- Cloud hosting moves servers, backups and upgrades to the vendor or a large cloud provider, which cuts on-site IT staff needs for smaller hospitals.
- Ambient speech documentation captures the consultation and drafts notes inside the record, which reduces typing time for clinicians in busy outpatient clinics.
- Patient app connectors push documents and medication lists to national apps such as the ePA and the NHS App, which keeps local records useful to patients.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Delivery records and certification decide contract awards
Competition in the Europe electronic medical record (EMR) market splits between enterprise hospital platforms and national practice software. Epic and Oracle Health compete for large university hospitals and shared regional contracts, where reference sites, implementation capacity and integrated modules decide awards. Dedalus, Nexus, ChipSoft and Tietoevry Care compete on local language, national certification and long installed bases in Germany, Spain, the Netherlands and Finland. In office care, CompuGroup Medical, Cegedim and Doctolib compete on monthly price, billing links and ease of use, while in England EMIS, owned by TPG since March 2026, and TPP's SystmOne serve most GP practices, a position that Doctolib's purchase of Medicus now challenges. InterSystems supplies record and data integration platforms to large hospital groups. Buyers judge suppliers on delivery record, total contract cost and readiness for EHDS certification, and a failed rollout now weighs heavily on any supplier's later bids.
How concentrated is EHR supply in Europe?
Supply is concentrated in hospitals and fragmented in office care. A handful of enterprise platforms, mainly Epic, Oracle Health, Dedalus, Nexus, ChipSoft and Tietoevry Care, hold most acute hospital contracts, and the Dutch case noted above shows how few suppliers can remain in one country. Practice software is split along national lines, because billing codes, insurer links and certification schemes such as Ségur or the German telematics infrastructure differ by country. Entry barriers are local reference sites, language and certification, so margins sit in maintenance and hosting contracts that run for a decade or more.
Suppliers European hospitals and practices shortlist
| Company | Type | Role in the market |
|---|---|---|
| Epic Systems Corporation | Enterprise EHR platform | Supplies hospital records to NHS trusts, Charité Berlin and Central Norway |
| Oracle Health (Oracle Corporation) | Enterprise EHR platform | Supplies Millennium and hosted records to NHS trusts and Spanish and Swedish hospitals |
| Dedalus | Hospital EHR specialist | Sells ORBIS and Dedalus Care acute records in DACH and Southern Europe |
| CompuGroup Medical | Practice and hospital software | Sells practice management and record software to physicians and hospitals |
| Nexus AG (TA Associates) | Hospital information systems | Sells clinical information systems to hospitals and clinics across nine European countries |
| ChipSoft | Hospital EHR specialist | Supplies the HiX hospital record used widely in Dutch hospitals |
| Tietoevry Care (Tieto) | Regional EHR supplier | Supplies Lifecare records to 16 Finnish wellbeing services counties |
| Doctolib (incl. Medicus) | Cloud practice software | Sells cloud practice software in France and GP software in Britain |
| Cegedim | Practice software supplier | Sells physician practice software in France, competing with Doctolib |
| InterSystems Corporation | Record and integration platform | Supplies record and data integration platforms used by hospital groups |
| EMIS (TPG) | GP practice software | Supplies EMIS Web GP records to more than half of English practices |
| TPP (The Phoenix Partnership) | Primary and community EHR | Supplies SystmOne records to GP practices and community services in England |
Delivery risk, not budget, decides the winners
Credence Research's view is that certification and delivery risk, not budget, will decide who wins European record contracts through 2035. Buyers have funds in Germany, England and Italy, but the Swedish contract exit described in the challenges shows how expensive a failed rollout becomes, and hospitals now ask for proof of local delivery before they sign. EHDS certification will thin out small practice software suppliers and move their customers toward larger groups and cloud entrants. Investors should expect more private equity ownership, more shared regional contracts in England and price pressure in office software as Doctolib widens its platform.
Estimates rest on public spending and contract data
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, and the country, product type, component, deployment and end-user splits are Credence Research estimates informed by public data. Sources include European Commission documents, national ministries and health agencies, regional health service releases, public contract notices, company disclosures and trade press. The 2025 value was built from health and IT spending data and supplier activity. Published country series on record software spending are thin, an evidence gap. No interviews or surveys were used to build these estimates.
Italy and cloud deployment carry growth to 2035
Credence Research expects the Europe electronic medical record (EMR) market to reach USD 18.01 billion by 2035, as EHDS deadlines in 2029 and 2031 keep hospitals and practices upgrading. Italy should keep the fastest pace while regions complete national health file work, and Germany remains the largest market on hospital penalties and the ePA. Cloud-based EMR grows at 7.4% a year during 2026–2035 as smaller hospitals give up local servers. The main risks are failed rollouts, cyberattacks and certification costs that push small vendors out of the market.
Certification pace and hospital budgets set the range
The range depends on whether member states and vendors meet the EHDS timetable for patient summaries and ePrescriptions, whether hospital budgets in Germany, the United Kingdom and Italy hold after recovery and transition funds end, and how quickly practices move to cloud software. Another large failed rollout or a delay in implementing acts would slow buying, while early certification and an Irish national award would lift it.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 4.2% | USD 15.70 billion | Implementing acts slip, hospital budgets tighten after recovery funds end and another big rollout fails |
| Base | 5.80% | USD 18.01 billion | EHDS exchange starts on the 2029 timetable and German penalties shift toward usage as planned |
| Upside | 7.1% | USD 20.11 billion | Early certification, an Irish national award and fast cloud moves by practices lift replacement demand |
Frequently Asked Questions
How big is the Europe electronic medical record (EMR) market?
Which country leads EHR and EMR spending in Europe?
How large is the U.K. EHR and EMR market?
What is driving EHR demand in Spain and Italy?
What does the European Health Data Space require?
Who are the largest EMR companies in Europe?
Which ambulatory EMR vendors lead in Europe?
What are the main challenges for EMR buyers and vendors?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Hospital EMR
- 1.2.2 Ambulatory EMR
- 1.3 By Component
- 1.3.1 EMR Software
- 1.3.2 EMR Services
- 1.4 By Deployment
- 1.4.1 Client Server Setup EMR
- 1.4.2 Hybrid Server Setup EMR
- 1.4.3 Cloud-Based EMR
- 1.5 By End User
- 1.5.1 Hospitals
- 1.5.2 Specialized Clinics
- 1.5.3 Ambulatory Surgical Centers
- 1.5.4 General Physician Clinics
- 1.5.5 Others
- 1.6 By Country
- 1.6.1 Germany
- 1.6.2 United Kingdom
- 1.6.3 France
- 1.6.4 Italy
- 1.6.5 Spain
- 1.6.6 Netherlands
- 1.6.7 Nordic Countries
- 1.6.8 Rest of Europe
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 10.25 billion → 2035: USD 18.01 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Electronic Medical Record (EMR) Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Electronic Medical Record (EMR) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Electronic Medical Record (EMR) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Electronic Medical Record (EMR) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Electronic Medical Record (EMR) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Electronic Medical Record (EMR) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Electronic Medical Record (EMR) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Electronic Medical Record (EMR) Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 10.25 billion → 2035: USD 18.01 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Electronic Medical Record (EMR) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospital EMR
- 12.3.7.2 Ambulatory EMR
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 EMR Software
- 12.4.7.2 EMR Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Client Server Setup EMR
- 12.5.7.2 Hybrid Server Setup EMR
- 12.5.7.3 Cloud-Based EMR
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End User - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Hospitals
- 12.6.7.2 Specialized Clinics
- 12.6.7.3 Ambulatory Surgical Centers
- 12.6.7.4 General Physician Clinics
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 By Country - Market Size and Forecast, 2025-2035
- 12.7.1 Segment Definition and Scope
- 12.7.2 Historical Market Size, 2018-2025
- 12.7.3 Revenue Forecast, 2025-2035
- 12.7.4 Volume Forecast, 2025-2035
- 12.7.5 Base-Year Market Share, 2025
- 12.7.6 Segment CAGR and Growth Drivers
- 12.7.7 Subsegment Market Size and Forecast
- 12.7.7.1 Germany
- 12.7.7.2 United Kingdom
- 12.7.7.3 France
- 12.7.7.4 Italy
- 12.7.7.5 Spain
- 12.7.7.6 Netherlands
- 12.7.7.7 Nordic Countries
- 12.7.7.8 Rest of Europe
- 12.7.8 Subsegment Pricing and Adoption Trends
- 12.7.9 Leading Suppliers and Competition
- 12.7.10 Regional Demand and Opportunities
- 12.8 Segment Growth Comparison
- 12.9 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Electronic Medical Record (EMR) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Electronic Medical Record (EMR) Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Country-Level Shares, 2025
- 14.2 Country Market Size Comparison, 2025
- 14.3 Country Market Forecasts, 2025-2035
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Electronic Medical Record (EMR) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Electronic Medical Record (EMR) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Epic Systems Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Oracle Health (Oracle Corporation)
- 18.4 Dedalus
- 18.5 CompuGroup Medical
- 18.6 Nexus AG (TA Associates)
- 18.7 ChipSoft
- 18.8 Tietoevry Care (Tieto)
- 18.9 Doctolib (incl. Medicus)
- 18.10 Cegedim
- 18.11 InterSystems Corporation
- 18.12 EMIS (TPG)
- 18.13 TPP (The Phoenix Partnership)
- 18.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

