
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dermatology & Eye Care Services Market Size 2024 | USD 83.31 Million |
| Dermatology & Eye Care Services Market, CAGR | 7.38% |
| Dermatology & Eye Care Services Market Size 2032 | USD 147.26 Million |
Market Overview
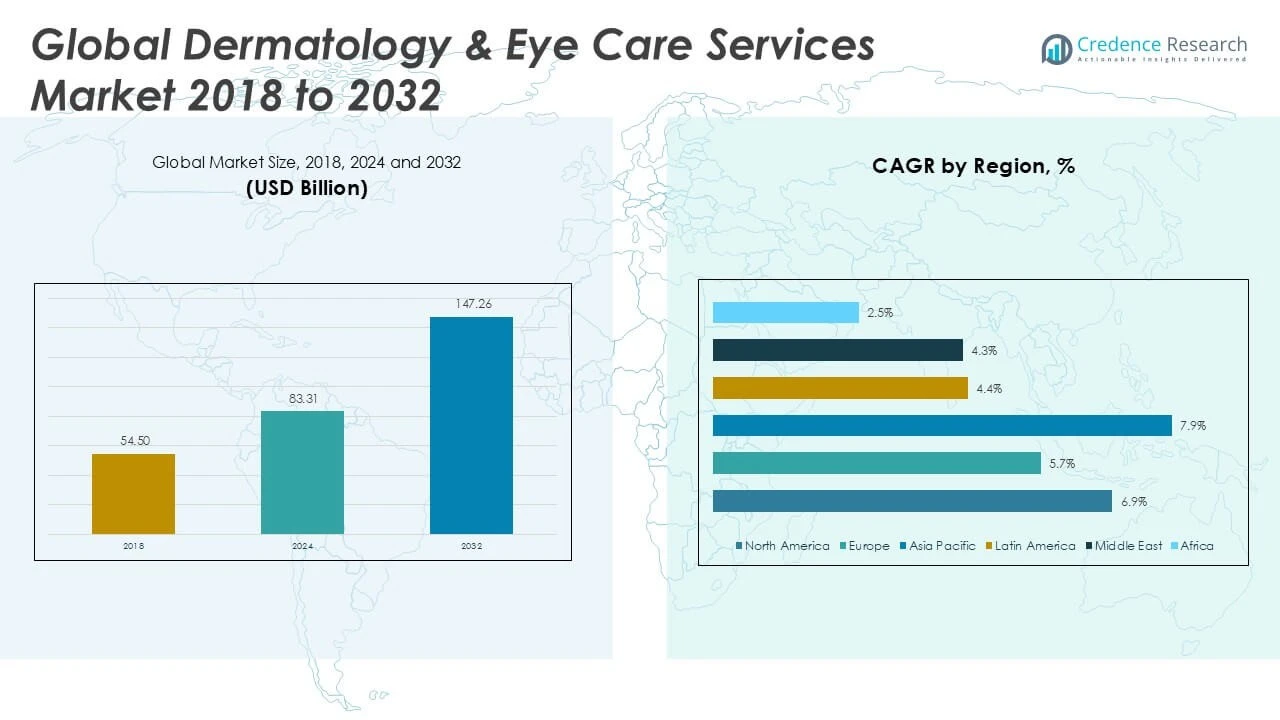
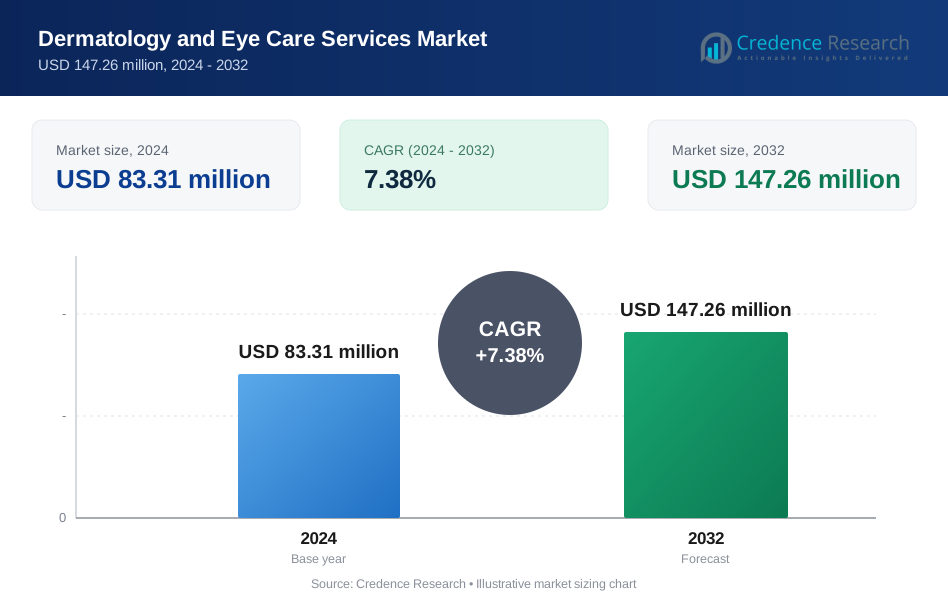
The Global Dermatology & Eye Care Services Market is projected to grow from USD 83.31 million in 2024 to an estimated USD 147.26 million by 2032, with a compound annual growth rate (CAGR) of 7.38% from 2025 to 2032.
Key drivers of this market include the escalating incidence of chronic skin disorders like acne, eczema, and psoriasis, as well as the growing prevalence of eye diseases such as cataracts, glaucoma, and diabetic retinopathy. Technological innovations, including the adoption of artificial intelligence (AI) for diagnostics and treatment planning, are revolutionizing care delivery. AI applications in dermatology, such as personalized skincare algorithms and mole mapping, are enhancing diagnostic accuracy and treatment outcomes . Similarly, in ophthalmology, deep learning models are improving the detection and management of ocular diseases .
Geographically, North America currently leads the market, owing to advanced healthcare infrastructure, high healthcare expenditure, and early adoption of digital health technologies. The Asia-Pacific region is anticipated to witness significant growth, driven by increasing healthcare awareness, rising disposable incomes, and expanding access to specialized care. Prominent players in the dermatology and eye care services market include Galderma, Novartis AG, Johnson & Johnson Services, Inc., Allergan, Topcon Corporation, and Bausch & Lomb Incorporated . These companies are at the forefront of developing innovative treatments and expanding service offerings to meet the evolving needs of patients globally.
Market Insights
- The Global Dermatology & Eye Care Services Market is projected to grow from USD 83.31 million in 2024 to USD 147.26 million by 2032, with a CAGR of 7.38%.
- Rising prevalence of chronic skin and eye conditions, along with advancements in medical technologies, drive market demand for specialized dermatology and ophthalmology services.
- AI applications in dermatology and ophthalmology, such as personalized skincare algorithms and deep learning models for eye disease detection, are enhancing diagnostic accuracy and treatment outcomes.
- An increasing elderly population worldwide is contributing to the demand for dermatology and eye care services, especially for age-related conditions like cataracts and skin cancer.
- Limited access to healthcare services in rural regions and the high cost of advanced treatments may hinder market growth, particularly in developing countries.
- North America leads the market due to its advanced healthcare infrastructure, while the Asia-Pacific region is expected to witness the fastest growth driven by rising healthcare awareness.
- Major players such as Galderma, Novartis AG, Johnson & Johnson Services, and Bausch & Lomb Incorporated are at the forefront of innovation and market expansion in dermatology and eye care services.
Market Drivers
Increasing Prevalence of Skin and Eye Disorders Driving Demand for Specialized Care
The rising incidence of chronic skin conditions such as acne, psoriasis, eczema, and skin cancer significantly fuels the demand for dermatology services worldwide. Similarly, the growing prevalence of eye diseases, including cataracts, glaucoma, diabetic retinopathy, and age-related macular degeneration, intensifies the need for specialized eye care. The Global Dermatology & Eye Care Services Market benefits from this increasing patient base, as more individuals seek early diagnosis and advanced treatments to manage these conditions effectively. Public health initiatives aimed at awareness and early detection also contribute to higher patient influx. It encourages healthcare providers to expand their dermatology and ophthalmology services. The increasing focus on preventive care supports sustained market growth.
- For instance, the prevalence of eczema affects nearly 1 in 10 Americans of all ages.
Technological Advancements Enhancing Diagnostic and Treatment Capabilities
Technological innovations in diagnostic tools and treatment methods considerably strengthen the Global Dermatology & Eye Care Services Market. The adoption of artificial intelligence and machine learning improves diagnostic accuracy and patient outcomes in both dermatology and ophthalmology. Digital imaging, teledermatology, and teleophthalmology platforms enhance access to expert care, especially in remote and underserved regions. Minimally invasive procedures and laser therapies provide effective treatment options with reduced recovery times. The integration of electronic health records facilitates better patient management and personalized treatment plans. These technological advancements motivate healthcare providers to invest in advanced equipment and training.
- For instance, teledermatology services have increased by over 300% during the COVID-19 pandemic, improving access to specialized care.
Growing Aging Population Expanding the Demand for Dermatology and Eye Care Services
The aging global population represents a critical driver for the Global Dermatology & Eye Care Services Market. Older adults face an increased risk of skin aging, wrinkles, and age-related eye disorders such as cataracts and glaucoma. It leads to higher demand for cosmetic dermatology services alongside therapeutic treatments. Age-related visual impairments further necessitate specialized eye care and surgical interventions. Healthcare systems respond by broadening service portfolios to cater to this demographic. The trend stimulates market expansion, as aging populations increase healthcare utilization. Chronic disease management also becomes a priority within this group, reinforcing demand.
Rising Awareness and Healthcare Infrastructure Development Promoting Market Growth
Increased awareness about skin and eye health, coupled with government initiatives, improves market penetration in emerging economies. The Global Dermatology & Eye Care Services Market benefits from expanded healthcare infrastructure and investments in specialty clinics and hospitals. Insurance coverage and reimbursement policies also encourage patients to seek professional care. Urbanization and rising disposable incomes contribute to higher healthcare spending, supporting market growth. Training programs for dermatologists and ophthalmologists enhance the availability of skilled professionals. These factors collectively create a favorable environment for sustained market expansion.
Market Trends
Rising Adoption of Teledermatology and Teleophthalmology Services Expanding Accessibility
The Global Dermatology & Eye Care Services Market experiences significant growth driven by the increasing adoption of telehealth solutions. Teledermatology and teleophthalmology platforms provide remote consultations, bridging gaps in access for patients in rural and underserved areas. It enables timely diagnosis and follow-up care, reducing the burden on traditional healthcare facilities. Advances in mobile technology and high-speed internet support these virtual services, improving patient convenience. Healthcare providers integrate telehealth to enhance service delivery and reach a broader patient base. Regulatory support for telemedicine further encourages market uptake. This trend reshapes care models and fosters continuous engagement between patients and specialists.
- For instance, sub-Saharan Africa had fewer than one dermatologist per million people in 2022, whereas the U.S. had 34 dermatologists per million, highlighting the critical role of teledermatology in improving access to care.
Integration of Artificial Intelligence and Machine Learning Enhancing Diagnostic Precision
Artificial intelligence (AI) and machine learning applications gain prominence in the Global Dermatology & Eye Care Services Market by improving diagnostic accuracy and treatment planning. AI-powered imaging tools assist in early detection of skin cancers, retinal diseases, and other disorders, enabling more precise interventions. It accelerates analysis of large datasets, facilitating personalized care tailored to patient-specific conditions. Providers increasingly incorporate AI-driven decision support systems to optimize clinical workflows and outcomes. Ongoing research expands AI capabilities across various subspecialties within dermatology and ophthalmology. This technological trend drives innovation and raises the standard of care.
- For instance, AI-based screening for diabetic retinopathy has demonstrated high classification performance, enabling early detection and intervention.
Expansion of Cosmetic Dermatology and Elective Eye Care Procedures Influencing Market Dynamics
Growth in cosmetic dermatology and elective eye care services impacts the Global Dermatology & Eye Care Services Market by attracting a broader demographic. Rising consumer interest in aesthetic procedures such as Botox, fillers, laser treatments, and refractive surgeries fuels market expansion. It reflects increasing awareness of appearance-related health and wellness among younger and middle-aged populations. Clinics and specialized centers diversify their offerings to include minimally invasive cosmetic solutions alongside therapeutic care. Marketing efforts and social media influence patient preferences and demand for these services. This trend drives revenue growth and shapes competitive strategies within the market.
Increasing Focus on Preventive Care and Early Intervention Boosting Service Demand
The Global Dermatology & Eye Care Services Market benefits from heightened emphasis on preventive care and early intervention to reduce disease burden. Screening programs for skin cancers and diabetic retinopathy improve early diagnosis rates, leading to better clinical outcomes. It encourages routine check-ups and patient education regarding lifestyle factors affecting skin and eye health. Healthcare providers promote awareness campaigns and integrate preventive services within primary care frameworks. Insurance coverage improvements support access to early treatment options. This trend fosters long-term patient engagement and sustains market demand for comprehensive care services.
Market Challenges
Limited Availability of Skilled Specialists and Impact on Service Delivery
The Global Dermatology & Eye Care Services Market faces challenges due to the shortage of trained dermatologists and ophthalmologists, particularly in rural and developing regions. It restricts timely access to quality care and increases patient wait times. The uneven distribution of specialists forces many patients to travel long distances for treatment, reducing overall healthcare efficiency. Training and retaining skilled professionals require significant investments and long-term commitment. This scarcity impacts the adoption of advanced treatments and limits market growth potential. Healthcare systems struggle to balance demand and supply effectively. Overcoming this challenge remains critical for expanding service reach and improving patient outcomes.
- For instance, the average wait time for a dermatology appointment in urban regions of the U.S. exceeds 30 days, highlighting the global challenge of specialist shortages and delayed access to care
High Treatment Costs and Limited Insurance Coverage Affecting Market Penetration
The Global Dermatology & Eye Care Services Market encounters barriers due to the high cost of advanced diagnostic procedures, treatments, and cosmetic services. It restricts affordability for large patient segments, particularly in low- and middle-income countries. Limited insurance coverage and reimbursement policies further constrain patient access to specialized care. The financial burden discourages timely consultation and follow-up visits, leading to disease progression and increased healthcare costs in the long term. Providers face difficulties in achieving broader market penetration under these constraints. Efforts to develop cost-effective solutions and expand insurance support are necessary to mitigate this challenge and sustain market growth.
Market Opportunities
Expansion of Telehealth and Digital Platforms Creating New Growth Channels
The Global Dermatology & Eye Care Services Market presents significant opportunities through the expansion of telehealth and digital care platforms. It enables providers to reach underserved populations and offer convenient, remote consultations. Increasing patient acceptance of virtual care supports sustained adoption and integration into standard practice. Telemedicine reduces operational costs and improves efficiency by facilitating follow-ups and chronic disease management. Emerging technologies such as mobile apps and AI-powered diagnostic tools enhance patient engagement and service personalization. Providers investing in digital infrastructure can capitalize on these trends to diversify revenue streams and expand market presence. The growing demand for accessible healthcare creates a favorable environment for innovation and service delivery transformation.
Growing Demand for Cosmetic and Preventive Care Services Driving Market Expansion
The Global Dermatology & Eye Care Services Market benefits from rising consumer interest in cosmetic treatments and preventive healthcare. Increasing awareness of aesthetic procedures, including laser therapies, injectables, and refractive surgeries, attracts a broad patient demographic. Preventive care programs focusing on early disease detection and lifestyle management further increase service utilization. It provides healthcare providers opportunities to develop specialized offerings tailored to patient preferences and emerging trends. Partnerships with wellness and beauty sectors can enhance market reach and brand differentiation. Expanding insurance coverage for preventive services supports patient access and compliance. These factors create multiple growth avenues for stakeholders aiming to capitalize on evolving consumer demands.
Market Segmentation Analysis
By Disease
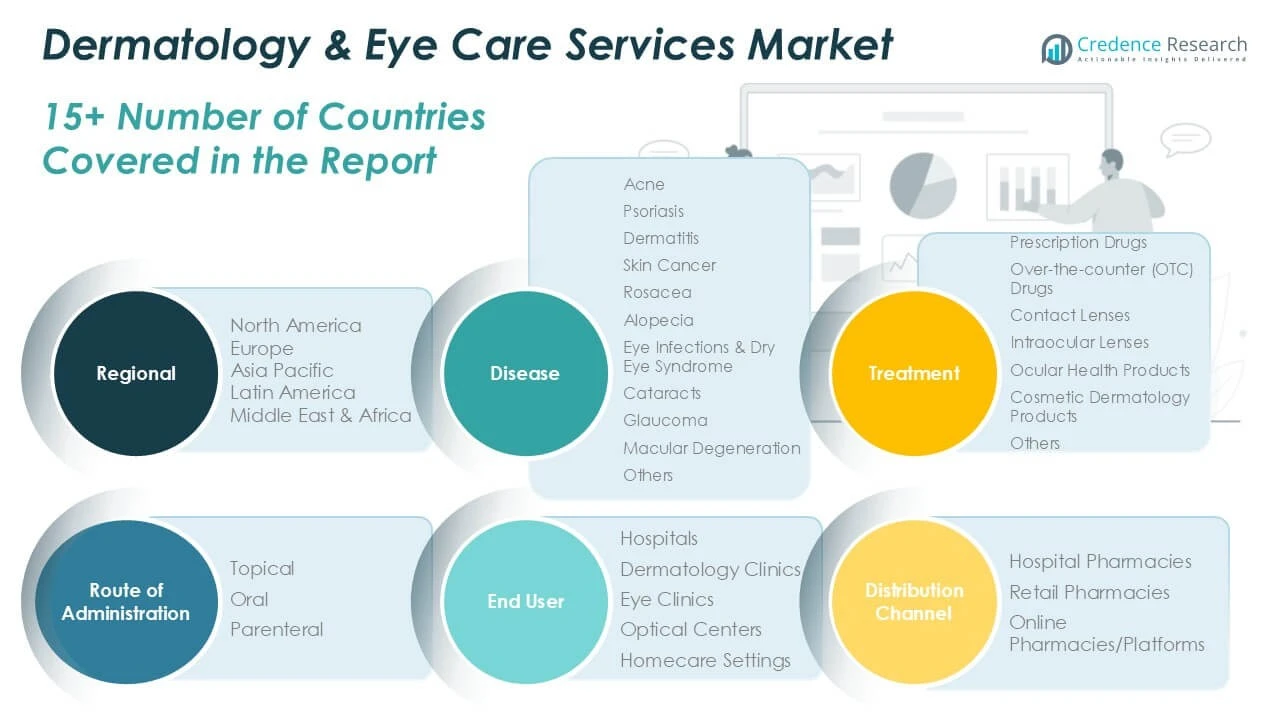
The disease segment includes prevalent conditions such as acne, psoriasis, dermatitis, skin cancer, rosacea, alopecia, eye infections, dry eye syndrome, cataracts, glaucoma, and macular degeneration. These disease categories drive targeted service demand, with chronic and age-related conditions accounting for significant revenue shares. Providers tailor interventions to meet the specific needs of each condition, influencing market dynamics.
- For instance, the prevalence of cataracts leads to approximately 28 million surgeries performed globally each year.
By Treatment
Treatment segmentation covers prescription drugs, over-the-counter (OTC) drugs, contact lenses, intraocular lenses, ocular health products, and cosmetic dermatology products. Prescription and OTC drugs hold substantial shares, supported by ongoing pharmaceutical innovations. The inclusion of advanced ocular devices and cosmetic products reflects evolving patient preferences for both therapeutic and aesthetic care, expanding the market scope.
- For instance, teledermatology services have increased by over 300% during the COVID-19 pandemic, improving access to specialized care.
By Route of administration
Route of administration divides services into topical, oral, and parenteral categories. Topical treatments dominate dermatology care, offering localized, non-invasive management, while oral and parenteral routes provide systemic therapy options for complex cases. This segmentation influences product development and delivery methods in the market.
By End User
End user analysis identifies hospitals, dermatology clinics, eye clinics, optical centers, and homecare settings as primary service delivery points. Hospitals and specialized clinics maintain the largest shares due to their comprehensive care capabilities. Homecare settings gain traction with increasing demand for remote and personalized services. Distribution channels include hospital pharmacies, retail pharmacies, and online pharmacies or platforms. The rise of digital pharmacy services supports broader access and convenience, enhancing overall market penetration and growth potential.
Segments
Based on Disease
- Acne
- Psoriasis
- Dermatitis
- Skin Cancer
- Rosacea
- Alopecia
- Eye Infections & Dry Eye Syndrome
- Cataracts
- Glaucoma
- Macular Degeneration
- Others
Based on Treatment
- Prescription Drugs
- Over-the-counter (OTC) Drugs
- Contact Lenses
- Intraocular Lenses
- Ocular Health Products
- Cosmetic Dermatology Products
- Others
Based on Route of Administration
- Topical
- Oral
- Parenteral
Based on End User
- Hospitals
- Dermatology Clinics
- Eye Clinics
- Optical Centers
- Homecare Settings
Based on Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies/Platforms
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Dermatology & Eye Care Services Market
The North America Dermatology & Eye Care Services Market held a market value of USD 34.31 million in 2024 and is expected to reach USD 60.82 million by 2032, registering a CAGR of 6.9%. It accounts for approximately 41% of the global market share in 2024, reflecting its dominant position. The region benefits from advanced healthcare infrastructure, high healthcare expenditure, and rapid adoption of innovative diagnostic and treatment technologies. Strong presence of key market players and increasing investments in R\&D fuel the market expansion. Growing prevalence of chronic skin and eye conditions among an aging population sustains service demand. Integration of telehealth services further enhances accessibility and patient engagement.
Europe Dermatology & Eye Care Services Market
Europe accounted for a market value of USD 15.60 million in 2024, projected to grow to USD 25.21 million by 2032, with a CAGR of 5.7%. It holds about 19% of the global market share in 2024. The region’s growth stems from well-established healthcare systems and increasing government initiatives promoting skin and eye health awareness. Investment in cutting-edge medical technologies and precision medicine strengthens diagnostic and therapeutic capabilities. Rising demand for cosmetic dermatology and preventive eye care supports market growth. Europe faces challenges with aging populations, but its strong regulatory framework ensures high-quality care standards. Expansion of telemedicine services improves patient reach across urban and rural areas.
Asia Pacific Dermatology & Eye Care Services Market
The Asia Pacific Dermatology & Eye Care Services Market recorded USD 27.79 million in 2024 and is anticipated to reach USD 53.19 million by 2032, growing at a CAGR of 7.9%. It represents roughly 33% of the global market share in 2024. This region benefits from increasing healthcare investments, expanding insurance coverage, and rising awareness of skin and eye diseases. Rapid urbanization and growing disposable incomes fuel demand for both therapeutic and cosmetic services. Expansion of healthcare infrastructure in countries like China, India, and Japan facilitates improved service availability. The increasing use of digital health platforms enhances access in remote and underserved areas. Market players focus on strategic partnerships and localized offerings to capture growth.
Latin America Dermatology & Eye Care Services Market
Latin America’s market value stood at USD 2.65 million in 2024, expected to grow to USD 3.90 million by 2032 with a CAGR of 4.4%. It accounts for approximately 3% of the global market share in 2024. Growth drivers include increasing awareness of dermatological and eye care conditions, supported by government health programs. Expanding healthcare infrastructure in key countries such as Brazil and Mexico aids service accessibility. The market faces challenges including uneven specialist distribution and limited insurance coverage. Rising demand for affordable and preventive care services creates growth opportunities. Adoption of telemedicine and online platforms is gradually increasing market penetration.
Middle East Dermatology & Eye Care Services Market
The Middle East Dermatology & Eye Care Services Market recorded a market value of USD 1.92 million in 2024, projected to reach USD 2.80 million by 2032, with a CAGR of 4.3%. It holds around 2% of the global market share in 2024. The region benefits from increasing healthcare investments, government initiatives for skin and eye health, and rising patient awareness. Growing medical tourism and demand for advanced cosmetic procedures further stimulate market growth. Challenges include disparities in healthcare access between urban and rural areas. Market players focus on expanding specialty clinics and leveraging digital health solutions to enhance care delivery.
Africa Dermatology & Eye Care Services Market
Africa’s Dermatology & Eye Care Services Market had a market value of USD 1.04 million in 2024 and is expected to reach USD 1.33 million by 2032, with a CAGR of 2.5%. It accounts for about 1% of the global market share in 2024. The region faces infrastructure limitations and a shortage of trained specialists, restricting widespread access to advanced care. Efforts to improve healthcare infrastructure and increase awareness of skin and eye diseases support gradual market expansion. Low healthcare spending and limited insurance coverage constrain growth. Emerging telemedicine initiatives offer potential to bridge care gaps. Focused investments and partnerships remain critical to unlocking market opportunities.
Key players
- Johnson & Johnson
- AbbVie Inc.
- Galderma
- Bausch Health Companies Inc.
- Alcon
- Pfizer Inc.
- Amgen Inc.
- EssilorLuxottica
- CooperVision
- Carl Zeiss Meditec AG
Competitive Analysis
The Global Dermatology & Eye Care Services Market features a highly competitive landscape dominated by several multinational corporations with diversified product portfolios and strong global presence. Key players such as Johnson & Johnson, AbbVie Inc., and Galderma leverage extensive R\&D capabilities to innovate and launch advanced therapeutic and cosmetic solutions. It faces intense competition based on product efficacy, technological advancement, and service accessibility. Strategic collaborations, mergers, and acquisitions enable companies to expand their market reach and enhance offerings. Companies focus on personalized care, integrating digital health platforms and telemedicine to meet evolving patient demands. Pricing strategies and regulatory compliance also influence competitive positioning. Continuous investment in emerging markets strengthens growth opportunities and maintains competitive advantage within the market.
Recent Developments
- In May 2025, Alcon received U.S. FDA approval for its new eye drop treatment, Tryptyr (acoltremon ophthalmic solution 0.003%), for dry eye disease. The treatment demonstrated effectiveness in late-stage trials by stimulating corneal sensory nerves to boost natural tear production. Alcon plans to launch Tryptyr in the U.S. in Q3 2025 and expand to other markets thereafter.
- In May 2025, EssilorLuxottica announced plans to acquire Optegra, an AI-focused ophthalmology platform, from MidEuropa. The acquisition includes over 70 eye hospitals and diagnostic centers across the UK, Czech Republic, Poland, Slovakia, and the Netherlands. The transaction is expected to close later in 2025, pending regulatory approval.
- In March 2025, Galderma achieved record net sales of \$4.41 billion for 2024, marking a 9.3% year-on-year increase. At the 2025 American Academy of Dermatology (AAD) Annual Meeting, Galderma presented updates on its dermatology portfolio, including products like Nemluvio, Sculptra, Restylane, and Relfydess.
- In February 2025, Amgen reported a 19% increase in total revenues to \$33.4 billion for 2024, driven by growth in products like TEPEZZA, a treatment for thyroid eye disease.
Market Concentration and Characteristics
The Global Dermatology & Eye Care Services Market exhibits moderate to high market concentration, with leading players like Johnson & Johnson, AbbVie Inc., and Galderma holding significant shares. It is characterized by a mix of large multinational corporations and specialized regional players offering a diverse range of products and services. Key characteristics include rapid innovation in diagnostic and therapeutic technologies, particularly in areas such as telemedicine, AI-driven diagnostics, and minimally invasive treatments. The market also benefits from increasing patient demand for cosmetic and preventive services. Companies focus on expanding service portfolios through partnerships, acquisitions, and investments in emerging markets. Regulatory compliance, technological advancements, and pricing strategies play a vital role in shaping competition. As healthcare providers adopt more personalized and accessible care models, the market will continue to evolve, driven by both innovation and increased consumer expectations.
Report Coverage
The research report offers an in-depth analysis based on Disease, Treatment, Route of Administration, End User, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Rising interest in aesthetic treatments, including Botox and laser therapies, will drive demand for dermatology services globally. Increased social media influence will further fuel consumer interest in cosmetic procedures.
- AI-powered diagnostics and telehealth platforms will expand access to care and improve patient outcomes, particularly in remote areas. These technologies will streamline treatment processes and enhance diagnostic accuracy.
- As the global population ages, there will be a growing need for both dermatology and ophthalmology services, especially in managing age-related conditions like cataracts and skin cancer. Older adults will drive market growth in the coming years.
- The focus on personalized medicine will lead to tailored treatment plans for dermatology and eye care. Precision medicine will enhance treatment outcomes, especially for complex skin and eye conditions.
- Companies will continue to invest in research and development to create new drugs, devices, and treatments. This will improve patient care and expand market offerings in both dermatology and eye care.
- Rising healthcare access and awareness in emerging markets, particularly in Asia-Pacific, will boost the demand for dermatology and eye care services. Growth in disposable income will drive patient spending on services and treatments.
- Telemedicine will play a significant role in managing chronic dermatological and eye conditions. Virtual consultations will become more common for ongoing treatment and management of diseases like psoriasis and glaucoma.
- Preventive dermatology and eye care services will gain traction, with more emphasis on early detection and health screenings. Programs aimed at preventing skin cancers and vision loss will become essential for long-term market growth.
- Governments worldwide will continue to provide regulatory support for new treatments, expediting approvals for breakthrough therapies. This will encourage innovation and new market entrants, particularly in dermatology and ophthalmology.
- The growth of online pharmacies and platforms will increase the accessibility of dermatology and eye care products. E-commerce will offer convenient, cost-effective solutions, benefiting both patients and healthcare providers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of Skin and Eye Disorders
The rising incidence of chronic skin conditions such as acne, psoriasis, and eczema, along with eye diseases like cataracts and glaucoma, is expanding the patient base seeking specialized dermatology and ophthalmology services. This trend is further supported by public health initiatives focused on early detection and awareness.
Technological Advancements in Diagnostics and Treatment
Innovations such as artificial intelligence for diagnostics, teledermatology, and teleophthalmology are improving diagnostic accuracy and expanding access to care, especially in remote and underserved regions. These technologies enable more efficient, personalized, and minimally invasive treatment options.
Aging Global Population
As the global population ages, there is a higher prevalence of age-related skin and eye conditions, including cataracts and skin cancer. This demographic shift is driving sustained demand for both therapeutic and cosmetic dermatology and eye care services.
Expansion of Telehealth and Digital Platforms
The adoption of telehealth solutions is making dermatology and eye care services more accessible, particularly for patients in rural or underserved areas. Telemedicine platforms facilitate remote consultations, follow-ups, and chronic disease management, broadening the reach of specialized care.
Growing Demand for Cosmetic and Preventive Care
Rising consumer interest in aesthetic procedures such as Botox, fillers, and refractive surgeries, along with increased emphasis on preventive screenings for skin cancers and eye diseases, is driving market expansion and encouraging providers to diversify their service offerings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global Dermatology & Eye Care Services Market in 2023?
What is the projected growth rate of the Global Dermatology & Eye Care Services Market?
Which factors are driving the growth of the Dermatology & Eye Care Services Market?
Which region leads the Global Dermatology & Eye Care Services Market?
Who are the key players in the Global Dermatology & Eye Care Services Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Disease
- 1.2.1 Acne
- 1.2.2 Psoriasis
- 1.2.3 Dermatitis
- 1.2.4 Skin Cancer
- 1.2.5 Cataracts
- 1.2.6 Glaucoma
- 1.3 By End User
- 1.3.1 Hospitals
- 1.3.2 Dermatology Clinics
- 1.3.3 Eye Clinics
- 1.3.4 Optical Centers
- 1.3.5 Homecare Settings
- 1.4 By Treatment
- 1.4.1 Prescription Drugs
- 1.4.2 Over-the-counter (OTC) Drugs
- 1.4.3 Contact Lenses
- 1.4.4 Intraocular Lenses
- 1.4.5 Cosmetic Dermatology Products
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 83.31 million → 2032: USD 147.26 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dermatology and Eye Care Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dermatology and Eye Care Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Dermatology and Eye Care Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Dermatology and Eye Care Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dermatology and Eye Care Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dermatology and Eye Care Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dermatology and Eye Care Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dermatology and Eye Care Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 83.31 million → 2032: USD 147.26 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dermatology and Eye Care Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Disease - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Acne
- 12.3.6.2 Psoriasis
- 12.3.6.3 Dermatitis
- 12.3.6.4 Skin Cancer
- 12.3.6.5 Cataracts
- 12.3.6.6 Glaucoma
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Hospitals
- 12.4.6.2 Dermatology Clinics
- 12.4.6.3 Eye Clinics
- 12.4.6.4 Optical Centers
- 12.4.6.5 Homecare Settings
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Treatment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Prescription Drugs
- 12.5.6.2 Over-the-counter (OTC) Drugs
- 12.5.6.3 Contact Lenses
- 12.5.6.4 Intraocular Lenses
- 12.5.6.5 Cosmetic Dermatology Products
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dermatology and Eye Care Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Dermatology and Eye Care Services Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Dermatology and Eye Care Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Dermatology and Eye Care Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Johnson & Johnson
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 AbbVie Inc.
- 18.4 Galderma
- 18.5 Bausch Health Companies Inc.
- 18.6 Alcon
- 18.7 Pfizer Inc.
- 18.8 Amgen Inc.
- 18.9 EssilorLuxottica
- 18.10 CooperVision
- 18.11 Carl Zeiss Meditec AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
