
Market Overview
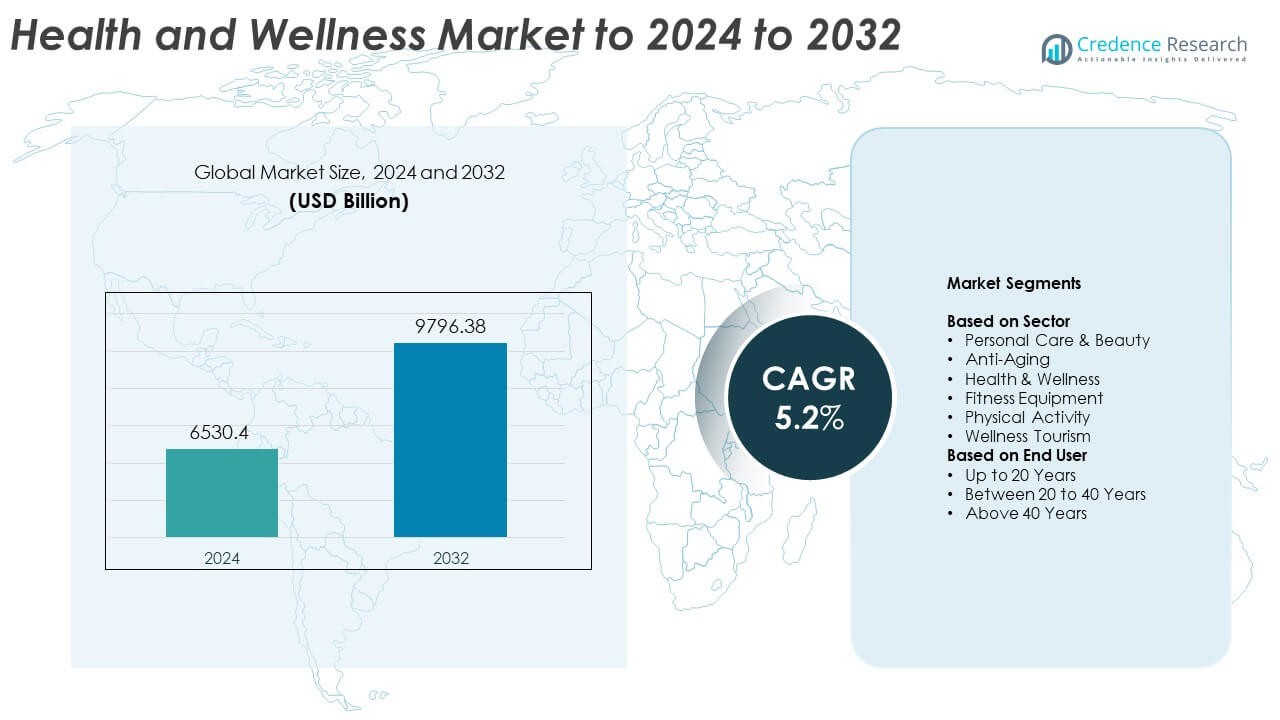
Health And Wellness Market size was valued at USD 6530.4 Billion in 2024 and is anticipated to reach USD 9796.38 Billion by 2032, at a CAGR of 5.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Health And Wellness Market Size 2024 | USD 6530.4 Billion |
| Health And Wellness Market, CAGR | 5.2% |
| Health And Wellness Market Size 2032 | USD 6530.4 Billion |
The health and wellness market is shaped by major players such as Procter & Gamble, Herbalife Nutrition Ltd., Unilever Plc, Fitness First, Nestlé SA, Vitabiotics Ltd., Bayer AG, L'Oréal SA, Amway Corp., Holland & Barrett Retail Limited, Danone, and David Lloyd Leisure Ltd. These companies strengthened their positions through wider product portfolios, strong retail distribution, and rising investment in digital wellness and clean-label solutions. North America led the global market with about 37% share due to high spending on preventive healthcare and personal wellness products. Europe followed with nearly 29% share, driven by strong demand for natural supplements, fitness services, and regulated health products.
Market Insights
- The health and wellness market reached USD 6530.4 Billion in 2024 and is projected to reach USD 9796.38 Billion by 2032, growing at a CAGR of 5.2%.
- Rising demand for preventive healthcare, clean-label nutrition, fitness services, and natural personal care products drives steady market expansion across age groups.
- Key trends include rapid adoption of digital wellness tools, growth of personalized nutrition, rising mental wellness spending, and increasing preference for sustainable and chemical-free products.
- Competition remains strong as global brands expand portfolios, enhance online distribution, and invest in research, ingredient transparency, and hybrid wellness experiences to strengthen market presence.
- North America held about 37% share, Europe accounted for nearly 29%, and Asia Pacific captured around 25%, while the leading segment by sector was personal care and beauty with about 32% share due to strong demand for clean and premium products.
Market Segmentation Analysis:
By Sector
Personal Care and Beauty led the sector in 2024 with about 32% share, driven by rising demand for clean-label skincare, premium cosmetics, and self-care routines across urban consumers. Anti-Aging products expanded as aging populations in Asia and Europe increased spending on collagen boosters and advanced dermatology solutions. Health and Wellness services gained traction due to higher focus on immunity, while Fitness Equipment and Physical Activity segments grew with home workouts and digital fitness programs. Wellness Tourism showed steady recovery as travelers sought holistic treatments, but Personal Care and Beauty stayed dominant due to continuous product innovation and mass-market reach.
- For instance, in 2023, Dove achieved its highest underlying sales growth in more than a decade, with turnover reaching €6 billion for Unilever.
By End User
Consumers between 20 to 40 years dominated the end-user segment in 2024 with nearly 46% share, supported by higher spending on gym memberships, organic skincare, supplements, and mental-wellness services. This age group adopted active lifestyles and purchased premium wellness products at faster rates than other groups. Users above 40 years also contributed strong demand for anti-aging and chronic-condition management solutions, while individuals up to 20 years showed rising interest in sports nutrition. The 20 to 40 years segment remained the largest due to strong digital engagement, higher disposable income, and strong adoption of preventive health practices.
- For instance, Planet Fitness reported about 18.7 million members and 2,575 gyms as of 31 December 2023.
Key Growth Drivers
Rising Focus on Preventive Healthcare
Consumers shifted toward preventive care as lifestyle-related disorders increased worldwide. People invested more in nutritional supplements, fitness plans, and wellness services to avoid long-term medical costs. Governments also promoted early diagnosis programs, which boosted demand for monitoring devices and digital health tools. Preventive habits strengthened market growth because buyers preferred sustainable routines over reactive treatments. This shift positioned preventive healthcare as the leading growth driver in the health and wellness market.
- For instance, Abbott stated that more than 6 million people in over 60 countries use its diabetes technology, including FreeStyle Libre systems.
Expansion of Digital and Connected Wellness Solutions
Digital platforms transformed how users track health goals, manage diets, and access remote fitness programs. Wearable devices, telehealth apps, and AI-driven wellness tools gained faster adoption across younger and middle-aged groups. Companies improved personalization features, which increased user engagement and subscription revenues. Hybrid wellness models that combine online and offline services expanded rapidly, making digital wellness a major driver of long-term market expansion.
- For instance, Peloton reported approximately 6.2 million total members and exactly 3.00 million paid connected fitness subscriptions as of December 31, 2023.
Growing Demand for Clean, Natural, and Functional Products
Consumers preferred natural formulations and chemical-free solutions in beauty, nutrition, and personal care. Clean-label supplements, organic skincare, and plant-based foods drew strong demand as shoppers prioritized safety and sustainability. Brands invested in transparent ingredient sourcing and eco-friendly packaging, which strengthened customer trust. Functional products that support immunity, stress reduction, and better sleep generated strong traction. This trend made the clean and functional product shift a key growth driver for the health and wellness market.
Key Trends and Opportunities
Rise of Holistic and Mental Wellness Adoption
Mental well-being emerged as a major focus as stress, sleep issues, and burnout increased across working populations. Consumers adopted meditation apps, mindfulness programs, and stress-management therapies, expanding the wellness ecosystem. Holistic routines that combine mental, physical, and emotional health gained strong acceptance. Companies offering integrated wellness programs found significant growth opportunities as buyers sought balanced and long-term lifestyle solutions.
- For instance, Headspace has been downloaded more than 100 million times globally and has users in over 190 countries and regions.
Growth of Personalized Wellness and Biohacking
Personalized nutrition, DNA-based diet plans, and biomarker-driven wellness gained traction as individuals aimed for tailored outcomes. Users relied on metabolic tests, smart wearables, and real-time health insights to optimize performance. Biohacking practices, such as intermittent fasting tools and micro-dosing supplements, became more mainstream. This shift created strong opportunities for brands offering customized products and data-driven coaching services in the health and wellness market.
- For instance, 23andMe was reported in 2024 to hold genotype and phenotype data for approximately 15 million individuals
Expansion of Wellness-Focused Travel and Experiences
Wellness tourism grew as travelers sought spa therapies, detox programs, and nature-based healing retreats. Demand increased across Asia, Europe, and the Middle East as consumers prioritized restorative journeys. Hotels upgraded wellness facilities, while specialized retreat operators expanded programs focused on mindfulness, fitness, and nutrition. This trend created new opportunities for destinations and businesses offering immersive wellness experiences.
Key Challenges
High Cost of Premium Wellness Products and Services
Premium supplements, organic foods, fitness equipment, and personalized wellness plans remain expensive for price-sensitive users. High costs limit adoption in developing economies where disposable incomes vary widely. The affordability gap restricts mass-market penetration, slowing the expansion of advanced wellness solutions. Companies must balance innovation with cost efficiency to reach broader consumer segments in the health and wellness market.
Regulatory Variations and Quality Control Issues
The wellness sector faces inconsistent regulations across supplements, personal care, digital health tools, and alternative therapies. Variations in labeling rules, testing standards, and ingredient compliance create barriers for global brands. Counterfeit or low-quality products in some regions further reduce consumer trust. Ensuring strict quality control and meeting changing regulatory expectations remain key challenges for companies operating in the health and wellness market.
Regional Analysis
North America
North America held the largest share of the health and wellness market in 2024 with about 37% share. The region benefited from strong spending on fitness services, preventive healthcare, organic nutrition, and digital wellness platforms. High awareness of lifestyle diseases pushed consumers toward supplements, gym memberships, and personalized coaching. The United States led demand due to a mature retail ecosystem and advanced telehealth adoption. Strong presence of global wellness brands and rising preference for clean-label products kept North America ahead in overall market contribution.
Europe
Europe accounted for nearly 29% of the market in 2024, supported by growing interest in functional foods, natural cosmetics, and regulated wellness services. The region saw strong demand for anti-aging solutions and preventive care as aging populations increased adoption. Countries like Germany, France, and the UK drove growth with structured fitness programs and sustainable product choices. Wellness tourism also expanded across Mediterranean destinations. Strong regulatory frameworks and consumer preference for high-quality health products kept Europe a major contributor to market revenue.
Asia Pacific
Asia Pacific captured about 25% share in 2024, driven by expanding middle-class populations and rising awareness of preventive health. Consumers invested more in supplements, home fitness tools, mental wellness apps, and natural personal care products. China, India, Japan, and South Korea showed strong growth due to urbanization and digital platform adoption. K-beauty, Ayurveda, and herbal nutrition gained traction, strengthening regional product diversity. Rapid economic growth, wider e-commerce access, and rising health consciousness positioned Asia Pacific as the fastest-growing region in the market.
Latin America
Latin America held nearly 6% share in 2024, supported by rising demand for fitness programs, natural cosmetics, and affordable wellness solutions. Brazil and Mexico led regional spending as consumers adopted preventive health practices and home exercise routines. Growth remained steady due to increasing focus on organic foods and regional beauty traditions. However, income variations limited adoption of premium services. Expanding retail channels, improved product availability, and rising digital fitness usage helped Latin America strengthen its presence in the market.
Middle East and Africa
Middle East and Africa accounted for around 3% share in 2024, with gradual growth driven by rising interest in wellness resorts, organic skincare, and fitness centers. Gulf countries led adoption as consumers invested more in luxury spa services, nutrition plans, and personalized training. Urbanization and growing health awareness supported moderate expansion across African nations. However, limited access to premium products and varying economic conditions slowed wider penetration. Investments in wellness tourism and expanding retail infrastructure continued to enhance regional market growth.
Market Segmentations:
By Sector
- Personal Care & Beauty
- Anti-Aging
- Health & Wellness
- Fitness Equipment
- Physical Activity
- Wellness Tourism
By End User
- Up to 20 Years
- Between 20 to 40 Years
- Above 40 Years
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the health and wellness market features leading companies such as Procter & Gamble, Herbalife Nutrition Ltd., Unilever Plc, Fitness First, Nestlé SA, Vitabiotics Ltd., Bayer AG, L'Oréal SA, Amway Corp., Holland & Barrett Retail Limited, Danone, and David Lloyd Leisure Ltd. The market remained highly dynamic as brands expanded product portfolios across nutrition, personal care, fitness services, and wellness solutions. Companies focused on clean-label formulations, digital engagement, and personalization to strengthen consumer loyalty. Strategic investments in research, advanced skincare science, dietary innovation, and hybrid fitness models helped players respond to shifting lifestyle needs. Many competitors upgraded online retail capabilities and partnered with wellness platforms to enhance global reach. Strong emphasis on sustainability, natural ingredients, and holistic well-being further shaped competition in both mature and emerging markets.
Key Player Analysis
- Procter & Gamble
- Herbalife Nutrition Ltd.
- Unilever Plc
- Fitness First
- Nestlé SA
- Vitabiotics Ltd.
- Bayer AG
- L'Oréal SA
- Amway Corp.
- Holland & Barrett Retail Limited
- Danone
- David Lloyd Leisure Ltd.
Recent Developments
- In 2025, Amway Corp. launched the Nutrilite™ Begin 30 Holistic Wellness Program , a 30-day guided wellness journey aimed at supporting gut health and adopting healthy habits.
- In 2025, David Lloyd Leisure Ltd. launched several new initiatives and club openings, including a new site with extensive facilities such as a 100+ station gym, heated pools, sports courts, and a luxurious adult-only Spa Retreat.
- In 2025, Holland & Barrett Retail Limited launched the Live Well Programme, a pioneering supply chain wellness initiative in Sri Lanka that educates workers on nutrition, hygiene, mental wellbeing, and disease prevention using a peer-led health champion model.
Report Coverage
The research report offers an in-depth analysis based on Sector, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily as consumers prioritize long-term preventive health solutions.
- Demand for personalized wellness plans will rise due to wider use of data-driven tools.
- Adoption of digital fitness platforms and remote coaching will expand across all age groups.
- Natural, clean-label, and sustainable products will gain stronger traction in beauty and nutrition.
- Mental wellness services will grow as stress and burnout issues increase in global populations.
- Wellness tourism will recover further and attract higher spending on immersive healing experiences.
- Hybrid fitness models combining online and offline formats will reshape consumer engagement.
- Functional foods and supplements will see rising acceptance for immunity, sleep, and gut health.
- Regulatory frameworks will strengthen to improve product quality and curb counterfeit items.
- Investments in AI-powered health monitoring devices will boost adoption of connected wellness ecosystems.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Focus on Preventive Healthcare
Consumers are increasingly investing in nutritional supplements, fitness plans, and wellness services to avoid long-term medical costs and manage lifestyle-related disorders. This shift toward prevention, supported by government initiatives and early diagnosis programs, is a primary growth engine for the health and wellness market.
Expansion of Digital and Connected Wellness Solutions
The adoption of wearable devices, telehealth apps, and AI-driven wellness tools is transforming how users track health, manage diets, and access fitness programs. Enhanced personalization and hybrid models combining online and offline services are driving user engagement and expanding the market.
Growing Demand for Clean, Natural, and Functional Products
Consumers are prioritizing natural formulations, chemical-free solutions, and clean-label products in beauty, nutrition, and personal care. This trend is driving brands to invest in transparent sourcing, eco-friendly packaging, and functional products that support immunity and stress reduction.
Rise of Holistic and Mental Wellness Adoption
Increasing stress, sleep issues, and burnout are fueling demand for meditation apps, mindfulness programs, and integrated wellness routines. Companies offering holistic solutions that address mental, physical, and emotional health are capturing new growth opportunities.
Growth of Personalized Wellness and Biohacking
Personalized nutrition, DNA-based diet plans, and biomarker-driven wellness are gaining traction as consumers seek tailored health outcomes. The mainstreaming of biohacking practices and data-driven coaching is opening new avenues for product and service innovation in the market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the health and wellness market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the health and wellness market projected to grow between 2025 and 2032?
Which health and wellness market segment held the largest share in 2024?
What are the primary factors fueling the growth of the health and wellness market?
Who are the leading companies in the health and wellness market?
Which region commanded the largest share of the health and wellness market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Sector
- 1.2.1 Personal Care & Beauty
- 1.2.2 Anti-Aging
- 1.2.3 Health & Wellness Services
- 1.2.4 Fitness Equipment
- 1.2.5 Physical Activity
- 1.2.6 Wellness Tourism
- 1.3 By End User
- 1.3.1 Up to 20 Years
- 1.3.2 Between 20 to 40 Years
- 1.3.3 Above 40 Years
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6530.4 Billion → 2032: USD 9796.38 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Health and Wellness Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Health and Wellness Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Health and Wellness Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Health and Wellness Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Health and Wellness Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Health and Wellness Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Health and Wellness Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Health and Wellness Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6530.4 Billion → 2032: USD 9796.38 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Health and Wellness Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Sector - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Personal Care & Beauty
- 12.3.7.2 Anti-Aging
- 12.3.7.3 Health & Wellness Services
- 12.3.7.4 Fitness Equipment
- 12.3.7.5 Physical Activity
- 12.3.7.6 Wellness Tourism
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Up to 20 Years
- 12.4.7.2 Between 20 to 40 Years
- 12.4.7.3 Above 40 Years
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Health and Wellness End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Health and Wellness Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Health and Wellness Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Health and Wellness Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Procter & Gamble
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Herbalife Nutrition Ltd.
- 18.4 Unilever Plc
- 18.5 Fitness First
- 18.6 Nestlé SA
- 18.7 Vitabiotics Ltd.
- 18.8 Bayer AG
- 18.9 L'Oréal SA
- 18.10 Amway Corp.
- 18.11 Holland & Barrett Retail Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

