
Market Overview
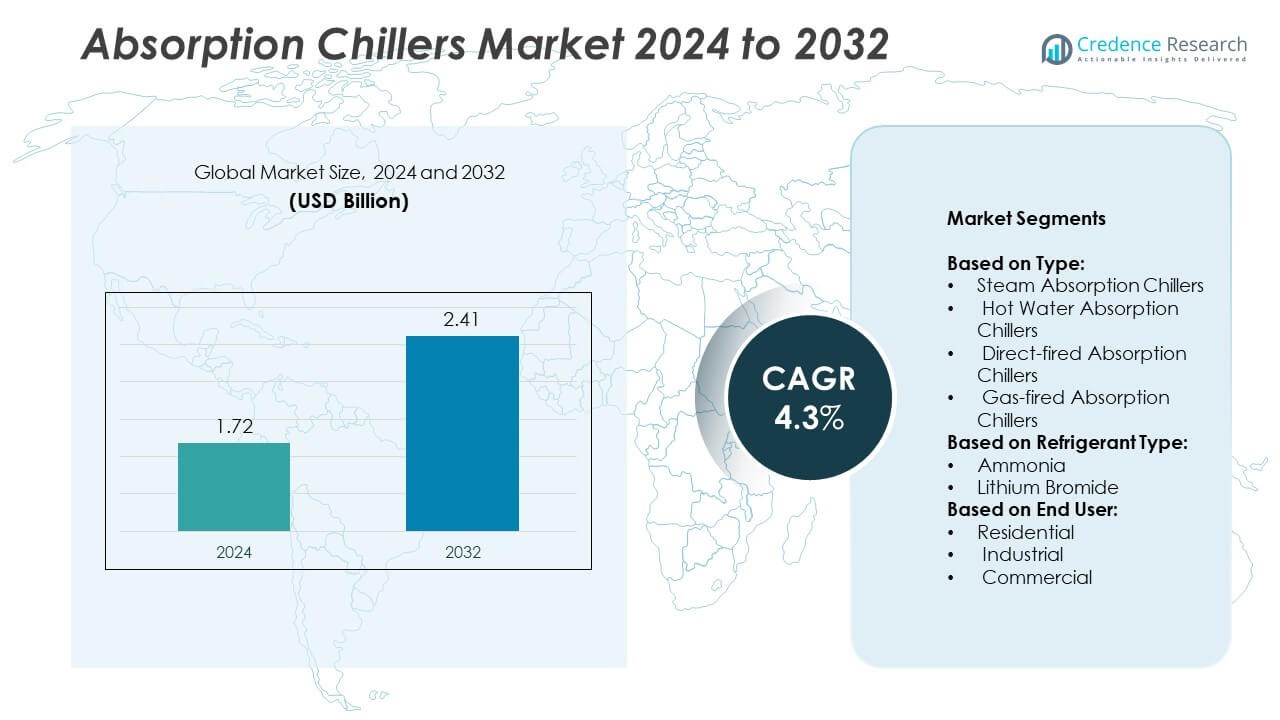
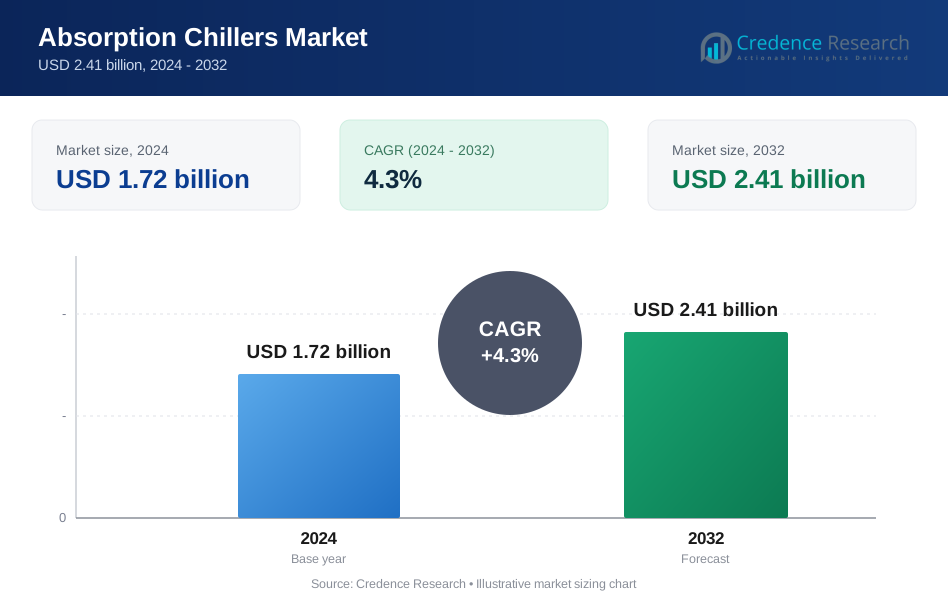
Absorption Chillers Market size was valued at USD 1.72 billion in 2024 and is projected to reach USD 2.41 billion by 2032, growing at a CAGR of 4.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Absorption Chillers Market Size 2024 | USD 1.72 Billion |
| Absorption Chillers Market, CAGR | 4.3% |
| Absorption Chillers Market Size 2032 | USD 2.41 Billion |
Broad Air Conditioning Ltd., Kirloskar Pneumatic Company Ltd., Carrier Corporation, Kawasaki Thermal Engineering Co., Ltd., Yazaki Corporation, EAW Energieanlagenbau GmbH, Johnson Controls, Robur Corporation, Shuangliang Eco-Energy Systems Co Ltd, Hyundai Climate Control Co., Ltd., Hitachi Ltd, Thermax Ltd, Trane Inc., and LG Electronics are the top players shaping the absorption chillers market. Asia-Pacific leads the market with over 35% share, driven by rapid industrialization, district cooling expansion, and strong manufacturing presence. North America follows with around 30% share, supported by combined heat and power installations and energy-efficiency initiatives. Europe holds over 25% share, benefitting from stringent energy regulations and retrofitting of commercial buildings. The Middle East & Africa and Latin America together contribute nearly 10%, fueled by district cooling projects and industrial adoption. These players focus on energy-efficient designs, product customization, and global service networks to strengthen their competitive positioning.
Market Insights
- The absorption chillers market was valued at USD 1.72 billion in 2024 and is projected to reach USD 2.41 billion by 2032, growing at a CAGR of 4.3%.
- Rising demand for energy-efficient cooling systems and waste-heat recovery solutions drives market growth across industrial and commercial sectors.
- Key trends include adoption of lithium bromide chillers for district cooling, integration with CHP plants, and development of low-emission gas-fired models.
- The market is moderately consolidated, with leading players focusing on product innovation, global expansion, and strong after-sales service networks to maintain competitiveness.
- Asia-Pacific leads with over 35% share, followed by North America at around 30% and Europe at more than 25%; steam absorption chillers hold over 40% share among types, driven by industrial applications and combined heat and power projects.
Market Segmentation Analysis:
By Type
Steam absorption chillers dominate the market with more than 40% share due to their ability to use waste steam from industrial processes and power plants efficiently. They are widely deployed in combined heat and power (CHP) plants, which reduces operating costs and boosts energy efficiency. Direct-fired absorption chillers are gaining adoption in regions with robust natural gas infrastructure, supporting cooling for large commercial spaces. Hot water absorption chillers remain essential for district cooling and renewable energy-based heating networks, while gas-fired units cater to high-capacity cooling applications requiring fuel flexibility.
- For instance, in a CHP‐integrated food processing facility in the US, two 415 kW reciprocating engine generators supply waste heat to an absorption chiller that delivers 160 tons of refrigeration at 25°F (≈ −4°C) using that low‐pressure steam heat.
By Refrigerant Type
Lithium bromide-based absorption chillers lead with over 70% market share, driven by their extensive use in HVAC systems for commercial and district cooling applications. Lithium bromide offers excellent thermodynamic stability, enabling consistent performance for large-capacity cooling loads. Ammonia-based absorption chillers continue to serve industrial refrigeration applications, especially in chemical, pharmaceutical, and food processing sectors, because of their efficiency and zero ozone depletion potential. Growing focus on sustainability and eco-friendly refrigerants ensures steady demand for both lithium bromide and ammonia systems across industries.
- For instance, the company AGO (“AGO Congelo” chillers) offers ammonia/water absorption chillers with cooling capacity averaging 100 kW to 1,500 kW for systems with supply thermal heat of ~90-160°C.
By End User
The industrial segment accounts for over 50% market share, fueled by rising process cooling requirements in petrochemical, chemical, and food manufacturing facilities. Industrial users adopt absorption chillers to recover waste heat and improve energy efficiency. The commercial segment is expanding with higher installations in hotels, shopping complexes, and office buildings, driven by green building initiatives and energy-saving regulations. The residential segment holds a smaller share but is growing in premium housing and district cooling projects where centralized, efficient cooling solutions are preferred.
Key Growth Drivers
Growing Demand for Energy-Efficient Cooling Solutions
Rising energy costs and strict efficiency regulations drive adoption of absorption chillers worldwide. These systems utilize waste heat or renewable energy sources, significantly lowering electricity consumption compared to mechanical chillers. Industrial sectors such as chemical, food processing, and petrochemical industries increasingly implement absorption chillers to improve energy utilization and meet sustainability goals. Government incentives for green buildings and carbon reduction initiatives further accelerate demand, making energy efficiency a major growth driver for the global market during the forecast period.
- For instance, in the Panasonic demonstration at H2 KIBOU FIELD in Japan, they lowered the minimum heat source temperature requirement of a fuel cell + absorption chiller system from 80°C to 70°C, enabling use of waste heat from hydrogen fuel cells in cooling.
Expansion of District Cooling Networks
Rapid urbanization and infrastructure growth fuel demand for centralized cooling systems, particularly in hot-climate regions. District cooling networks favor absorption chillers for their ability to operate using steam or hot water, improving overall system efficiency. Large-scale installations in commercial complexes, airports, and hospitals support higher adoption. The technology reduces peak electricity load, making it attractive for cities focusing on smart energy management. Growing investments in district cooling projects across Asia, the Middle East, and Europe are expected to significantly contribute to market growth in coming years.
- For instance, World Energy installed an absorption heat pump at Kumho Petrochemical in Korea. The system recovers latent heat from a solvent mixed gas at approximately 83°C, which is generated during synthetic rubber production. The heat pump produces 8 tons per hour of steam at a pressure of 1 bar G, with a saturation temperature of 120°C. A similar installation produced 8 tons per hour of steam from waste heat at the same site
Increasing Industrial Waste-Heat Recovery Projects
Industrial facilities are increasingly investing in waste-heat recovery solutions to optimize energy use. Absorption chillers offer a cost-effective way to convert surplus heat into useful cooling, improving overall plant efficiency. Sectors such as steel, cement, and power generation adopt these systems to cut operating costs and meet emission reduction targets. This trend aligns with global sustainability objectives and corporate ESG commitments. As industries move toward carbon-neutral operations, demand for absorption chillers utilizing waste-heat sources is set to grow significantly across multiple geographies.
Key Trends & Opportunities
Rising Adoption of Lithium Bromide-Based Chillers
Lithium bromide-based chillers dominate the market due to their reliability, thermodynamic stability, and suitability for large-capacity cooling. Their ability to deliver consistent performance in HVAC and district cooling applications makes them the preferred choice for commercial and industrial sectors. Growing awareness about low-GWP refrigerants and sustainability targets strengthens the shift toward lithium bromide systems. Manufacturers are investing in developing advanced designs with higher efficiency and longer life cycles, which will further boost demand and market penetration over the forecast period.
- For instance, the Trane Classic single‐stage LiBr absorption chillers operate with steam at up to 14 psig (≈0.97 bar above atmospheric) and steam temperatures up to 340°F (≈171°C), providing chilled water in the range 40-50°F (≈4-10°C).
Integration with IoT and Smart Building Systems
The trend toward digitalization is reshaping the absorption chillers market. Integration with IoT platforms and smart building management systems enables remote monitoring, predictive maintenance, and optimized energy use. Real-time data analytics help operators improve performance and reduce downtime. Smart controls are particularly valuable for large facilities and district cooling plants where system reliability is critical. This shift toward connected solutions opens new opportunities for manufacturers to offer value-added services, strengthening customer relationships and driving recurring revenue streams.
- For instance, the YORK YHAU-CW Double-effect Steam-Fired Absorption Chiller has a capacity range from 120 to 4,000 tons of refrigeration (≈ 422 to 14,067 kW).
Key Challenges
High Initial Investment and Installation Costs
One of the major challenges restraining market growth is the high upfront cost of absorption chillers and associated installation expenses. These systems require significant capital investment, including piping and integration with heat sources, which can be prohibitive for small and mid-sized facilities. Long payback periods also discourage adoption in cost-sensitive markets. To overcome this challenge, manufacturers and service providers are exploring financing models and performance-based contracts that spread costs over time, making the technology more accessible to a broader customer base.
Limited Awareness in Emerging Markets
In developing economies, lack of awareness about absorption chiller benefits and technical requirements poses a challenge. Many industries still rely on conventional electric chillers due to familiarity and lower initial investment. Limited availability of skilled technicians for installation and maintenance further slows adoption. Market players must invest in training programs, demonstration projects, and targeted marketing to educate potential customers. Growing focus on sustainability and rising energy costs are expected to gradually bridge this knowledge gap and create opportunities for wider deployment.
Regional Analysis
North America
North America holds over 30% share of the absorption chillers market, driven by strong adoption in industrial facilities and district cooling networks. The United States leads the region, supported by investments in energy-efficient HVAC systems and combined heat and power (CHP) plants. Demand is further supported by government incentives promoting sustainable cooling technologies and carbon reduction initiatives. Canada contributes steadily with rising deployment in commercial spaces, particularly in large office complexes and healthcare facilities. The market benefits from the availability of natural gas, which supports the use of direct-fired chillers in industrial and commercial applications.
Europe
Europe accounts for more than 25% of the global market, supported by stringent EU energy efficiency regulations and rising adoption of low-carbon technologies. Germany, France, and the U.K. are leading countries, driven by industrial waste heat recovery projects and district heating and cooling networks. The region favors lithium bromide absorption chillers for commercial and residential applications due to their environmental compatibility. Government initiatives and funding programs such as Horizon Europe encourage energy-efficient cooling solutions. Growth is also supported by retrofitting projects across aging infrastructure and increasing demand for sustainable HVAC systems in both commercial and public sector facilities.
Asia-Pacific
Asia-Pacific dominates with over 35% share, driven by rapid industrialization, urbanization, and growing investments in district cooling projects. China, India, and Japan are key contributors, with strong adoption in petrochemical, chemical, and food processing industries. Rising demand for energy-efficient solutions aligns with government policies focused on reducing carbon emissions and optimizing power consumption. The availability of cost-effective labor and equipment manufacturing supports large-scale chiller production, reducing system costs. Commercial sectors in Southeast Asia are also investing in absorption chillers for malls, hotels, and airports, further boosting regional growth.
Middle East & Africa
The Middle East & Africa region holds around 5% share, with growth driven by large-scale district cooling projects in the Gulf Cooperation Council (GCC) countries. The UAE, Saudi Arabia, and Qatar are major markets, using absorption chillers to meet cooling needs in high-temperature climates while utilizing waste heat from power plants and desalination facilities. Government initiatives for energy efficiency and green building standards accelerate adoption in commercial complexes and residential projects. Africa contributes through industrial and infrastructure development projects, particularly in South Africa, though overall adoption remains at a relatively early stage compared to other regions.
Latin America
Latin America captures nearly 5% share, supported by steady demand from industrial and commercial sectors. Brazil and Mexico lead the market, with installations in chemical processing, food and beverage production, and commercial buildings. Government efforts to modernize infrastructure and adopt sustainable cooling solutions drive adoption. The region also benefits from growing foreign investments in manufacturing plants, which create demand for waste heat recovery systems. Rising awareness of energy efficiency and operational cost savings encourages companies to shift from conventional electric chillers to absorption chillers, improving energy utilization across diverse applications.
Market Segmentations:
By Type:
- Steam Absorption Chillers
- Hot Water Absorption Chillers
- Direct-fired Absorption Chillers
- Gas-fired Absorption Chillers
By Refrigerant Type:
- Ammonia
- Lithium Bromide
By End User:
- Residential
- Industrial
- Commercial
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Broad Air Conditioning Ltd., Kirloskar Pneumatic Company Ltd., Carrier Corporation, Kawasaki Thermal Engineering Co., Ltd., Yazaki Corporation, EAW Energieanlagenbau GmbH, Johnson Controls, Robur Corporation, Shuangliang Eco-Energy Systems Co Ltd, Hyundai Climate Control Co., Ltd., Hitachi Ltd, Thermax Ltd, Trane Inc., and LG Electronics lead the global absorption chillers market. The market is shaped by continuous advancements in energy-efficient designs, waste-heat recovery integration, and large-capacity installations for industrial and commercial projects. Strong focus on sustainability drives demand for low-emission and eco-friendly systems, supporting adoption in district cooling and green building projects. Competitive strategies center on product innovation, global expansion, and robust after-sales service networks. Increasing investments in research and development, along with customized solutions for diverse end-user requirements, strengthen competitive positioning and enable players to capture emerging opportunities across manufacturing, infrastructure, and commercial sectors worldwide.
Key Player Analysis
- Broad Air Conditioning Ltd.
- Kirloskar Pneumatic Company Ltd.
- Carrier Corporation
- Kawasaki Thermal Engineering Co., Ltd.
- Yazaki Corporation
- EAW Energieanlagenbau GmbH
- Johnson Controls
- Robur Corporation
- Shuangliang Eco-Energy Systems Co Ltd
- Hyundai Climate Control Co., Ltd.
- Hitachi Ltd
- Thermax Ltd
- Trane Inc.
- LG Electronics
Recent Developments
- In 2025, Johnson Controls launched Silent-Aire Coolant Distribution Units for data centers.
- In 2025, Kirloskar Pneumatic is expanding its air conditioning and refrigeration segment, which includes vapor absorption chillers, with plans for capacity expansion and new product launches through 2026.
- In 2024, Broad Air Conditioning Ltd. launched a 2024 service-training webinar series for absorption chillers.
Report Coverage
The research report offers an in-depth analysis based on Type, Refrigerant Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily with rising adoption of energy-efficient cooling technologies.
- Demand will increase for chillers integrated with combined heat and power systems.
- Lithium bromide chillers will remain the preferred choice for large commercial applications.
- Gas-fired models will gain traction in regions with strong natural gas infrastructure.
- Industrial users will continue driving adoption through waste-heat recovery projects.
- District cooling projects in urban areas will support large-capacity chiller installations.
- Manufacturers will invest in R&D to enhance efficiency and reduce emissions.
- Digital monitoring and IoT-enabled controls will improve operational performance and maintenance.
- Asia-Pacific will remain the largest market due to rapid industrialization and infrastructure growth.
- Retrofit opportunities in Europe and North America will create steady replacement demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Absorption Chillers market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Absorption Chillers market projected to grow between 2025 and 2032?
Which Absorption Chillers market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Absorption Chillers market?
Who are the leading companies in the Absorption Chillers market?
Which region commanded the largest share of the Absorption Chillers market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Absorption Chillers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Absorption Chillers Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1.72 billion → 2032: USD 2.41 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Absorption Chillers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Absorption Chillers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Absorption Chillers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Absorption Chillers Market Drivers
- 3.3 Absorption Chillers Market Restraints & Challenges
- 3.4 Absorption Chillers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Absorption Chillers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Absorption Chillers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Absorption Chillers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Absorption Chillers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Absorption Chillers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Absorption Chillers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Absorption Chillers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Absorption Chillers Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Absorption Chillers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Absorption Chillers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Absorption Chillers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Absorption Chillers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Absorption Chillers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Absorption Chillers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Absorption Chillers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Absorption Chillers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Absorption Chillers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Absorption Chillers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Absorption Chillers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
