
Direct to Consumer Testing Market Overview:
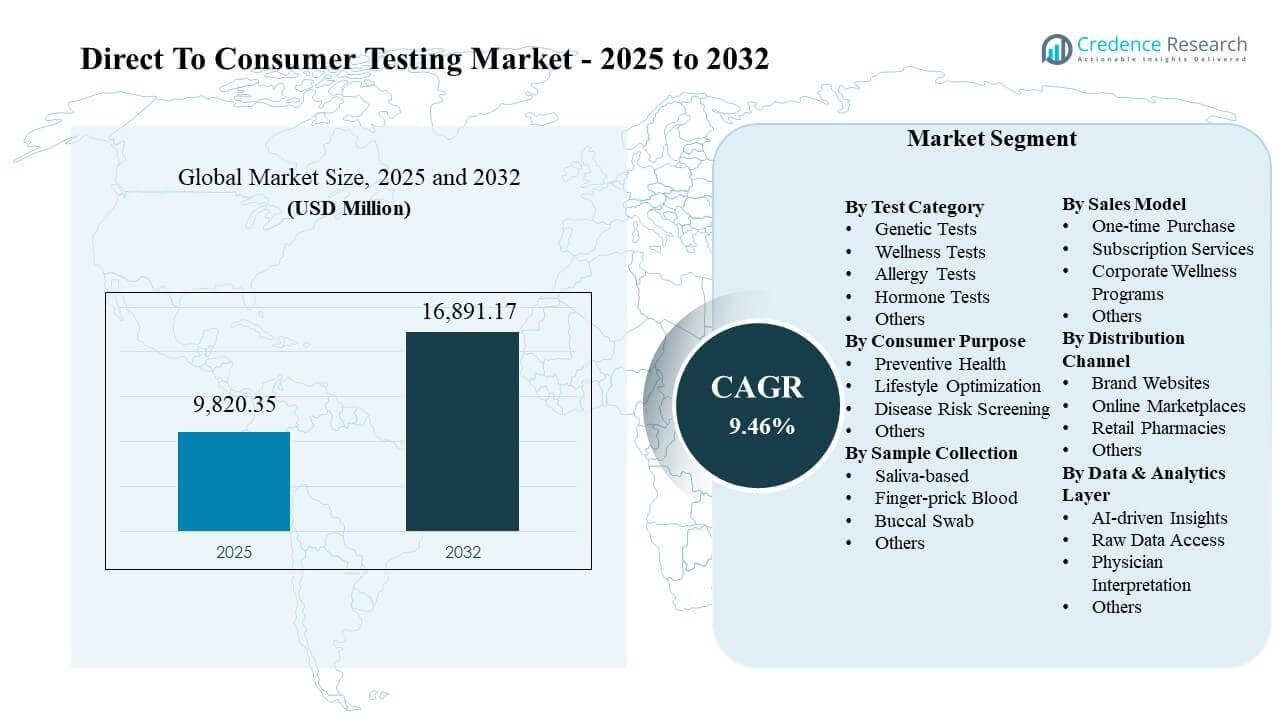
The Direct to Consumer Testing Market size was estimated at USD 9,820.35 million in 2025 and is expected to reach USD 16,891.17 million by 2032, growing at a CAGR of 9.46% from 2025 to 2032. Demand accelerates as consumers shift routine screening and wellness monitoring into at-home purchase and collection flows supported by digital results and follow-on guidance. Growth also benefits from expanding employer wellness adoption and broader availability of clinically validated panels across metabolic, hormone, and genetic use cases.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2021-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Direct-to-Consumer Testing Market Size 2025 | USD 9,820.35 million |
| Direct-to-Consumer Testing Market, CAGR | 9.46% |
| Direct-to-Consumer Testing Market Size 2032 | USD 16,891.17 million |
Key Market Trends & Insights
- The Direct to Consumer Testing Market is projected to grow from USD 9,820.35 million (2025) to USD 16,891.17 million (2032), reflecting a 9.46% CAGR (2025–2032).
- North America represented 47.60% of 2025 revenue, supported by high digital health engagement and strong DTC fulfillment infrastructure.
- Europe accounted for 22.70% share in 2025, reflecting broad consumer wellness adoption and established diagnostics capacity.
- Genetic Tests led By Test Category with a 39.75% share in 2025, reflecting strong consumer interest in risk screening and actionable insights.
- Brand Websites led By Distribution Channel with a 47.10% share in 2025, indicating the importance of direct education, onboarding, and result delivery.
Segment Analysis
The Direct to Consumer Testing Market continues to expand as consumers seek convenient access to screening, wellness, and risk assessment without clinic-first friction. Home-based sample collection and digital result delivery reduce time barriers and improve repeat testing behavior. Demand is reinforced by broader test menus that bundle biomarkers with interpretation layers, which increases perceived usefulness beyond a single report. Privacy expectations and data governance considerations increasingly shape provider positioning and buyer confidence.
Competition intensifies around test breadth, result turnaround time, clinical validation, and the ability to convert results into next-step actions. Providers differentiate through user experience design, sample logistics, and post-result pathways such as clinician review, coaching, and care navigation. Employer-linked programs also influence category growth by expanding access beyond out-of-pocket spending. These dynamics favor platforms that combine high-trust operations with scalable digital engagement.
By Test Category Insights
Genetic Tests accounted for the largest share of 39.75% in 2025. Genetic Tests lead because consumer demand remains anchored in disease risk screening, family-history discovery, and preventive planning use cases. Genetic Tests benefit from strong brand recognition and high perceived value tied to personalized insights. Genetic Tests also support ongoing engagement through updated reports, expanded trait libraries, and add-on health services.
By Consumer Purpose Insights
Preventive Health is a central driver for adoption because consumers increasingly pursue early signals and routine monitoring outside traditional care pathways. Lifestyle Optimization demand grows as platforms translate results into habit guidance, nutrition recommendations, and follow-up programs. Disease Risk Screening remains important for consumers with family-history concerns who want a clearer view of potential inherited risks. Purchase motivation also depends on trust, privacy assurances, and clarity of next steps after results.
By Sample Collection Insights
Finger-prick Blood accounted for the largest share of 45.20% in 2025. Finger-prick Blood leads because blood-based panels support a wide range of biomarkers linked to metabolic health, cardiovascular risk, micronutrients, and hormone monitoring. Finger-prick Blood collection also aligns with repeat testing behavior for consumers tracking progress over time. Finger-prick Blood formats benefit from improving kit usability, collection guidance, and logistics that protect sample integrity.
By Sales Model Insights
One-time Purchase remains a common entry point because first-time buyers often want a single panel to validate value before committing to repeat monitoring. Subscription Services gain traction when platforms bundle periodic testing with coaching, digital nudges, and longitudinal dashboards. Corporate Wellness Programs support adoption through employer-sponsored access and structured engagement workflows. Sales model performance depends on perceived outcomes, affordability, and frictionless reordering.
By Distribution Channel Insights
Brand Websites accounted for the largest share of 47.10% in 2025. Brand Websites lead because direct channels allow providers to control education, consent flows, kit selection, and pre-test expectations. Brand Websites also enable tighter integration between ordering, identity verification, and digital result delivery. Brand Websites support retention through reminders, cross-sell of additional panels, and seamless re-testing journeys.
By Data & Analytics Layer Insights
AI-driven Insights strengthen adoption as consumers expect clearer interpretation and personalized guidance rather than raw lab values alone. Raw Data Access remains relevant for advanced users who want portability across third-party tools and self-interpretation ecosystems. Physician Interpretation supports higher-trust positioning for sensitive results and can improve follow-through on recommended next steps. Data layer differentiation increasingly influences repeat usage and customer lifetime value.
Direct-to-Consumer Testing Market Drivers
Consumer shift toward self-directed preventive care
Direct to Consumer Testing Market growth is propelled by rising consumer willingness to manage health decisions outside clinic-first pathways. At-home ordering and collection reduce time costs and broaden access for consumers with limited appointment availability. Digital result delivery improves usability and shortens the feedback loop between symptoms, curiosity, and action. Broader test menus expand addressable demand across wellness, screening, and monitoring use cases. Improving user experience design increases completion rates and repeat usage.
Expansion of test menus and clinical-grade validation
Direct to Consumer Testing Market momentum benefits from wider availability of validated panels that address common concerns such as metabolic risk, hormones, and deficiencies. Clearer claims, better assay performance, and tighter operational quality reduce skepticism among new buyers. Product bundling and panel design simplify decision-making and raise average order value. Some providers add clinician review options that increase trust for higher-stakes results. These shifts make consumer testing feel closer to mainstream diagnostics.
Digital engagement and longitudinal insights
Direct to Consumer Testing Market demand increases when platforms provide actionable explanations and easy tracking over time. Longitudinal dashboards encourage periodic re-testing and improve retention beyond one-time purchases. Engagement tools such as reminders, goal setting, and education increase perceived utility between testing cycles. Interpretation layers help consumers connect results to diet, activity, and sleep behaviors. Better engagement improves conversion from curiosity-driven testing to routine monitoring.
- For instance, Levels uses continuous glucose monitoring data that can generate up to 288 glucose readings per day, enabling users to track metabolic responses over time and turning test output into ongoing behavioral guidance.
Employer wellness and channel expansion
Direct to Consumer Testing Market adoption is supported by employers seeking scalable ways to improve health engagement. Corporate wellness programs expand access beyond out-of-pocket spending and can normalize periodic screening behavior. Employers often value standardized reporting and population insights that support benefit strategy planning. Partnerships with pharmacies and digital health ecosystems strengthen distribution and improve convenience. These channels accelerate penetration across segments that may not self-purchase initially.
- For instance, Quest Diagnostics supports consumer and employer testing access through a U.S. network of more than 2,250 patient service centers, strengthening standardized collection and reporting while improving convenience across multiple access channels.
Direct-to-Consumer Testing Market Challenges
Direct to Consumer Testing Market development faces constraints from privacy expectations and regulatory scrutiny, especially for genetic and sensitive health data. Consumer trust can weaken when data governance appears unclear or when corporate changes raise concerns about data handling. Test interpretation risk persists when results are oversimplified or when follow-up pathways are not well integrated. Quality control across sample collection, shipping, and lab processing can affect reliability and satisfaction.
- For instance, 23andMe expanded its technology offering by making its Total Health service available to all customers with whole-exome sequencing, biannual lab testing, and 55+ key blood biomarkers, yet privacy concerns remained highly visible after regulators reported that a 2023 breach affected 6,984,430 customers worldwide.
Direct to Consumer Testing Market providers also face commercialization pressure from customer acquisition costs and competitive price comparison across similar panels. Consumer churn can rise when platforms fail to demonstrate clear outcomes beyond a single report. Reimbursement limitations in many settings keep demand more exposed to discretionary spending cycles. Operational scale adds complexity across logistics, customer support, and result turnaround expectations.
Direct-to-Consumer Testing Market Trends and Opportunities
Direct to Consumer Testing Market opportunity expands as providers embed interpretation, coaching, and care navigation into the post-result experience. Integration with telehealth pathways can increase confidence and improve conversion to recommended follow-ups. Personalized recommendations and automated nudges strengthen engagement and can raise repeat testing rates. Broader partnerships with digital health platforms create new funnels and reduce dependence on paid acquisition.
Direct to Consumer Testing Market innovation also accelerates through expansion into new biomarkers and condition-focused panels that align with high-interest wellness categories. Providers increasingly refine segmentation to target specific needs such as metabolic health optimization and hormone-related concerns. Employer adoption opens opportunities for standardized programs with measurable engagement targets. Improving kit usability and sample integrity can expand addressable groups that were previously hesitant about home collection.
- For instance, LetsGetChecked states that it can measure more than 100 bioindicators at home, fulfilled one client request for 30,000 kits within 2 weeks, returns home-screening results in about 2-5 business days after lab receipt, and has conducted over 9,000 onsite screening events reaching more than 1 million people across the U.S.
Regional Insights
North America
Direct to Consumer Testing Market activity in North America benefits from mature e-commerce behaviors, established at-home fulfillment, and a large base of consumers comfortable with digital health services. Strong brand-led education and a wide menu of panels support repeat ordering. Employer-sponsored offerings also scale quickly due to established benefits ecosystems. North America reached 47.60% share in 2025, reflecting the region’s leadership in commercialization and consumer adoption.
Europe
Direct to Consumer Testing Market growth in Europe is supported by strong consumer wellness awareness and a large diagnostics footprint in key countries. Buyers often evaluate privacy, transparency, and clinical credibility closely, which pushes providers to refine consent and reporting experiences. Cross-border complexity encourages localized operational models and partnerships. Europe accounted for 22.70% share in 2025, indicating significant scale alongside structured governance expectations.
Asia Pacific
Direct to Consumer Testing Market expansion in Asia Pacific is driven by rising middle-class health spending, rapid digital adoption, and growing interest in preventive monitoring. Large populations and expanding private diagnostics capacity support long-term upside. Country diversity creates uneven adoption, but leading markets can scale quickly with strong mobile-first engagement. Asia Pacific represented 20.85% share in 2025, reflecting growing contribution and strong expansion potential.
Latin America
Direct to Consumer Testing Market adoption in Latin America grows as online marketplaces expand reach and consumers seek more convenient access to testing. Private-pay diagnostics and wellness spending provide a foundation for DTC models in urban centers. Logistics reliability and affordability remain important constraints that shape category penetration. Latin America held a 4.95% share in 2025, indicating an emerging but improving regional contribution.
Middle East & Africa
Direct to Consumer Testing Market growth in the Middle East & Africa is supported by private healthcare expansion and increasing digital health initiatives in select markets. Consumer adoption tends to cluster where purchasing power and logistics capability are stronger. Providers often rely on partnerships to ensure sample handling quality and trustworthy processing. Middle East & Africa represented 3.90% share in 2025, reflecting early-stage scale with selective growth pockets.
Competitive Landscape
Direct to Consumer Testing Market competition emphasizes test portfolio breadth, clinical credibility, turnaround time, and the strength of digital interpretation layers. Leading participants invest in consumer experience design, sample logistics, and post-result engagement to improve repeat testing behavior. Differentiation also depends on privacy safeguards, data governance practices, and the ability to connect users to next-step actions. Partnerships with employers, pharmacies, and digital health ecosystems support distribution resilience and access expansion.
23andMe maintains a distinctive positioning through consumer-scale genetic testing programs and data-driven insight products that support ongoing engagement. 23andMe strategies often emphasize accessible onboarding, consumer education, and continued feature expansion that keeps users engaged beyond an initial report. 23andMe capabilities can be strengthened when genetic insights connect to broader health services and follow-up pathways. 23andMe differentiation depends on sustaining trust, maintaining robust consent practices, and delivering clear value from interpretation.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- 23andMe
- AncestryHealth
- Everlywell
- LetsGetChecked
- Thriva
- Color Health
- Numan
- InsideTracker
- Veritas Genetics
- Helix
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In January 2026, Hims & Hers expanded into lab testing through a partnership with Quest Diagnostics, allowing consumers to book testing at Quest locations and access broad biomarker panels through the Hims platform.
- In July 2025, TTAM Research Institute completed the acquisition of the Personal Genome Service and Research Services business lines of 23andMe, a deal that strengthened TTAM’s position in consumer-focused genetic testing and related research services.
- In April 2025, Quest Diagnostics launched its AD-Detect Abeta 42/40 and p-tau217 Evaluation blood test to help physicians confirm amyloid brain pathology associated with Alzheimer’s disease in patients with mild cognitive impairment or dementia, expanding its presence in consumer-accessible diagnostic testing.
- In June 2024, PHASE Scientific introduced the INDICAID At-Home Collection Kits for Diabetes (HbA1c) and Heart Health (Lipid Panel), adding new home-based testing options aimed at chronic condition monitoring and preventive care.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 9,820.35 million |
| Revenue forecast in 2032 | USD 16,891.17 million |
| Growth rate (CAGR) | 9.46% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Test Category; By Consumer Purpose; By Sample Collection; By Sales Model; By Distribution Channel; By Data & Analytics Layer |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | 23andMe; AncestryHealth; Everlywell; LetsGetChecked; Thriva; Color Health; Numan; InsideTracker; Veritas Genetics; Helix |
| No. of Pages | 328 |
Segmentation
By Test Category
- Genetic Tests
- Wellness Tests
- Allergy Tests
- Hormone Tests
- Others
By Consumer Purpose
- Preventive Health
- Lifestyle Optimization
- Disease Risk Screening
- Others
By Sample Collection
- Saliva-based
- Finger-prick Blood
- Buccal Swab
- Others
By Sales Model
- One-time Purchase
- Subscription Services
- Corporate Wellness Programs
- Others
By Distribution Channel
- Brand Websites
- Online Marketplaces
- Retail Pharmacies
- Others
By Data & Analytics Layer
- AI-driven Insights
- Raw Data Access
- Physician Interpretation
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Direct to Consumer Testing Market in 2025 and the forecast for 2032?
What is the CAGR for the Direct to Consumer Testing Market during 2025–2032?
What is the largest segment in the Direct to Consumer Testing Market?
What factors are driving growth in the Direct to Consumer Testing Market?
Which companies are leading in the Direct to Consumer Testing Market?
Which region leads the Direct to Consumer Testing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 9,820.35 million → 2032: USD 16,891.17 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Direct-to-Consumer Testing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Direct-to-Consumer Testing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Direct-to-Consumer Testing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Direct-to-Consumer Testing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Direct-to-Consumer Testing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Direct-to-Consumer Testing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Direct-to-Consumer Testing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Direct-to-Consumer Testing Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 9,820.35 million → 2032: USD 16,891.17 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Direct-to-Consumer Testing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Direct-to-Consumer Testing Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Direct-to-Consumer Testing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Direct-to-Consumer Testing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

