
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
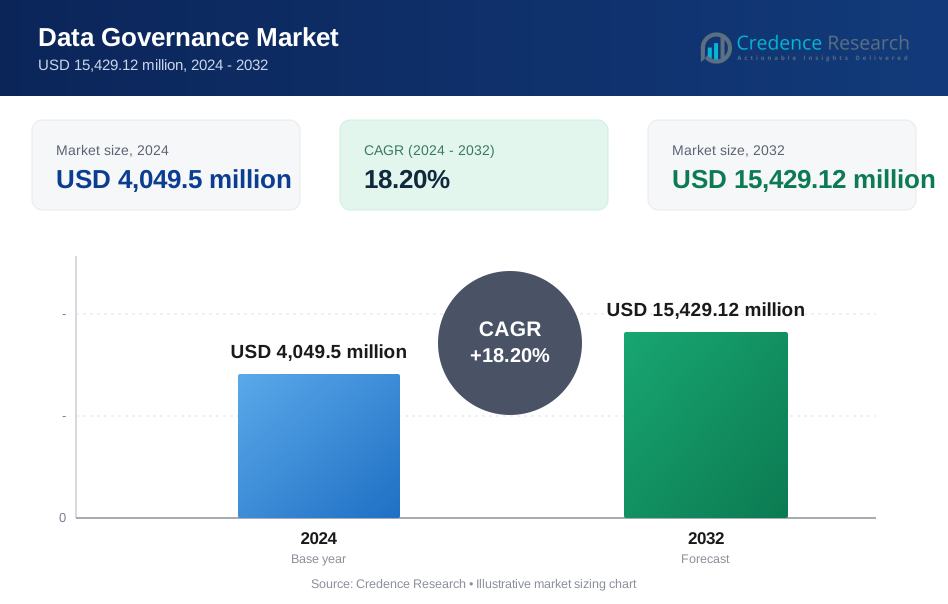
| Data Governance Market Size 2024 | USD 4,049.5 Million |
| Data Governance Market, CAGR | 18.20% |
| Data Governance Market Size 2032 | USD 15,429.12 Million |
Market Overview
The Data Governance Market is projected to expand significantly, growing from USD 4,049.5 million in 2024 to USD 15,429.12 million by 2032, with a robust compound annual growth rate (CAGR) of 18.20%.
The Data Governance Market is driven by increasing regulatory compliance requirements and the growing need for data quality and security across organizations. Companies are investing in data governance solutions to manage and protect vast amounts of data, ensuring its accuracy and accessibility. The rise of big data and analytics further fuels this demand, as businesses seek to leverage data for strategic decision-making. Additionally, trends such as AI and machine learning integration in data governance frameworks enhance automation and efficiency, providing a competitive edge. This convergence of compliance, technology, and data utilization underscores the market's robust growth trajectory.
The Data Governance Market demonstrates robust growth across various regions, with key players like IBM Corporation, Oracle Corporation, and SAP leading the charge globally. North America remains a dominant force due to its advanced technological infrastructure and high adoption rates of data governance solutions. Europe follows, driven by stringent regulatory requirements and a strong focus on data privacy. The Asia-Pacific region is emerging rapidly, fueled by increased digital transformation and rising investments in data management. Prominent regional players include Informatica, SAS, and Varonis, each contributing significantly to the market's expansion through innovative solutions and services.
Market Drivers
Growing Data Volume and Complexity
The explosion of data within organizations is primarily driven by the proliferation of the Internet of Things (IoT) and the widespread adoption of cloud computing. For instance, the proliferation of the Internet of Things (IoT) and the widespread adoption of cloud computing have led to an explosion of data within organizations. These technologies generate vast amounts of data, with IoT devices alone expected to generate more than 79 zettabytes of data by 2025. These technologies generate vast amounts of data in diverse and often complex formats, necessitating robust data governance practices. Effective data governance ensures that this burgeoning data is of high quality, secure, and accessible. Organizations must implement comprehensive governance frameworks to manage and utilize this data effectively. Without such frameworks, the sheer volume and complexity of data can lead to significant challenges, including data silos, inconsistencies, and vulnerabilities, ultimately hampering operational efficiency and decision-making processes.
Escalating Regulatory Compliance Demands
The landscape of regulatory compliance is becoming increasingly stringent. For example, regulations such as the General Data Protection Regulation (GDPR) and the California Consumer Privacy Act (CCPA) impose rigorous data privacy and security requirements. Organizations must adopt data governance solutions to ensure compliance with these regulations, thereby avoiding substantial fines and reputational damage. These solutions help organizations establish clear policies and procedures for data handling, storage, and sharing. By implementing robust data governance practices, businesses can demonstrate their commitment to data privacy and security, thereby gaining trust from customers and stakeholders. This regulatory pressure is a significant driver for the adoption of comprehensive data governance frameworks across various industries.
Need for Improved Data-Driven Decision Making
In today's competitive business environment, organizations increasingly rely on data to inform strategic decisions. For instance, a survey of more than 1,000 senior executives conducted by PwC found that highly data-driven organizations are three times more likely to report significant improvements in decision-making compared to those who rely less on data. Data governance plays a crucial role in ensuring the accuracy, consistency, and trustworthiness of this data. By implementing strong governance practices, organizations can enhance the reliability of their data, leading to more informed and effective decision-making outcomes. High-quality, well-governed data provides a solid foundation for analytics and business intelligence initiatives, enabling organizations to identify trends, uncover insights, and make proactive decisions. As the importance of data-driven strategies grows, the need for robust data governance frameworks becomes even more critical to achieve and maintain a competitive edge.
Rising Data Security Threats
Cyberattacks and data breaches pose significant risks to organizations, with the potential to cause severe financial and reputational damage. Implementing robust data governance practices is essential to protect sensitive data from such threats. Data governance frameworks help organizations establish and enforce security measures, such as encryption, access controls, and monitoring systems, to safeguard their data assets. By prioritizing data security within their governance strategies, organizations can mitigate risks and ensure the confidentiality, integrity, and availability of their data. Additionally, as data democratization empowers employees across departments to access and utilize data, clear ownership, access controls, and usage guidelines become crucial to prevent unauthorized access and misuse, further underscoring the importance of effective data governance.
Market Trends
Cloud-Based Solutions and Data Democratization with Governance
The increasing adoption of cloud technology is significantly influencing the data governance market, driving a surge in demand for cloud-based data governance solutions. For instance, the increasing adoption of cloud technology is significantly influencing the data governance market. As per a report, 94% of enterprises already use a cloud service, and 83% of enterprise workloads will be in the cloud. These solutions provide organizations with scalability, flexibility, and easier deployment options, making them highly attractive to businesses of all sizes. Cloud-based data governance tools enable seamless integration with existing cloud infrastructures, allowing for efficient data management and governance across distributed environments. Furthermore, as businesses strive to balance the need for data access with proper controls, data governance solutions are evolving to facilitate secure self-service data access for authorized users across various departments. This focus on data democratization ensures that employees can access and leverage data effectively while maintaining robust security and compliance standards. By adopting cloud-based data governance solutions, organizations can enhance their data governance frameworks, ensuring that data is managed, protected, and utilized efficiently in a cloud-centric environment.
Integration with AI and ML, User-Friendly Interfaces, and Evolving Regulatory Landscape
The integration of artificial intelligence (AI) and machine learning (ML) into data governance tools is transforming the way organizations manage and govern their data. For instance, AI and ML technologies are being used for tasks such as data lineage tracking, automated data classification, and anomaly detection, which significantly enhance data quality and governance effectiveness. These technologies automate tedious processes, reduce manual intervention, and improve overall data governance by providing deeper insights and more accurate data management. Additionally, there is a growing focus on developing user-friendly interfaces and self-service capabilities in data governance solutions. For example, the General Data Protection Regulation (GDPR) imposes rigorous data privacy and security requirements. In the United States, there is a mix of laws that go by acronyms like HIPAA, FCRA, FERPA, GLBA, ECPA, COPPA, and VPPA. These intuitive interfaces empower business users to understand and manage their data more effectively without solely relying on IT teams, fostering a culture of data literacy and responsibility across the organization. Simultaneously, the evolving regulatory landscape is prompting organizations to adopt data governance solutions that can adapt to and ensure compliance with emerging data privacy and protection regulations globally.
Market Challenges Analysis
Lack of Clear Strategies, Skilled Professionals, and Integration Issues
One of the primary challenges in the data governance market is the lack of clear strategies and policies within organizations. Many businesses struggle to define and articulate comprehensive data governance frameworks, leading to confusion and inconsistencies in implementation. Without well-defined strategies, organizations face difficulties in establishing a cohesive approach to managing data quality, security, and accessibility. This ambiguity hampers the effective execution of data governance practices and undermines efforts to maintain consistent standards across the enterprise. Compounding this issue is the shortage of skilled professionals with the expertise required to manage data governance programs effectively. Implementing and maintaining robust data governance frameworks demand specialized skills that are currently in short supply. The dearth of knowledgeable professionals makes it challenging for organizations to develop and sustain effective data governance initiatives, ultimately affecting the overall quality and reliability of their data management practices. The existence of data silos not only complicates data management but also undermines efforts to achieve a unified and comprehensive view of organizational data. Overcoming these integration challenges is critical to establishing a seamless and efficient data governance framework that ensures data consistency and accessibility across all departments.
Resistance to Change, Cost Justification, and Privacy Concerns
Implementing data governance can also encounter significant resistance to change from employees. Introducing data governance often involves changes in workflows and user behavior, which some employees may resist. This resistance can stem from a lack of understanding of the benefits of data governance or from a reluctance to adopt new processes and technologies. Achieving widespread adoption and ensuring that all employees adhere to data governance practices requires effective change management strategies and ongoing education to highlight the importance and benefits of robust data governance. Additionally, the cost associated with data governance solutions poses a challenge for many organizations. Implementing these solutions requires investment in both technology and personnel, and demonstrating the return on investment (ROI) can be difficult. Organizations often struggle to justify the expense of data governance initiatives without clear and measurable ROI, which can hinder the allocation of resources necessary for effective implementation. Privacy concerns related to data governance tools further complicate the landscape. Data governance tools themselves collect and store information about data usage, and ensuring the privacy and security of this metadata is crucial. Organizations must address privacy concerns to build trust with users and ensure compliance with regulatory requirements. Ensuring that data governance tools adhere to stringent privacy and security standards is essential to prevent potential breaches and protect sensitive information. This involves implementing robust security measures and continuously monitoring and auditing data governance practices to mitigate risks.
Market Segmentation Analysis:
By Solution:
The data governance market is delineated into software and services, each catering to different organizational needs. The software segment provides essential tools for data management, including data quality, data integration, and compliance monitoring. These tools are critical for automating governance processes, ensuring data accuracy, and facilitating adherence to regulatory standards. On the other hand, the services segment is divided into professional and managed services. Professional services encompass consulting, integration and implementation, and support and maintenance. Consulting services help organizations develop and execute effective data governance strategies. Integration and implementation services ensure the seamless integration of governance tools within existing systems, while support and maintenance services address ongoing operational needs and troubleshooting. Managed services offer a comprehensive approach by providing outsourced management of data governance processes, which is ideal for organizations seeking expertise without the need for internal resources.
By Deployment:
Deployment methods in the data governance market are primarily classified into cloud-based and on-premises solutions. Cloud-based deployment is favored for its scalability, flexibility, and cost efficiency. It enables organizations to access governance tools and manage data from any location, making it suitable for businesses with dynamic or distributed operations. This model also supports rapid updates and easier integration with other cloud-based systems. Conversely, on-premises solutions provide greater control and security as they are hosted within the organization’s own infrastructure. This deployment is often preferred by entities with stringent data privacy requirements or specific compliance needs that mandate localized data management. Both deployment options offer unique advantages, and organizations select based on their specific requirements for data accessibility, security, and overall cost.
Segments:
Based on Solution:
- Software
- Services
- Professional Services
- Consulting Services
- Integration & Implementation
- Support & Maintenance
- Managed Services
- Professional Services
Based on Deployment:
- Cloud-Based
- On-Premises
Based on Enterprise Size:
- Small & Medium Enterprises (SMEs)
- Large Enterprises
Based on Industry:
- BFSI (Banking, Financial Services, and Insurance)
- Manufacturing
- Healthcare
- Retail
- Government
- IT & Telecom
- Others
Based on the Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America dominates the global data governance market, commanding a substantial 40% market share. This leadership position is primarily driven by the region's advanced technological infrastructure, stringent data protection regulations, and the presence of major data-centric industries. The United States, in particular, contributes significantly to this market dominance, with its robust financial services, healthcare, and technology sectors implementing comprehensive data governance strategies. The North American market is characterized by a high level of awareness regarding the importance of data quality, security, and compliance, especially in light of regulations such as CCPA and HIPAA. Organizations in the region are increasingly investing in sophisticated data governance tools and platforms to manage the exponential growth of data volumes and complexity. The market benefits from a strong ecosystem of data governance solution providers, ranging from established tech giants to innovative startups, offering a wide array of products and services. Additionally, the region's emphasis on digital transformation across industries has further accelerated the adoption of data governance practices, as businesses seek to leverage data as a strategic asset while mitigating risks associated with data breaches and non-compliance.
Europe
Europe holds the second-largest share in the data governance market at 30%, with countries like the United Kingdom, Germany, and France leading the charge. The European market is primarily driven by the stringent data protection regulations, most notably the General Data Protection Regulation (GDPR), which has made data governance a critical priority for organizations across the continent. The region's market is characterized by a strong focus on privacy-centric data governance solutions, reflecting the cultural and regulatory emphasis on individual data rights. European organizations are increasingly adopting data governance frameworks to ensure compliance, enhance data quality, and improve decision-making processes. The market has seen significant growth in sectors such as banking, insurance, and healthcare, where data sensitivity and regulatory scrutiny are particularly high. Furthermore, the European Union's initiatives to create a single digital market have spurred investments in cross-border data governance solutions. As organizations continue to navigate complex data landscapes and regulatory requirements, the European data governance market is poised for steady growth, with emerging technologies such as AI and blockchain playing an increasingly important role in enhancing data governance capabilities.
Key Player Analysis
- Alation
- ASG Technologies
- Ataccama
- Claravine
- Egnyte
- IBM Corporation
- Informatica
- Information Builders
- Oracle Corporation
- SAP
- SAS
- Synscort
- TIBCO
- Varonis
Competitive Analysis
The Data Governance Market is highly competitive, with leading players such as IBM Corporation, Oracle Corporation, and SAP setting the industry standards. IBM offers a comprehensive suite of data governance solutions, leveraging its cloud and AI capabilities to enhance data management and compliance. Oracle provides robust tools through its Oracle Enterprise Data Management Cloud, focusing on integration and data quality. SAP’s data governance solutions are notable for their integration with SAP's broader enterprise resource planning (ERP) systems, ensuring consistency and control across data landscapes. Informatica and SAS are also key competitors, offering advanced data governance platforms with strong analytics and integration features. Alation and Ataccama bring innovative approaches with their emphasis on data cataloging and automated data quality, respectively. Each player differentiates through unique strengths in cloud capabilities, regulatory compliance, and data integration, driving the market’s competitive dynamics and technological advancements.
Recent Developments
- In May 2024, Alation, a leading data intelligence company, launched Workflow Automation to help organizations proactively identify and address data governance gaps. This solution leverages Alation automation bots to automate repetitive data management tasks, enabling data stewards to focus on strategic initiatives that drive business impact.
- In March 2024, SAP and Collibra expanded their partnership to help customers address the growing need for AI governance. The partnership aims to prioritize and scale AI initiatives safely by providing automated governance workflows, processes, and policies to deliver trusted AI across the enterprise, addressing concerns around AI's unpredictable nature, legal issues, data security, and more.
- In September 2023, Informatica and Oracle strengthened their collaboration by launching an Oracle Cloud Infrastructure (OCI) point of delivery for thousands of joint customers across North America. They unveiled new integrations and capabilities enhancing data governance for their Intelligent Data Management Cloud (IDMC) platform across Oracle's modern data platform. IDMC now offers expanded data control with native scanners collecting metadata and profiling data for quality and semantic insights from Oracle's autonomous database and Oracle GoldenGate.
- In September 2023, Fasoo and Egnyte announced a partnership to simplify data governance for enterprises, integrating Fasoo's data security and privacy solution with Egnyte's enterprise file sharing platform. This enables organizations to discover, classify, and protect sensitive data across their content repositories, providing a comprehensive solution for managing and securing unstructured data throughout its lifecycle. Fasoo's AI-powered data discovery and classification capabilities identify and classify sensitive information within Egnyte's content repositories.
- In June 2023, Privacera, the cloud data governance and security leader, announced the private preview of Privacera AI Governance (PAIG), the industry's first and most comprehensive AI data security governance solution for High-performance AI-driven data control and security for AI use cases, building on Privacera's existing data privacy, security, and access governance capabilities.
Market Concentration & Characteristics
The Data Governance Market exhibits moderate to high concentration, with leading players such as IBM, Oracle, and SAP dominating the landscape. These major companies leverage their extensive resources and technological expertise to offer comprehensive solutions that address various aspects of data governance, including data quality, compliance, and integration. The market is characterized by a strong emphasis on advanced technologies like AI and machine learning, which are integrated into data governance tools to enhance automation and accuracy. Additionally, there is a growing trend towards cloud-based solutions, driven by the demand for scalable and flexible deployment options. Despite the presence of large, established players, there is also significant innovation from specialized firms like Alation and Ataccama, which focus on niche aspects such as data cataloging and data quality. This combination of established leaders and emerging innovators contributes to a dynamic and evolving market, catering to diverse organizational needs.
Report Coverage
The research report offers an in-depth analysis based on Solution, Deployment, Enterprise Size, Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Data Governance Market is expected to experience significant growth driven by the increasing complexity of data management needs.
- Cloud-based data governance solutions will continue to gain traction due to their scalability and cost-effectiveness.
- The integration of artificial intelligence and machine learning will enhance data governance capabilities, providing more automated and accurate data management.
- Businesses will increasingly adopt data governance practices to meet stringent regulatory requirements and ensure compliance.
- There will be a growing focus on data privacy and security, with solutions evolving to protect sensitive information from breaches and unauthorized access.
- Enhanced data democratization efforts will lead to more user-friendly and accessible governance tools, enabling broader organizational use.
- The need for real-time data insights will drive demand for solutions that support rapid data processing and analysis.
- Investment in data lineage and provenance technologies will rise as organizations seek to understand and trace their data's journey.
- Small and medium enterprises will increasingly adopt data governance solutions as they recognize the importance of managing data effectively.
- The market will see continued innovation and competition, with emerging players offering specialized solutions alongside established industry leaders.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Data Volume and Complexity
The proliferation of IoT devices and widespread cloud adoption are generating massive and complex data sets, necessitating robust data governance frameworks to ensure data quality, accessibility, and security across organizations.
Escalating Regulatory Compliance Demands
Stringent regulations such as GDPR and CCPA require organizations to implement comprehensive data governance solutions to avoid fines and reputational damage, driving adoption across industries that handle sensitive or regulated data.
Need for Improved Data-Driven Decision Making
Organizations are increasingly relying on high-quality, well-governed data to inform strategic decisions, making data governance essential for ensuring data accuracy, consistency, and trustworthiness in analytics and business intelligence initiatives.
Rising Data Security Threats
The growing frequency and sophistication of cyberattacks and data breaches are pushing organizations to adopt data governance practices that enforce security measures, protect sensitive information, and ensure compliance with privacy standards.
Cloud-Based Solutions and Data Democratization
The shift toward cloud-based data governance tools offers scalability and flexibility, while enabling secure self-service data access for employees, supporting both operational efficiency and compliance in distributed environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Data Governance Market?
What factors are driving the growth of the Data Governance Market?
What are the key segments within the Data Governance Market?
What are some challenges faced by the Data Governance Market?
Who are the major players in the Data Governance Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Industry
- 1.2.1 BFSI
- 1.2.2 Manufacturing
- 1.2.3 Healthcare
- 1.2.4 Retail
- 1.2.5 Government
- 1.2.6 IT & Telecom
- 1.2.7 Others
- 1.3 By Solution
- 1.3.1 Software
- 1.3.2 Professional Services
- 1.3.3 Managed Services
- 1.4 By Deployment
- 1.4.1 Cloud-Based
- 1.4.2 On-Premises
- 1.5 By Enterprise Size
- 1.5.1 Small & Medium Enterprises (SMEs)
- 1.5.2 Large Enterprises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,049.5 million → 2032: USD 15,429.12 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Data Governance Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Data Governance Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Data Governance Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Data Governance Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Data Governance Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Data Governance Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Data Governance Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Data Governance Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,049.5 million → 2032: USD 15,429.12 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Data Governance Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Industry - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 BFSI
- 12.3.6.2 Manufacturing
- 12.3.6.3 Healthcare
- 12.3.6.4 Retail
- 12.3.6.5 Government
- 12.3.6.6 IT & Telecom
- 12.3.6.7 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Solution - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Software
- 12.4.6.2 Professional Services
- 12.4.6.3 Managed Services
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Cloud-Based
- 12.5.6.2 On-Premises
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Enterprise Size - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Small & Medium Enterprises (SMEs)
- 12.6.6.2 Large Enterprises
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Data Governance End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Data Governance Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Data Governance Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Data Governance Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IBM Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Oracle Corporation
- 18.4 SAP
- 18.5 Informatica
- 18.6 SAS
- 18.7 Alation
- 18.8 Ataccama
- 18.9 Egnyte
- 18.10 Varonis
- 18.11 ASG Technologies
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

