
Market Overview:
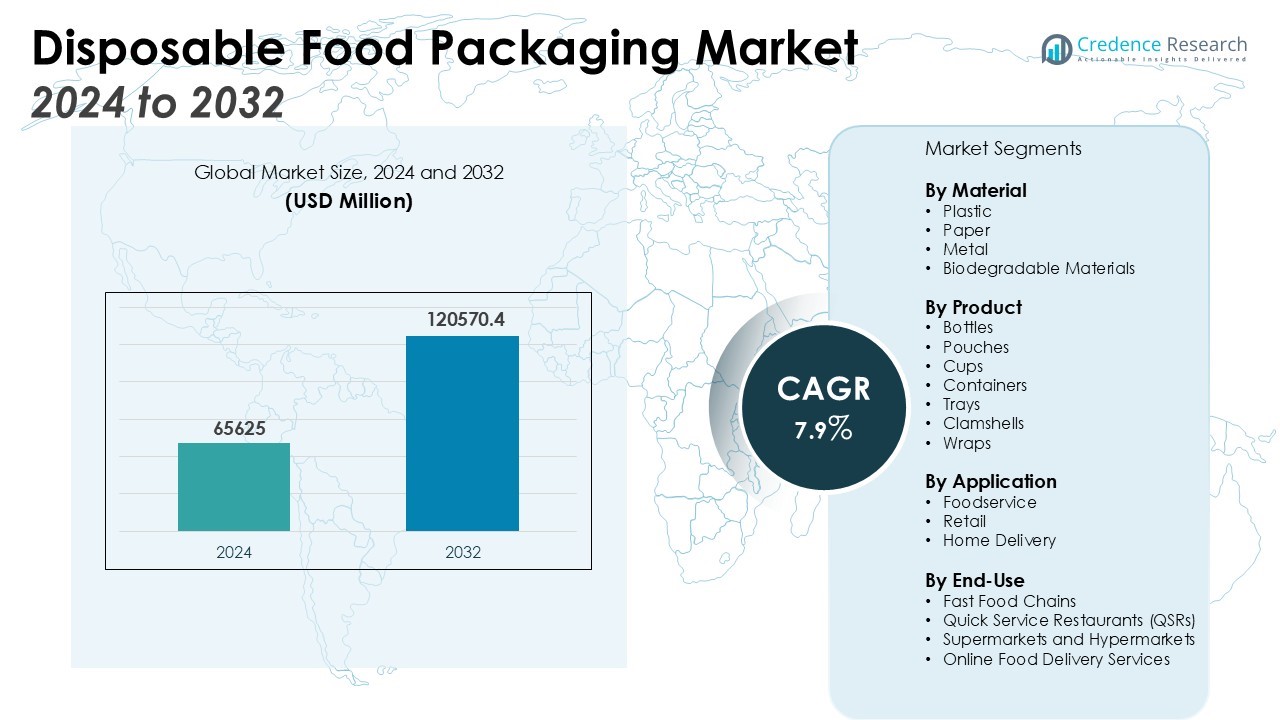
The Disposable Food Packaging Market size was valued at USD 65625 million in 2024 and is anticipated to reach USD 120570.4 million by 2032, at a CAGR of 7.9% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Disposable Food Packaging Market Size 2024 | USD 65625 Million |
| Disposable Food Packaging Market , CAGR | 7.9% |
| Disposable Food Packaging Market Size 2032 | USD 120570.4 Million |
Key drivers of the market include the growing preference for on-the-go food options, which boosts the demand for single-serve packaging solutions. Additionally, sustainability concerns and the shift toward eco-friendly materials are influencing the industry, with many companies adopting biodegradable and recyclable packaging to align with consumer preferences. The need for enhanced hygiene and the growing popularity of fast food, takeaway, and home-delivery services further support market expansion, as disposable packaging is seen as a more hygienic and convenient option.
Regionally, North America holds the largest market share due to the widespread use of disposable food packaging in the foodservice industry and the presence of key players in the region. Increased focus on sustainability and advancements in packaging technologies also contribute to the region's dominance. The Asia Pacific market is expected to witness the highest growth rate during the forecast period, driven by rapid urbanization, increasing consumer demand for packaged food, and expanding foodservice industries in countries like China and India. Additionally, improvements in disposable packaging infrastructure and changing lifestyles in emerging economies are accelerating market growth in this region.
Market Insights:
- The Disposable Food Packaging Market was valued at USD 65.625 million in 2024 and is expected to reach USD 120.570.4 million by 2032, growing at a CAGR of 7.9% during the forecast period.
- Growing preference for on-the-go food options and the rise of fast food, takeaway, and home-delivery services are driving the demand for single-serve disposable packaging solutions.
- Sustainability concerns are pushing companies to adopt biodegradable, recyclable, and eco-friendly packaging alternatives, significantly shaping the market.
- Hygiene and safety concerns, especially in the foodservice sector, are further fueling market growth as disposable packaging ensures a more hygienic food handling and transportation solution.
- North America holds 35% of the market share, driven by the demand for disposable packaging in the foodservice industry and the push for sustainable packaging solutions.
- Asia Pacific, holding a 28% market share, is experiencing rapid growth due to urbanization, rising disposable incomes, and increased demand for convenient food options.
- Europe, with a 22% market share, is focusing on sustainability and compliance with stricter regulations, driving demand for eco-friendly and biodegradable packaging solutions.
Market Drivers:
Growing Demand for Convenient, On-the-Go Food Options
The increasing demand for convenient, on-the-go food options plays a crucial role in driving the growth of the Disposable Food Packaging Market. Busy lifestyles and changing consumer preferences have led to a surge in the consumption of ready-to-eat food products. Single-serve packaging solutions are becoming more popular, offering convenience for both consumers and foodservice providers. This demand aligns with the growing trend of fast food, takeaway, and meal delivery services, which all rely on disposable packaging for convenience and hygiene. The ease of carrying and consuming packaged meals has led to an uptick in disposable food packaging applications across various sectors.
- For instance, Anchor Packaging’s Crisp Food Technologies® containers are now used in over 21,000 restaurant, supermarket, and convenience store locations to keep fried foods hot and crispy during delivery and takeout, illustrating rapid technological adoption in food packaging solutions.
Shift Toward Eco-Friendly and Sustainable Packaging Solutions
Sustainability concerns and the shift toward eco-friendly materials are significantly shaping the Disposable Food Packaging Market. With increasing awareness about environmental issues, consumers and companies are prioritizing the use of biodegradable, recyclable, and compostable packaging. Several countries have implemented strict regulations on plastic usage, prompting businesses to adopt sustainable alternatives to reduce their environmental impact. Innovations in packaging materials, such as plant-based plastics and recyclable composites, are enabling the market to respond to these sustainability demands. The growing consumer preference for environmentally conscious brands further accelerates this trend.
Hygiene and Safety Concerns in the Foodservice Sector
The growing importance of hygiene and safety in the foodservice industry is another key driver for the Disposable Food Packaging Market. Disposable packaging offers a more hygienic and sanitary option compared to reusable containers, especially in food handling and transportation. The COVID-19 pandemic further emphasized the need for disposable packaging as a means of reducing contamination risks. This trend is particularly noticeable in fast food, delivery, and takeout services, where maintaining hygiene and food safety is paramount. Packaging innovations that enhance product integrity and prevent contamination are fueling the market's growth.
- For instance, in July 2023, researchers at McMaster University developed a packaging tray embedded with a sensor that can instantly signal contamination by Salmonella, allowing users to scan the package with a mobile phone for immediate safety verification-targeting a global issue that results in approximately 600 million foodborne illnesses annually.
Expansion of Fast Food and Home-Delivery Services
The expansion of fast food and home-delivery services directly impacts the Disposable Food Packaging Market. The increasing preference for ordering food online, coupled with the rise of quick-service restaurants (QSRs), has led to a higher demand for packaging solutions that ensure food quality and safety during transportation. Disposable packaging, which is lightweight, cost-effective, and practical, caters to these needs. Furthermore, foodservice providers are continuously seeking packaging that maintains the temperature and quality of their products while being environmentally responsible. This surge in demand from the foodservice and delivery sectors is driving market expansion.
Market Trends:
Shift Toward Sustainable and Biodegradable Materials
One of the prominent trends in the Disposable Food Packaging Market is the shift toward the adoption of sustainable and biodegradable materials. With growing environmental concerns, both consumers and businesses are increasingly prioritizing eco-friendly packaging solutions. Governments across various regions have implemented policies to reduce plastic waste, pushing the food packaging industry to explore alternatives such as plant-based plastics, recycled materials, and compostable packaging. This trend reflects a broader movement toward circular economy practices, where packaging is designed for reuse, recycling, or composting. As consumers demand more environmentally responsible options, packaging manufacturers are investing in research and development to create innovative, sustainable solutions that align with these preferences. These efforts contribute to a significant change in the industry, impacting packaging materials, production processes, and supply chain logistics.
- For instance, The Biden-Harris administration has set a federal goal to phase out single-use plastics from food service packaging by 2027 and all federal operations by 2035.
Integration of Smart Packaging and Digital Technologies
Another notable trend in the Disposable Food Packaging Market is the integration of smart packaging technologies. Packaging solutions with integrated digital features, such as QR codes, RFID tags, and temperature indicators, are becoming increasingly common. These innovations enable manufacturers, retailers, and consumers to track product freshness, monitor temperature control during transportation, and ensure authenticity. The use of smart packaging enhances food safety and provides real-time product data, improving transparency in the supply chain. As consumer expectations evolve, manufacturers are focusing on adding value through interactive and intelligent packaging solutions that provide additional functionalities. The increasing reliance on digital technologies in the foodservice industry further promotes this trend, with smart packaging playing a key role in improving operational efficiency and customer satisfaction.
- For instance, Mondelēz International piloted a traceability program on Triscuit Original boxes, where consumers can scan a QR code to access the wheat’s journey from 127 verified Unity Gold farmers to the factory.
Market Challenges Analysis:
Rising Environmental Concerns and Regulatory Pressures
A significant challenge in the Disposable Food Packaging Market is the growing pressure to address environmental concerns. With the increasing awareness of plastic pollution and its environmental impact, governments around the world are introducing stricter regulations to limit the use of single-use plastics. The demand for sustainable and biodegradable packaging materials is pushing companies to adapt, but these alternatives often come with higher production costs. The complexity of compliance with regional laws and international environmental standards further strains manufacturers, as they must continuously innovate while managing production costs. The industry faces pressure to balance the need for packaging convenience with environmental sustainability.
Fluctuating Raw Material Costs and Supply Chain Disruptions
Another challenge facing the Disposable Food Packaging Market is the volatility in raw material costs and supply chain disruptions. The prices of materials such as paper, plastic, and biodegradable components can fluctuate significantly due to factors like global economic conditions and limited supply of raw materials. These cost fluctuations make it difficult for manufacturers to maintain stable pricing for end consumers while managing profitability. Moreover, disruptions in the global supply chain, such as those caused by geopolitical tensions or natural disasters, further complicate sourcing and delivery timelines, potentially leading to delays and increased costs for packaging solutions.
Market Opportunities:
Growing Demand for Eco-Friendly Packaging Solutions
The increasing demand for sustainable packaging solutions presents a significant opportunity for the Disposable Food Packaging Market. As consumers become more environmentally conscious, they are actively seeking products with eco-friendly packaging. This shift is encouraging packaging manufacturers to invest in innovative materials such as biodegradable plastics, plant-based materials, and recyclable composites. Companies that can successfully develop cost-effective, sustainable packaging solutions stand to benefit from increased market share. The rising trend of sustainability, driven by both consumer preference and regulatory requirements, offers a substantial growth avenue for businesses that adapt to these demands.
Expansion of Online Food Delivery Services
The rapid growth of online food delivery services offers another promising opportunity for the Disposable Food Packaging Market. The increasing reliance on food delivery platforms due to changing consumer lifestyles and the rise of convenience-driven dining creates a higher demand for disposable packaging. As restaurants and foodservice providers expand their online presence, they require packaging solutions that maintain food quality and ensure safe delivery. The surge in demand for packaged meals, especially in urban areas, positions the market for continued growth. By developing packaging solutions tailored to the needs of online food delivery services, companies can tap into this rapidly expanding segment.
Market Segmentation Analysis:
By Material
The material segment includes plastic, paper, metal, and biodegradable materials. Plastic continues to dominate the market due to its versatility, cost-effectiveness, and wide availability. However, the shift towards sustainability has increased the demand for biodegradable and recyclable materials. Paper-based packaging is growing in popularity, especially for food items like sandwiches and beverages, due to its eco-friendly appeal. Biodegradable materials, such as plant-based plastics and compostable fibers, are gaining traction as consumers and companies seek more sustainable alternatives.
By Product
In the product segment, packaging solutions include bottles, pouches, cups, containers, and trays. Bottles and pouches are increasingly favored for beverages and ready-to-drink products due to their convenience. Containers and trays are widely used for both takeout and fast food, ensuring food safety and easy handling. Cups are essential for the beverage industry, with coffee cups being a key contributor to growth. The demand for multi-compartment trays and microwave-safe containers is rising, particularly in quick-service restaurants (QSRs).
- For instance, Amcor produced 1,278,000 metric tons of recyclable rigid packaging, primarily bottles and pouches, in FY24.
By Application
The Disposable Food Packaging Market is widely used across various applications, including the foodservice industry, retail, and home delivery. The foodservice industry is the largest consumer, driven by the increasing number of fast food chains and delivery services. Retail applications focus on packaging products for shelf stability, while home delivery applications are growing with the rise of online food orders. All segments benefit from the growing need for convenience, hygiene, and product safety.
- For instance, Printpack won a Gold Award for Shelf Impact in 2025 for their new Goldfish® Crisps flexible packaging, marking a technological achievement in shelf-ready innovations for major retail brands.
Segmentations:
- By Material:
- Plastic
- Paper
- Metal
- Biodegradable Materials
- By Product:
- Bottles
- Pouches
- Cups
- Containers
- Trays
- Clamshells
- Wraps
- By Application:
- Foodservice
- Retail
- Home Delivery
- By End-Use:
- Fast Food Chains
- Quick Service Restaurants (QSRs)
- Supermarkets and Hypermarkets
- Online Food Delivery Services
- By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
North America: Leading Market with Strong Demand for Disposable Food Packaging
North America holds a market share of 35% in the Disposable Food Packaging Market. The region’s advanced foodservice sector and high demand for ready-to-eat food products drive the widespread use of disposable packaging solutions. The preference for fast food, takeaway, and delivery services in the U.S. and Canada significantly contributes to market growth. Additionally, strict environmental regulations in these countries are fostering a shift toward sustainable and recyclable packaging. The presence of major packaging manufacturers and foodservice companies in the region further bolsters demand. As consumer expectations evolve, the need for eco-friendly packaging solutions continues to grow, providing long-term market potential.
Asia Pacific: Rapid Growth Fueled by Urbanization and Evolving Lifestyles
The Asia Pacific region holds a market share of 28% in the Disposable Food Packaging Market, with rapid urbanization and increasing consumer demand propelling its growth. Countries like China, India, and Japan are witnessing significant changes in lifestyles, with rising disposable incomes and an increasing preference for convenient, on-the-go food options. The expanding foodservice sector, driven by fast-food chains and online food delivery platforms, is also fueling packaging demand. Additionally, advancements in packaging technologies and growing awareness of sustainability are creating opportunities for innovation in eco-friendly packaging solutions. As consumer preferences evolve, the region is positioned for continued market expansion.
Europe: Focus on Sustainability and Compliance Driving Market Demand
Europe commands a market share of 22% in the Disposable Food Packaging Market, with a strong emphasis on sustainability and regulatory compliance. European countries have enacted policies to reduce plastic waste, prompting businesses to adopt biodegradable, recyclable, and compostable packaging. The rising consumer demand for eco-friendly packaging materials plays a vital role in shaping the market landscape. The growing foodservice sector, particularly quick-service restaurants (QSRs) and delivery services, further supports the demand for disposable packaging. Packaging manufacturers in Europe are responding by developing innovative solutions that meet both sustainability standards and evolving consumer preferences.
Key Player Analysis:
- Genpak
- Pactiv Evergreen Inc.
- Graphic Packaging International, LLC
- Sonoco Products Company
- Carlisle FoodService Products
- GreenGood
- Sabert Corporation
- Amhil
- Huhtamaki
- Inteplast Group
- Anchor Packaging LLC
- Dart Container Corporation
- Mondi
- Georgia-Pacific LLC
- Printpack
Competitive Analysis:
The Disposable Food Packaging Market is highly competitive, with several key players leading the industry. Major companies focus on innovation, sustainability, and cost-efficiency to maintain market share. Key players in this market include Amcor PLC, Sealed Air Corporation, Berry Global, Inc., and Sonoco Products Company. These companies are investing heavily in research and development to introduce eco-friendly and biodegradable packaging solutions, responding to consumer demand for sustainable alternatives. Strategic partnerships, mergers, and acquisitions are common, as firms seek to expand their product portfolios and geographical reach. Regional players are also focusing on enhancing their production capabilities and distribution networks to capture emerging markets. Competition is intensifying in regions like Asia Pacific, where rapid urbanization and growing foodservice industries offer significant growth opportunities. The focus on meeting regulatory requirements and offering customized packaging solutions further drives competition among these players.
Recent Developments:
- In May 2025, Graphic Packaging International launched a new portfolio of sustainable paperboard sushi packaging designed to comply with the EU Single-Use Plastics Directive.
- In January 2025, Genpak launched Grab-A-Bowl, a new line of polypropylene bowls and lids for foodservice, designed for both hot and cold applications, featuring easy-grip tabs, stackability, and clear visibility of contents, suitable for convenience stores, restaurants, and grocery retailers.
Market Concentration & Characteristics:
The Disposable Food Packaging Market exhibits moderate concentration, with a few dominant global players and a large number of regional and local companies. Key players such as Amcor PLC, Sealed Air Corporation, and Berry Global, Inc. hold significant market share, driven by their extensive product portfolios and advanced manufacturing capabilities. The market is characterized by intense competition, innovation, and a shift towards sustainable packaging solutions. Companies are increasingly focusing on environmentally friendly materials, such as biodegradable and recyclable packaging, to meet growing consumer demand. New entrants are emerging, especially in regions with expanding foodservice and retail sectors, contributing to the overall market dynamics. The market is also witnessing regional fragmentation, with variations in consumer preferences, regulatory standards, and packaging requirements. This creates both opportunities and challenges for companies striving to maintain competitive advantages while adapting to local market conditions.
Report Coverage:
The research report offers an in-depth analysis based on Material, Product, Application, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- A significant shift towards sustainable materials, with biodegradable, compostable, and recyclable options gaining preference over traditional plastics.
- Increased adoption of flexible packaging formats, driven by their lightweight nature and cost-effectiveness.
- Integration of smart packaging technologies, such as QR codes and NFC tags, enhancing consumer engagement and product traceability.
- Expansion of online food delivery services, boosting demand for packaging solutions that ensure food safety and convenience.
- Implementation of stricter environmental regulations, compelling companies to innovate and comply with sustainability standards.
- Growth in the use of edible and plant-based packaging materials, offering eco-friendly alternatives to conventional options.
- Increased consumer awareness and preference for brands that demonstrate environmental responsibility and transparency.
- Advancements in packaging design and functionality, focusing on enhancing user experience and reducing waste.
- Collaborations between manufacturers, retailers, and regulators to develop and promote sustainable packaging solutions.
- Continued investment in research and development to create innovative packaging materials and technologies that align with market demands.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for Convenient, On-the-Go Food Options
Busy lifestyles and the rise of fast food, takeaway, and home-delivery services are increasing the need for single-serve and portable packaging solutions, directly boosting the disposable food packaging market.
Shift Toward Eco-Friendly and Sustainable Packaging Solutions
Heightened environmental awareness and regulatory actions are pushing companies to adopt biodegradable, recyclable, and compostable packaging, driving innovation and growth in sustainable disposable food packaging.
Hygiene and Safety Concerns in the Foodservice Sector
Disposable packaging is perceived as more hygienic than reusable alternatives, especially in food handling and delivery, which has become even more critical post-pandemic, fueling market expansion.
Expansion of Fast Food and Home-Delivery Services
The proliferation of quick-service restaurants and the surge in online food delivery platforms require reliable, cost-effective, and protective disposable packaging to maintain food quality and safety during transit.
Advancements in Packaging Technologies
Innovations such as smart packaging with sensors and traceability features are enhancing food safety, shelf life, and consumer engagement, encouraging adoption of advanced disposable packaging solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Disposable Food Packaging Market?
What factors are driving the growth of the Disposable Food Packaging Market?
What are the key segments within the Disposable Food Packaging Market?
What are some challenges faced by the Disposable Food Packaging Market?
Who are the major players in the Disposable Food Packaging Market?
Q: Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Fast Food Chains
- 1.2.2 Quick Service Restaurants (QSRs)
- 1.2.3 Supermarkets and Hypermarkets
- 1.2.4 Online Food Delivery Services
- 1.3 By Product
- 1.3.1 Bottles
- 1.3.2 Pouches
- 1.3.3 Cups
- 1.3.4 Containers
- 1.3.5 Trays
- 1.3.6 Clamshells
- 1.3.7 Wraps
- 1.4 By Material
- 1.4.1 Plastic
- 1.4.2 Paper
- 1.4.3 Metal
- 1.4.4 Biodegradable Materials
- 1.5 By Application
- 1.5.1 Foodservice
- 1.5.2 Retail
- 1.5.3 Home Delivery
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 65,625 million → 2032: USD 120,570.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Disposable Food Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Disposable Food Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Disposable Food Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Disposable Food Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Disposable Food Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Disposable Food Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Disposable Food Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Disposable Food Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 65,625 million → 2032: USD 120,570.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Disposable Food Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fast Food Chains
- 12.3.7.2 Quick Service Restaurants (QSRs)
- 12.3.7.3 Supermarkets and Hypermarkets
- 12.3.7.4 Online Food Delivery Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Bottles
- 12.4.7.2 Pouches
- 12.4.7.3 Cups
- 12.4.7.4 Containers
- 12.4.7.5 Trays
- 12.4.7.6 Clamshells
- 12.4.7.7 Wraps
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Plastic
- 12.5.7.2 Paper
- 12.5.7.3 Metal
- 12.5.7.4 Biodegradable Materials
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Foodservice
- 12.6.7.2 Retail
- 12.6.7.3 Home Delivery
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Disposable Food Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Disposable Food Packaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Disposable Food Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Disposable Food Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amcor PLC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sealed Air Corporation
- 18.4 Berry Global, Inc.
- 18.5 Sonoco Products Company
- 18.6 Graphic Packaging International, LLC
- 18.7 Pactiv Evergreen Inc.
- 18.8 Huhtamaki
- 18.9 Dart Container Corporation
- 18.10 Mondi
- 18.11 Genpak
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

