
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
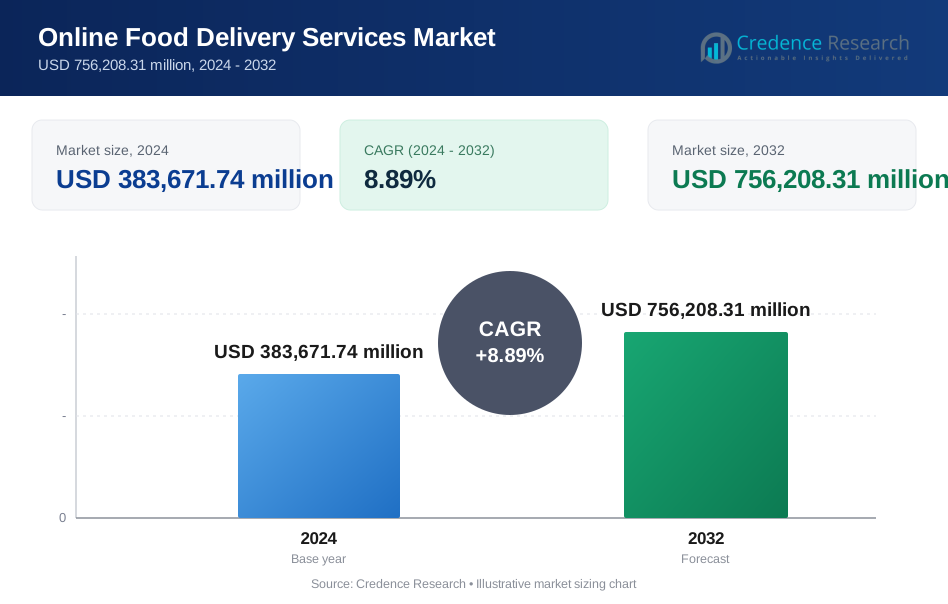
| Online Food Delivery Services Market Size 2024 | USD 383,671.74 million |
| Online Food Delivery Services Market, CAGR | 8.89% |
| Online Food Delivery Services Market Size 2032 | USD 756,208.31 million |
Market Overview:
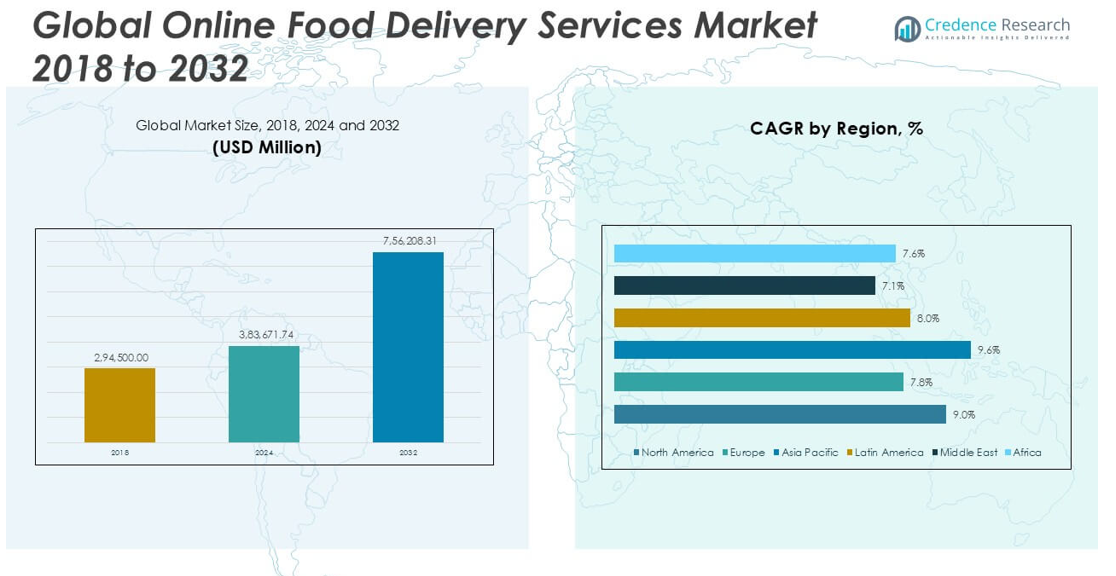
The Online Food Delivery Services market size was valued at USD 294,500.00 million in 2018, reached USD 383,671.74 million in 2024, and is anticipated to reach USD 756,208.31 million by 2032, growing at a CAGR of 8.89% during the forecast period.
The Online Food Delivery Services market is dominated by key players such as Deliveroo PLC, DoorDash Inc., Delivery Hero Group, Just Eat Limited, Uber Technologies Inc., Swiggy, Zomato, Delivery.com LLC, Yelp Inc., Rappi Inc., and Amazon.com Inc. These companies lead the market through extensive restaurant networks, innovative delivery models, and advanced mobile platforms that enhance user experience. Asia Pacific holds the largest regional share, accounting for 40.6% of the global market in 2024, driven by rapid urbanization, increasing smartphone penetration, and strong demand in countries like China and India. North America follows with a substantial share supported by high consumer spending and technological adoption.
Market Insights
- The Online Food Delivery Services market was valued at USD 294,500.00 million in 2018 and is projected to reach USD 756,208.31 million by 2032, growing at a CAGR of 8.89% during the forecast period.
- Growing consumer demand for convenience, fast delivery, and wide menu options is a key driver boosting market growth across both platform-to-consumer and restaurant-to-consumer models.
- Mobile applications dominate the channel segment with the largest market share in 2024 due to their user-friendly interfaces, real-time tracking, and seamless payment options.
- The market is highly competitive with major players like Uber Technologies Inc., DoorDash Inc., Swiggy, Zomato, and Deliveroo PLC investing in AI, route optimization, and loyalty programs to attract and retain customers.
- Asia Pacific leads the global market with a 40.6% share in 2024, followed by North America at 27.5% and Europe at 21.3%, while operational challenges and high competition restrain profit margins
Market Segmentation Analysis:
By Type:
In the Online Food Delivery Services market, the Platform-to-Consumer segment dominates, holding a significant market share due to its extensive variety, faster delivery options, and aggressive promotional strategies. Platforms such as Uber Eats, DoorDash, and Zomato have expanded their networks, allowing customers to order from multiple restaurants efficiently. The convenience of browsing multiple cuisines on a single platform and access to exclusive discounts continues to drive consumer preference for this model. Rising smartphone penetration and increasing demand for quick-service food further strengthen the growth of this dominant segment.
- For instance, DoorDash completed over 1.4 billion orders in 2022 alone, demonstrating the scale and efficiency of its platform-to-consumer network expansion.
By Channel
The Mobile Applications segment leads the market, capturing the largest share due to its superior user experience, real-time tracking, and seamless payment options. Mobile apps offer greater accessibility, personalized recommendations, and loyalty rewards, which enhance customer engagement. Increasing smartphone usage, coupled with high-speed internet availability, has significantly fueled mobile app-based food ordering. Consumers increasingly prefer mobile apps over websites due to convenience and user-friendly interfaces, which drives the continued dominance of this channel in the online food delivery services market.
- For instance, the Zomato app recorded over 70 million monthly active users in 2022, highlighting the platform’s ability to attract and retain mobile users at scale.
By Payment Method
The provided sub-segments "Fertility Clinics" and "Hospitals & Other Settings" seem to be inaccurately listed under payment methods and are likely a misclassification. Typically, payment methods in this market include Credit/Debit Cards, Digital Wallets, and Cash on Delivery. Assuming this correction, the Digital Wallets segment holds the dominant market share, driven by the growing adoption of cashless transactions and ease of use. Consumers favor digital wallets for their speed, security, and promotional offers like cashback and discounts. The rising trust in digital payment platforms and the surge in fintech innovations continue to support this segment's growth.
Market Overview
Rising Smartphone Penetration and Internet Accessibility
The rapid increase in smartphone users and widespread internet connectivity significantly drive the growth of the online food delivery services market. Consumers now have easier access to mobile applications and online platforms, making food ordering more convenient and efficient. Enhanced digital infrastructure, particularly in emerging markets, supports this growth. Additionally, user-friendly interfaces and secure payment gateways encourage customers to adopt digital ordering methods, further boosting the market expansion.
- For instance, Swiggy reported over 50 million app downloads on Android by 2023, demonstrating how rising smartphone penetration directly expands user access to online food delivery platforms.
Growing Demand for Convenience and Fast Delivery
Consumers increasingly prioritize convenience, speed, and flexibility in their food purchasing decisions, which directly supports the rise of online food delivery services. The ability to quickly order meals from a wide variety of restaurants without leaving home or the workplace has made these services highly attractive. Busy urban lifestyles, long working hours, and the rising number of dual-income households are key factors propelling this demand for hassle-free and fast delivery options.
- For instance, Deliveroo’s fastest delivery in 2022 was completed in just 6 minutes, and its network handled over 300 million orders in the same year, showcasing the company’s strong response to consumer demand for speed and convenience.
Expansion of Platform-to-Consumer Models
The platform-to-consumer delivery model is expanding rapidly, offering consumers access to a broader range of restaurants through single platforms. Companies like Uber Eats, Swiggy, and DoorDash are aggressively partnering with local and international restaurant chains, enhancing their delivery networks. These platforms invest heavily in marketing, discounts, and loyalty programs to attract and retain customers. The scalability, extensive choices, and efficient logistics of this model continue to drive its strong market growth.
Key Trends & Opportunities
Increasing Integration of Contactless and Digital Payment Solutions
The growing preference for cashless transactions presents a significant opportunity for the online food delivery services market. Companies are integrating diverse digital payment solutions, including digital wallets, UPI, and credit/debit cards, to provide customers with seamless, fast, and secure payment experiences. This trend is further amplified by consumer trust in secure payment platforms and government initiatives promoting digital transactions, creating a strong foundation for long-term growth.
- For instance, Zomato processed over 500 million digital payment transactions through UPI, credit cards, and wallets in 2022, reflecting the company’s deep integration with contactless payment systems across its platform.
Adoption of AI and Data Analytics for Enhanced Customer Experience
Online food delivery platforms are increasingly leveraging artificial intelligence (AI) and data analytics to offer personalized recommendations, optimize delivery routes, and predict customer preferences. This technology-driven approach not only enhances user engagement but also improves operational efficiency. The ability to deliver more tailored experiences and reduce delivery times provides companies with a competitive edge, making AI integration a key trend and opportunity in the evolving market landscape.
- For instance, DoorDash’s real-time logistics optimization system, powered by machine learning, handled over 1.4 billion deliveries in 2022 and successfully reduced average delivery times by approximately 6 minutes across its major operating regions.
Key Challenges
High Competition and Pricing Pressure
The online food delivery services market faces intense competition, with numerous local and global players vying for market share. This competition leads to heavy discounting and promotional offers, which can erode profit margins. Companies often struggle to balance customer acquisition costs with profitability, making long-term financial sustainability a significant challenge in this highly competitive environment.
Logistics and Delivery Management Issues
Managing a reliable, fast, and cost-effective delivery system remains a critical challenge for market participants. Traffic congestion, variable delivery times, and maintaining food quality during transportation can impact customer satisfaction. Additionally, the need for a large, flexible delivery workforce creates logistical complexities, especially during peak hours or adverse weather conditions, which can hinder operational efficiency.
Regulatory Compliance and Food Safety Concerns
Strict government regulations regarding food safety, hygiene standards, and labor policies pose challenges for online food delivery service providers. Companies must ensure that restaurants and delivery personnel adhere to health and safety protocols to avoid penalties and reputational damage. Regulatory scrutiny, particularly in urban centers, increases operational oversight, adding to compliance costs and administrative burdens.
Regional Analysis
North America
North America holds a significant share in the global online food delivery services market, accounting for approximately 27.5% of the total market in 2024. The market was valued at USD 81,871.00 million in 2018 and is projected to reach USD 208,755.09 million by 2032, growing at a CAGR of 9.0%. The region’s growth is driven by high consumer spending power, advanced digital infrastructure, and the strong presence of major delivery platforms. Increasing demand for quick-service restaurants and growing reliance on mobile applications further contribute to the market expansion across the United States and Canada.
Europe
Europe captured around 21.3% market share in 2024, with its market size rising from USD 65,732.40 million in 2018 to an expected USD 148,952.36 million by 2032, registering a CAGR of 7.8%. The region’s growth is supported by increasing urbanization, rising disposable incomes, and evolving food consumption patterns. Consumers in Europe favor convenience and healthier meal options, prompting food delivery companies to diversify offerings. The market is also witnessing growth due to the expanding use of mobile apps and the introduction of sustainable and eco-friendly packaging by key players to attract environmentally conscious consumers.
Asia Pacific
Asia Pacific dominates the global online food delivery services market, holding the largest share of 40.6% in 2024. The market was valued at USD 116,327.50 million in 2018 and is expected to reach USD 324,654.45 million by 2032, growing at the highest CAGR of 9.6%. Rapid urbanization, a booming middle class, and increasing smartphone penetration drive this robust growth. Countries like China, India, and Japan are witnessing substantial increases in online food orders due to busy lifestyles and the availability of affordable delivery options. Strategic partnerships and technology adoption further accelerate the region’s market expansion.
Latin America
Latin America accounts for 6.0% of the global market in 2024, with its market size growing from USD 17,964.50 million in 2018 to an anticipated USD 42,627.46 million by 2032, at a CAGR of 8.0%. The market is driven by rising internet penetration, increasing mobile app usage, and a growing young consumer base that prefers convenient food delivery solutions. Countries such as Brazil and Mexico are key contributors to the region's growth. Additionally, aggressive market entry by international delivery platforms and increasing investment in last-mile logistics are supporting the region's expanding online food delivery ecosystem.
Middle East
The Middle East holds a modest but growing share of 2.3% in 2024, with the market size rising from USD 7,421.40 million in 2018 to an estimated USD 14,968.01 million by 2032, growing at a CAGR of 7.1%. The increasing demand for international cuisines, rising urban populations, and the region's fast adoption of mobile technologies support market growth. Key cities such as Dubai, Riyadh, and Doha are experiencing a surge in online food orders due to high smartphone penetration and the convenience of app-based food delivery platforms. The market also benefits from a growing expatriate population.
Africa
Africa represents approximately 2.4% of the global market in 2024, with its size increasing from USD 5,183.20 million in 2018 to an expected USD 16,250.95 million by 2032, growing at a CAGR of 7.6%. Market growth is supported by the gradual improvement of internet infrastructure, growing smartphone adoption, and a rising middle-income population. Major urban centers such as Johannesburg, Lagos, and Nairobi are seeing increased demand for online food delivery, driven by convenience and changing dietary preferences. Despite infrastructure and logistical challenges, international food delivery platforms are steadily expanding operations in key African markets.
Market Segmentations:
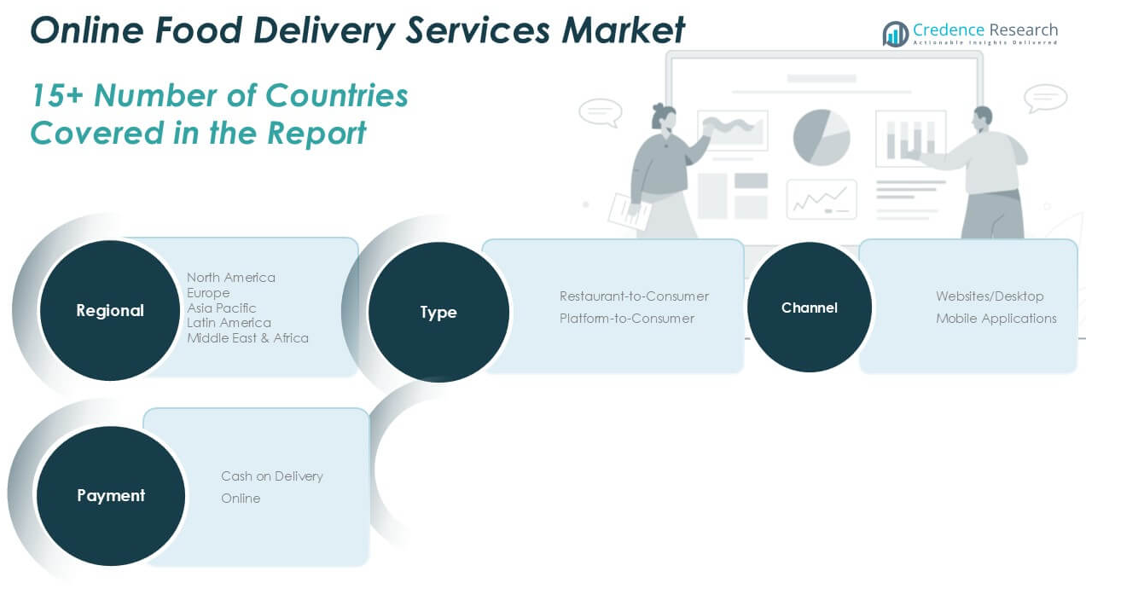
By Type
- Restaurant-to-Consumer
- Platform-to-Consumer
By Channel
- Websites/Desktop
- Mobile Applications
By Payment Method
- Fertility Clinics
- Hospitals & Other Settings
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The online food delivery services market is highly competitive, characterized by the presence of several established global and regional players striving to enhance their market positions through technological advancements, strategic partnerships, and geographic expansions. Leading companies such as Deliveroo PLC, DoorDash Inc., Delivery Hero Group, Just Eat Limited, Uber Technologies Inc., Swiggy, Zomato, and Amazon.com Inc. focus on expanding their customer base by offering diverse cuisines, faster delivery times, and attractive loyalty programs. Intense competition drives continuous innovation, including the integration of AI, real-time tracking, and user-personalized recommendations to improve service efficiency and customer experience. Companies are also investing in sustainable delivery practices and contactless payment options to meet evolving consumer preferences. Regional players like Rappi Inc. and Delivery.com LLC are gaining market traction through localized strategies and competitive pricing. This dynamic market landscape encourages continuous service enhancements and consolidation activities as companies vie for greater market share and customer loyalty.
Key Player Analysis
- Deliveroo PLC
- DoorDash Inc.
- Delivery Hero Group
- Just Eat Limited
- Uber Technologies Inc.
- Swiggy
- Zomato
- com LLC
- Yelp Inc.
- Rappi Inc.
- com Inc.
Recent Developments
- In December 2024, Swiggy announced the expansion of its 10-minute food delivery service, Bolt, to tier 2 and 3 cities, including Roorkee, Patna, and Nashik. This initiative aims to enhance market share by offering rapid delivery options in smaller urban areas.
- In November 2024, Wonder completed the acquisition of Grubhub, a leading food ordering and delivery platform with over 375,000 merchants and 200,000 delivery partners across the U.S. This acquisition, valued at USD 650 million, aims to integrate Grubhub's extensive network with Wonder's innovative food hall concept, enhancing customer access to a diverse range of dining options.
- In June 2023, GrubHub, a food ordering and delivery platform, announced the expansion of its collaboration with Amazon. As part of this extended partnership, Grubhub will offer a one-year complimentary Grubhub+ membership to Amazon Prime members in the United States. This initiative is designed to provide added value to Amazon Prime members who have previously enrolled in Grubhub+ since its introduction in July 2022. These members will now receive an extra 12 months of free Grubhub+ membership.
- In February 2023, Zomato, a prominent online food delivery service provider, unveiled its latest offering called Zomato Every day, replacing its previously introduced 10-minute delivery feature from last year.
- In December 2022, Ultrafast grocery delivery giant Getir agreed to acquire rival Gorillas in a transaction reportedly valued at USD 1.2 billion.
- In December 2022, DoorDash Canada launched new Partnership Plans to support restaurant partners better nationwide. All Canadian local restaurant owners have the choice of three different plans, with commission rates that vary based on the inclusion of services provided. Additionally, DoorDash includes DoorDash Storefront, an Online Ordering Software, in all partnership plans that enables any restaurant to turn their website into an eCommerce store.
Market Concentration & Characteristics
The Online Food Delivery Services Market shows moderate to high market concentration, with several global players holding significant shares and regional companies contributing to localized growth. It features rapid technological advancement, price sensitivity, and strong consumer preference for convenience and speed. The market structure supports intense competition where leading companies such as Uber Technologies Inc., DoorDash Inc., Swiggy, Zomato, and Deliveroo PLC consistently improve service quality, delivery times, and user engagement through mobile applications and loyalty programs. It relies heavily on mobile penetration, secure digital payment platforms, and evolving consumer behavior driven by busy lifestyles. The market favors players who can balance aggressive pricing with sustainable profitability, while smaller providers often compete by focusing on niche services or regional specialties. Partnerships with a wide range of restaurants, efficient logistics, and customer trust in online transactions strengthen competitive positioning. The Online Food Delivery Services Market requires continuous investment in technology, delivery infrastructure, and customer experience to retain market share and drive long-term growth.
Report Coverage
The research report offers an in-depth analysis based on Type, Channel, Payment Method, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The online food delivery services market is expected to continue growing steadily driven by increasing consumer demand for convenience.
- Mobile applications will remain the preferred ordering channel due to their accessibility and user-friendly features.
- Platform-to-consumer delivery models will maintain dominance by offering a wide variety of restaurant options on a single platform.
- Digital payment adoption will further accelerate, reducing reliance on cash transactions.
- Companies will increasingly integrate artificial intelligence and data analytics to offer personalized customer experiences.
- The Asia Pacific region will continue to lead the market, followed by North America and Europe.
- Demand for healthier, customized, and premium food delivery options will rise among urban consumers.
- Sustainable packaging and eco-friendly delivery practices will gain importance across all regions.
- Competition will intensify, pushing companies to invest in faster delivery networks and improved customer service.
- Partnerships between delivery platforms and restaurants will expand to offer exclusive menus and faster delivery options.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Smartphone Penetration and Internet Accessibility
The proliferation of smartphones and improved internet connectivity have made it easier for consumers to access online food delivery platforms, especially through mobile applications. This digital infrastructure expansion is particularly significant in emerging markets, enabling rapid user base growth.
Demand for Convenience and Fast Delivery
Busy urban lifestyles and the need for quick, hassle-free meal solutions are driving consumers to opt for online food delivery services. The ability to order from a wide variety of restaurants and receive food rapidly at home or work is a major factor fueling market expansion.
Expansion of Platform-to-Consumer Models
Leading platforms are aggressively partnering with restaurants and investing in logistics to offer consumers a broader selection and faster delivery. This model's scalability and efficiency attract both customers and restaurant partners, reinforcing its dominance in the market.
Integration of Digital Payment Solutions
The adoption of digital wallets, UPI, and contactless payment methods enhances transaction speed, security, and convenience for users. This shift towards cashless payments is supported by fintech innovation and government initiatives, further accelerating market growth.
Adoption of AI and Data Analytics
Online food delivery companies are leveraging AI and data analytics to personalize recommendations, optimize delivery routes, and predict customer preferences. These technologies improve operational efficiency and customer satisfaction, giving companies a competitive edge.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Online Food Delivery Services Market?
What are the key segments within the Online Food Delivery Services Market?
What are some challenges faced by the Online Food Delivery Services Market?
Who are the major players in the Online Food Delivery Services Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Platform-to-Consumer
- 1.2.2 Restaurant-to-Consumer
- 1.3 By Channel
- 1.3.1 Mobile Applications
- 1.3.2 Websites/Desktop
- 1.4 By Payment Method
- 1.4.1 Credit/Debit Cards
- 1.4.2 Digital Wallets
- 1.4.3 Cash on Delivery
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 383,671.74 million → 2032: USD 756,208.31 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Online Food Delivery Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Online Food Delivery Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Online Food Delivery Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Online Food Delivery Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Online Food Delivery Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Online Food Delivery Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Online Food Delivery Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Online Food Delivery Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 383,671.74 million → 2032: USD 756,208.31 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Online Food Delivery Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Platform-to-Consumer
- 12.3.6.2 Restaurant-to-Consumer
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Channel - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Mobile Applications
- 12.4.6.2 Websites/Desktop
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Payment Method - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Credit/Debit Cards
- 12.5.6.2 Digital Wallets
- 12.5.6.3 Cash on Delivery
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Online Food Delivery Services Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Online Food Delivery Services Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Online Food Delivery Services Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Deliveroo PLC
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 DoorDash Inc.
- 17.4 Delivery Hero Group
- 17.5 Just Eat Limited
- 17.6 Uber Technologies Inc.
- 17.7 Swiggy
- 17.8 Zomato
- 17.9 Delivery.com LLC
- 17.10 Yelp Inc.
- 17.11 Rappi Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

