
Market Overview
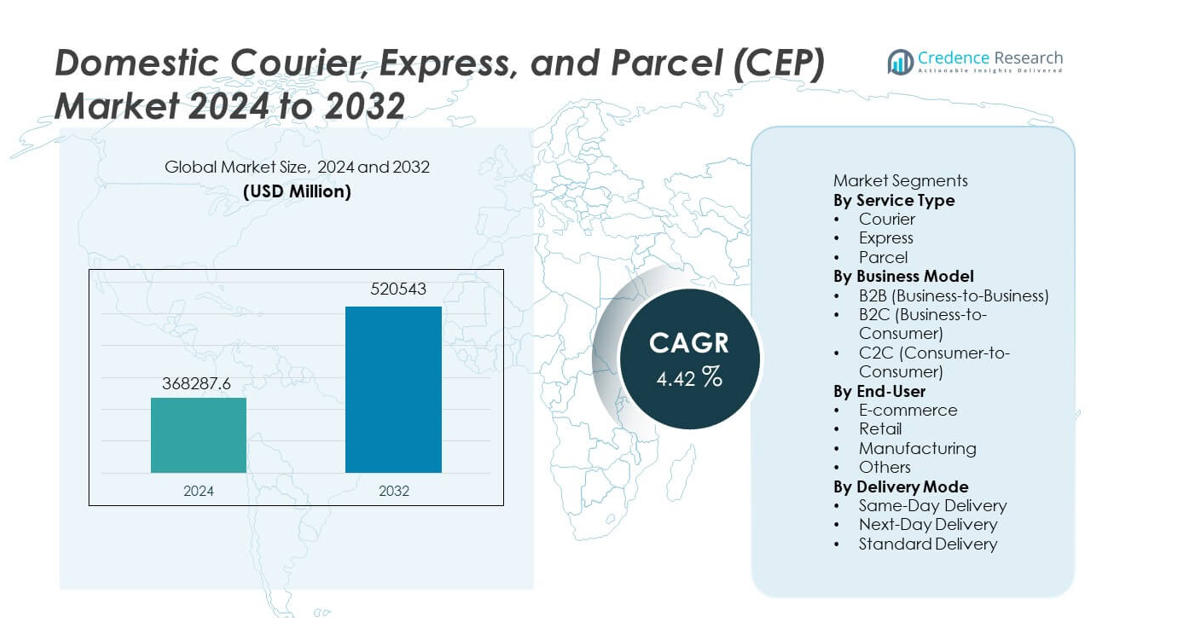
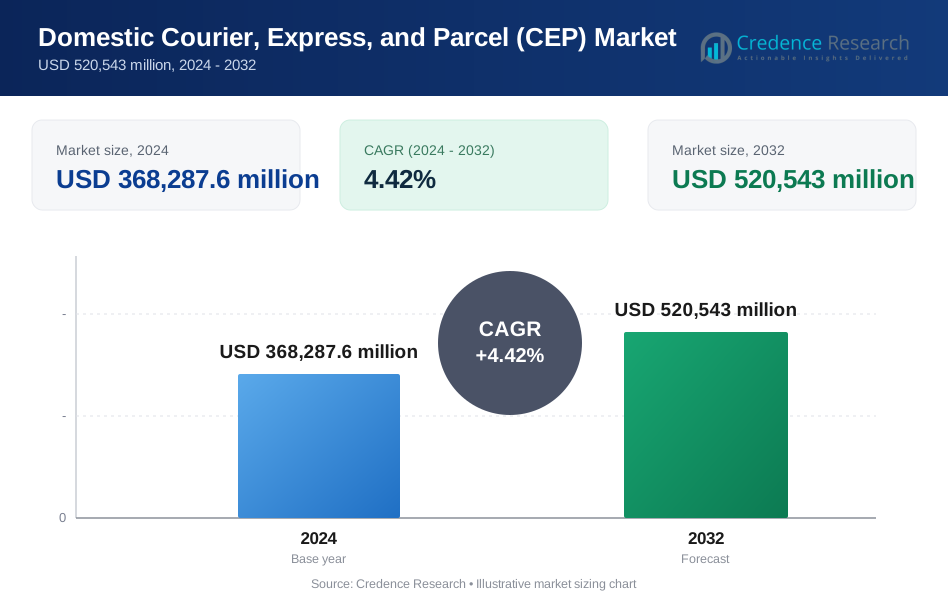
The Domestic Courier, Express, and Parcel (CEP) Market reached USD 368,287.6 million in 2024 and is projected to grow to USD 520,543 million by 2032, registering a CAGR of 4.42% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Domestic Courier, Express, and Parcel (CEP) Market Size 2024 | USD 368,287.6 million |
| Domestic Courier, Express, and Parcel (CEP) Market, CAGR | 4.42% |
| Domestic Courier, Express, and Parcel (CEP) Market Size 2032 | USD 520,543 million |
Top players in the Domestic Courier, Express, and Parcel (CEP) market include DHL, FedEx, UPS, USPS, Royal Mail, Japan Post, SF Express, YTO Express, Blue Dart Express, and Aramex, all of which focus on strengthening last-mile delivery, expanding automated sorting capabilities, and improving real-time tracking systems to meet rising parcel volumes. These companies enhance competitiveness through digital platforms, flexible delivery options, and partnerships with major e-commerce retailers. Asia Pacific leads the market with a 35% share, driven by strong online retail growth and dense urban demand, while North America and Europe follow due to advanced logistics infrastructure and high adoption of express delivery services.
Market Insights
- The Domestic CEP market reached USD 368,287.6 million in 2024 and will grow at a CAGR of 4.42% through 2032.
- Key drivers include rising online shopping volumes and demand for faster home deliveries, with the parcel segment leading at 57% due to frequent small-package shipments.
- Major trends highlight automation in sorting, AI-based routing, and contactless delivery innovations, while Asia Pacific holds the largest regional share at 35%, driven by rapid digital retail growth.
- Competitive activity intensifies as leading players invest in last-mile infrastructure, electric fleets, and digital tracking platforms to enhance reliability and efficiency.
- Market restraints include high last-mile delivery costs and capacity challenges during peak seasons, while the B2C segment maintains dominance with a 62% share, supported by strong e-commerce penetration.
Market Segmentation Analysis:
By Service Type
The parcel segment dominates this category with a 57% share, driven by rapid growth in e-commerce shipments, increased home deliveries, and rising adoption of subscription-based retail models. Parcels account for the largest volume due to frequent small-package orders across fashion, electronics, personal care, and household goods. Express services follow as customers demand faster delivery options and same-day fulfillment. Courier services maintain steady demand for time-sensitive business documents and high-value deliveries. Expanding last-mile infrastructure and rising consumer expectations for speed and reliability continue to reinforce the leadership of the parcel segment.
- For instance, DHL is a major logistics provider which delivers well over a billion parcels annually, supported by an extensive global network of operational facilities and a significant fleet of vehicles for pick-up and delivery.
By Business Model
The B2C segment leads the business model category with a 62% share, supported by strong online shopping activity and growing demand for fast and affordable home delivery services. Retailers rely heavily on CEP partners to manage high-volume, multi-location shipments. The B2B segment follows, driven by industrial supply chains, spare parts distribution, and inter-company logistics. The C2C segment grows steadily with higher use of peer-to-peer selling platforms and online marketplaces. The dominance of B2C remains firmly anchored in rising digital commerce, efficient last-mile networks, and flexible delivery options.
- For instance, Amazon Logistics managed 5,900 million parcel deliveries in 2023 across its B2C network covering more than 21 countries.
By End-User
E-commerce holds the largest share at 48%, reflecting strong reliance on efficient parcel networks to handle high-frequency, low-weight shipments. Increasing online penetration, promotional sales events, and diverse product categories fuel consistent volume growth. Retail follows as stores restock frequently and support omnichannel operations such as click-and-collect and store-to-home delivery. Manufacturing relies on CEP services for time-critical components and spare parts, maintaining steady demand. The “Others” category expands with growing use by healthcare, financial services, and small businesses. E-commerce remains the dominant force due to continuous digital adoption and evolving customer delivery expectations.
Key Growth Driver
Expansion of E-Commerce and Digital Retail
The rapid rise of online shopping drives significant growth in the Domestic CEP market as retailers depend on reliable parcel networks to fulfill frequent and diverse customer orders. Increasing smartphone usage, digital payment adoption, and aggressive discounting by e-commerce platforms boost shipment volumes. Consumers expect faster and more flexible delivery options, prompting logistics providers to upgrade last-mile infrastructure and expand distribution centers. Seasonal sales events and subscription-based purchases further elevate demand. This sustained surge in online retail strengthens the long-term growth outlook for domestic courier, express, and parcel services.
- For instance, India Post has the largest postal network in the world, with over one hundred and sixty thousand post offices nationwide, which has recently undergone a massive digital transformation to improve parcel services.
Advancements in Last-Mile Delivery Solutions
Technological advancements in routing optimization, real-time tracking, and automated sorting systems enhance speed and reliability in last-mile delivery operations. Logistics providers invest in electric vehicles, micro-fulfillment centers, and smart lockers to improve efficiency and reduce operational costs. Urbanization increases delivery density, creating opportunities for faster distribution. Delivery innovations such as crowdsourced fleets and contactless services also support customer convenience. These advancements help CEP providers manage rising volumes while maintaining high service standards, strengthening their competitive positioning in the domestic market.
- For instance, UPS has a global fleet with many thousands of alternative fuel and advanced technology vehicles which it continues to deploy across its worldwide delivery routes.
Growth of SMEs and Consumer-to-Consumer Shipments
A growing number of small and medium enterprises rely on CEP networks to reach customers across regions with fast and cost-effective delivery options. The rise of online marketplaces enables individual sellers and home-based businesses to participate in national commerce, increasing C2C shipment volumes. Flexible pricing models, digital booking platforms, and improved pickup services support wider adoption. SMEs benefit from better access to shipping infrastructure without needing in-house logistics capabilities. This expanding user base contributes significantly to overall market growth.
Key Trend and Opportunity
Increasing Adoption of Automation and AI in Logistics
Automation and AI reshape domestic CEP operations by improving sorting accuracy, reducing manual labor, and optimizing vehicle routing. AI-powered forecasting helps providers predict demand spikes and allocate resources efficiently. Automation in hubs accelerates parcel throughput, supporting next-day and same-day delivery commitments. As companies digitize operations, opportunities emerge for advanced tracking tools, automated customer communication, and predictive maintenance for fleets. These technologies enable cost reductions and service improvements, unlocking new efficiencies and competitive advantages for CEP players.
- For instance, SF Express deployed extensive robotic automation in its sorting centers and processed a substantial volume of parcels in supported by AI-driven routing.
Expansion of Sustainable and Green Delivery Models
Sustainability initiatives create strong opportunities as logistics companies adopt electric delivery vehicles, low-emission fleets, and eco-friendly packaging. Urban regulations encouraging green mobility accelerate this transition. Consumers increasingly prefer brands aligned with environmental responsibility, prompting CEP providers to integrate carbon-neutral shipping options and energy-efficient operations. Investments in renewable-powered warehouses and optimized routing help reduce carbon footprints. As sustainability becomes a competitive differentiator, companies capable of delivering greener services gain market share and stronger customer loyalty.
- For instance, Royal Mail deployed thousands of electric vans and operated all of its delivery offices using renewable power.
Key Challenge
Rising Operational Costs in Last-Mile Delivery
Last-mile delivery remains the costliest part of logistics due to fuel expenses, labor shortages, and complex urban delivery environments. Traffic congestion and dispersed delivery points increase time and resource requirements. Providers must balance speed, affordability, and profitability as consumer expectations tighten. Maintaining service reliability during peak seasons further strains operational budgets. Without effective route optimization and infrastructure upgrades, rising costs weaken margins and hinder scalability. Managing these pressures is critical for sustained performance in the Domestic CEP market.
Capacity Strain from High Delivery Volumes
Rapid growth in parcel volumes often overwhelms sorting hubs, transportation networks, and last-mile teams, especially during peak periods. Limited warehouse space and outdated logistics infrastructure create bottlenecks that delay deliveries. Sudden surges from e-commerce events can exceed capacity, reducing efficiency and service quality. CEP providers must invest continuously in automation, fleet expansion, and workforce training to keep pace with rising demand. Failure to scale infrastructure effectively can lead to customer dissatisfaction and lost business opportunities.
Regional Analysis
North America
North America holds a market share of 29%, driven by strong e-commerce penetration, mature retail networks, and high demand for fast home deliveries. Major CEP providers invest in automation, advanced tracking systems, and last-mile delivery innovations to meet rising expectations for same-day and next-day services. Growth in subscription commerce and cross-state shipping further strengthens market activity. The region also benefits from well-developed logistics infrastructure and widespread digital adoption. Increasing B2C parcel volumes and expanding fulfillment centers continue to support the region’s competitive position in the Domestic CEP market.
Europe
Europe accounts for a market share of 27%, supported by dense urban populations, strong regulatory frameworks, and advanced logistics networks. The region experiences steady demand across e-commerce, manufacturing, and retail sectors, with parcel shipments growing due to high consumer reliance on online shopping. Sustainability initiatives drive investment in electric delivery fleets and carbon-neutral solutions. Cross-border domestic-style operations within the EU further enhance parcel flows. The region’s focus on service reliability, automation, and green logistics supports continued growth and maintains Europe as a key market for CEP services.
Asia Pacific
Asia Pacific leads the market with a market share of 35%, driven by rapid urbanization, expanding digital commerce, and rising middle-class consumption. Countries such as China, India, Japan, and South Korea generate high parcel volumes due to large e-commerce ecosystems and increasing B2C shipments. Investments in last-mile delivery, smart warehouses, and automated sorting hubs accelerate efficiency. The region’s strong manufacturing base supports robust B2B and industrial shipments. Government support for logistics modernization and digital payment adoption further strengthens Asia Pacific’s leadership in the Domestic CEP market.
Latin America
Latin America holds a market share of 6%, supported by steady e-commerce expansion and growing demand for reliable parcel delivery across urban centers. Markets such as Brazil, Mexico, and Argentina show rising B2C activity driven by improved digital infrastructure and greater online retail participation. CEP providers invest in last-mile networks and regional distribution centers to overcome geographic and infrastructural challenges. While growth is gradual, increasing smartphone usage and enhanced payment systems support long-term expansion. Economic development initiatives further contribute to strengthening the logistics ecosystem.
Middle East & Africa
The Middle East & Africa region represents a market share of 3%, driven by rising e-commerce adoption and investments in logistics hubs, particularly in the UAE, Saudi Arabia, and South Africa. Growing consumer demand for faster delivery options and expansion of online retail platforms fuel parcel volume growth. Infrastructure improvements, free-trade zones, and urban development projects support logistics efficiency. However, market expansion is moderated by geographic diversity and uneven digital adoption. Continued investment in transportation networks and fulfillment centers is key to supporting long-term growth in the region.
Market Segmentations:
By Service Type
- Courier
- Express
- Parcel
By Business Model
- B2B (Business-to-Business)
- B2C (Business-to-Consumer)
- C2C (Consumer-to-Consumer)
By End-User
- E-commerce
- Retail
- Manufacturing
- Others
By Delivery Mode
- Same-Day Delivery
- Next-Day Delivery
- Standard Delivery
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape includes DHL, FedEx, UPS, USPS, Royal Mail, Japan Post, SF Express, YTO Express, Blue Dart Express, and Aramex. These companies compete by expanding delivery networks, improving last-mile efficiency, and leveraging technology for real-time tracking and automated sorting. Growing parcel volumes from e-commerce push providers to enhance capacity and adopt flexible delivery models such as same-day and contactless services. Strategic partnerships with online retailers strengthen market positioning, while investments in electric vehicles and sustainable logistics address environmental goals. Regional players gain traction through localized service capabilities and competitive pricing. As consumer expectations for speed and reliability intensify, companies focus on digital platforms, route optimization, and diversified service offerings to maintain an edge in the Domestic CEP market.
Key Player Analysis
- DHL
- FedEx
- UPS
- USPS (United States Postal Service)
- Royal Mail
- Japan Post
- SF Express
- YTO Express
- Blue Dart Express
- Aramex
Recent Developments
- In August 2024, J&T Express launched a new parcel delivery service called J&T SPEED in Saudi Arabia, marking a significant expansion of its offerings in the Middle Eastern logistics market.
- In February 2024, Emirates Post Group, rebranded as 7X, unveiled EMX, a new subsidiary dedicated to reshaping the courier, express, and parcel (CEP) industry in the UAE. Leveraging cutting-edge technologies, EMX aims to deliver unparalleled logistics solutions, prioritizing speed, reliability, and customer-centric services.
- In April 2023, Interroll launched the High Performance Conveyor Platform (HPP) specifically designed for the demanding courier, express, and parcel (CEP) market
Report Coverage
The research report offers an in-depth analysis based on Service Type, Business Model, End-User, Delivery Mode and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for domestic CEP services will rise as e-commerce penetration continues to grow.
- Same-day and next-day delivery options will expand as consumers expect faster fulfillment.
- Automation in sorting hubs and AI-powered routing will improve delivery efficiency.
- Electric and green delivery fleets will gain adoption as sustainability becomes a priority.
- Investments in last-mile infrastructure will increase to manage higher parcel volumes.
- Retailers and logistics firms will deepen partnerships to streamline delivery networks.
- Digital tracking and real-time visibility tools will become standard across all service tiers.
- Subscription commerce and recurring deliveries will contribute to consistent shipment growth.
- Regional logistics startups will gain traction with specialized and hyperlocal delivery models.
- Continued urbanization will drive higher delivery density, supporting optimized service routes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Domestic Courier, Express, and Parcel (CEP) market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Domestic Courier, Express, and Parcel (CEP) market projected to grow between 2025 and 2032?
Which Domestic Courier, Express, and Parcel (CEP) market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Domestic Courier, Express, and Parcel (CEP) market?
Who are the leading companies in the Domestic Courier, Express, and Parcel (CEP) market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 368,287.6 million → 2032: USD 520,543 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Domestic Courier, Express, and Parcel (CEP) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Domestic Courier, Express, and Parcel (CEP) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Domestic Courier, Express, and Parcel (CEP) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Domestic Courier, Express, and Parcel (CEP) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Domestic Courier, Express, and Parcel (CEP) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Domestic Courier, Express, and Parcel (CEP) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Domestic Courier, Express, and Parcel (CEP) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Domestic Courier, Express, and Parcel (CEP) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 368,287.6 million → 2032: USD 520,543 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Domestic Courier, Express, and Parcel (CEP) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Domestic Courier, Express, and Parcel (CEP) Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Domestic Courier, Express, and Parcel (CEP) Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Domestic Courier, Express, and Parcel (CEP) Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
