
Market Overview
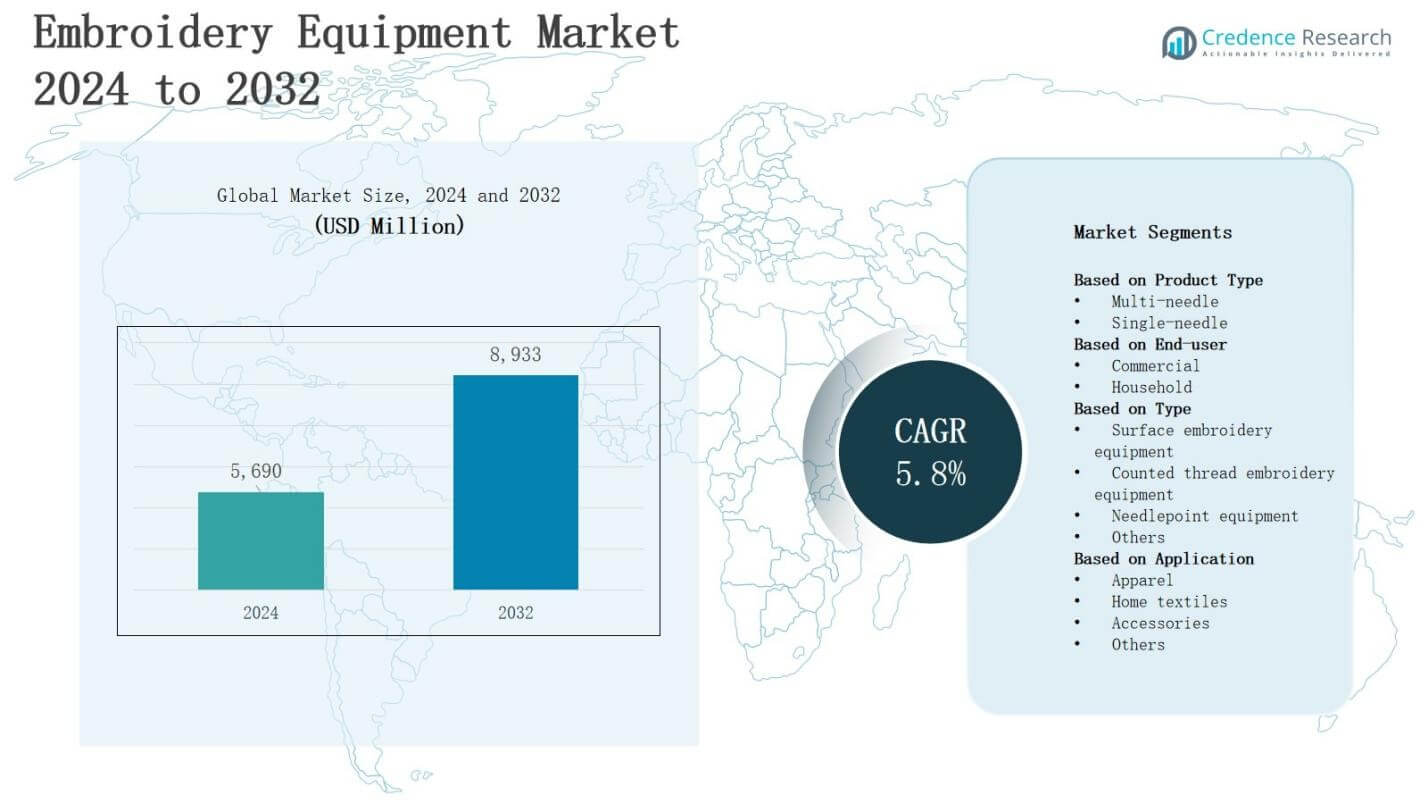
The embroidery equipment market is projected to grow from USD 5,690 million in 2024 to USD 8,933 million by 2032, registering a steady CAGR of 5.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Embroidery Equipment Market Size 2024 | USD 5,690 Million |
| Embroidery Equipment Market, CAGR | 5.8% |
| Embroidery Equipment Market Size 2032 | USD 8,933 Million |
The embroidery equipment market is driven by rising demand for customized apparel, home textiles, and promotional products, supported by the fashion industry’s emphasis on personalization and branding. Advancements in computer-aided design (CAD), automation, and multi-head machines enhance productivity, precision, and design flexibility, encouraging adoption across small enterprises and large-scale manufacturers. Growing popularity of e-commerce and online customization platforms further fuels demand for high-speed, user-friendly equipment. Trends include integration of digital technologies, such as AI-powered pattern recognition and IoT-enabled monitoring, along with increasing preference for eco-friendly threads and sustainable production practices, aligning the market with evolving consumer and industry requirements.
The embroidery equipment market demonstrates diverse geographical growth, with Asia Pacific holding the largest share driven by strong textile production in China, India, and Vietnam. Europe follows with demand from luxury fashion and sustainable embroidery practices, while North America benefits from technological adoption and branding needs. Latin America shows rising adoption through apparel exports, led by Brazil and Mexico. Middle East & Africa witness growth from traditional apparel and luxury markets. Key players include BERNINA, Brother, Feiya, HappyJapan, Janome, Ricoma, OC Oerlikon, SINSIM, and others.
Market Insights
- The embroidery equipment market is projected to grow from USD 5,690 million in 2024 to USD 8,933 million by 2032, registering a CAGR of 8%.
- Rising demand for customized apparel, home textiles, and promotional products fuels growth, with strong emphasis on branding and personalization.
- Advancements in CAD, automation, and multi-needle machines enhance productivity, precision, and design flexibility for both small and large manufacturers.
- Expansion of e-commerce and online customization platforms drives adoption of high-speed, user-friendly embroidery solutions across global markets.
- Growing shift toward eco-friendly threads, energy-efficient machines, and sustainable practices creates new growth opportunities.
- Regional distribution: Asia Pacific 35%, Europe 25%, North America 22%, Middle East & Africa 10%, Latin America 8%, reflecting diverse adoption patterns.
- Key players include BERNINA, Brother, Feiya, HappyJapan, Janome, Ricoma, OC Oerlikon, SINSIM, HEFENG, Mobase Sunstar, MAYA Mechanical and Electrical Technology, and Stitch It International.
Market Drivers
Rising Demand for Customized and Branded Products
The embroidery equipment market is propelled by the growing preference for customized apparel, promotional merchandise, and corporate branding. Businesses increasingly adopt embroidery solutions to enhance product differentiation and brand identity. Fashion houses, sportswear companies, and event organizers invest in advanced machines to deliver intricate logos and designs with precision. It strengthens customer engagement by offering personalization at scale. Expanding demand for school uniforms and workwear embroidery also reinforces consistent adoption across industries.
- For instance, luxury fashion brand Burberry, which uses specialized embroidery technology to create unique, personalized monograms on high-end apparel, strengthening its distinct brand presence.
Technological Advancements and Automation Integration
Continuous technological innovations fuel the embroidery equipment market by enhancing operational efficiency and design flexibility. Automated multi-head machines, CAD software integration, and computer-controlled stitching systems allow manufacturers to reduce production time while maintaining accuracy. It empowers small and large businesses to meet growing design complexity. IoT-enabled solutions further improve monitoring, predictive maintenance, and workflow management. Rising adoption of AI-driven design tools supports seamless customization while reducing labor dependency in production environments.
- For instance, Stratasys's J850 TechStyle printer enables direct-to-textile 3D printing, allowing complex, customized designs to be produced rapidly on fabrics.
Expanding E-Commerce and Online Customization Platforms
The embroidery equipment market benefits from the rapid expansion of e-commerce platforms offering on-demand customization services. Growing popularity of online ordering for personalized clothing, accessories, and home textiles increases demand for fast and efficient embroidery solutions. It enables businesses to process bulk and small-batch orders with equal ease. Direct-to-consumer brands increasingly rely on embroidery for value addition. Integration with digital storefronts enhances customer reach and supports global expansion of embroidery-focused businesses.
Sustainability and Eco-Friendly Production Preferences
Sustainability initiatives drive transformation in the embroidery equipment market, with manufacturers adopting energy-efficient machines and eco-friendly threads. Rising consumer preference for sustainable fashion motivates brands to invest in equipment supporting reduced waste and optimized resource utilization. It creates opportunities for innovative materials and recycling practices in embroidery. Government regulations on sustainable production further accelerate adoption. Growing awareness of environmentally responsible textiles positions embroidery equipment as a strategic tool in future-ready manufacturing.
Market Trends
Integration of Digital and Smart Technologies
The embroidery equipment market is witnessing strong adoption of digital and smart technologies that enhance design accuracy and workflow efficiency. AI-powered design recognition, IoT-enabled monitoring, and cloud-based storage of embroidery patterns are becoming standard features. It improves precision, reduces manual errors, and supports predictive maintenance for machines. Smart connectivity enables real-time order tracking and seamless communication between designers and operators. Growing demand for software-driven automation strengthens the shift toward technologically advanced embroidery solutions.
- For instance, Tajima’s Digitally Controlled Presser Foot (DCP), which measures fabric thickness with every stitch to minimize fabric flutter, decreasing defects by 40% during embroidery on delicate or heavy fabrics.
Growing Popularity of Multi-Head and High-Speed Machines
Manufacturers in the embroidery equipment market are focusing on multi-head and high-speed machines to meet bulk production requirements. These systems allow businesses to execute multiple designs simultaneously, reducing turnaround time significantly. It increases productivity while maintaining consistent quality across diverse materials. Fashion brands, uniform suppliers, and promotional merchandise companies prefer such solutions to meet rising customer expectations. Advancements in needle technology and faster stitching capabilities further expand applications in both industrial and small-scale operations.
- For instance, the SWF KE Dual Series embroidery machine features a 6-head setup that can operate either as a single 6-head unit or split into two independent 3-head machines, enabling simultaneous production of different designs and boosting productivity by 20-25%.
Sustainability and Eco-Friendly Material Utilization
A key trend in the embroidery equipment market is the growing adoption of eco-friendly threads, recycled fabrics, and energy-efficient machines. Brands increasingly prioritize sustainable embroidery practices to align with environmental goals and regulatory standards. It fosters the development of machines that minimize waste, optimize energy use, and support biodegradable materials. Rising consumer awareness about sustainable fashion accelerates this transition. Manufacturers focusing on green technologies gain competitive advantage while strengthening long-term value creation in textile industries.
Expansion of E-Commerce and On-Demand Customization
The embroidery equipment market benefits from the surge in e-commerce and on-demand customization platforms. Consumers prefer personalized apparel, accessories, and home décor, driving demand for user-friendly and high-speed embroidery machines. It supports small businesses, startups, and direct-to-consumer brands offering quick turnaround times. Integration of embroidery machines with digital storefronts enhances customer interaction and expands global reach. The growing trend of print-on-demand services further positions embroidery equipment as a central element of modern retail ecosystems.
Market Challenges Analysis
High Initial Investment and Maintenance Costs
The embroidery equipment market faces challenges from the high cost of advanced machinery and ongoing maintenance requirements. Small and medium enterprises often struggle to afford automated multi-head machines, which limits adoption. It creates barriers for startups aiming to enter the customization and apparel decoration segment. Regular servicing, replacement of components, and software upgrades further increase operational expenses. Price sensitivity in emerging economies slows down large-scale adoption. Limited financing options also restrict access for small businesses.
Skilled Labor Shortage and Technological Adaptation Barriers
Another significant challenge for the embroidery equipment market is the shortage of skilled operators capable of handling complex automated machines. Businesses face difficulties in training staff to work with CAD software, AI-based design tools, and IoT-enabled systems. It leads to delays, reduced efficiency, and errors in production processes. Resistance to adopting digital technologies in traditional embroidery hubs also restricts modernization. High learning curves associated with advanced systems discourage smaller firms. This slows overall industry transformation.
Market Opportunities
Rising Demand for Personalization and Premium Products
The embroidery equipment market holds strong opportunities in the growing demand for personalization across fashion, home textiles, and corporate merchandise. Consumers increasingly seek customized apparel, accessories, and décor, driving adoption of advanced embroidery solutions. It enables businesses to offer unique branding and premium finishes that enhance product value. Expansion of luxury fashion and high-end interior design further strengthens this demand. Small enterprises and online platforms benefit from affordable entry-level machines catering to niche personalization markets.
Adoption of Digitalization and Sustainable Practices
Opportunities for the embroidery equipment market expand with rising digitalization and sustainability trends. Manufacturers developing eco-friendly threads, energy-efficient machines, and waste-reducing technologies gain preference from environmentally conscious brands. It supports compliance with stricter global sustainability standards while opening access to premium markets. Integration of AI-driven design platforms and IoT-enabled monitoring enhances productivity and customer engagement. Emerging economies with growing textile industries create untapped markets where digital and sustainable embroidery solutions can achieve rapid adoption and growth.
Market Segmentation Analysis:
By Product Type
The embroidery equipment market is segmented into multi-needle and single-needle machines. Multi-needle equipment dominates commercial usage due to its ability to handle bulk orders with precision and speed. It offers flexibility for executing complex designs and is widely preferred by apparel manufacturers and branding firms. Single-needle machines cater to hobbyists and small businesses, offering affordability and ease of use. Rising consumer interest in DIY projects supports steady demand for single-needle systems.
For instance, the Brother PR680W, a 6-needle machine, offers adjustable embroidery speeds up to 1,000 stitches per minute and supports large embroidery fields, making it ideal for small business owners handling multi-color designs efficiently.
By End-user
Based on end-user, the embroidery equipment market is divided into commercial and household segments. Commercial users, including textile manufacturers and promotional merchandise companies, account for a significant share due to large-scale demand for customized apparel and branding. It ensures high productivity through automated and digital solutions. Household users represent a growing segment, supported by rising interest in home décor customization and personal fashion projects. Online tutorials and affordable machines drive greater adoption in domestic spaces.
- For instance, brands such as Bernina and Janome offer user-friendly, compact embroidery machines that are promoted through online tutorials, enabling hobbyists to create personalized fashion and décor items at home.
By Type
The embroidery equipment market is further categorized into surface embroidery equipment, counted thread embroidery equipment, needlepoint equipment, and others. Surface embroidery equipment holds strong demand in fashion and promotional textiles due to its versatility in design applications. Counted thread and needlepoint equipment are gaining traction among craft enthusiasts and niche markets. It supports artistic and decorative projects across apparel and home décor. The “others” category includes specialized machines addressing unique embroidery needs in emerging applications.
Segments:
Based on Product Type
- Multi-needle
- Single-needle
Based on End-user
- Commercial
- Household
Based on Type
- Surface embroidery equipment
- Counted thread embroidery equipment
- Needlepoint equipment
- Others
Based on Application
- Apparel
- Home textiles
- Accessories
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The embroidery equipment market in North America holds 22% share, driven by strong demand from fashion, promotional merchandise, and corporate branding sectors. The region benefits from advanced technological adoption, with businesses investing in multi-needle and automated machines to improve efficiency. It is supported by a mature apparel industry, sportswear brands, and rising interest in personalized consumer goods. Growth in small businesses and e-commerce platforms also drives household embroidery adoption. Sustainability initiatives further push demand for eco-friendly equipment.
Europe
Europe accounts for 25% share of the embroidery equipment market, supported by its strong luxury fashion, home décor, and textile manufacturing sectors. The region’s focus on sustainability accelerates demand for energy-efficient and eco-friendly embroidery solutions. It benefits from leading fashion capitals and a robust demand for high-quality customization. Advancements in design software and automation increase machine usage across commercial embroidery firms. Growing consumer preference for premium apparel and branded textiles supports consistent investment in embroidery equipment.
Asia Pacific
Asia Pacific leads the embroidery equipment market with 35% share, driven by its large-scale textile and apparel production base. Countries such as China, India, and Vietnam dominate exports of embroidered garments, creating high demand for multi-needle and high-speed machines. It benefits from low-cost manufacturing and expanding e-commerce platforms that boost personalized apparel. Rising disposable incomes encourage adoption of embroidery in household applications. Government support for textile modernization further enhances equipment sales in the region.
Latin America
Latin America holds 8% share of the embroidery equipment market, supported by growing apparel exports and rising adoption of customized fashion. Brazil and Mexico are major contributors, driven by expanding retail and promotional sectors. It experiences increasing demand for both commercial and household embroidery equipment. Cultural emphasis on decorative textiles sustains market expansion. Investments in small-scale textile enterprises and greater e-commerce penetration also fuel growth opportunities in this region.
Middle East & Africa
The embroidery equipment market in the Middle East & Africa accounts for 10% share, driven by growing demand in hospitality, luxury fashion, and traditional apparel segments. Gulf countries invest in modern embroidery equipment to support premium textile industries. It benefits from strong cultural demand for embroidered garments in markets such as UAE and Saudi Arabia. Africa’s emerging fashion sector also contributes to equipment adoption. Rising investments in retail and textile infrastructure strengthen long-term opportunities in this region.
Key Player Analysis
- Stitch It International
- HEFENG
- Brother Industries Ltd.
- Ricoma International Corp.
- MAYA MECHANICAL AND ELECTRICAL TECHNOLOGY CO. LTD.
- BERNINA International AG
- Janome Corp.
- HappyJapan Inc.
- SINSIM
- Feiya Group Co
- Mobase Sunstar Co. Ltd.
- OC Oerlikon Corp. AG
Competitive Analysis
The embroidery equipment market is highly competitive with players focusing on innovation, automation, and digital integration to strengthen their market position. Companies such as BERNINA International AG, Brother Industries Ltd., Feiya Group Co., HappyJapan Inc., HEFENG, Janome Corp., MAYA Mechanical and Electrical Technology Co. Ltd., Mobase Sunstar Co. Ltd., OC Oerlikon Corp. AG, Ricoma International Corp., SINSIM, and Stitch It International lead through product differentiation and global reach. It emphasizes high-speed multi-needle machines, CAD integration, and eco-friendly designs to meet diverse industry requirements. Strategic partnerships, regional expansions, and investments in sustainable manufacturing enhance competitiveness. Leading brands expand distribution networks across e-commerce and specialty stores to capture small-scale and household demand while maintaining dominance in commercial segments. The growing importance of e-commerce-driven customization compels firms to integrate user-friendly software and connectivity features. It creates opportunities for companies to expand into emerging economies where textile and fashion industries continue rapid development. This competitive environment fosters continuous innovation and keeps pricing strategies dynamic, strengthening growth opportunities across both developed and developing markets.
Recent Developments
- In July 2025, Janome introduced three new Memory Craft combo sewing and embroidery machines priced under US $2,000, designed to provide advanced features for both beginners and experienced users.
- In July 2025, ACP acquired EAC Limited, a Denver-based apparel and embroidery company, to enhance internal production capabilities and reduce dependence on third-party providers.
- In February 3, 2025, Oklahoma Embroidery Supply & Design (OESD) acquired Designs in Machine Embroidery (DIME) known for its innovative software, magnetic hoops, and accessories further strengthening its position as a one-stop provider for studios and retailers.
- In September 2023, HSW International Pvt. Ltd. (India) launched the HSW 5G embroidery machine, equipped with advanced safeguards against voltage fluctuations and a flashing needle position reminder for quick troubleshooting.
Market Concentration & Characteristics
The embroidery equipment market exhibits moderate concentration, with a mix of global leaders and regional players competing across commercial and household segments. Established companies such as BERNINA International AG, Brother Industries Ltd., Janome Corp., Ricoma International Corp., and OC Oerlikon Corp. AG dominate through innovation, advanced multi-needle systems, and strong distribution networks. Emerging firms like Feiya Group Co., HEFENG, SINSIM, and Stitch It International enhance competition by targeting niche markets with cost-effective solutions. It emphasizes continuous technological upgrades, including CAD integration, IoT-enabled monitoring, and AI-driven design tools to meet evolving consumer demand. The market is characterized by high product differentiation, strong reliance on automation, and increasing sustainability-driven investments. While larger firms maintain dominance in industrial-scale operations, smaller manufacturers capture opportunities in household and craft segments. The competitive landscape encourages innovation, regional expansion, and partnerships, making the market dynamic and growth-oriented with balanced opportunities for both established and emerging players.
Report Coverage
The research report offers an in-depth analysis based on Product Type, End-User, Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness stronger adoption of automated multi-needle machines across industrial embroidery applications.
- Digital integration with AI-driven design platforms will enhance customization speed and accuracy.
- IoT-enabled monitoring systems will become standard for predictive maintenance and workflow optimization.
- E-commerce platforms will drive higher demand for on-demand embroidery solutions globally.
- Sustainable production will expand with eco-friendly threads and energy-efficient machinery.
- Household embroidery machines will gain traction due to rising DIY and personalization trends.
- Emerging economies will offer growth opportunities with expanding textile and apparel industries.
- Luxury fashion and premium home décor sectors will continue driving demand for advanced equipment.
- Strategic partnerships and regional expansions will shape competitive positioning of global players.
- Continuous innovation in design flexibility and speed will define the long-term growth of the market.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Customization and Branding Demand
The increasing need for personalized apparel, promotional products, and branded merchandise is driving adoption of advanced embroidery equipment, as businesses seek to differentiate their offerings and strengthen brand identity.
Technological Advancements and Automation
Innovations such as CAD integration, multi-head machines, and IoT-enabled monitoring are enhancing productivity, precision, and design flexibility, making embroidery equipment more attractive to both large manufacturers and small enterprises.
Growth of E-commerce and Online Customization
The expansion of e-commerce and digital customization platforms is fueling demand for high-speed, user-friendly embroidery machines, enabling businesses to efficiently fulfill both bulk and small-batch personalized orders.
Sustainability and Eco-Friendly Practices
Rising consumer and regulatory focus on sustainable fashion is encouraging manufacturers to invest in energy-efficient machines and eco-friendly threads, opening new market opportunities and aligning with global sustainability trends.
Expansion in Emerging Markets
Rapid growth of textile and apparel industries in emerging economies, particularly in Asia Pacific, is boosting demand for embroidery equipment as manufacturers modernize production and tap into global export opportunities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Embroidery equipment market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Embroidery equipment market projected to grow between 2025 and 2032?
Which Embroidery equipment market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Embroidery equipment market?
Who are the leading companies in the Embroidery equipment market?
Which region commanded the largest share of the Embroidery equipment market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Surface embroidery equipment
- 1.2.2 Counted thread embroidery equipment
- 1.2.3 Needlepoint equipment
- 1.2.4 Others
- 1.3 By End-user
- 1.3.1 Commercial
- 1.3.2 Household
- 1.4 By Application
- 1.4.1 Apparel
- 1.4.2 Home textiles
- 1.4.3 Accessories
- 1.4.4 Others
- 1.5 By Product Type
- 1.5.1 Multi-needle
- 1.5.2 Single-needle
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,690 million → 2032: USD 8,933 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Embroidery Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Embroidery Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Embroidery Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Embroidery Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Embroidery Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Embroidery Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Embroidery Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Embroidery Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,690 million → 2032: USD 8,933 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Embroidery Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Surface embroidery equipment
- 12.3.7.2 Counted thread embroidery equipment
- 12.3.7.3 Needlepoint equipment
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-user - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Commercial
- 12.4.7.2 Household
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Apparel
- 12.5.7.2 Home textiles
- 12.5.7.3 Accessories
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Multi-needle
- 12.6.7.2 Single-needle
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Embroidery Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Embroidery Equipment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Embroidery Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Embroidery Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BERNINA International AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Brother Industries Ltd.
- 18.4 Janome Corp.
- 18.5 Ricoma International Corp.
- 18.6 Feiya Group Co.
- 18.7 HappyJapan Inc.
- 18.8 OC Oerlikon Corp. AG
- 18.9 SINSIM
- 18.10 HEFENG
- 18.11 Stitch It International
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

