
Verified claims now define sustainable clothing sales
The global sustainable fashion market was valued at USD 9.57 billion in 2025 and is projected to increase from USD 11.10 billion in 2026 to USD 42.22 billion by 2035, registering a CAGR of 16.00% during 2026–2035. Demand comes from brands that must prove recycled, organic or low-impact content as laws tighten, and from shoppers who accept secondhand and verified goods. Europe held the largest regional share, 38.0% in 2025, because EU rules now restrict the destruction of unsold clothing at large companies. Asia Pacific is the fastest-growing region at 17.39% a year, helped by certified factories in India, China and Bangladesh. Textile Exchange counted a record 132 million metric tons of fiber output in 2024, which shows how much conventional volume remains open to replacement. Commercially, the change is a move from small capsule ranges to multi-year offtake contracts for recycled fiber, including deals signed by lululemon and Inditex.
What counts as sustainable and ethical clothing in this market?
The market counts apparel, footwear and accessories sold as separately labeled lines under a verified environmental or ethical claim, not a brand's whole range because it uses preferred fibers, such as certified organic fiber, recycled content, upcycled material, bio-based leather or audited factory standards. Ethical clothing sits inside this definition when labor and sourcing claims are certified rather than self-declared. Buyers purchase through brand stores, multi-brand retail and online platforms.
General secondhand sales are tracked as a related channel rather than counted in full, since most resale value involves conventional garments. Conventional clothing that carries only unverified environmental wording is excluded from the count. The value chain runs from fiber producers and recyclers through certified mills and garment factories to brands, retailers and take-back or exchange programs.
Sustainable Fashion Market Insights
- The market stands at USD 9.57 billion in 2025 and reaches USD 42.22 billion by 2035, a 16.00% CAGR across 2026–2035 as disclosure and recycling rules bind.
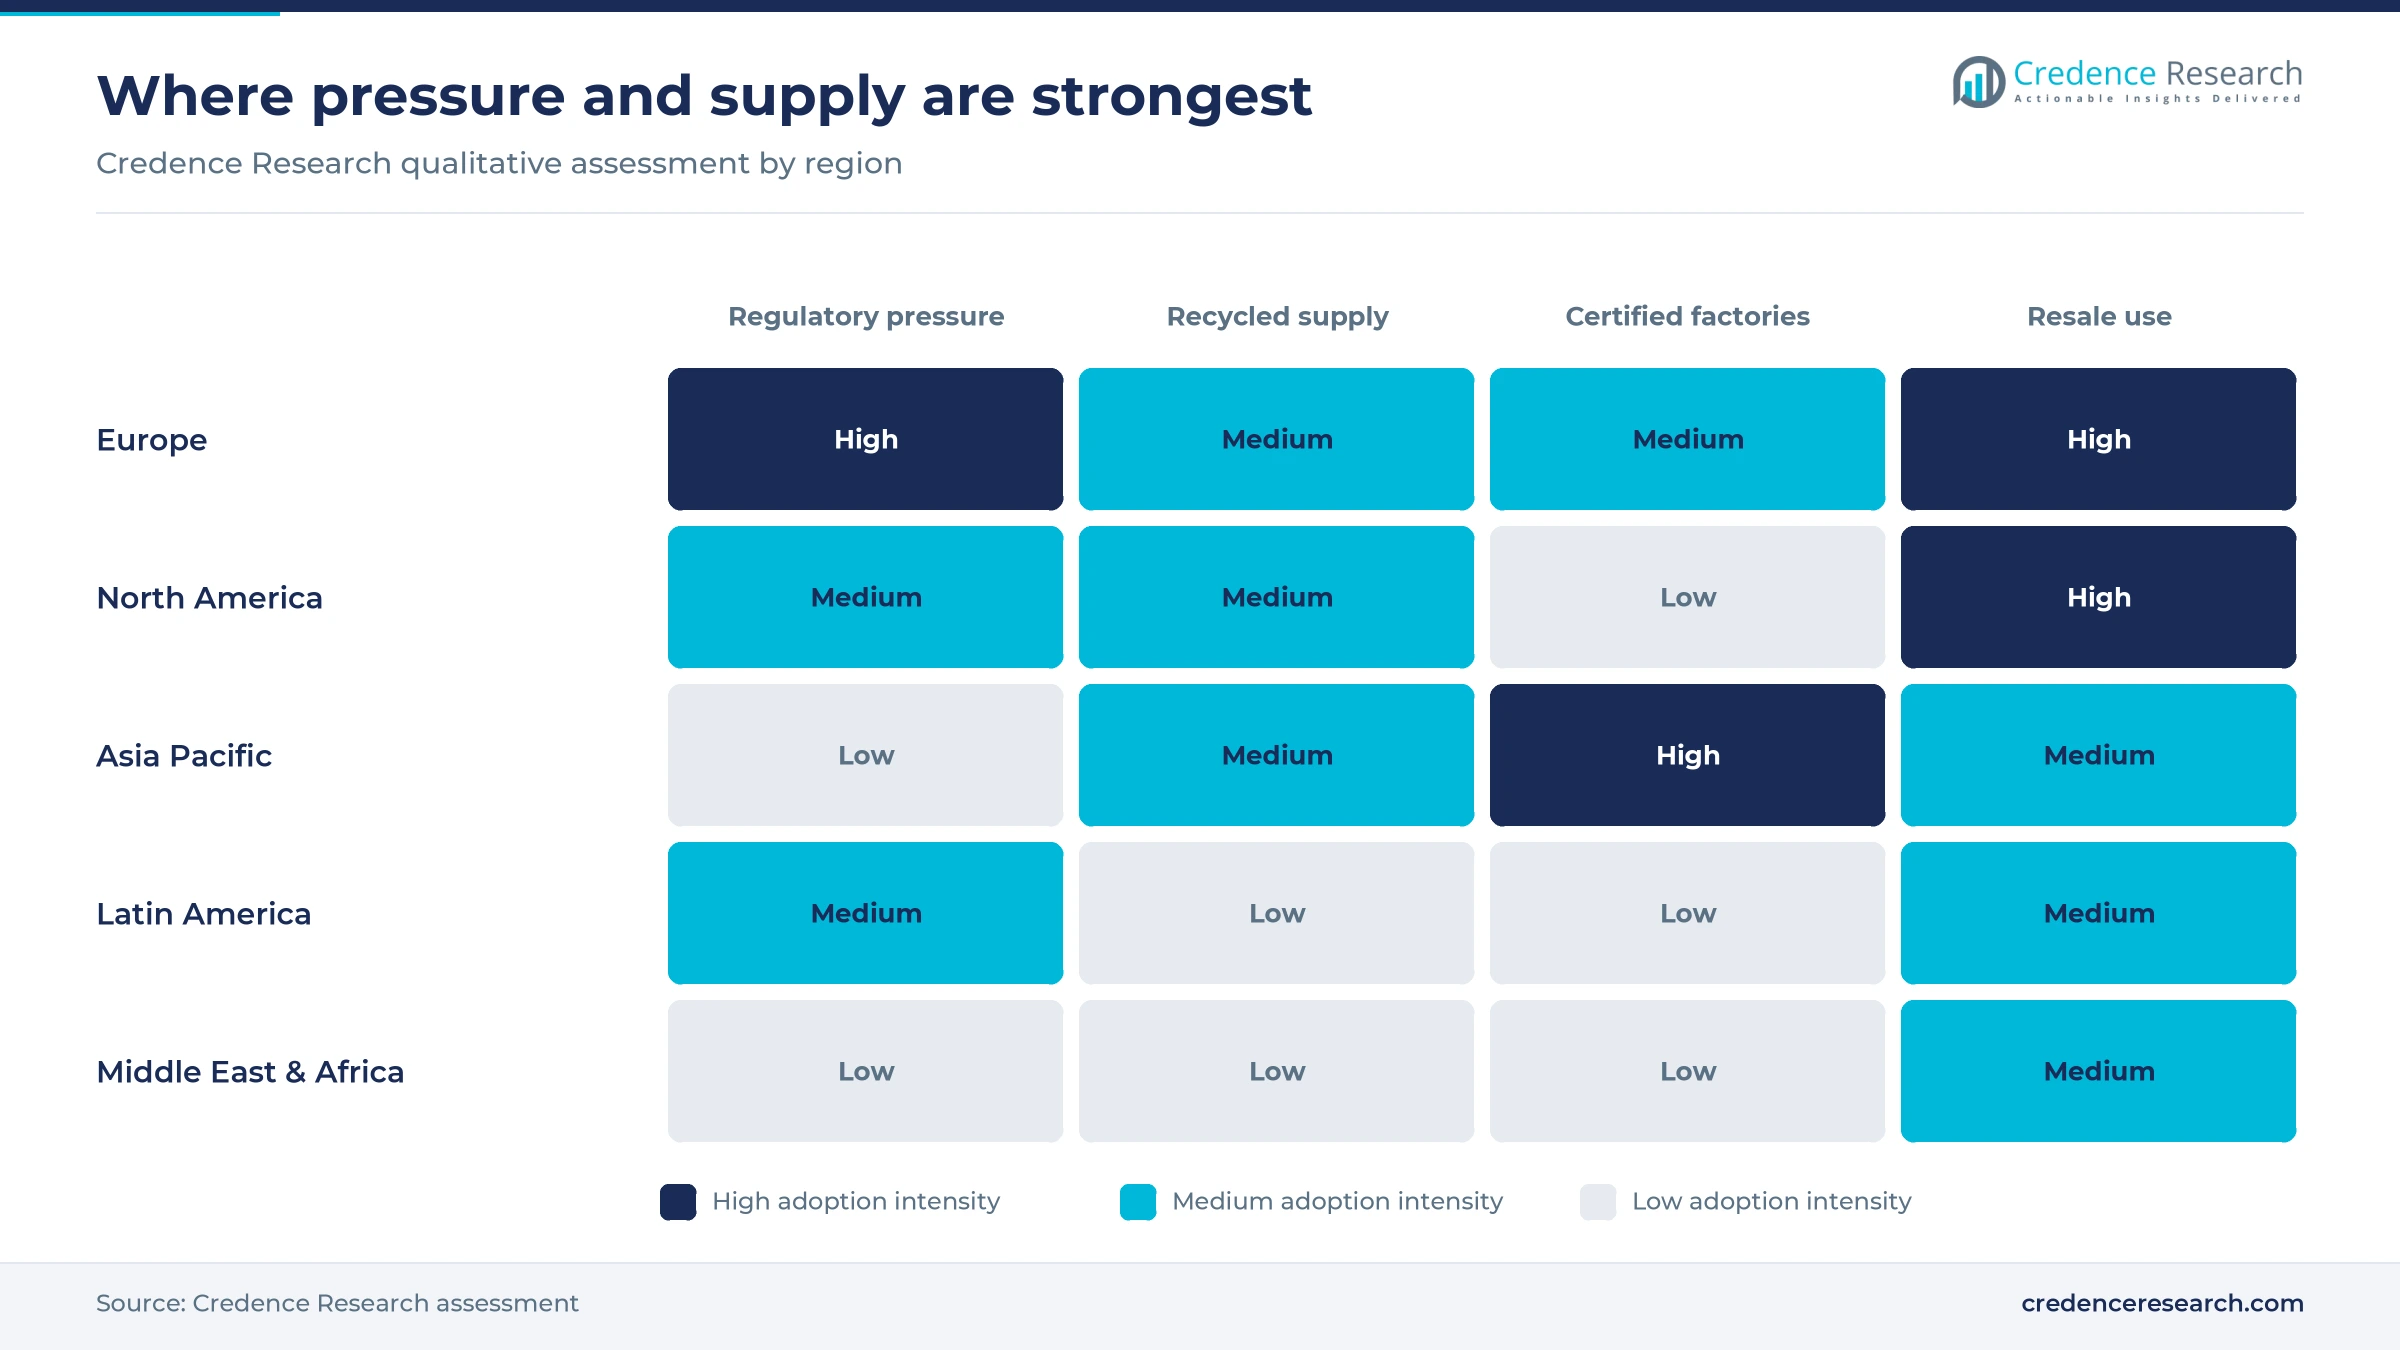
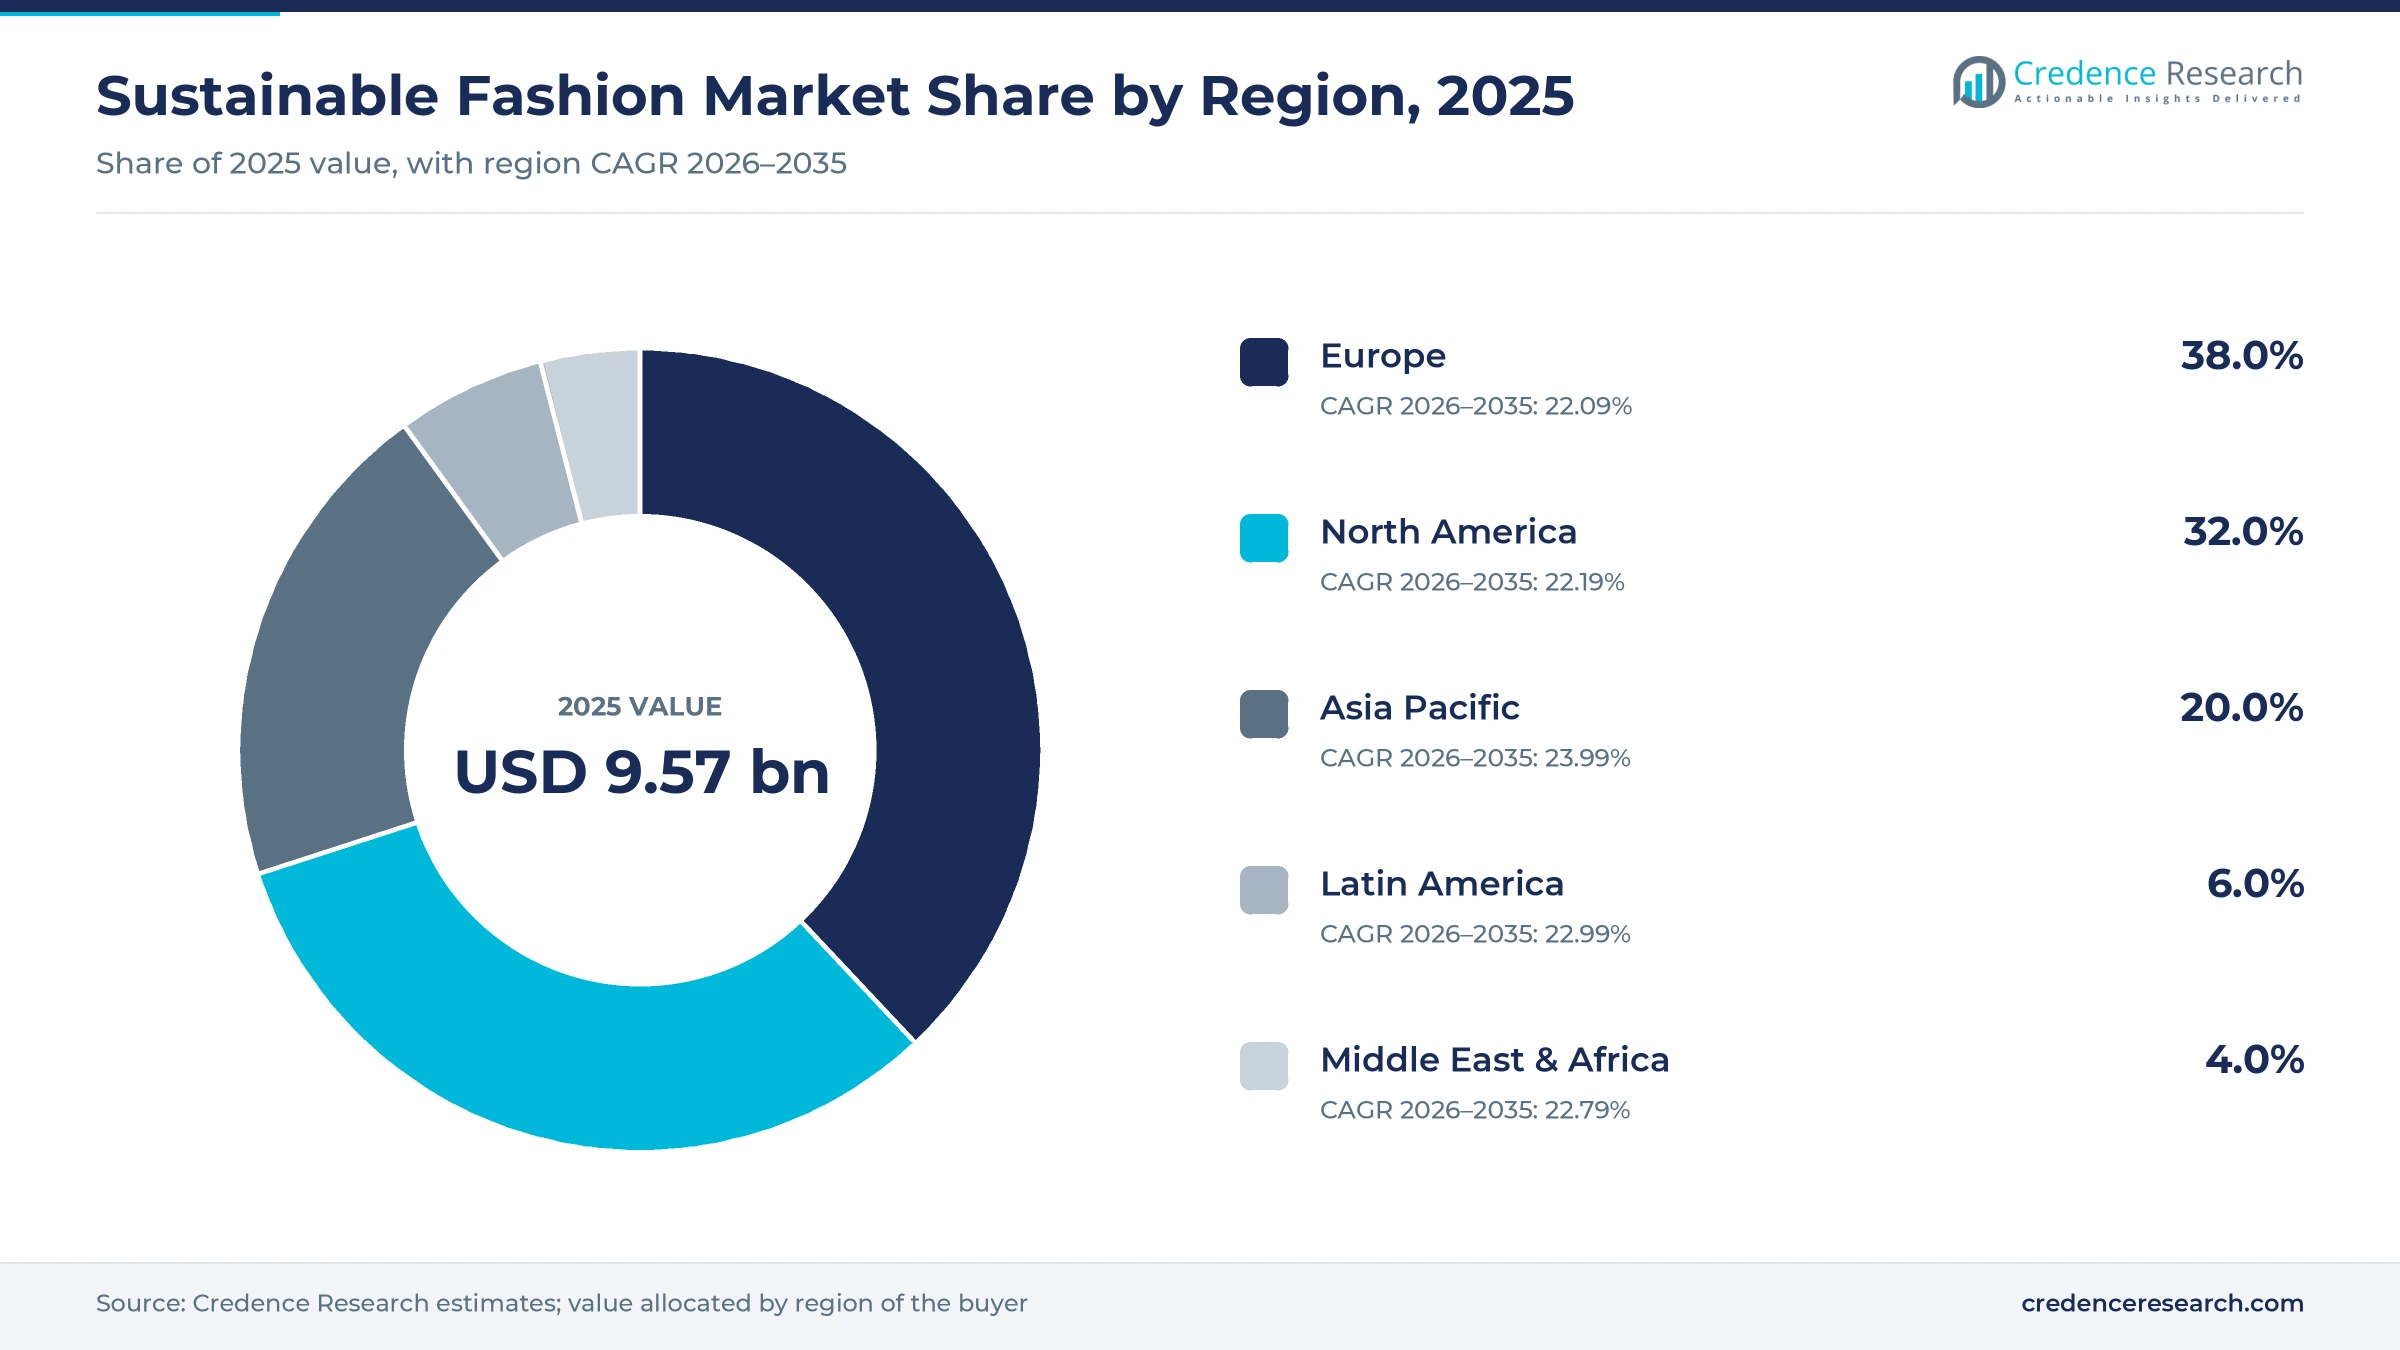
- Europe held the largest regional share at 38.0% in 2025, reflecting the destruction ban on unsold clothing at large companies from July 2026.
- Recycled Materials Apparel led product types with 37.0% in 2025 because recycled fiber already reaches about 7.6% of global fiber output.
- Enforcement began on July 19, 2026, when large companies in the EU lost the right to destroy unsold textiles and footwear.
- Competition centers on secured supply, shown by the 10-year offtake that lululemon signed with Samsara Eco on June 12, 2025, for recycled raw materials.
Recycled apparel leads while upcycled lines grow fastest
Why recycled apparel leads and upcycled lines grow fastest
Based on product type, the market is categorized into recycled materials apparel, organic clothing, vegan leather products, upcycled fashion, biodegradable fashion items and other items. Recycled Materials Apparel led with 37.0% of 2025 value because recycled fiber already has scale, with Textile Exchange reporting about 7.6% of global fiber as recycled in 2024. By contrast, organic cotton output was about 706,000 metric tons in 2023/24. Upcycled Fashion grows fastest at 18.19% a year as EU rules effective July 19, 2026, leave refurbishment and remanufacturing as lawful alternatives to destroying unsold clothes at large companies, HLC noted.
Casual ranges hold volume while activewear moves fastest
Based on design, the market is categorized into casual wear, activewear, accessories, footwear and formal wear. Casual Wear led with 46.0% of 2025 value because everyday ranges carry the largest certified volumes, as H&M Group reported 32% recycled materials for 2025 across its mass-market brands. Activewear grows fastest at 17.09% a year as adidas reported 155,309 of its 156,917 metric tons of polyester as recycled in 2025. Performance sportswear buyers are also securing future supply, since lululemon said Samsara Eco materials could support about 20% of its fiber portfolio.
Stores lead sales while online platforms gain share
Based on sales channel, the market is categorized into offline retail and online platforms. Offline Retail led with 58.0% of 2025 value because stores still anchor exchange and secondhand programs, and GreenTech Lead reported H&M Group resale and secondhand offerings across 26 markets, supported by 38 physical stores. Online Platforms grows fastest at 17.02% a year as ThredUp reported U.S. online resale growth of 23% in 2024, its second straight year of acceleration. That same 2025 report expects online resale to reach $40 billion by 2029, which keeps pressure on brands to sell verified lines digitally.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Recycled Materials Apparel | 37.0% | Upcycled Fashion | 18.19% |
| By Design | Casual Wear | 46.0% | Activewear | 17.09% |
| By Sales Channel | Offline Retail | 58.0% | Online Platforms | 17.02% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Binding rules and brand targets pull demand forward
EU destruction ban forces new routes for unsold stock
Mandatory rules are the strongest demand driver because they change what large sellers may legally do with unsold stock. According to legal firm HLC, the EU destruction ban took effect for large enterprises on July 19, 2026, and medium-sized companies follow on July 19, 2030. Between 4% and 9% of unsold textile products in the EU were being destroyed each year, so that stock now needs resale, repair or remanufacturing routes. Separately, the revised Waste Framework Directive entered into force on Oct. 16, 2025, and it sets common producer-pays rules for textiles. This pressure helps explain why Europe holds the largest regional share, as compliance costs reward products designed for reuse.
Fiber targets turn brand pledges into purchase orders
Published material targets translate directly into purchase volumes, which gives suppliers more certainty about future orders. H&M Group said in its March 2026 report that 91% of its materials were recycled or sustainably sourced in 2025, against a goal of 100% by 2030. Likewise, adidas reported 60% of materials as recycled or sustainably sourced renewable in 2025 and wants 10% of its recycled polyester to come from textile waste by 2030. Inditex committed 70 million euros in October 2023 to buy Ambercycle recycled polyester, and it targets 25% next-generation fibers by 2030. Because most of this feedstock begins as recycled PET, recycled materials apparel holds 37.0% of 2025 value.
Consumer demand holds when prices stay close to conventional
Consumer demand for sustainable fashion is real, but it depends on price and credible proof. IEMA reported a survey of more than 20,000 consumers in 31 countries and territories in which 80% would pay more for sustainably produced goods, averaging a 9.7% premium. However, this stated intent may not convert into spending under inflation pressure. ThredUp found that younger shoppers plan to spend 46% of their apparel budgets on secondhand over the next 12 months, against 34% for all consumers. In addition, 59% of consumers said they would seek cheaper options like secondhand if tariffs raise clothing prices. The Ethos quoted Coach chief executive Todd Kahn in January 2025 calling the green premium a fiction, because shoppers want it but will not pay more.
Producer-pays laws spread well beyond Europe
Producer-pays laws outside the EU widen the pool of companies that need verified collection and recycling plans. In California, covered producers had to join Landbell USA, the state-approved producer responsibility organization, by July 1, 2026, under SB 707, with full rollout expected in 2031. CalRecycle estimates Californians discard about 1.2 million tons of textiles each year, or roughly 3% of the material landfilled in the state. Chile extended its producer responsibility law to textiles in June 2025, so importers must now report clothing volumes. France also moved against low-priced imports when senators voted 337 to 1 in June 2025 for eco-score penalties on ultra-fast fashion. Together these measures raise the cost of conventional disposal, and California's law supports North America's 32.0% share.
Fiber recycling and resale reshape the supply base
Shift toward industrial fiber-to-fiber recycling plants
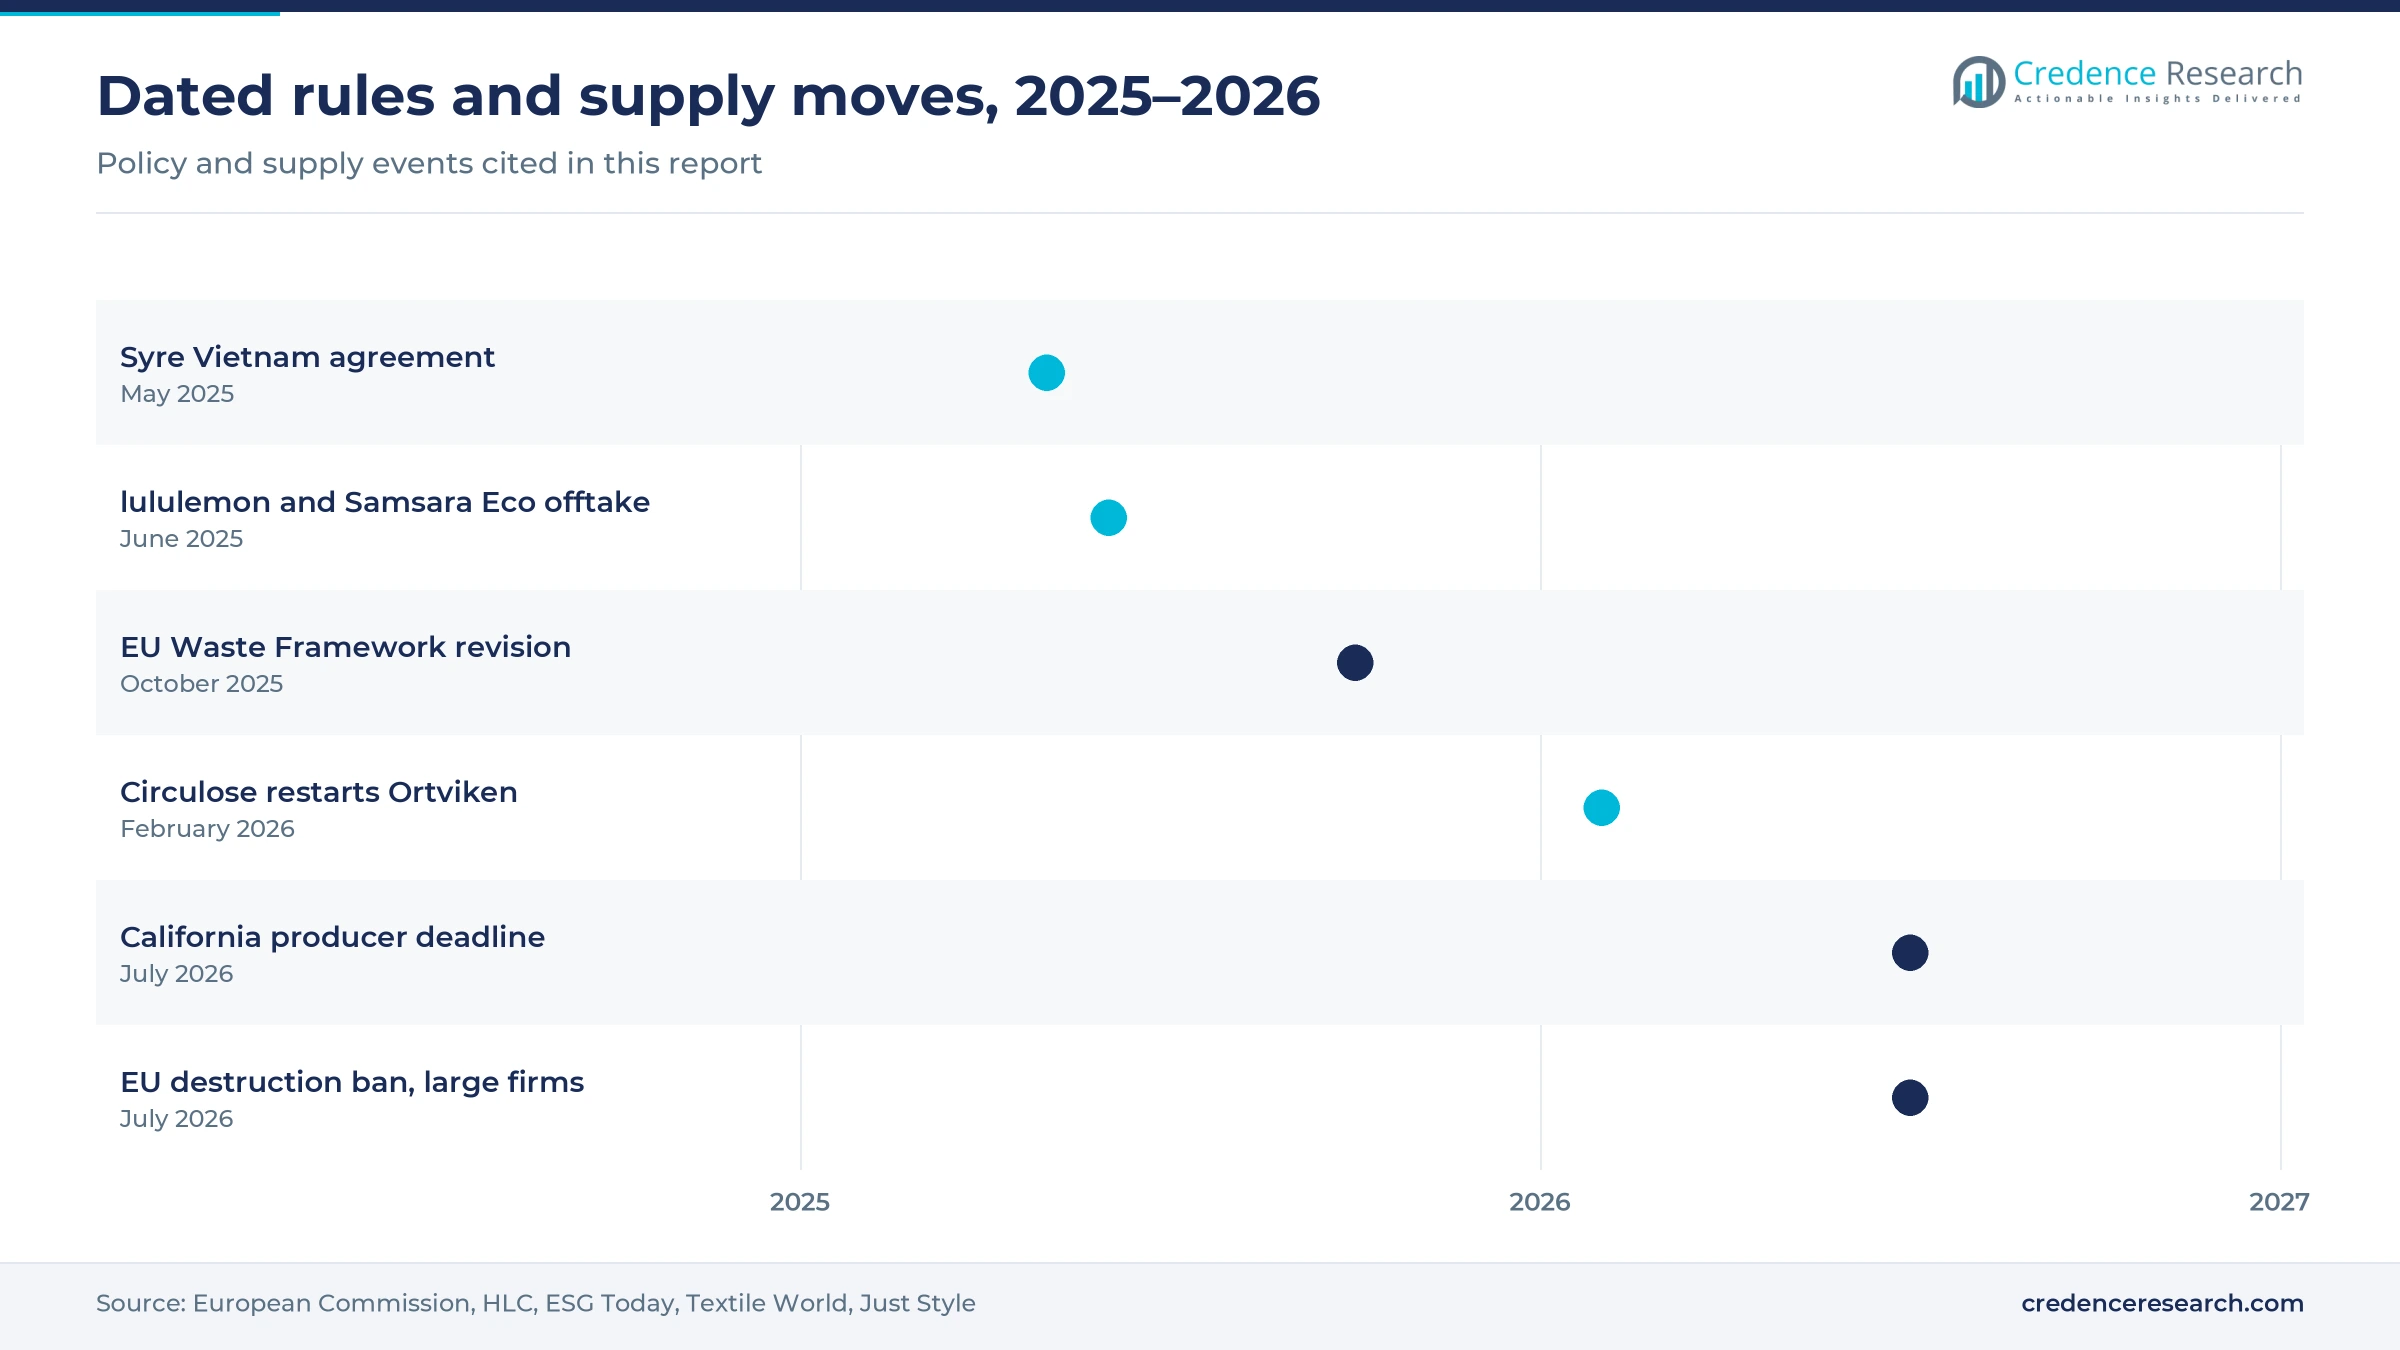
Recycling is shifting from pilot lines toward large industrial plants built around long supply contracts. Syre, founded with H&M backing in 2024, agreed with Vietnam's Binh Dinh Province, according to ESG Today in May 2025, to pursue a first plant designed for 100,000 to 250,000 metric tons of circular polyester a year. In Sweden, Circulose restarted commercial operations at Ortviken in February 2026 and expects new pulp production in the fourth quarter of 2026, with commitments from 11 brands, Just Style reported. Samsara Eco opened its first plant at Jerrabomberra in New South Wales on Sept. 3, 2025, and plans an international commercial facility in 2028. These projects matter because textile-to-textile recycling remains below 1% of all fibers, which leaves Recycled Materials Apparel with ample room to expand.
Rise of resale as a mainstream eco-conscious channel
Eco-conscious fashion resale is rising because shoppers now treat secondhand as a normal way to buy apparel. ThredUp estimated in March 2025 that U.S. secondhand apparel sales grew 14% in 2024, about five times faster than the broader clothing retail market. It also projects the U.S. market reaching $74 billion by 2029 and global secondhand apparel reaching $367 billion that year. Brands are responding with their own programs, including Coach (Re)Loved, whose exchanged goods will feed recycled leather production. This trend adds value to online platforms, which grow at 17.02% a year. However, only a part of that resale spending counts here, since the market measures verified sustainable lines and not every used garment. Retail executives also like resale because 54% consider it a steadier source amid tariff changes.
Opportunity in certified Asian factories for ethical sourcing
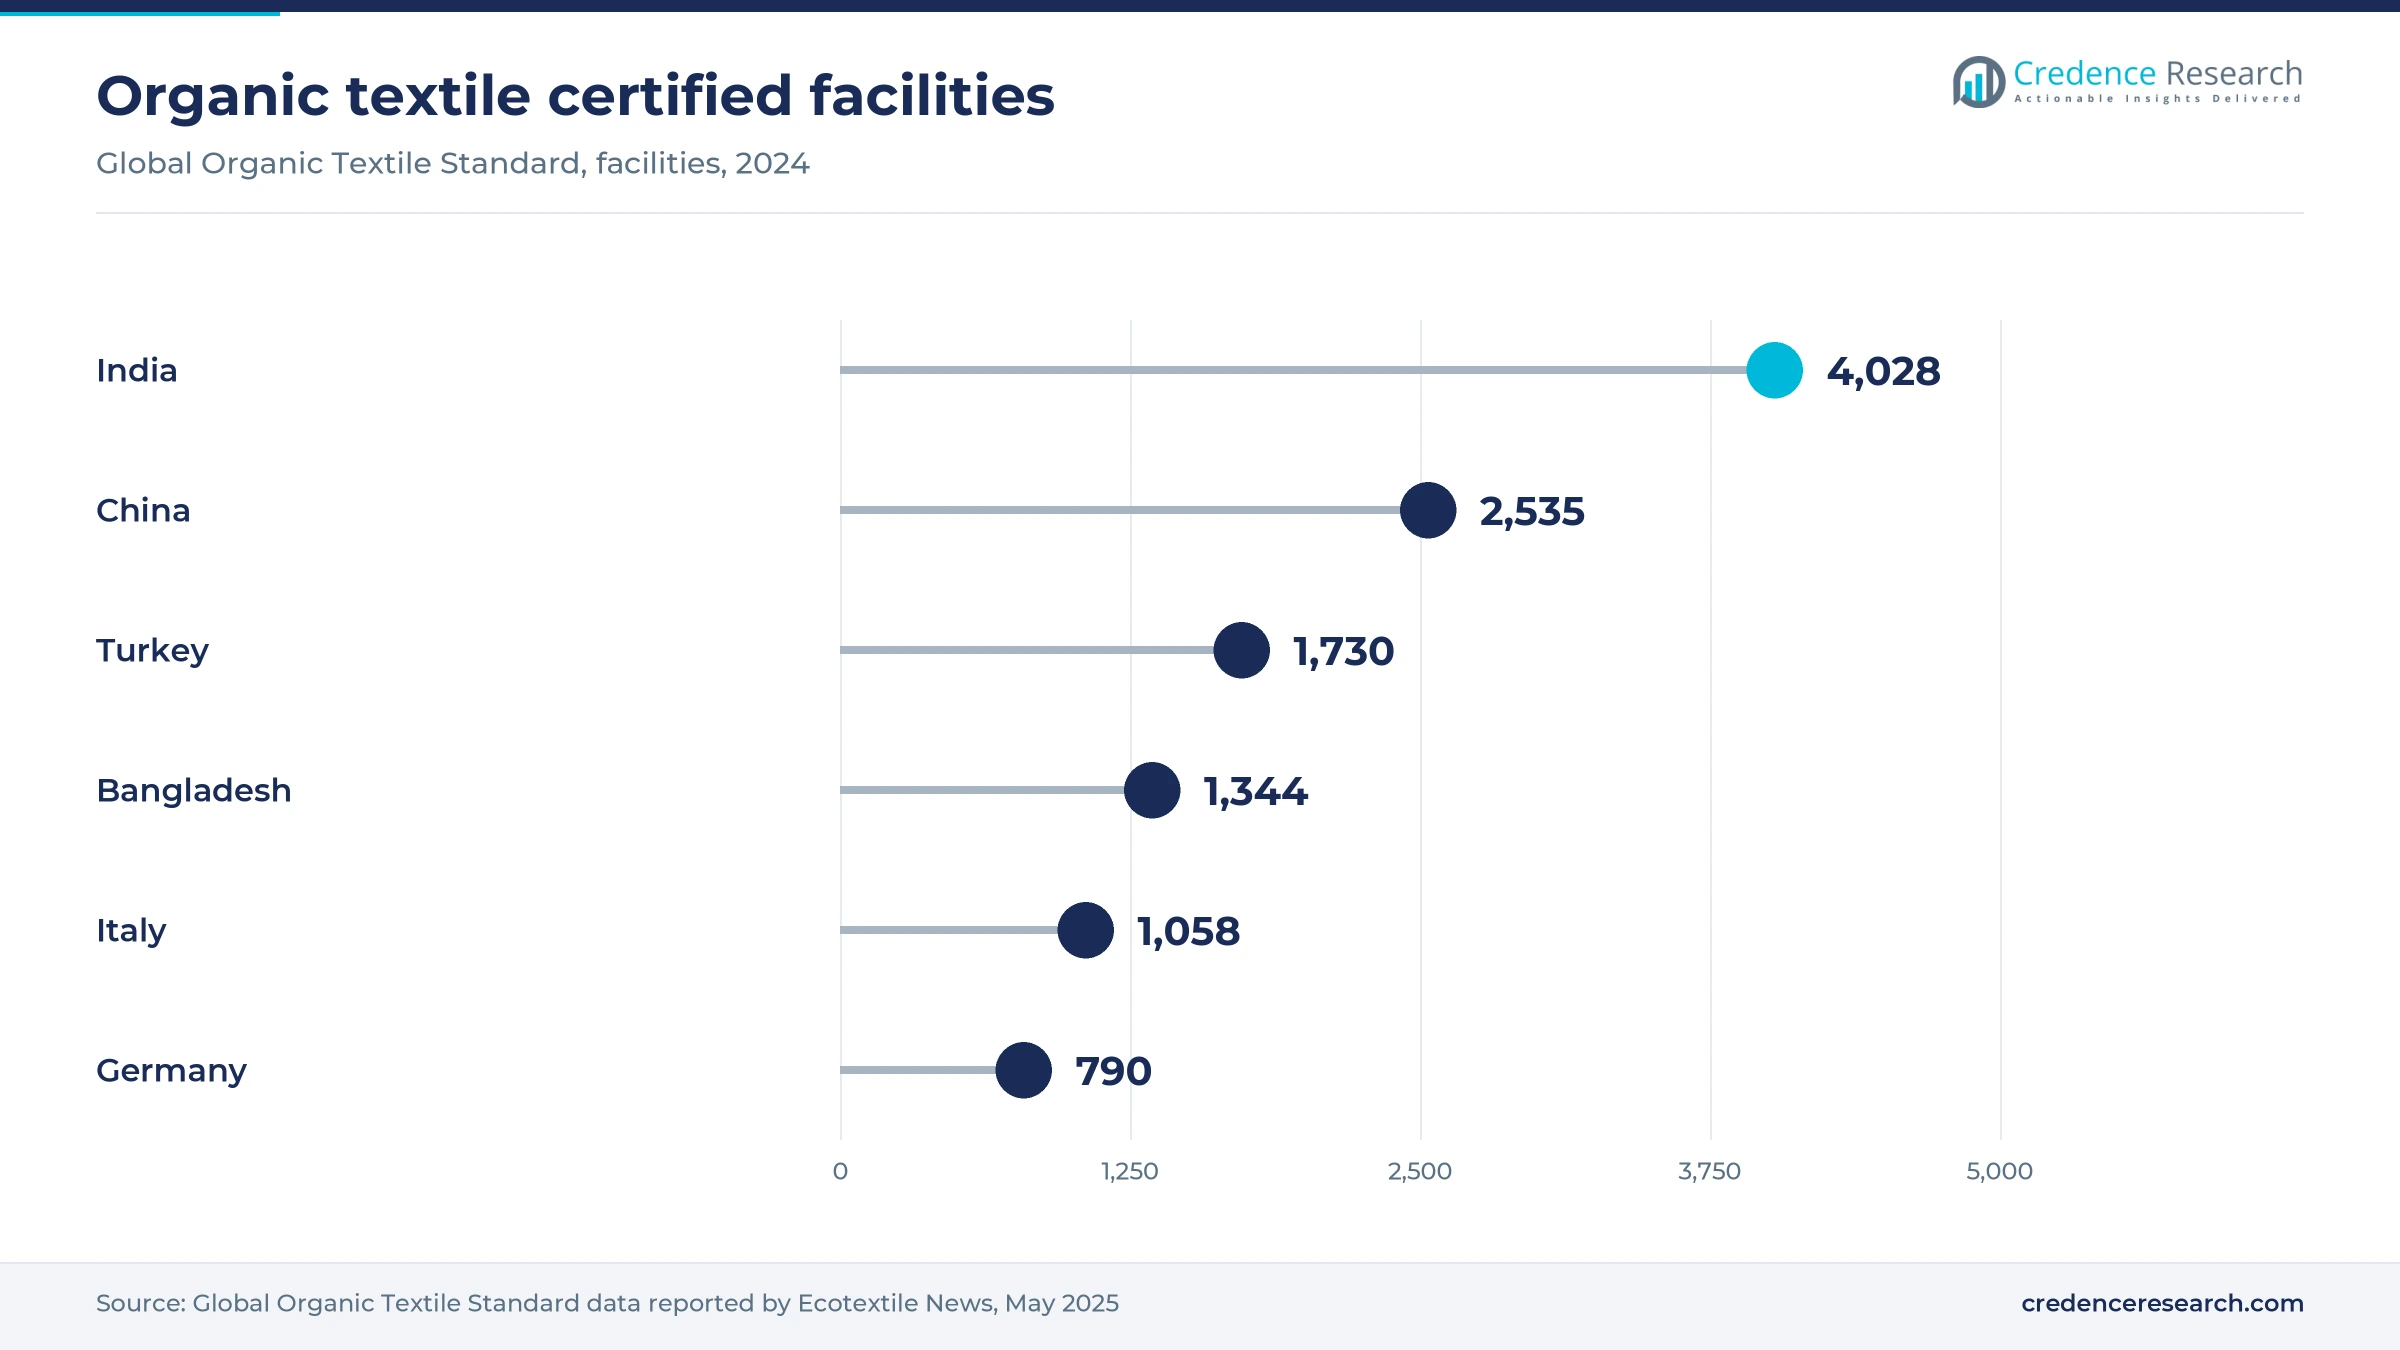
Certified factories in South Asia offer brands a clear opening to lower sourcing risk while meeting audit demands. Bangladesh added 38 LEED-certified garment factories in 2025, its highest annual total on record, according to the U.S. Green Building Council, for a total of 270 including 114 rated Platinum. Global Organic Textile Standard certifications reached 15,441 facilities in 2024, up 5%, Ecotextile News reported in May 2025, with India first at 4,028 and China second at 2,535. Certified output still lags demand, since Textile Exchange put certified virgin cotton at only about 34% in 2023/24. This base supports Asia Pacific as the fastest-growing region, and it offers an opening for ethical Asian brands that want to sell certified lines directly to international buyers.
Opportunity in bio-based leather for premium accessories
Premium accessories offer an opening for bio-based leather, since these buyers tolerate smaller runs and higher material costs. Stella McCartney reached a 91% sustainability rate in a spring 2025 collection that included a silver handbag made from fungi leather, The Ethos reported. Ganni phased out new animal leather in 2023 and moved to materials such as Vegea, a grape-waste leather. Italian developer Sqim combines agricultural residues with natural latex without petroleum, while MycoWorks has placed its Reishi material in furniture and small luxury projects. Suppliers of mycelium-based materials therefore have a narrower but more defensible route than mass apparel. Vegan leather products already hold a meaningful place in this report, and accessories stand to gain as luxury houses test alternatives through limited releases.
Feedstock, funding and emissions limit the pace
Bottle-based polyester masks a shortage of textile feedstock
Recycled claims rest on a narrow base, which limits how far brands can extend them. Textile Exchange put recycled fiber at about 7.6% of the 2024 total, with 6.9% from plastic bottles and less than 1% from recycled textiles. Polyester also rose to about 78 million metric tons, or 59% of output. Consequently, buyers with textile-waste targets compete for very little supply. Collection is part of the problem, since only about one-fifth of EU textile waste was separately collected in 2019. Common EU producer-pays rules should help ease this shortage as national schemes start.
Plant funding remains fragile for chemical recyclers
Chemical recycling needs large capital outlays, and recent setbacks show how exposed those projects remain. Eastman put its $1.2 billion Longview, Texas, recycling plant on hold for two years after losing a $375 million U.S. Department of Energy grant in May 2025, Recycling Today reported. Similarly, Circulose is still filling orders from stock made before the Renewcell insolvency, with new pulp due only in late 2026. Brands therefore face delayed volumes and tighter supply of recycled inputs. Long offtake contracts reduce this risk, though they tie up purchasing budgets for years.
Bio-based leather startups struggle to reach scale
Next-generation leather has suffered repeated failures, even with famous backers behind it. Bolt Threads ceased production of its Mylo mycelium material in 2023 despite support from Stella McCartney and Kering, according to La Conceria. Later, EcoCult writer Alden Wicker described Natural Fiber Welding and Modern Meadow as shuttered or stalled too. These failures leave designers with few dependable suppliers and uneven material quality. As a result, most bio-based products remain limited runs, and brands must qualify several suppliers to protect their collections.
Material emissions keep rising despite brand pledges
Progress on materials has not yet lowered absolute emissions, which exposes brands to greenwashing criticism. Just Style reported on Sept. 18, 2025, that the impact of material production rose about 6% from 2023 to 2024 and stood about 20% above 2019. That compares with a sector goal of a 45% cut by 2030. Polyester, mostly fossil-based, drives about 43% of that total impact. Recycled claims therefore remain open to challenge whenever total fiber volumes keep growing. Companies can respond by publishing audited material data and reducing virgin polyester tonnage.
Europe leads on regulation as Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Europe | 3.64 | 38.0% | 15.49% |
| North America | 3.06 | 32.0% | 15.59% |
| Asia Pacific | 1.91 | 20.0% | 17.39% |
| Latin America | 0.57 | 6.0% | 16.39% |
| Middle East & Africa | 0.38 | 4.0% | 16.19% |
Europe leads because compliance now shapes retail ranges
Europe held 38.0% of 2025 value and grows at 15.49% a year, with rules doing more than consumer preference to set the pace. Delegated Regulation (EU) 2026/296 set the permitted exceptions to the destruction ban, and Italy targets its own textile producer decree by the end of 2026, HLC noted. Demand for used clothing across the continent adds a further outlet for unsold and returned stock. Italy also counted 1,058 Global Organic Textile Standard facilities in 2024, and Germany had 790.
North America grows on California rules and resale demand
North America held 32.0% of 2025 global value, or USD 3.06 billion, and it grows at 15.59% a year. California anchors the policy case, as SB 707 requires an approved plan by July 1, 2030, ahead of 2031 rollout. Resale adds consumer momentum, since ThredUp expects U.S. online resale to grow 13% annually through 2029. However, federal support weakened in 2025 when the Energy Department revoked the Eastman grant, so recycled supply in the United States may arrive more slowly.
Asia Pacific grows fastest on certified manufacturing
Asia Pacific held 20.0% of 2025 value and is the fastest-growing region at 17.39% a year, because production and new recycling capacity sit there. India, China and Bangladesh together counted 7,907 Global Organic Textile Standard facilities in 2024, based on Ecotextile News figures. Fast Retailing has set a target of 50% recycled materials in Uniqlo clothing by fiscal 2030. Vietnam is also courting recycling investment through the Syre agreement, including a proposed pilot that would license imported recyclable textile material from nearby countries.
Latin America responds to the Atacama clothing waste problem
Latin America held 6.0% of 2025 value and grows at 16.39% a year, with Chile providing the region's clearest policy signal. About 123,000 tons of used clothing enter Chile each year, and over 90% of its textiles are imported, Environmental Health News reported in June 2025. These flows have created illegal dumps in the Atacama Desert, which prompted the textile extension of the producer responsibility law. Local brands and importers will therefore need traceable records, which favors verified lines over unmanaged used imports.
Middle East and Africa remains small but central to reuse
The Middle East and Africa held 4.0% of 2025 value and grows at 16.19% a year from a small base of branded sustainable sales. The region matters more for reuse than for new premium ranges, since Ghana's Kantamanto Market is the country's largest secondhand clothing market. A fire damaged the market in January 2025, and Ecotextile News reported in March that the Or Foundation and Vestiaire Collective urged fashion companies to help rebuild it. That appeal raises questions about who pays for reuse in importing countries.
Plants, offtakes and rules set the 2025–2026 pace
| Development | Status and market relevance |
|---|---|
| In May 2025, Syre signed an agreement with Vietnam's Binh Dinh Province to pursue its first large polyester recycling plant. | Investment decision pending; sets a template for Asian recycling hubs. |
| In June 2025, lululemon and Samsara Eco announced a 10-year offtake agreement for recycled raw materials. | Signed; could support about 20% of the lululemon fiber portfolio. |
| In October 2025, the revised EU Waste Framework Directive entered into force with common producer responsibility rules for textiles. | In force; sets common producer-pays rules for textiles. |
| In February 2026, Circulose restarted commercial operations at its Ortviken site in Sweden with commitments from 11 brands. | New pulp expected in the fourth quarter of 2026. |
| In July 2026, the EU ban on destroying unsold textiles and footwear took effect for large enterprises. | In force; medium-sized companies follow in July 2030. |
Recycling chemistry decides which claims can scale
- Enzymatic recycling uses engineered enzymes to break down nylon 6,6 and polyester, as Samsara Eco showed with lululemon sample garments in 2024.
- Chemical pulp recycling turns discarded cotton into dissolving pulp for viscose and lyocell, the route behind Circulose agreements with Aditya Birla and Tangshan Sanyou.
- Textile polyester depolymerization targets the 59% of fiber output that is polyester and aims to move recycled content away from plastic bottles.
- Bio-based leather relies on grape waste, agricultural residues or mycelium, which suit accessories better than high-volume garments today.
- Digital product passports will carry material and repair data under the EU ecodesign rules, with a 2027 to 2028 timeframe cited by HLC for textiles.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Large brands compete on secured recycled supply
Competition among large brands now centers on who locks in scarce recycled fiber, rather than on who runs the most visible campaign. H&M Group and adidas report material shares that smaller rivals struggle to match, and both are working on textile waste rather than bottle polyester alone. Inditex and lululemon use multi-year purchase agreements with Ambercycle and Samsara Eco to reserve future volume. In luxury, Prada switched its virgin nylon to regenerated Econyl by 2021, while Tapestry backs Gen Phoenix for Coach. Stella McCartney and Ganni compete on materials leadership at smaller scale, whereas Kering has backed bio-based experiments such as Mylo. Fast Retailing relies on long-term recycled material targets across its Uniqlo clothing. Barriers are rising, since regulated disclosure rewards companies that already have traceable supplier data and can absorb verification costs across their whole ranges.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| H&M Group | Mass-market brand owner | Reported 32% recycled materials for 2025 and backs Syre |
| Inditex | Mass-market brand owner | Buys Ambercycle recycled polyester under a 70 million euro deal |
| adidas | Sportswear brand | Reported 99% recycled polyester use in 2025 |
| Fast Retailing | Casual wear brand owner | Targets 50% recycled materials at Uniqlo by fiscal 2030 |
| lululemon | Activewear brand | Signed a 10-year offtake with Samsara Eco |
| Prada | Luxury house | Switched virgin nylon to regenerated nylon through Re-Nylon |
| Tapestry | Accessories group | Committed Coach to Gen Phoenix recycled leather purchases |
| Stella McCartney | Luxury label | Uses fungi leather and has never used animal leather |
| Ganni | Contemporary label | Phased out new animal leather in 2023 |
Supply contracts matter more than green marketing
Credence Research's view is that sustainable fashion is becoming a supply and compliance question more than a marketing one. The brands best placed by 2030 will hold contracted recycled fiber, audited factory data and working reuse programs, since regulators in the EU and California now ask for records rather than promises. Investors should treat stated consumer premiums with caution, because value still decides most purchases. The most assumption-heavy part of this outlook is the pace of textile-to-textile capacity, given recent funding setbacks, so growth above 16.00% would require faster plant completions than current evidence supports.
How Credence Research sized this market
The report uses 2025 as the base year, and the 2025 value was brought forward from the previous Credence Research estimate, then checked against public apparel and fiber data, and the forecast growth rate was re-estimated from that check. Market values come from the Credence Research model, and regional and segment splits are Credence Research estimates. Sources used are regulator publications, legal notices on EU law, company reports and releases, trade press and nonprofit industry data such as Textile Exchange. No interviews or surveys were conducted for this report, and third-party survey figures are attributed by name.
Compliance becomes the baseline for clothing by 2035
By 2035 the market reaches USD 42.22 billion, with verified content becoming a basic expectation for large apparel sellers rather than a premium claim. The EU ban widens to medium-sized companies in 2030, and California reaches full rollout in 2031, so two large consumer regions will have binding rules. Asia Pacific should gain share as recycling plants open near its garment factories. Upcycled lines and online sales should expand faster than the market overall. The main risk is that fiber-to-fiber capacity arrives late, which would keep most recycled claims dependent on plastic bottles for longer than brands expect.
Frequently Asked Questions
What is the sustainable fashion market size?
What share of the market is North America?
Which region leads the ethical clothing and sustainable apparel market?
What drives consumer demand for sustainable fashion?
Which product type is the largest?
Who are the key players in sustainable fashion?
What are the main sustainable fashion trends?
What limits growth in the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Recycled Materials Apparel
- 1.2.2 Organic Clothing
- 1.2.3 Vegan Leather Products
- 1.2.4 Upcycled Fashion
- 1.2.5 Biodegradable Fashion Items
- 1.2.6 Other Sustainable Fashion Items
- 1.3 By Design
- 1.3.1 Casual Wear
- 1.3.2 Activewear
- 1.3.3 Accessories
- 1.3.4 Footwear
- 1.3.5 Formal Wear
- 1.4 By Sales Channel
- 1.4.1 Offline Retail
- 1.4.2 Online Platforms
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 9.57 billion → 2035: USD 42.22 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sustainable Fashion Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sustainable Fashion Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sustainable Fashion Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sustainable Fashion Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sustainable Fashion Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sustainable Fashion Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sustainable Fashion Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sustainable Fashion Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 9.57 billion → 2035: USD 42.22 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sustainable Fashion Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Recycled Materials Apparel
- 12.3.7.2 Organic Clothing
- 12.3.7.3 Vegan Leather Products
- 12.3.7.4 Upcycled Fashion
- 12.3.7.5 Biodegradable Fashion Items
- 12.3.7.6 Other Sustainable Fashion Items
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Design - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Casual Wear
- 12.4.7.2 Activewear
- 12.4.7.3 Accessories
- 12.4.7.4 Footwear
- 12.4.7.5 Formal Wear
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Offline Retail
- 12.5.7.2 Online Platforms
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sustainable Fashion Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Sustainable Fashion Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Sustainable Fashion Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 H&M Group
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Inditex
- 17.4 adidas
- 17.5 Fast Retailing
- 17.6 lululemon
- 17.7 Prada
- 17.8 Tapestry
- 17.9 Kering
- 17.10 Stella McCartney
- 17.11 Ganni
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

