
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Environmental Testing Equipment Market Size 2025 | USD 1.8 Billion |
| Environmental Testing Equipment Market, CAGR | 6.5% |
| Environmental Testing Equipment Market Size 2032 | USD 2.7 Billion |
Market Overview
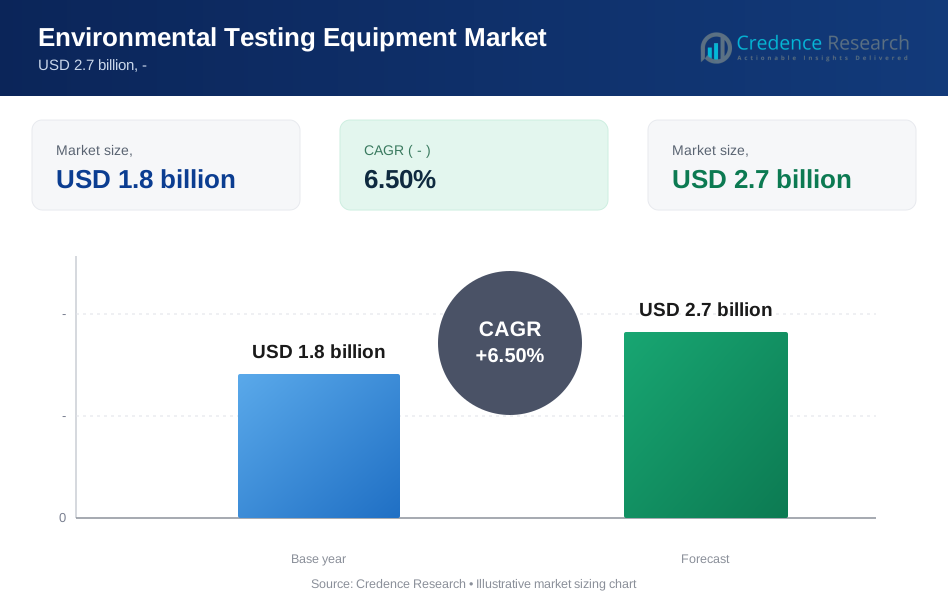
The environmental testing equipment market was valued at USD 1.8 billion in 2025 and is projected to reach USD 2.7 billion by 2032, registering a CAGR of 6.5% during the forecast period from 2025 to 2032. This growth trajectory reflects rising investment in environmental monitoring technologies, increasing regulatory enforcement, and broader industry adoption of advanced testing solutions across multiple end-use sectors.
Market expansion is being driven by the growing global emphasis on environmental sustainability and compliance with environmental standards. Governments, regulatory agencies, and industrial stakeholders are investing in technologies that support accurate monitoring of critical environmental parameters, including air quality, water quality, and soil contamination. As a result, environmental testing equipment has become increasingly important in supporting pollution control, environmental risk assessment, and long-term resource management strategies.
A key growth driver is the implementation of stringent regulatory frameworks across major industries. Environmental protection policies aimed at reducing emissions, improving waste management, and preserving natural resources have increased demand for sophisticated testing instruments capable of delivering precise and reliable analytical results. Sectors such as manufacturing, energy, agriculture, and chemicals are placing greater emphasis on regulatory compliance, which continues to accelerate adoption of air quality monitors, water testing systems, and soil analyzers.
Technological innovation is also reshaping the market landscape. The integration of IoT, artificial intelligence, and remote sensing technologies has improved the speed, accuracy, and efficiency of environmental testing processes. Automated and real-time monitoring systems are gaining wider acceptance as they enable continuous data collection and faster decision-making. In parallel, demand is increasing for portable and user-friendly testing equipment that supports on-site analysis and rapid compliance verification, particularly in applications requiring immediate operational response.
.
Market Drivers
Increasing Regulatory Compliance Requirements
The growing stringency of environmental regulations worldwide is a major force behind demand for environmental testing equipment, as governments are requiring tighter monitoring of emissions, contaminants, and compliance performance across industrial sites and public systems. In Europe, the revised Industrial Emissions Directive makes emission limits stricter, mandates electronic permitting, and allows penalties of at least 3 percent of a company’s annual EU turnover for the most serious infringements, while in the United States the EPA’s first legally enforceable PFAS drinking water standard requires public water systems to complete initial monitoring by 2027 and implement corrective solutions by 2029 where limits are exceeded.
These tougher rules are pushing companies in sectors such as industry, utilities, energy, and regulated manufacturing to invest in more advanced instruments for measuring pollutants, hazardous compounds, and environmental performance data with greater speed and accuracy. For instance, Thermo Fisher Scientific reported $44.56 billion in 2025 revenue and specifically lists environmental and process instruments within its analytical portfolio, showing how large global equipment makers are directly positioned to benefit as customers upgrade testing capabilities to meet rising compliance expectations.
As countries intensify enforcement and expand monitoring obligations, businesses are increasingly treating environmental testing equipment not as an optional purchase but as a core part of risk management, regulatory readiness, and operational continuity.
Growing awareness of environmental issues
Growing awareness of environmental issues is becoming a powerful driver of demand for environmental testing equipment worldwide, as governments, businesses, and communities place greater emphasis on measuring pollution, tracking ecological risks, and supporting more accountable sustainability practices. This shift is no longer limited to policy circles, with the UNDP and University of Oxford finding in the Peoples Climate Vote 2024 that 80 percent of people globally want stronger government action on climate change and 86 percent want countries to work together on the issue, showing how public concern is translating into stronger expectations for environmental monitoring and data-driven decision-making.
Companies are responding to this change by expanding solutions that help laboratories and industries test air, water, soil, and contaminants more accurately and efficiently, and Thermo Fisher Scientific reported $44.56 billion in 2025 revenue while identifying environmental and process instruments as part of its analytical portfolio for government, industrial, and research markets. For instance, Agilent said products carrying My Green Lab ACT labels already accounted for 40 percent of its instrument revenue and that it refurbished 5,400 instruments in one year, a 25 percent increase, reflecting how customer demand is increasingly favoring testing solutions that support both environmental compliance and broader sustainability goals.
Technological advancements and innovation
The use of environmental testing equipment is mostly driven by growing concerns and increased knowledge of environmental deterioration and contamination. As corporate responsibility and sustainability gain momentum, companies and communities are starting to pay greater attention to how their actions affect the environment. Due to increased awareness, there is a growing need for instruments and technology that allow precise accuracy through thorough examination of the surrounding circumstances. Environmental risk monitoring and mitigation are receiving greater attention as people, organizations, and governments become more aware of the long-term effects of pollution and climate change. This mentality change is driving the use of state-of-the-art environmental testing apparatus, which can deliver data and insights in real time, enabling stakeholders to make well-informed decisions with the goal of reducing their ecological footprint. As more businesses realize how important it is to invest in reliable testing solutions to solve environmental issues and promote sustainable practices, the market is growing.
Expansion of Industrial Activities and Infrastructure Development
The worldwide infrastructure boom and the rise of industrial activity are two major factors driving the environmental testing equipment market. There is an increasing need to track and control the environmental effects of new infrastructure projects and industry expansion. The use of environmental impact assessments in decision-making processes by governments and project stakeholders is growing, which calls for the deployment of sophisticated testing apparatus.
In order to guarantee adherence to environmental standards and solve issues with soil contamination, noise pollution, air and water quality, and the construction, manufacturing, and energy industries in particular, there is a growing demand for environmental testing solutions. As a result, the market is seeing a rise in the adoption of advanced environmental testing equipment by a variety of businesses aiming to strike a balance between environmental sustainability and economic growth.
Market segmentation
By Product
- GC-MS Instruments
- Mass Spectrometers
- Liquid Chrome
- ICP-MS Instruments
- LC-MS Instruments
- Gas Chromatography
- Chromatography Products: Autograph
By Platform:
- Conventional/Benchtop Platforms
- Handheld Platforms
- Portable/Mobile Platforms
By Application
- Water quality testing
- Organic Pollutants
- PFAS (poly- and perfluoroalkyl substances)
- Heavy Metals
- Solid Pollutants
- Microbial and Other Water Pollutants
By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Market Trends
The environmental testing equipment market is witnessing dynamic changes as it adapts to evolving regulatory standards, technological advancements, and increasing environmental awareness. Here are some key trends shaping the current landscape:
Rising Demand for Air Quality Monitoring Solutions:
More sophisticated air quality monitoring technology is in demand as worries about air pollution and its effects on public health increase. Modern equipment is being purchased by governments, businesses, and environmental organizations in order to detect and examine air pollutants such as nitrogen dioxide, particulate matter, and volatile organic compounds (VOCs). The capacity of real-time monitoring systems with cutting-edge sensors to deliver precise and timely data is making them more and more popular.
Integration of IoT and Sensor Technologies:
Environmental testing equipment is being revolutionized by the integration of sensor technologies and the Internet of Things (IoT). Monitoring systems are increasingly being equipped with smart sensors, which allow for automatic reporting, real-time analysis, and remote data collection. This improves environmental testing effectiveness while also enabling proactive decision-making based on useful information.
Focus on Water Quality Monitoring:
The necessity to combat water pollution and the rising shortage of freshwater resources have led to an increased emphasis on water quality on a worldwide scale. The use of cutting-edge equipment for assessing water quality has increased as a result. Monitoring wastewater discharges, evaluating the general health of aquatic ecosystems, and guaranteeing the safety of drinking water are all made possible by the use of technologies like spectroscopy, chromatography, and microbiological testing.
Emergence of Portable and Handheld Devices:
The demand for on-the-spot evaluations and field monitoring has led to a rise in the use of portable and handheld environmental testing equipment. Environmental specialists can conduct tests in a variety of places thanks to the portability and usability of these little instruments. In sectors where timely and accurate environmental data is essential, such as construction, agriculture, and emergency response, the trend towards portability is especially noteworthy.
Adoption of Advanced Analytical Techniques:
The market for environmental testing equipment is changing as a result of sophisticated analytical methods used for testing that are more thorough and accurate. Methods including next-generation sequencing, mass spectrometry, and chromatography-mass spectrometry are increasingly essential for accurately identifying and measuring pollutants. The necessity for trustworthy outcomes in accordance with strict environmental rules is what's driving this trend.
Growing Emphasis on Green Technologies:
Green technology development and promotion are becoming a growing priority for producers of environmental testing equipment. This covers the use of sustainable packaging, energy-efficient designs, and environmentally friendly materials in the production process. Customers are choosing ecologically friendly products, and the business is moving towards larger sustainability goals.
Key Market Restraints and Challenges
Regulatory Complexity and Compliance Burden
The environmental testing equipment market faces a significant challenge in the form of increasingly complex and stringent regulatory frameworks. Environmental standards across major economies are subject to frequent revisions, requiring manufacturers to continuously update product specifications to remain compliant. This environment increases the need for ongoing investment in research and development, product certification, and regulatory validation. As a result, compliance-related costs continue to rise, creating a notable barrier for new entrants and placing additional pressure on small and medium-sized manufacturers.
High Initial Capital Requirement
The high upfront cost of advanced environmental testing equipment remains a major restraint to broader market adoption. Sophisticated instruments designed for high-precision analysis often require substantial capital investment, particularly when equipped with automation, digital monitoring, and advanced analytical capabilities. In addition to purchase costs, end users must also account for installation, calibration, maintenance, and software upgrades. This high total cost of ownership can restrict adoption among budget-sensitive organizations, especially smaller enterprises and institutions in price-sensitive markets.
Technological Obsolescence
Rapid technological advancement presents an ongoing challenge for market participants. Continuous innovation in sensor technology, artificial intelligence, remote monitoring, and data analytics is shortening product life cycles and increasing the risk of technological obsolescence. Equipment that is currently effective may lose competitiveness as newer and more efficient systems enter the market. This requires manufacturers to maintain a consistent pace of innovation and compels end users to make periodic upgrade decisions, which may affect long-term purchasing confidence.
Raw Material Price Volatility and Economic Uncertainty
The market is also exposed to macroeconomic instability and fluctuations in raw material prices. Environmental testing equipment manufacturing depends on components such as metals, polymers, semiconductors, and electronic systems. Variability in the cost of these materials can increase production expenses, reduce margin stability, and complicate pricing strategies. In addition, broader economic uncertainty may delay capital spending by industrial end users, resulting in slower procurement cycles and reduced short-term demand visibility.
Competition from Alternative Technologies
The industry is increasingly facing competition from alternative environmental assessment methods, including remote sensing technologies, predictive modeling tools, and digital simulation platforms. These approaches are gaining attention due to their scalability, cost efficiency, and ability to support broader environmental analysis. Although conventional environmental testing equipment remains essential for precise measurement and regulatory compliance, substitute technologies may limit demand in selected applications. Manufacturers must therefore strengthen product differentiation through innovation, accuracy, and operational efficiency to maintain market relevance.
Strategic Implications
Overall, the environmental testing equipment market remains supported by strong long-term demand fundamentals; however, growth is moderated by regulatory pressure, high capital requirements, fast-paced technological change, supply-side cost volatility, and intensifying competitive alternatives. These challenges are expected to influence product development strategies, investment priorities, and market entry decisions across the industry.
Regional analysis of the market
The environmental testing equipment market is experiencing significant regional variations, with the United States emerging as a dominant force in North America. With a substantial market share of 24.6%, the US market is propelled by stringent environmental regulations and a mature industry landscape. Simultaneously, Canada is expected to contribute proportionately to the region's growth, benefiting from the overall positive trends observed in North America.
Moving to Europe, Germany stands out with a noteworthy market share of 6.1%. The country's advanced technological infrastructure and strong commitment to environmental standards position it as a key player in the European environmental testing equipment market. The combined market share of France, the United Kingdom, Italy, and Spain underscores the overall strength and influence of the European market, reflecting a collaborative approach to environmental sustainability.
In Asia Pacific, Japan commands a significant market share of 5.2%, driven by its commitment to technological advancements and environmental conservation. Meanwhile, China, as a major industrial hub, is expected to lead the market share in Asia Pacific, although specific figures are not provided. The contributions of India, Australia, South Korea, and the rest of the region collectively shape the diverse dynamics of the environmental testing equipment market in Asia Pacific.
Australia, with a modest market share of 0.4%, plays a distinctive role within the Asia-Pacific market, emphasizing its focus on environmental conservation and sustainable practices. In Latin America, specific market share figures are not given for Brazil and Mexico, but they are acknowledged as pivotal players. Brazil, with its abundant natural resources, is anticipated to hold a substantial market share, while the rest of Latin America contributes collectively to the region's environmental testing equipment market.
The Middle East and Africa region is experiencing gradual but steady growth, with specific market share data not provided. The potential for diverse contributions from countries in this region indicates emerging opportunities. Collaborations and partnerships are expected to play a crucial role in shaping market dynamics as environmental awareness continues to rise in the Middle East and Africa.
Recent Developments:
- In December 2025, Industrial Scientific announced the acquisition of Aeroqual, a New Zealand-based company focused on real-time environmental monitoring, to expand its sensing technology portfolio for air-quality and environmental applications.
- In November 2025, CSIR-NPL announced that the National Environmental Standard Laboratory had been established to test and recalibrate instruments used for air pollution monitoring, strengthening environmental measurement infrastructure in India.
- In December 2025, DeltaStarK highlighted a new development wave in environmental test chambers centered on AI integration, IoT connectivity, advanced sensors, and energy-efficient designs, signaling ongoing product innovation in the segment.
Key players in the environmental testing equipment market
- Eurofins
- Intertek
- Alex Stewart
- Bureau Veritas SA
- ALS Limited
- SGS SA
- Agilent Technologies, Inc.
- Thermo Fisher Scientific, Inc.
- Asurequality Limited
- Mérieux Nutrisciences Corporation
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Regulatory Compliance Requirements
Stricter environmental regulations worldwide are compelling industries to invest in advanced testing equipment to monitor emissions, contaminants, and ensure compliance, especially as penalties for violations become more severe.
Growing Awareness of Environmental Issues
Heightened public and governmental focus on pollution, climate change, and sustainability is driving demand for accurate environmental monitoring and testing solutions across sectors.
Technological Advancements and Innovation
Integration of IoT, AI, and advanced sensor technologies is enhancing the speed, accuracy, and efficiency of environmental testing, making real-time and remote monitoring more accessible and reliable.
Expansion of Industrial Activities and Infrastructure Development
Rising industrialization and infrastructure projects globally are increasing the need for environmental impact assessments and ongoing monitoring, fueling demand for sophisticated testing equipment.
Adoption of Portable and User-Friendly Testing Solutions
The need for rapid, on-site analysis and compliance verification in diverse environments is boosting the uptake of portable and handheld environmental testing devices.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What factors are driving the growth of the environmental testing equipment market?
Which specific areas within environmental testing are expected to see significant growth?
How will sustainability be addressed in the future of environmental testing solutions?
Are there any collaborative efforts expected in the market for research and development?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 GC-MS Instruments
- 1.2.2 Mass Spectrometers
- 1.2.3 Liquid Chromatography
- 1.2.4 ICP-MS Instruments
- 1.2.5 LC-MS Instruments
- 1.2.6 Gas Chromatography
- 1.3 By Platform
- 1.3.1 Conventional/Benchtop Platforms
- 1.3.2 Handheld Platforms
- 1.3.3 Portable/Mobile Platforms
- 1.4 By Application
- 1.4.1 Water Quality Testing
- 1.4.2 Air Quality Testing
- 1.4.3 Soil Contamination Analysis
- 1.4.4 Organic Pollutants Detection
- 1.4.5 Heavy Metals Analysis
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1.8 billion → 2032: USD 2.7 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Environmental Testing Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Environmental Testing Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Environmental Testing Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Environmental Testing Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Environmental Testing Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Environmental Testing Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Environmental Testing Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Environmental Testing Equipment Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1.8 billion → 2032: USD 2.7 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Environmental Testing Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 GC-MS Instruments
- 12.3.7.2 Mass Spectrometers
- 12.3.7.3 Liquid Chromatography
- 12.3.7.4 ICP-MS Instruments
- 12.3.7.5 LC-MS Instruments
- 12.3.7.6 Gas Chromatography
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Platform - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Conventional/Benchtop Platforms
- 12.4.7.2 Handheld Platforms
- 12.4.7.3 Portable/Mobile Platforms
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Water Quality Testing
- 12.5.7.2 Air Quality Testing
- 12.5.7.3 Soil Contamination Analysis
- 12.5.7.4 Organic Pollutants Detection
- 12.5.7.5 Heavy Metals Analysis
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Environmental Testing Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Environmental Testing Equipment Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Environmental Testing Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Environmental Testing Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thermo Fisher Scientific, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Agilent Technologies, Inc.
- 18.4 Eurofins
- 18.5 SGS SA
- 18.6 ALS Limited
- 18.7 Bureau Veritas SA
- 18.8 Intertek
- 18.9 Mérieux Nutrisciences Corporation
- 18.10 Asurequality Limited
- 18.11 Alex Stewart
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

