
Market Overview
Gas chromatography (GC), a pivotal analytical technique, showcased robust growth in 2023, reaching a market value of 3,167.70 million USD. This surge reflects the expanding adoption of GC systems across diverse industries, driven by technological advancements and increasing demand for precise analytical solutions. With its unparalleled ability to separate complex mixtures and detect trace compounds with exceptional sensitivity, GC continues to be instrumental in pharmaceuticals, environmental monitoring, petrochemicals, and food safety sectors.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Gas chromatography Market Size 2023 | USD 3,167.70 Million |
| Gas chromatography Market, CAGR | 4.1% |
| Gas chromatography Market Size 2032 | USD 4,577.70 Million |
Looking ahead to 2032, the gas chromatography market is poised for further expansion, with a projected growth to 4,577.70 million USD. This forecast underscores the sustained demand for GC instrumentation and consumables, fueled by regulatory compliance requirements, industry advancements, and evolving customer needs. The compound annual growth rate (CAGR) of 4.1% reflects the steady trajectory of market development, as manufacturers innovate to enhance instrument performance, usability, and affordability.
Despite facing challenges such as cost constraints and competition from alternative technologies, gas chromatography remains indispensable for critical applications such as pharmaceutical quality control, environmental analysis, and food safety assurance. As global industries prioritize quality assurance, safety, and regulatory compliance, the demand for precise and reliable analytical solutions provided by GC is expected to drive sustained market growth, fostering continued innovation and expansion in the gas chromatography landscape.
Market Drivers
Technological Advancements Driving Innovation
Gas chromatography (GC) continues to evolve with advancements in technology, propelling innovation in analytical capabilities. Miniaturization of components, automation, and integration with other analytical techniques enhance efficiency and accuracy. High-resolution systems, such as comprehensive two-dimensional GC (GCxGC), enable detailed separation and identification of complex mixtures, catering to diverse industry needs. Moreover, developments in detectors, such as mass spectrometry and flame ionization, improve sensitivity and selectivity, expanding application horizons across pharmaceuticals, environmental analysis, and food safety.
Increasing Demand for Analytical Accuracy and Precision
With stringent regulatory requirements and quality standards across industries, the demand for precise and accurate analytical techniques like gas chromatography is on the rise. GC's ability to separate and quantify components within complex mixtures with high precision makes it indispensable in pharmaceutical drug development, environmental monitoring, and forensic analysis. As industries strive for product quality assurance and compliance with regulatory norms, gas chromatography emerges as a key tool for ensuring accuracy in qualitative and quantitative analysis, thereby driving its market growth.
Growing Focus on Environmental Monitoring and Sustainability
In the wake of escalating environmental concerns and regulatory pressures to mitigate pollution, there's a heightened focus on environmental monitoring and sustainability initiatives. Gas chromatography plays a pivotal role in analyzing air, water, and soil samples for pollutants, volatile organic compounds (VOCs), and greenhouse gasses. The ability of GC to detect trace levels of contaminants and quantify pollutants accurately positions it as an essential tool for environmental monitoring agencies, research institutions, and industries striving for sustainable practices, thus fueling its market expansion.
Expanding Applications in Pharmaceutical and Biotechnology Industries
The pharmaceutical and biotechnology sectors are witnessing rapid growth, driven by increasing research and development activities, drug discovery endeavors, and regulatory approvals. Gas chromatography finds extensive applications in these industries for drug purity analysis, residual solvent determination, and impurity profiling during drug manufacturing processes. Additionally, GC is instrumental in analyzing volatile organic compounds in biological samples, contributing to metabolomics and biomarker discovery research. As these sectors continue to expand globally, the demand for gas chromatography instruments and consumables is poised to escalate accordingly.
Rising Adoption in Food and Beverage Testing
Food and beverage safety and quality are paramount concerns for consumers, regulatory bodies, and manufacturers alike. Gas chromatography plays a crucial role in analyzing food contaminants, pesticides, additives, and flavor compounds to ensure compliance with food safety regulations and quality standards. With increasing consumer awareness and stringent regulatory oversight, the adoption of gas chromatography in food and beverage testing laboratories is witnessing an upsurge. The ability of GC to provide accurate and reliable results swiftly makes it indispensable for ensuring the safety, authenticity, and quality of food products, thus driving its market growth in this sector.
Emergence of Portable and Handheld GC Solutions
The advent of portable and handheld gas chromatography solutions is revolutionizing field analysis and on-site testing across various industries. These compact systems offer real-time analysis capabilities, enabling rapid decision-making in critical scenarios such as environmental monitoring, industrial process control, and emergency response situations. The portability and ease of use of these GC systems enhance operational efficiency, reduce sample transportation costs, and facilitate quick identification of contaminants or analytes in remote or challenging environments. As the demand for on-site analysis continues to rise, the market for portable and handheld GC solutions is experiencing significant growth.
Integration with Data Analytics and Artificial Intelligence
Integration of gas chromatography with advanced data analytics and artificial intelligence (AI) algorithms is driving new possibilities in data interpretation, pattern recognition, and predictive analysis. By leveraging machine learning techniques, GC systems can efficiently process large datasets, identify complex patterns in chromatograms, and predict analyte concentrations or sample characteristics with high accuracy. This integration enhances analytical capabilities, reduces analysis time, and facilitates the discovery of hidden insights in chromatographic data. As industries embrace digitalization and seek to extract actionable intelligence from analytical results, the convergence of GC with data analytics and AI presents compelling opportunities for market expansion.
Shift towards Green and Sustainable Analytical Practices
In line with global sustainability goals, there is a growing emphasis on adopting green and eco-friendly analytical practices within laboratories and industries. Gas chromatography manufacturers are responding to this trend by developing energy-efficient instruments, eco-friendly consumables, and sustainable sample preparation techniques. Additionally, there is a rising demand for alternative solvents and stationary phases that minimize environmental impact without compromising analytical performance. The integration of renewable energy sources and the implementation of green chemistry principles in GC workflows are further contributing to sustainable analytical practices, driving market growth among environmentally conscious consumers and organizations.
Key Market Segmentation:
By Product:
- Accessories and Consumables
- Fittings and Tubing
- Columns and Accessories
- Auto-sampler Accessories
- Flow Management and Pressure Regulator Accessories
- Others
By Instruments
- Systems
- Auto-samplers
- Fraction Collectors
- Detectors
- Flame Ionization Detectors (FID)
- Thermal Conductivity Detectors (TCD)
- Mass Spectrometry Detectors
- Others
By Reagents
- Analytical Gas Chromatography Reagents
- Bioprocess Gas Chromatography Reagents
By End Use Industry:
- Food and Beverage
- Agriculture
- Pharmaceutical
- Oil and Gas
- Environmental Biotechnology
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Market Trends
Miniaturization and Portable GC Systems:
There is a growing demand for portable and miniaturized GC systems, especially in field applications such as environmental monitoring, food safety, and homeland security. Miniaturization allows for increased portability, reduced sample volume requirements, and faster analysis times. These systems often utilize microfabrication techniques and innovative sample introduction methods to achieve high sensitivity and selectivity in a compact format.
Hyphenated Techniques:
GC hyphenated with mass spectrometry (GC-MS) or other detection techniques continues to gain popularity due to its ability to provide comprehensive analysis and identification of complex mixtures. Coupling GC with techniques like Fourier-transform infrared spectroscopy (GC-FTIR), atomic emission spectroscopy (GC-AES), or tandem mass spectrometry (GC-MS/MS) enhances analytical capabilities, enabling researchers to tackle challenging analytical problems with higher sensitivity and specificity.
Advanced Column Technologies:
Column technology plays a crucial role in GC performance. Recent advancements focus on the development of novel stationary phases, such as superficially porous particles (SPPs), monolithic columns, and chiral stationary phases (CSPs). These advancements aim to improve separation efficiency, resolution, and speed while accommodating a wider range of analytes and sample matrices.
Automation and Integration:
Automation of sample preparation, injection, and data analysis workflows streamlines the GC process, reducing human error and increasing throughput. Integrated systems that combine sample preparation, separation, and detection modules into a single platform further enhance efficiency and reproducibility. Automated sample introduction techniques, such as headspace analysis and solid-phase microextraction (SPME), enable high-throughput analysis of volatile and semivolatile compounds in diverse sample matrices.
Green Analytical Chemistry:
Sustainable practices are gaining traction in analytical chemistry, including gas chromatography. Manufacturers are developing eco-friendly GC systems that minimize solvent and energy consumption, reduce waste generation, and utilize renewable resources wherever possible. Additionally, there is a growing emphasis on the development of green sample preparation techniques and the use of alternative solvents with lower environmental impact.
Data Handling and Chemometrics:
With the increasing complexity of analytical data generated by GC systems, robust data handling and chemometric tools are essential for effective interpretation and decision-making. Software packages equipped with advanced data processing algorithms, multivariate analysis techniques, and machine learning algorithms facilitate rapid data analysis, pattern recognition, and compound identification. Integration of these tools into GC systems enables real-time monitoring, method optimization, and automated reporting of results.
Restraints and Challenges
- Cost Constraints: One prominent hurdle in the widespread adoption of gas chromatography is the initial investment cost. Procuring high-quality GC equipment along with the necessary accessories and consumables demands a significant financial commitment. Additionally, the cost of maintenance, calibration, and skilled personnel further adds to the overall expenditure, limiting its accessibility to smaller laboratories and institutions with constrained budgets.
- Complexity in Operation: Gas chromatography systems often entail intricate operational procedures and require specialized training for proficient handling. Novice users may face challenges in setting up instruments, optimizing parameters, and interpreting results accurately. This complexity in operation acts as a deterrent for potential users, necessitating comprehensive training programs and user-friendly interfaces to enhance usability and reduce operational errors.
- Sample Preparation Challenges: Effective sample preparation is crucial for the success of gas chromatography analysis. However, certain samples, especially those with high complexity or low analyte concentrations, pose significant challenges in extraction, derivatization, and cleanup processes. Sample matrix interference, analyte instability, and limited sample availability further exacerbate these challenges, often requiring labor-intensive and time-consuming preparation methods.
- Instrumentation Limitations: Despite advancements in gas chromatography instrumentation, certain limitations persist, hindering its applicability in certain analytical scenarios. These limitations may include insufficient sensitivity for trace-level analysis, inadequate resolution for complex sample matrices, and limited compatibility with specific analyte types or detection techniques. Addressing these limitations necessitates ongoing research and development efforts to enhance instrument performance and versatility.
- Regulatory Compliance: Compliance with stringent regulatory requirements and quality standards poses a significant challenge for gas chromatography users, particularly in regulated industries such as pharmaceuticals, environmental monitoring, and food safety. Ensuring method validation, instrument qualification, and data integrity in accordance with regulatory guidelines demands meticulous documentation, adherence to standard operating procedures, and regular audits, adding complexity and cost to analytical workflows.
- Emerging Technologies and Competition: The dynamic landscape of analytical instrumentation witnesses the continuous emergence of novel technologies competing with traditional gas chromatography systems. Techniques such as liquid chromatography-mass spectrometry (LC-MS), capillary electrophoresis (CE), and portable spectroscopy offer alternative solutions with distinct advantages in terms of sensitivity, speed, and versatility. In response, gas chromatography vendors must innovate and differentiate their offerings to remain competitive in the market.
Regional Analysis-
- The gas chromatography market, while diverse, can be broadly understood by examining key regions and their respective market shares. In North America, the United States dominates with roughly 60-70% of the market share, followed by Canada with around 10-15%. Europe's market is led by Germany, contributing approximately 20-25%, followed by the United Kingdom and France with 15-20% and 10-15% respectively. In the Asia Pacific region, China leads with 25-30%, followed by Japan and India with 15-20% and 10-15% respectively. Latin America sees Brazil as a frontrunner with 25-30%, followed by Mexico with 15-20%. South Africa leads in the Middle East and Africa with 20-25%, followed by Saudi Arabia with 15-20%.
- These regional insights offer a simplified view of the gas chromatography market's distribution. North America and Europe, along with key Asian countries like China and Japan, hold significant shares, with the United States and Germany as dominant players. In Latin America and the Middle East, Brazil and South Africa emerge as leading markets respectively. These percentages, while approximate, provide a snapshot of each region's contribution to the global gas chromatography landscape. For precise data, consulting recent market reports is recommended, as market shares may fluctuate over time due to various factors such as economic conditions and technological advancements.
Recent developments-
Key players-
- Agilent Technologies, Inc.
- Thermo Fisher Scientific Inc.
- Shimadzu Corporation
- PerkinElmer, Inc.
- Waters Corporation
- Restek Corporation
- Merck KGaA (Merck Millipore)
- SGE Analytical Science
- Dani Instruments S.p.A.
- LECO Corporation
Future outlook-
- Technological Advancements: Continued advancements in GC instrumentation and software will enhance efficiency, sensitivity, and resolution, enabling faster and more accurate analysis.
- Miniaturization: Miniaturization of GC systems will lead to portable and field-deployable instruments, expanding the application areas to on-site analysis and remote locations.
- Automation and Integration: Increasing automation and integration with other analytical techniques such as mass spectrometry and spectroscopy will streamline workflows and improve data interpretation.
- High-Throughput Analysis: Development of high-throughput GC systems will cater to the growing demand for rapid analysis in industries such as pharmaceuticals and environmental monitoring.
- Enhanced Data Management: Advancements in data management solutions will facilitate better storage, retrieval, and analysis of large datasets generated by GC systems, supporting complex analytical tasks.
- Application Expansion: GC techniques will find new applications in emerging fields such as metabolomics, proteomics, and forensic analysis, driven by advancements in sample preparation and detection methods.
- Sustainability Focus: Adoption of green chromatography principles, including the use of alternative and eco-friendly stationary phases and solvents, will gain momentum to address environmental concerns.
- Customization and Modularization: Increasing demand for customizable GC systems and modular components will allow users to tailor instruments to specific analytical requirements, improving flexibility and performance.
- Market Growth in Developing Regions: Growing industrialization and investments in R&D in developing regions will drive market growth, particularly in Asia-Pacific and Latin American countries.
- Regulatory Compliance and Quality Control: Stringent regulatory requirements and the need for robust quality control measures will continue to bolster the demand for GC systems in pharmaceutical, food safety, and environmental testing industries.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements Driving Innovation
Continuous improvements in GC instrumentation, such as miniaturization, automation, and integration with mass spectrometry, are enhancing analytical performance, efficiency, and usability, making GC more attractive for a wider range of applications.
Increasing Demand for Analytical Accuracy and Precision
Stringent regulatory requirements in pharmaceuticals, food safety, and environmental monitoring are driving the need for highly precise and accurate analytical techniques, positioning gas chromatography as a critical tool for compliance and quality assurance.
Growing Focus on Environmental Monitoring and Sustainability
Rising environmental concerns and regulatory mandates for pollution control are fueling the adoption of GC for the detection and quantification of pollutants, VOCs, and greenhouse gases in air, water, and soil samples.
Expanding Applications in Pharmaceutical and Biotechnology Industries
The growth of pharmaceutical and biotech sectors, with increased R&D and drug development activities, is boosting demand for GC in drug purity analysis, impurity profiling, and metabolomics research.
Emergence of Portable and Handheld GC Solutions
The development of portable and handheld GC systems is enabling real-time, on-site analysis in field applications such as environmental monitoring and emergency response, expanding the market’s reach beyond traditional laboratory settings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What are the key factors influencing the growth of the gas chromatography market?
How does miniaturization impact the future of gas chromatography?
What role does sustainability play in the future of gas chromatography?
Which regions are expected to experience significant growth in the gas chromatography market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Accessories and Consumables
- 1.2.2 Fittings and Tubing
- 1.2.3 Columns and Accessories
- 1.2.4 Auto-sampler Accessories
- 1.2.5 Flow Management and Pressure Regulator Accessories
- 1.2.6 Others
- 1.3 By Instrument
- 1.3.1 Systems
- 1.3.2 Auto-samplers
- 1.3.3 Fraction Collectors
- 1.3.4 Detectors
- 1.3.5 Others
- 1.4 By End Use Industry
- 1.4.1 Food and Beverage
- 1.4.2 Agriculture
- 1.4.3 Pharmaceutical
- 1.4.4 Oil and Gas
- 1.4.5 Environmental Biotechnology
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
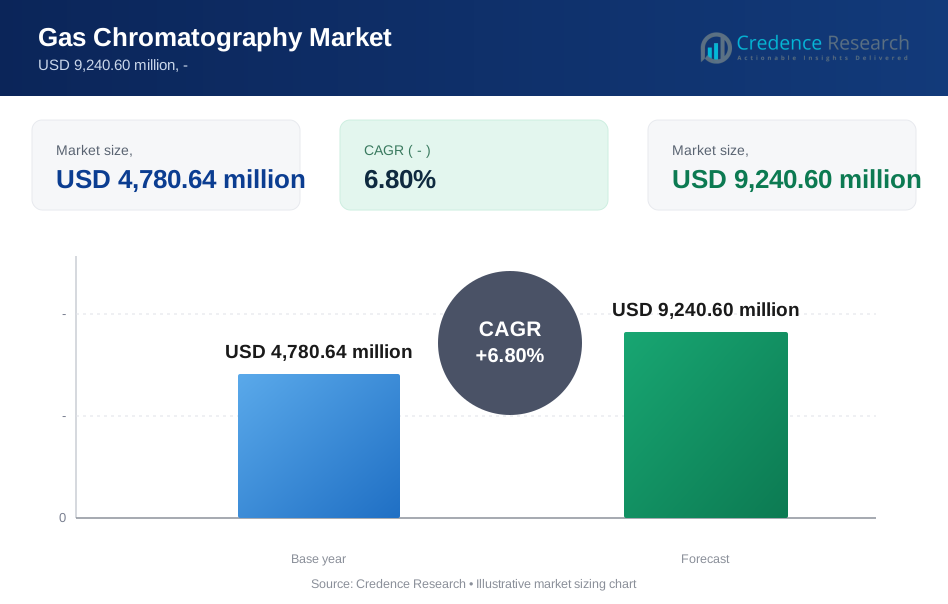
- 2.5.1 2023: USD 4,780.64 million → 2032: USD 9,240.60 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Gas Chromatography Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Gas Chromatography Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Gas Chromatography Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Gas Chromatography Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Gas Chromatography Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Gas Chromatography Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Gas Chromatography Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Gas Chromatography Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 4,780.64 million → 2032: USD 9,240.60 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Gas Chromatography Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Accessories and Consumables
- 12.3.7.2 Fittings and Tubing
- 12.3.7.3 Columns and Accessories
- 12.3.7.4 Auto-sampler Accessories
- 12.3.7.5 Flow Management and Pressure Regulator Accessories
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Instrument - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Systems
- 12.4.7.2 Auto-samplers
- 12.4.7.3 Fraction Collectors
- 12.4.7.4 Detectors
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End Use Industry - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Food and Beverage
- 12.5.7.2 Agriculture
- 12.5.7.3 Pharmaceutical
- 12.5.7.4 Oil and Gas
- 12.5.7.5 Environmental Biotechnology
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Gas Chromatography End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Gas Chromatography Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Gas Chromatography Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Gas Chromatography Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Agilent Technologies, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Thermo Fisher Scientific Inc.
- 18.4 Shimadzu Corporation
- 18.5 PerkinElmer, Inc.
- 18.6 Waters Corporation
- 18.7 Restek Corporation
- 18.8 Merck KGaA (Merck Millipore)
- 18.9 SGE Analytical Science
- 18.10 Dani Instruments S.p.A.
- 18.11 LECO Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

