
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Biomass Pellets Market Size 2024 | USD 8400 million |
| Europe Biomass Pellets Market, CAGR | 5.3% |
| Europe Biomass Pellets Market Size 2032 | USD 12697.1 million |
Market Overview:
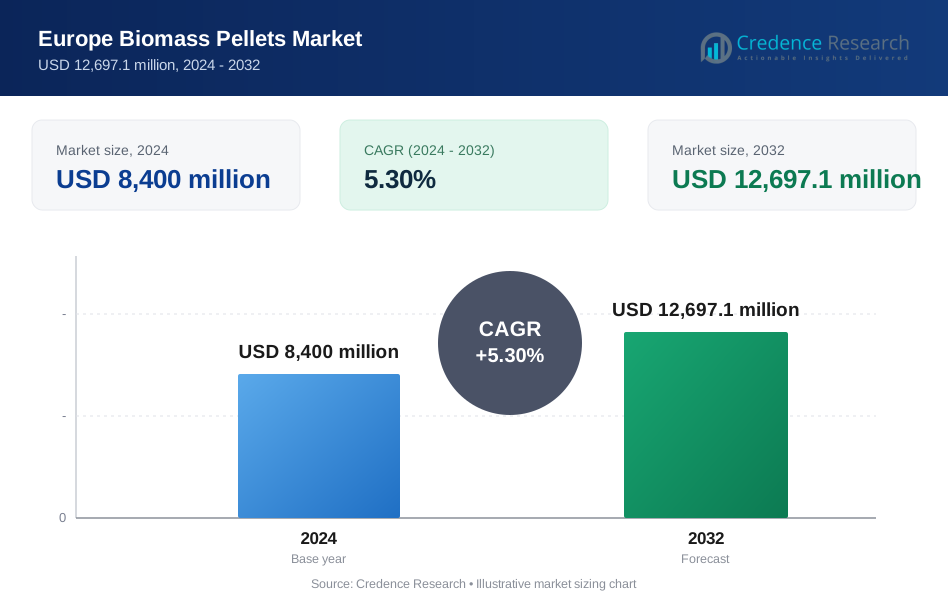
Europe Biomass Pellets Market size was valued at USD 8400 million in 2024 and is anticipated to reach USD 12697.1 million by 2032, at a CAGR of 5.3% during the forecast period (2024-2032).
Key drivers fueling market growth include strong governmental support for renewable energy adoption and strict emission regulations aimed at reducing carbon footprints. Initiatives such as the EU Renewable Energy Directive and country-level subsidies for biomass heating systems are encouraging the shift towards pellet-based solutions. Moreover, the increasing volatility in fossil fuel prices and growing public awareness regarding climate change are pushing consumers and industries alike to adopt more sustainable energy practices. Technological advancements in pellet production, logistics, and combustion systems are also improving efficiency and reducing costs, further strengthening the market's growth trajectory. The rising use of smart metering and automation in pellet boilers is enhancing operational control and energy savings. Strategic partnerships between pellet producers and energy utilities are facilitating broader adoption in the commercial segment.
Regionally, Western Europe dominates the biomass pellets market, accounting for a significant share of total consumption. Countries such as Germany, France, Italy, and Austria are leading in terms of production and usage due to strong policy support and established infrastructure. The Nordic countries also show high adoption rates, with Sweden and Finland leveraging extensive forest resources for pellet production. Eastern Europe is emerging as a key growth area, with countries like Poland and the Baltic States expanding their biomass capacities to meet rising energy needs and align with EU decarbonization goals. Localized pellet manufacturing is reducing reliance on imports, promoting energy independence in the region. The cross-border trade of pellets within Europe is also facilitating market integration and balancing regional demand.Bottom of Form
Market Insights:
- The Europe Biomass Pellets Market was valued at USD 8,400 million in 2024 and is anticipated to reach USD 12,697.1 million by 2032, growing at a CAGR of 5.3% during the forecast period due to increasing demand for renewable energy solutions.
- Government initiatives such as the EU Renewable Energy Directive and national subsidies for biomass heating systems are driving widespread adoption of biomass pellets across residential, industrial, and utility sectors.
- Rising concerns over energy security and the push for locally sourced fuel are accelerating the use of agricultural and forestry residues for pellet production, aligning with circular economy goals.
- Technological improvements in pellet manufacturing, combustion efficiency, and automated heating systems are enhancing fuel performance and reducing costs for end-users.
- Geopolitical factors, including the EU’s import restrictions on Russian wood pellets, have strengthened intra-European production and trade, ensuring a more resilient and self-sufficient supply network.
- Complex regulatory compliance, certification requirements, and raw material supply disruptions pose challenges, particularly for smaller producers, impacting scalability and investment planning.
- Western Europe leads the market with 55% share due to mature infrastructure and policy support, followed by Northern Europe at 25% with strong export capacity, while Southern and Eastern Europe together hold 20% and show increasing potential through expanding production capacity and policy alignment.
Market Drivers:
Robust Policy Support and Carbon Neutrality Targets Accelerate Market Expansion
Government policies and ambitious carbon neutrality goals drive the Europe Biomass Pellets Market. The European Union’s Renewable Energy Directive sets higher renewable energy quotas and enforces sustainability criteria for biomass, encouraging industries to transition from fossil fuels to bioenergy. Many European countries are actively phasing out coal and fossil fuels, prioritizing biomass alternatives to meet net-zero emissions targets. This regulatory framework secures consistent demand for biomass pellets in power generation, residential heating, and district heating networks. Leading nations such as Germany, France, the Netherlands, and the UK are at the forefront of this transition. The market maintains strong momentum due to these policy-driven initiatives.
Growing Demand for Renewable and Local Energy Sources Drives Adoption
Energy security concerns and the push for stable, local energy supplies stimulate the adoption of biomass pellets across Europe. The market capitalizes on the use of agricultural and forestry residues, aligning with circular economy principles and resource efficiency. Biomass pellets offer a reliable, cost-effective solution for residential heating, industrial power production, and combined heat and power plants. The preference for clean, efficient, and locally sourced energy has attracted significant investment in pellet production and logistics. It continues to gain traction as consumers and industries seek alternatives to imported fossil fuels.
- For instance, in July 2022, Enviva Inc. began construction of its Epes plant in Alabama, designed with a nameplate capacity of 1.1 million metric tons per year-the company’s largest wood pellet production facility, with full production expected by 2025.
Technological Advancements and Supply Chain Optimization Enhance Competitiveness
Advancements in pellet production, compression, and combustion technologies have improved the energy density, durability, and efficiency of biomass pellets. The Europe Biomass Pellets Market benefits from innovations such as torrefied and black pellets, which offer higher energy content and lower moisture, making them suitable for co-firing in coal power stations. Optimized supply chains and regional trade agreements have increased pellet availability and reduced costs. Real-time monitoring and digital integration in pellet-burning systems further enhance fuel efficiency for end users.
- For instance, ANDRITZ pellet mills now produce more than 50% of all biofuel pellets worldwide, supporting both large-scale power stations and residential heating applications.
Geopolitical Shifts and Price Volatility Influence Market Dynamics
Geopolitical developments, including the EU’s restrictions on Russian wood pellet imports, have reshaped supply chains and increased reliance on domestic and intra-European production. Fluctuations in fossil fuel and natural gas prices have made biomass pellets a more attractive option for industrial and residential consumers. The market demonstrates resilience by adapting to supply disruptions and maintaining strong consumption in residential and commercial sectors. It continues to serve as a key component of Europe’s renewable energy landscape, supporting long-term sustainability goals.
Market Trends:
Rising Integration of Advanced Pellet Technologies and Sustainable Feedstock Sourcing
The Europe Biomass Pellets Market demonstrates a clear shift toward advanced pellet technologies and sustainable feedstock sourcing. Producers invest in torrefied and black pellet production, which improves energy density and reduces moisture content, making pellets more suitable for co-firing in existing coal plants. It also sees a growing preference for certified sustainable biomass, with suppliers adopting third-party certification schemes to ensure traceability and compliance with EU sustainability standards. The market benefits from increased use of agricultural residues and waste wood, reducing reliance on traditional wood sources and supporting circular economy principles. Companies focus on optimizing pellet quality and production efficiency through automation and digital monitoring. These trends enhance the market’s competitiveness and environmental credentials.
- For instance, in 2024, Germany produced almost 3.7 million tonnes of ENplus® certified wood pellets, the highest in Europe, demonstrating the country’s leadership in sustainable and technologically advanced pellet production.
Expansion of Residential and Commercial Applications Alongside Supply Chain Diversification
The Europe Biomass Pellets Market experiences expanding demand in residential heating, commercial buildings, and district heating networks. It responds to consumer preference for low-carbon, locally sourced heating solutions, driving investments in pellet stove and boiler technologies. The market adapts to supply chain disruptions by diversifying sourcing strategies and strengthening regional production capacities. Countries invest in logistics infrastructure, including bulk storage and efficient transport systems, to ensure reliable pellet delivery. The market also witnesses the emergence of long-term supply agreements between producers and utilities, stabilizing prices and ensuring supply security. These trends collectively reinforce the market’s role in Europe’s energy transition and resilience.
- For instance, the ENplus® certification scheme reached over 1,300 identified and solved fraud cases in 2024, directly enhancing trust and reliability in the European pellet supply chain.
Market Challenges Analysis:
Complex Regulatory Landscape and Sustainability Compliance Create Barriers
The Europe Biomass Pellets Market faces significant challenges from a complex regulatory environment and stringent sustainability requirements. It must comply with evolving EU directives that demand rigorous documentation and third-party certification of feedstock sources. This process increases operational costs and creates barriers for smaller producers. Regulatory uncertainty in some countries complicates long-term investment decisions. The market also contends with public scrutiny over land use and the carbon neutrality of biomass, which can delay project approvals. These factors collectively hinder rapid expansion and require continuous adaptation.
Supply Chain Disruptions and Price Volatility Impact Market Stability
The market encounters supply chain disruptions and price volatility, which threaten its stability. It depends on reliable access to raw materials, yet geopolitical tensions and trade restrictions can limit feedstock availability. Fluctuating transportation costs and labor shortages further strain logistics. The Europe Biomass Pellets Market must also address competition from alternative renewable energy sources, which can impact demand. Price instability affects both producers and consumers, making long-term planning difficult. These challenges necessitate robust risk management and supply chain diversification strategies.
Market Opportunities:
Expansion into Industrial Decarbonization and District Heating Systems Fuels Growth
The Europe Biomass Pellets Market holds strong opportunities in industrial decarbonization and district heating. It can support large-scale energy users seeking to reduce emissions by replacing coal and natural gas with sustainable biomass. Growing investments in district heating networks across urban centers create new demand for high-quality pellets. The market can leverage EU funding and public-private partnerships to accelerate infrastructure upgrades. Industrial sectors such as cement, steel, and chemicals present untapped potential for pellet adoption. These segments require reliable, high-energy fuels that align with strict environmental standards.
Innovation in Feedstock Utilization and Cross-Border Trade Unlocks New Potential
Opportunities arise from innovation in feedstock utilization and the expansion of cross-border trade. The Europe Biomass Pellets Market can diversify raw material sources by incorporating agricultural residues, energy crops, and waste streams. It benefits from advancements in pellet production technologies that improve efficiency and product quality. Expanding intra-European trade agreements facilitates smoother pellet movement and strengthens supply security. The market can also tap into growing demand for certified sustainable pellets in export markets. These factors position it to play a pivotal role in Europe’s transition to renewable energy.
Market Segmentation Analysis:
By Type
The Europe Biomass Pellets Market is segmented into wood pellets and non-wood pellets. Wood pellets dominate this category due to their uniform size, high combustion efficiency, and suitability for both domestic and industrial applications. Their compatibility with modern pellet stoves and boilers supports widespread adoption. Non-wood pellets, produced from materials like straw and husks, are gaining interest where wood resources are limited or where agricultural waste is abundant.
- For instance, Graanul Invest, a leading European producer, is expected to produce 2.2 million tons of wood pellets in 2024, reflecting its advanced manufacturing capacity and strong market presence.
By Source
Based on source, the market includes forest residues, agricultural residues, and energy crops. Forest residues account for the largest share, driven by the region’s established forestry industry and sustainable forest management practices. Agricultural residues are emerging as a viable source, especially in Eastern and Southern Europe, where crop-based biomass is readily available. Energy crops, such as switchgrass and miscanthus, hold future potential but currently represent a small portion due to limited cultivation and infrastructure.
- For instance, the ECO-Pet project, funded by the European Commission under Horizon 2020, received US$ 9.09 million to develop durable and absorbent pellets from sawmilling residuals and wood waste, demonstrating their technical and economic viability for animal bedding and energy applications.
By End-Use
In terms of end-use, the market is categorized into residential, commercial, and industrial sectors. The residential sector leads, supported by rising demand for eco-friendly heating systems and financial incentives for pellet stove installations. The commercial segment is growing steadily, with biomass being used in district heating networks and public buildings. The industrial sector is adopting biomass pellets to replace fossil fuels in power generation and manufacturing processes, driven by emission reduction targets and fuel diversification strategies.
Segmentations:
By Type:
- Wood Pellets
- Black Pellets
- Forestry Pellets
- Agricultural Pellets
- Biomass Briquettes
By Source:
- Agricultural Residue
- Wood Sawdust
- Wood Chips
- Others
By End-use:
- Residential
- Heating
- Cooking
- Power Generation
- Industrial
- Heating
- Power Generation
- Bio-refining
- Others
- Commercial
- Heating
- Power Generation
- Others
By Region:
- Germany
- Italy
- France
- The United Kingdom
- Spain
- Belgium
- Netherland
- Russia
- Rest of Europe
Regional Analysis:
Western Europe Leads with Strong Policy Support and High Consumption Rates
Western Europe holds 55% market share in the Europe Biomass Pellets Market, making it the clear leader in the region. Germany, the United Kingdom, France, and the Netherlands drive this dominance through robust renewable energy targets and substantial incentives for biomass heating and power generation. It benefits from advanced infrastructure, mature supply chains, and a well-developed market for residential and industrial pellet use. The region’s utilities and district heating networks continue to invest in large-scale pellet-fueled facilities, ensuring stable demand. Public awareness of sustainability and energy security further supports market growth. Western Europe’s leadership sets the benchmark for other regions in terms of innovation and regulatory alignment.
Northern Europe Sets Standards in Sustainable Production and Export Capacity
Northern Europe accounts for 25% market share in the Europe Biomass Pellets Market, reflecting its strong position in sustainable production and exports. Sweden, Finland, and Denmark utilize abundant forest resources and a tradition of sustainable forestry management to supply both domestic and international markets with high-quality certified pellets. It has invested in modern pellet plants and efficient logistics, enabling reliable supply to key European markets. Northern Europe’s expertise in integrating biomass into district heating and combined heat and power systems positions it as a technical leader. The region’s export-oriented approach helps stabilize the broader European market.
Southern and Eastern Europe Show Emerging Potential with Resource Availability
Southern and Eastern Europe together represent 20% market share in the Europe Biomass Pellets Market, highlighting their emerging role. Poland, Romania, and Italy are increasing investments in pellet production capacity, leveraging agricultural residues and underutilized forests. It faces challenges in infrastructure development and market awareness but benefits from rising demand for affordable, local heating solutions. Regional governments are aligning policies with EU directives to attract investment and stimulate market growth. The expansion of local supply chains and adoption of modern pellet technologies are expected to drive future growth in these regions. Southern and Eastern Europe’s development will contribute to a more balanced and resilient European biomass market.
Key Player Analysis:
- Ekman & Co. AB
- Lignetics, Inc.
- Graanul Invest (AS Graanul Invest)
- German Pellets GmbH
- Stora Enso Oyj
- Pinnacle Renewable Energy
- Ecostan India Pvt Ltd
- Enviva Inc.
- Drax Group plc (with Pinnacle Renewable Energy)
Competitive Analysis:
The Europe Biomass Pellets Market features a competitive landscape marked by a mix of multinational corporations and regional producers. It is driven by established players such as Drax Group plc, Graanul Invest, German Pellets GmbH, and Stora Enso Oyj, which possess strong production capacities, advanced technology, and broad distribution networks. These companies focus on expanding their market presence through strategic partnerships, acquisitions, and investments in modern pellet facilities. Smaller regional firms contribute to supply flexibility and cater to localized demand, particularly in Eastern and Southern Europe. The market benefits from innovation in pellet production, quality enhancement, and logistics optimization. Export-oriented firms in Northern Europe maintain a strong foothold in international trade. Market competition is influenced by regulatory compliance, sustainability certifications, and cost efficiency. Companies that align closely with EU renewable energy goals and offer certified, high-quality pellets gain a competitive edge and maintain long-term customer relationships across multiple application sectors.
Recent Developments:
- In December 2024, Enviva announced its successful emergence from Chapter 11 bankruptcy protection, completing a major financial restructuring.
- In February 2023, Enviva announced a new partnership with the Girl Scouts of Greater Mississippi to support forest restoration and reforestation, including financial support for long-term forest management and tree planting initiatives.
- In September 2024, Drax Group PLC and Karbon-X Corp launched a new partnership to facilitate transactions in carbon offsets, accelerating large-scale carbon removal and sustainable energy generation.
Market Concentration & Characteristics:
The Europe Biomass Pellets Market shows moderate to high market concentration, with a few major players accounting for a significant share of total production and distribution. It is characterized by vertically integrated operations, where leading companies manage sourcing, processing, and logistics to maintain control over supply chains and product quality. The market operates within a strict regulatory framework, requiring compliance with EU sustainability standards and third-party certifications. It supports both large-scale industrial applications and small-scale residential use, reflecting versatility in demand. The market relies heavily on forest-based feedstock, though agricultural residues are gaining traction in specific regions. It also features seasonal demand fluctuations, influenced by heating requirements during winter months. Companies that invest in innovation, automation, and geographic expansion tend to secure a stronger position. Cross-border trade, particularly within Western and Northern Europe, reinforces market integration and helps balance regional supply-demand dynamics.
Report Coverage:
The research report offers an in-depth analysis based on Type, Source, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- European policymakers will tighten sustainability regulations to ensure pellet feedstock traceability and certification.
- Demand will increase across residential heating due to expansion of government-supported pellet stove incentive programs.
- Industrial energy consumers will shift from coal to biomass pellets to meet emission-reduction targets under evolving EU frameworks.
- Pellet producers will invest in torrefaction and densification technology to improve energy density and reduce transport costs.
- Logistics providers will expand intermodal transport solutions to streamline pellet distribution across Western and Eastern Europe.
- Farmers and agribusinesses will scale up agricultural residue collection, integrating biomass into rural energy systems.
- Energy utilities will integrate biomass pellets into district heating and combined heat and power facilities for stable energy supply.
- Export-oriented firms in Nordic countries will secure new trade agreements to serve emerging markets in Southern Europe.
- Innovation in smart combustion systems and IoT-enabled boilers will enhance operational efficiency and fuel management.
- Companies will form strategic alliances and joint ventures to access raw material sources and expand regional footprint.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe Biomass Pellets Market?
What are the key segments within the Europe Biomass Pellets Market?
What are some challenges faced by the Europe Biomass Pellets Market?
Who are the major players in the Europe Biomass Pellets Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Biomass Pellets Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Region & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Europe Biomass Pellets Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,400 million → 2032: USD 12,697.1 million)
- 2.1.2 Volume & Revenue – Regional Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Biomass Pellets Segmentation Snapshot
- 2.2.1 Market Split by Country – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Biomass Pellets Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Biomass Pellets Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Country
- 3.2 Europe Biomass Pellets Drivers
- 3.3 Europe Biomass Pellets Restraints & Challenges
- 3.4 Europe Biomass Pellets Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Biomass Pellets Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Biomass Pellets Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regional & Country Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Biomass Pellets category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Biomass Pellets Attractiveness Analysis
- 4.1.1 By Country – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Country – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Country – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Country Opportunity Scorecards
- 4.5.1 Priority Country 1
- 4.5.2 Priority Country 2
- 4.5.3 Priority Country 3
- 4.5.4 Priority Country 4
Note: Priority countries are selected from within the region covered by the study. Numbered entries are indicative and are populated with relevant country names based on market size, growth potential, and strategic relevance.
Chapter 5. Europe Biomass Pellets Cross-Border Trade & Market Access Analysis
- 5.1 Intra-Regional & Extra-Regional Trade Overview
- 5.1.1 Regional Export Value by Country (2024)
- 5.1.2 Regional Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Regional Import Value by Country (2024)
- 5.1.4 Regional Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: Cross-border analysis applies where relevant to Europe Biomass Pellets. Country trade flows distinguish intra-regional activity from trade with markets outside the region. Regional external trade totals exclude intra-regional flows to avoid double counting. Classifications and transaction measures follow the market scope; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Biomass Pellets Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Biomass Pellets Share Analysis – 2024
- 6.2.1 Regional Revenue Share by Company
- 6.2.2 Regional Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Country
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Regional Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Europe Biomass Pellets Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure by Country Within the Region
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Biomass Pellets (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Europe Biomass Pellets
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Europe Biomass Pellets – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Country Market Analysis – Regional Overview
- 8.1 Country Market Overview Within the Region
- 8.1.1 Country Volume Share Within the Region (Where Applicable)
- 8.1.2 Country Revenue Share Within the Region
- 8.1.3 Market Volume by Country (Where Applicable)
- 8.1.4 Market Revenue by Country
- 8.1.5 Country Forecasts Through 2032
- 8.2 Cross-Country Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Europe Biomass Pellets – Priority Country 1
Chapter 10. Europe Biomass Pellets – Priority Country 2
Chapter 11. Europe Biomass Pellets – Priority Country 3
Chapter 12. Europe Biomass Pellets – Priority Country 4
Chapter 13. Europe Biomass Pellets Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Regional Market Focus & Country Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – Country-Level Estimates & Regional Aggregation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
