
Combined Heat And Power Market Overview:
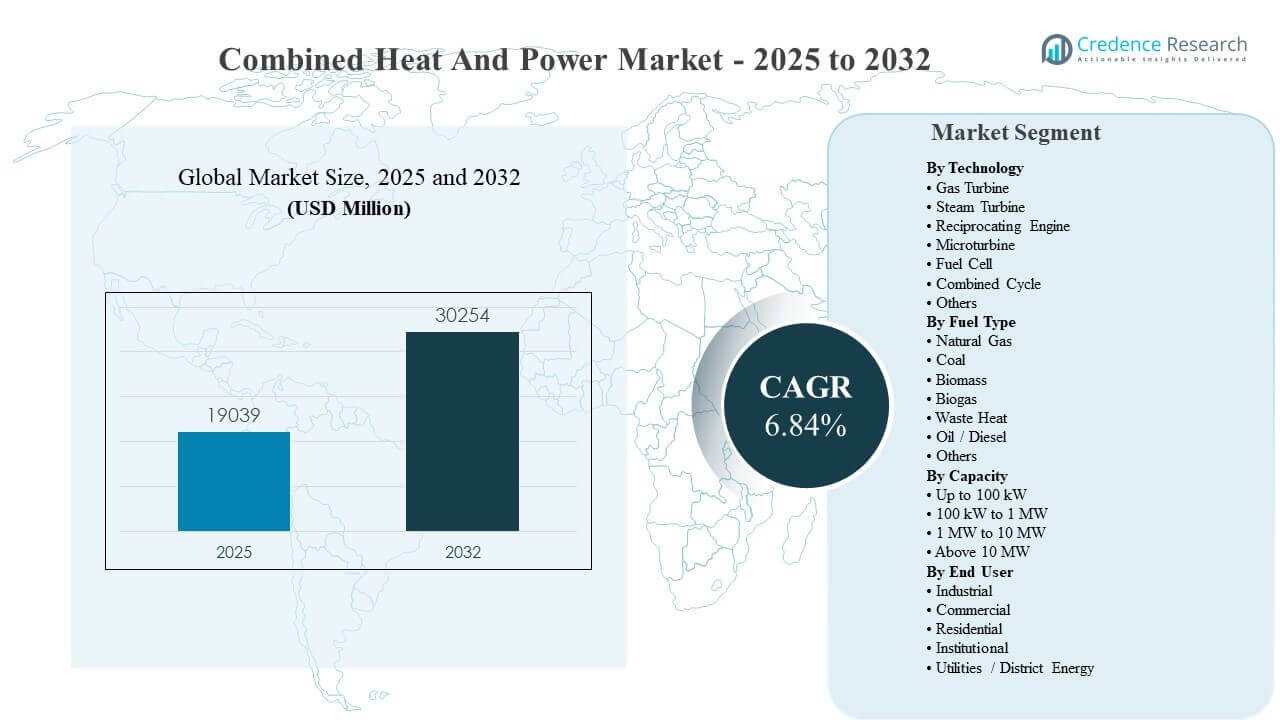
The global combined heat and power market size was estimated at USD 19039 million in 2025 and is expected to reach USD 30254 million by 2032, growing at a CAGR of 6.84% from 2025 to 2032. Expansion is being shaped by the need for higher energy efficiency across industrial plants, commercial facilities, and district energy systems, where simultaneous generation of electricity and useful heat offers stronger fuel utilization than conventional standalone power production. The market is also benefiting from modernization of distributed energy infrastructure, growing interest in on-site resilience, and broader use of cleaner fuel pathways such as natural gas, biogas, and waste-heat-based systems in both developed and emerging economies.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Combined Heat And Power Market Size 2025 | USD 19039 million |
| Combined Heat And Power Market, CAGR | 6.84% |
| Combined Heat And Power Market Size 2032 | USD 30254 million |
Key Market Trends & Insights
- The market was valued at USD 19039 million in 2025, establishing a sizable installed-base-driven replacement and upgrade opportunity across power and thermal applications.
- The market is projected to reach USD 30254 million by 2032, reflecting continued demand for efficient decentralized generation solutions.
- The forecast period implies a CAGR of 6.84% from 2025 to 2032, indicating steady medium-term expansion rather than short-cycle growth.
- Absolute revenue expansion is expected to total USD 11215 million between 2025 and 2032, showing meaningful incremental value creation across the period.
- The 2025-2032 outlook represents a roughly 1.59x market expansion over seven years, highlighting durable investment momentum in CHP systems.
Segment Analysis
The combined heat and power market is characterized by a broad operating spectrum that ranges from compact distributed systems for localized commercial and residential use to large-scale installations serving industrial and district energy needs. Technology selection typically depends on fuel availability, power-to-heat ratio requirements, efficiency goals, emissions considerations, and site-specific operating profiles. End users are increasingly evaluating CHP systems as long-term energy productivity assets rather than only backup or captive generation options. This positioning is strengthening demand for systems that can deliver reliability, flexibility, and lifecycle cost control in parallel.
Fuel choice remains a core determinant of market adoption because it directly influences operating cost, regulatory compliance, maintenance requirements, and environmental performance. Natural gas continues to shape many deployments because of its established infrastructure and favorable efficiency profile in several CHP configurations. At the same time, biomass, biogas, and waste heat are gaining relevance where policy support, circular energy models, or industrial process recovery opportunities improve project economics. Capacity ranges also create distinct demand pockets, with smaller systems serving building-level efficiency needs and larger systems supporting continuous high-load operations.
Technology Insights
Gas turbine systems remain a prominent technology category in the combined heat and power market because they are well suited for continuous-duty applications, larger commercial facilities, and industrial sites that require stable thermal and electrical output. Steam turbine installations retain importance in settings with existing boiler infrastructure and process steam demand, particularly where integrated heat recovery supports overall plant efficiency. Reciprocating engines and microturbines broaden the addressable market by serving more modular and distributed operating environments. Fuel cell-based CHP systems also continue to attract interest where lower emissions, quiet operation, and high-efficiency distributed generation are strategic priorities.
Fuel Type Insights
Natural gas remains one of the most commercially attractive fuel types in the combined heat and power market because of its widespread availability, established supply networks, and compatibility with several mature CHP technologies. Coal and oil or diesel remain more limited to specific legacy or location-based use cases where infrastructure constraints or reliability needs shape procurement decisions. Biomass and biogas are becoming more relevant in projects linked to sustainability targets, waste-to-energy strategies, and localized feedstock access. Waste heat applications also hold strong value in energy-intensive industries that are seeking to capture lost thermal energy and convert it into productive power output.
Capacity Insights
Up to 100 kW and 100 kW to 1 MW systems support decentralized applications where building-level efficiency, localized resilience, and lower upfront deployment complexity are critical. The 1 MW to 10 MW category serves a wide range of industrial, institutional, and commercial operations that require balanced electrical and thermal performance. Above 10 MW systems are more closely associated with large industrial campuses, utility-linked operations, and district heating or cooling networks. Capacity selection across the market is therefore closely tied to site load profile, continuity of thermal demand, and the economic value of on-site power generation.
End User Insights
Industrial users represent a major source of demand because manufacturing plants, refineries, chemical sites, and food processing operations often have sustained simultaneous needs for power and heat. Commercial adoption is also expanding in hospitals, hotels, campuses, and large buildings where energy cost management and reliability have become more important. Residential CHP remains comparatively niche but relevant in selected markets that support small-scale cogeneration for multi-unit or localized heating applications. Institutional and utilities or district energy users continue to provide a strong long-term market base because CHP systems align well with centralized thermal distribution and public infrastructure efficiency goals.
Combined Heat And Power Market Drivers
Rising focus on energy efficiency
Combined heat and power systems are gaining traction because they make more productive use of fuel by generating electricity and useful thermal energy from the same input stream. This dual-output model is attractive in sectors where thermal loads are continuous and energy spending is material. Industrial and institutional facilities increasingly view CHP as an operational efficiency tool rather than only a power asset. Stronger pressure to reduce waste and improve energy productivity continues to support adoption.
- For instance, Siemens Energy states that its CHP solutions can achieve fuel efficiency as high as 90%, and it also references a new district heating power plant using two gas turbine packages with an expected fuel efficiency of 93%.
Demand for on-site energy resilience
Businesses and public institutions are placing greater emphasis on power continuity, especially in facilities where downtime can disrupt operations, safety, or service delivery. CHP systems support resilience by enabling localized generation close to the point of use. This reduces dependence on grid-only supply and strengthens energy security in critical environments. The value proposition is particularly strong in hospitals, industrial plants, campuses, and district energy networks.
- For instance, Thermal Energy Corp. (TECO) operates a natural-gas-fired CHP system at the Texas Medical Center that delivers 48 MW of power to a 19 million square foot medical campus, and the U.S. Department of Energy reported that the system operated without interruption during Hurricane Harvey.
Expansion of distributed energy infrastructure
The market is also benefiting from broader investment in distributed and decentralized energy architectures. End users are increasingly interested in systems that can be integrated into microgrids, hybrid energy setups, and site-level efficiency programs. CHP aligns well with this direction because it can support stable base-load output and useful heat recovery in one platform. This makes the technology relevant across both mature infrastructure markets and rapidly urbanizing regions.
Transition toward cleaner and alternative fuels
Cleaner fuel pathways are reshaping CHP project design and procurement decisions. Natural gas remains central in many deployments, but biomass, biogas, and waste-heat-based CHP are expanding where environmental goals and local economics are favorable. This broadens the application base and improves the strategic fit of CHP within sustainability programs. Fuel flexibility also helps vendors position systems for evolving regulatory expectations and long-term decarbonization planning.
Combined Heat And Power Market Challenges
One of the main challenges in the combined heat and power market is the high upfront capital requirement associated with system installation, site integration, and supporting thermal infrastructure. Project economics can vary widely depending on fuel prices, local regulations, load profile stability, and interconnection requirements. This makes procurement decisions more complex for smaller commercial and institutional buyers. Long payback concerns can delay adoption even when lifecycle efficiency benefits are compelling.
- For instance, the UK government’s CHP case study on Volac’s biomass CHP plant in West Wales reported 2.993 MWe of installed capacity, a £38 million investment cost, and a 10-year payback period, even though the project reduced site carbon emissions by 60% versus the 2014 baseline.
Another challenge is that CHP performance depends heavily on application suitability and continuous thermal utilization. Systems may underperform financially when heat demand is inconsistent or poorly matched with power generation capacity. Regulatory uncertainty around emissions, permitting, and grid export can also complicate deployment in some markets. In addition, technology selection requires technical expertise, which can lengthen sales cycles and reduce adoption speed in less mature customer segments.
Combined Heat And Power Market Trends and Opportunities
A major trend in the combined heat and power market is the growing convergence of CHP with broader distributed energy and decarbonization strategies. Buyers are increasingly evaluating CHP alongside energy storage, renewables integration, and microgrid controls. This is creating opportunities for solution providers that can position CHP as part of a wider energy optimization platform. Digital monitoring and predictive service models are also becoming more important in differentiating vendor offerings.
- For instance, Danone South Africa selected a Jenbacher microgrid solution built around two J616 containerized CHP engines with total capacity of 5 MWe, integrated with the site’s solar PV array, four existing diesel gensets, a waste heat boiler, and a 75,000-liter thermal store, while INNIO states that its myPlant digital platform already connects more than 13,000 active engines across more than 100 countries for real-time monitoring and predictive asset management.
Another opportunity lies in the modernization of district energy systems and industrial energy recovery infrastructure. Many facilities are reassessing legacy boilers, grid dependence, and inefficient thermal processes in favor of integrated generation models. Waste heat recovery, biogas utilization, and flexible modular systems are opening new avenues for adoption beyond conventional fuel-led CHP projects. Vendors that tailor systems by end-use profile and local fuel economics are likely to capture stronger demand.
Regional Insights
North America
North America accounted for 29.6% of the combined heat and power market in 2025, supported by strong industrial infrastructure, established gas networks, and continued interest in resilient on-site generation. Demand is reinforced by commercial buildings, healthcare facilities, campuses, and industrial operators that prioritize energy productivity and continuity. District energy modernization and distributed energy planning also create favorable conditions for CHP deployment. Replacement opportunities across mature installed bases further support market activity.
Europe
Europe accounted for 34.8% of the combined heat and power market in 2025, reflecting solid demand driven by district heating networks, industrial efficiency programs, and policy support for lower-emission energy systems. The regional market benefits from a strong focus on fuel efficiency, energy cost optimization, and modernization of thermal infrastructure. Biomass, biogas, and waste-heat-linked applications are especially relevant across several European countries. Project development is also shaped by long-term energy transition goals and public infrastructure upgrades.
Asia Pacific
Asia Pacific accounted for 24.1% of the combined heat and power market in 2025 and remains a significant growth region due to industrial expansion, urban infrastructure development, and rising electricity demand across manufacturing and commercial sectors. CHP systems are increasingly considered where grid reliability, fuel economics, and energy efficiency are strategic priorities. Large industrial users and expanding urban utility systems create a strong addressable base. The region also presents opportunities for both large-scale and modular decentralized CHP deployments.
Latin America
Latin America accounted for 6.3% of the combined heat and power market in 2025, reflecting selective opportunities for CHP adoption in industrial processing, commercial facilities, and localized energy projects where efficiency improvements can generate measurable cost benefits. Market momentum is influenced by fuel availability, industrial concentration, and project financing conditions. Adoption tends to be more targeted than broad-based, with stronger relevance in sectors that maintain stable thermal demand. Distributed generation trends may gradually strengthen the regional market outlook.
Middle East & Africa
The Middle East and Africa accounted for 5.2% of the combined heat and power market in 2025, supported by opportunities in industrial complexes, utility-linked developments, and large facilities that require dependable and efficient energy supply. Demand is often shaped by localized project economics, industrial diversification efforts, and infrastructure expansion. Energy-intensive facilities and district cooling or heating applications can create favorable use cases in parts of the region. Market development remains uneven but is supported by rising interest in more efficient energy conversion systems.
Competitive Landscape
The combined heat and power market is moderately consolidated around diversified energy equipment providers, engine manufacturers, and specialist distributed generation companies. Competition is shaped by efficiency performance, fuel flexibility, lifecycle service capability, installed base credibility, and the ability to tailor systems by customer load profile. Vendors differentiate through turnkey engineering, maintenance support, digital controls, and integration with broader energy management solutions. Strategic positioning is strongest among companies that can address both large industrial projects and smaller decentralized installations.
GE Vernova holds a strong competitive position through its broad power generation heritage, technology depth, and ability to serve large-scale and complex customer requirements. The company’s approach in CHP is supported by capabilities across gas-based generation, engineering integration, and service networks that are relevant to industrial and utility-linked applications. GE Vernova benefits from brand recognition in high-efficiency power systems and from customer demand for proven equipment platforms. This positioning supports participation in both new-build and modernization opportunities.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- GE Vernova
- Siemens Energy
- Caterpillar Inc.
- Mitsubishi Power
- Wärtsilä
- Kawasaki Heavy Industries
- MAN Energy Solutions
- Bosch Thermotechnology
- Cummins Inc.
- 2G Energy AG
- Capstone Green Energy
- Veolia
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In January 2025, Siemens Energy and Shell announced a strategic partnership to accelerate the deployment of large-scale combined heat and power projects. The collaboration is intended to combine Siemens Energy’s CHP technology expertise with Shell’s financing and project development capabilities for industrial decarbonization projects.
- In August 2025, Catalyst Power Holdings acquired a 4.5 MW portfolio of operational and in-development cogeneration projects from Aegis Energy Services. The company said the deal expands its CHP footprint in key Northeast markets and strengthens its ability to deliver efficient onsite energy solutions to commercial and industrial customers.
- In August 2025, 2G Energy announced that NRGTEQ is formally operating as 2G Energy B.V. after its earlier acquisition, and the company said the business is expanding its focus to include combined heat and power technologies. The update reflects 2G Energy’s effort to strengthen its integrated CHP and heat-pump portfolio in the Dutch market.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 19039 million |
| Revenue forecast in 2032 | USD 30254 million |
| Growth rate (CAGR) | 6.84% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | Technology Outlook, Fuel Type Outlook, Capacity Outlook, End User Outlook |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | GE Vernova, Siemens Energy, Caterpillar Inc., Mitsubishi Power, Wärtsilä, Kawasaki Heavy Industries, MAN Energy Solutions, Bosch Thermotechnology, Cummins Inc., 2G Energy AG, Capstone Green Energy, Veolia |
| No.of Pages | 324 |
Segmentation
By Technology
- Gas Turbine
- Steam Turbine
- Reciprocating Engine
- Microturbine
- Fuel Cell
- Combined Cycle
- Others
By Fuel Type
- Natural Gas
- Coal
- Biomass
- Biogas
- Waste Heat
- Oil / Diesel
- Others
By Capacity
- Up to 100 kW
- 100 kW to 1 MW
- 1 MW to 10 MW
- Above 10 MW
By End User
- Industrial
- Commercial
- Residential
- Institutional
- Utilities / District Energy
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising focus on energy efficiency
Combined heat and power systems maximize fuel utilization by generating both electricity and useful heat from a single input, making them highly attractive for sectors with continuous thermal loads. This dual-output approach supports operational efficiency and cost savings, driving adoption in industrial, institutional, and commercial settings.
Demand for on-site energy resilience
CHP systems enhance energy security by providing localized generation, reducing reliance on the grid and supporting critical facilities such as hospitals, campuses, and industrial plants. The ability to maintain operations during grid outages or disruptions is a key factor fueling market growth.
Expansion of distributed energy infrastructure
The shift toward decentralized and distributed energy systems is increasing demand for CHP, as these solutions can be integrated into microgrids and hybrid energy setups. This trend is particularly strong in regions modernizing their energy infrastructure or seeking to improve grid stability and efficiency.
Transition toward cleaner and alternative fuels
Growing emphasis on sustainability and decarbonization is encouraging the adoption of CHP systems that utilize natural gas, biogas, biomass, and waste heat. These cleaner fuel pathways help end users meet regulatory requirements and environmental targets, broadening the market’s appeal.
Modernization of industrial and district energy systems
Aging thermal infrastructure and the need for improved energy productivity are prompting upgrades and replacements with CHP solutions. Industrial plants and district energy networks are increasingly turning to CHP to reduce emissions, lower costs, and enhance overall system performance.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current and forecast size of the combined heat and power market?
What is the CAGR of the combined heat and power market?
Which segment leads the combined heat and power market?
What is driving growth in the combined heat and power market?
Which companies are profiled in the combined heat and power market report?
Which region leads the combined heat and power market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Capacity
- 1.2.1 Up to 100 kW
- 1.2.2 100 kW to 1 MW
- 1.2.3 1 MW to 10 MW
- 1.2.4 Above 10 MW
- 1.3 By End User
- 1.3.1 Industrial
- 1.3.2 Commercial
- 1.3.3 Residential
- 1.3.4 Institutional
- 1.3.5 Utilities / District Energy
- 1.4 By Fuel Type
- 1.4.1 Natural Gas
- 1.4.2 Coal
- 1.4.3 Biomass
- 1.4.4 Biogas
- 1.4.5 Waste Heat
- 1.4.6 Oil / Diesel
- 1.4.7 Others
- 1.5 By Technology
- 1.5.1 Gas Turbine
- 1.5.2 Steam Turbine
- 1.5.3 Reciprocating Engine
- 1.5.4 Microturbine
- 1.5.5 Fuel Cell
- 1.5.6 Combined Cycle
- 1.5.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 19039 million → 2032: USD 30254 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Combined Heat And Power Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Combined Heat And Power Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Combined Heat And Power Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Combined Heat And Power Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Combined Heat And Power Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Combined Heat And Power Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Combined Heat And Power Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Combined Heat And Power Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 19039 million → 2032: USD 30254 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Combined Heat And Power Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Capacity - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Up to 100 kW
- 12.3.7.2 100 kW to 1 MW
- 12.3.7.3 1 MW to 10 MW
- 12.3.7.4 Above 10 MW
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Industrial
- 12.4.7.2 Commercial
- 12.4.7.3 Residential
- 12.4.7.4 Institutional
- 12.4.7.5 Utilities / District Energy
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Fuel Type - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Natural Gas
- 12.5.7.2 Coal
- 12.5.7.3 Biomass
- 12.5.7.4 Biogas
- 12.5.7.5 Waste Heat
- 12.5.7.6 Oil / Diesel
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Technology - Market Size and Forecast, 2025-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2025-2032
- 12.6.4 Volume Forecast, 2025-2032
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Gas Turbine
- 12.6.7.2 Steam Turbine
- 12.6.7.3 Reciprocating Engine
- 12.6.7.4 Microturbine
- 12.6.7.5 Fuel Cell
- 12.6.7.6 Combined Cycle
- 12.6.7.7 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Combined Heat And Power End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Combined Heat And Power Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Combined Heat And Power Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Combined Heat And Power Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 GE Vernova
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Siemens Energy
- 18.4 Caterpillar Inc.
- 18.5 Mitsubishi Power
- 18.6 Wärtsilä
- 18.7 Kawasaki Heavy Industries
- 18.8 MAN Energy Solutions
- 18.9 Bosch Thermotechnology
- 18.10 Cummins Inc.
- 18.11 2G Energy AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

