
Market Overview
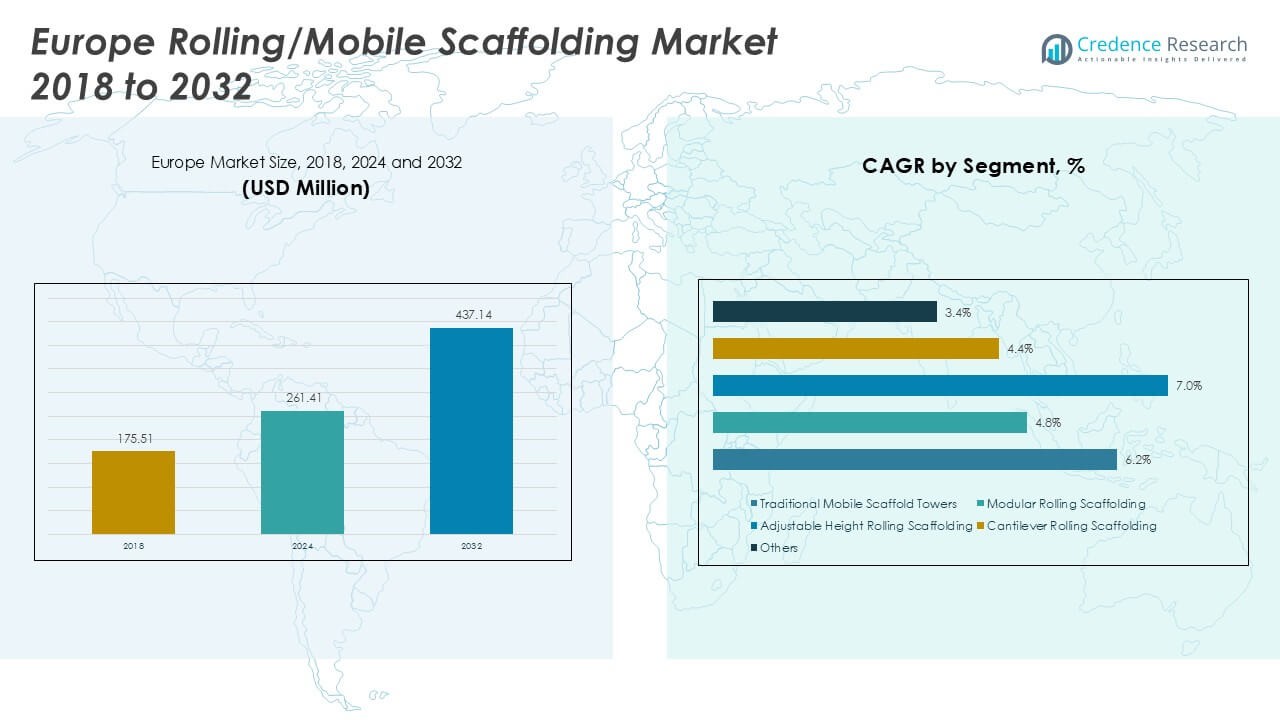
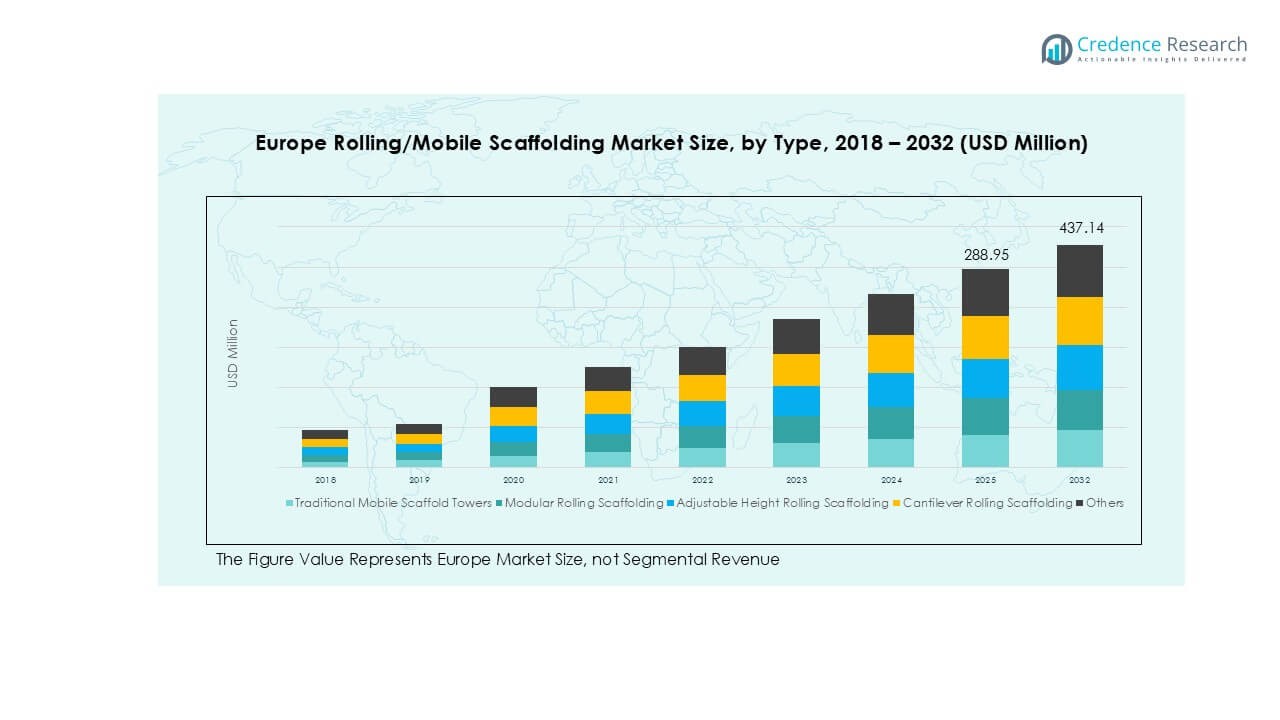
The Europe Rolling/Mobile Scaffolding market size was valued at USD 175.51 million in 2018 and grew to USD 261.41 million in 2024. It is anticipated to reach USD 437.14 million by 2032, expanding at a CAGR of 6.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Rolling Mobile Scaffolding Market Size 2024 | USD 261.41 Million |
| Europe Rolling Mobile Scaffolding Market, CAGR | 6.1% |
| Europe Rolling Mobile Scaffolding Market Size 2032 | USD 437.14 Million |
The Europe Rolling/Mobile Scaffolding market is led by prominent players such as Euroscaffold Netherlands, Altrad Group, GBM Italy, ZARGES, Altrex, and Hünnebeck GmbH, each offering a broad range of scaffolding systems tailored to meet stringent European safety standards. These companies maintain a competitive edge through product innovation, regional expansion, and robust rental networks. Germany emerged as the leading regional market in 2024, accounting for 23% of the total European market share, driven by its advanced construction sector and strong industrial maintenance activities. The United Kingdom and France followed, with 19% and 17% market shares respectively, supported by infrastructure modernization, renovation projects, and strict workplace safety regulations.
Market Insights
- The Europe Rolling/Mobile Scaffolding market was valued at USD 261.41 million in 2024 and is projected to reach USD 437.14 million by 2032, growing at a CAGR of 6.1% during the forecast period.
- Market growth is driven by increasing urban infrastructure projects, rising demand for building maintenance and retrofitting, and strict enforcement of worker safety regulations across Europe.
- Key trends include the rising use of lightweight aluminuim scaffolding, growth in rental services, and integration of modular, ergonomic designs to improve safety and efficiency on-site.
- Leading companies such as Euroscaffold Netherlands, Altrad Group, and ZARGES dominate the market through innovation, regional expansions, and product diversification, while smaller players compete in niche segments.
- Regionally, Germany leads with a 23% share, followed by the UK (19%) and France (17%). Segment-wise, traditional mobile scaffold towers and aluminuim-based systems hold the highest shares due to their adaptability and ease of use.
Market Segmentation Analysis:
By Type
In the Europe Rolling/Mobile Scaffolding market, Traditional Mobile Scaffold Towers emerged as the dominant sub-segment in 2024, accounting for over 35% of the market share. Their widespread use in residential and commercial construction, driven by ease of assembly, mobility, and cost-effectiveness, contributes to their leading position. Meanwhile, Modular Rolling Scaffolding is gaining traction due to its versatility in complex architectural projects and multi-level work platforms. The increasing demand for flexible and safety-enhanced scaffolding solutions across renovation and infrastructure upgrade projects in urban areas continues to fuel growth across all type-based segments.
- For instance, Altrex’s RS TOWER 52 module system supports working heights up to 14.2 meters for indoor use and 10.2 meters for outdoor setups, highlighting the popularity of modular towers in variable site conditions.
By Material:
Aluminium-based rolling scaffolding led the material segment, holding more than 48% of the market share in 2024. This dominance is attributed to aluminium’s lightweight, corrosion-resistant properties and ease of transportation, making it ideal for quick setup and frequent relocation. The growing adoption of sustainable and recyclable materials in construction further supports the segment’s expansion. Steel scaffolding, known for its strength and durability, remains crucial in heavy-duty industrial applications, while composite materials are slowly emerging as a niche solution, driven by innovation in hybrid scaffolding structures.
- For instance, ZARGES manufactures rolling towers with high-strength aluminium that reduce unit weight to as low as 65.5 kg for full scaffold configurations, allowing faster repositioning and setup in high-frequency work cycles.
By Application:
The Construction segment dominated the application landscape, capturing approximately 52% of the market share in 2024. Rolling scaffolding systems are extensively used in residential, commercial, and infrastructure projects for tasks such as painting, plastering, and exterior maintenance. The rising trend of renovation and energy-efficient retrofitting across Europe is driving consistent demand in this segment. Maintenance and Repairs followed closely, particularly in industrial and municipal facilities, where mobility and quick deployment are essential. Meanwhile, the Warehousing and Logistics sub-segment is expanding steadily due to growing automation needs and facility upgrades requiring temporary elevated access.
Key Growth Drivers
Rising Urban Infrastructure Development
The rapid pace of urbanization across Europe is fueling demand for modern construction and renovation projects, especially in residential and commercial sectors. Governments and private developers are heavily investing in urban renewal, energy-efficient buildings, and public infrastructure, which require safe, mobile, and flexible access systems. Rolling/mobile scaffolding provides ideal support for multi-level access, especially in confined or complex architectural environments, thereby gaining widespread adoption. This surge in urban construction activity continues to serve as a critical growth engine for scaffolding equipment manufacturers across the region.
- For instance, Hünnebeck GmbH supported over 200 commercial infrastructure projects across Germany, France, and Poland in 2023 using its mobile scaffolding systems, enabling consistent supply for vertical access solutions in urban cores.
Growing Emphasis on Worker Safety and Compliance
Stringent occupational safety regulations enforced by European agencies such as OSHA and EU-OSHA are propelling the use of secure access platforms like mobile scaffolding. Traditional access methods are being phased out in favor of systems that meet higher safety and ergonomic standards. Rolling scaffolding, with features like guardrails, lockable wheels, and height adjustability, ensures compliance with these guidelines while minimizing accident risks. This increased focus on worker protection and regulatory adherence is driving organizations to invest in advanced, safety-enhanced scaffolding solutions.
- For instance, the Altrad Group reported a 27% reduction in on-site incidents after deploying its UniTech scaffolding systems with integrated toe boards, fall arrest points, and double guardrail mechanisms across its European projects.
Increasing Demand for Refurbishment and Maintenance Projects
Europe’s mature real estate and industrial sectors are witnessing a spike in maintenance, repair, and refurbishment activities, particularly in aging buildings and historical structures. These projects require mobile and adjustable scaffolding that offers quick assembly and disassembly with minimal disruption. Rolling scaffolding solutions address this need effectively, enabling efficient access in operational facilities or restricted urban environments. The market benefits from this trend, as demand rises from both public and private sectors undertaking periodic upgrades and retrofitting initiatives.
Key Trends & Opportunities
Integration of Lightweight and Sustainable Materials
The use of lightweight materials such as aluminium and composite alloys is becoming increasingly common, driven by the need for easy-to-transport and energy-efficient solutions. These materials not only reduce labor fatigue but also lower the environmental impact, aligning with Europe’s strong sustainability goals. Manufacturers are innovating product lines with recyclable, corrosion-resistant materials that maintain structural integrity without adding bulk. This trend opens new opportunities for suppliers to align their offerings with green building standards and attract eco-conscious buyers.
- For instance, Mauderer Alutechnik offers mobile scaffolds made from 100% recyclable EN AW-6082 aluminium, contributing to a company-wide initiative that processed over 740 metric tons of recycled aluminium in 2023 alone.
Technological Advancements in Scaffold Design and Manufacturing
The industry is witnessing a shift toward digitalized and modular scaffolding systems. Advanced features such as tool-less assembly mechanisms, modular connectors, and CAD-driven customization are gaining popularity among end-users seeking efficiency and adaptability. The adoption of ergonomic design practices is also improving worker productivity and safety. Additionally, 3D modeling and simulation tools are enabling more accurate on-site scaffold planning. These innovations not only streamline operations but also offer differentiation for manufacturers in a highly competitive market.
- For instance, GBM Italy integrated 3D modeling software into its product design in 2022, leading to a 38% improvement in prototype-to-market turnaround times for new modular scaffolding systems.
Key Challenges
High Initial Costs and Price Sensitivity
Despite the long-term benefits, the high upfront cost of quality rolling scaffolding systems acts as a deterrent for small contractors and budget-sensitive projects. Many SMEs opt for traditional or rental equipment to avoid capital expenditure, which slows adoption rates for advanced scaffolding. Additionally, fluctuating raw material prices, particularly for aluminium and steel, affect production costs and price competitiveness. This challenge necessitates flexible pricing strategies and value-driven product differentiation for sustained market penetration.
Limited Awareness Among Smaller Enterprises
While large construction firms recognize the advantages of mobile scaffolding, awareness and adoption remain limited among small and medium-sized enterprises (SMEs), especially in Eastern and Southern Europe. These firms often rely on conventional scaffolding or ladders due to limited technical knowledge and training. The lack of targeted outreach, on-site demonstrations, and education around the benefits of rolling scaffolding impedes wider market adoption. Overcoming this barrier will require collaborative efforts between manufacturers, regulators, and training institutions.
Regional Analysis
United Kingdom
The United Kingdom held approximately 19% of the Europe Rolling/Mobile Scaffolding market in 2024, driven by a strong construction sector and ongoing urban regeneration projects across cities like London, Manchester, and Birmingham. The UK's strict regulatory focus on worker safety and scaffold quality standards continues to favor mobile scaffolding adoption, especially among contractors involved in public infrastructure upgrades and residential retrofits. Additionally, the growing emphasis on sustainable construction practices has led to increased demand for lightweight aluminium scaffolding. Rising investments in the housing sector and maintenance of aging public buildings further support the growth of mobile scaffolding solutions.
France
France accounted for nearly 17% of the regional market in 2024, supported by robust public infrastructure development and an active refurbishment sector. The French government's initiatives for energy-efficient building upgrades, such as retrofitting and facade renewals, are major contributors to market demand. Mobile scaffolding is increasingly used in urban restoration projects and cultural heritage site maintenance, where mobility and minimal structural interference are critical. The construction of eco-districts and large-scale transport projects like Grand Paris Express also sustains demand. Local manufacturers and rental companies continue to innovate scaffolding systems to comply with evolving safety norms and construction needs.
Germany
Germany led the Europe Rolling/Mobile Scaffolding market in 2024, capturing approximately 23% of the market share. The country’s well-established construction sector, combined with a high volume of industrial maintenance work, drives consistent demand for mobile scaffolding. German firms prioritize precision, safety, and durability, pushing demand for modular, high-load-bearing scaffolds. Strong investment in residential energy efficiency programs, industrial retrofits, and automotive manufacturing facilities further propels market growth. Germany’s leadership in automation and smart construction practices also encourages the integration of innovative scaffolding designs that align with modern building technologies and digital construction workflows.
Italy
Italy held about 12% of the European mobile scaffolding market in 2024, supported by a resurgence in building restoration and seismic retrofit projects. The country’s large inventory of aging infrastructure and historical architecture demands non-invasive, adaptable scaffolding systems, making rolling scaffolding a preferred choice. Public initiatives promoting sustainable urban development, along with renovation tax incentives, are boosting scaffolding demand, particularly in central and southern regions. Although the market remains price-sensitive, growing awareness around construction safety and improved scaffold designs is gradually driving adoption. The rental market continues to expand as contractors seek flexible and cost-effective solutions.
Spain
Spain contributed around 10% of the regional market share in 2024, largely driven by growth in residential construction and tourism-related renovations. Rolling scaffolding is widely used in maintenance of hotels, public buildings, and coastal infrastructure. Spain’s recovery from earlier economic slowdowns has reignited interest in energy-efficient housing and commercial properties, driving refurbishment projects that rely heavily on mobile access systems. While adoption remains fragmented across regions, major urban centers like Madrid and Barcelona show stronger uptake of advanced scaffolding due to stricter safety standards and urban renewal plans. Increased investments in transport infrastructure also support segment expansion.
Russia
Russia accounted for approximately 9% of the European Rolling/Mobile Scaffolding market in 2024. Despite economic fluctuations and geopolitical tensions, the country maintains a steady demand for scaffolding in its industrial and residential sectors. The growing number of energy infrastructure projects, especially in oil and gas, as well as urban development in cities like Moscow and St. Petersburg, are key market drivers. However, challenges related to import restrictions and currency volatility affect the availability and pricing of premium scaffolding solutions. Domestic production is expanding to meet demand, although safety regulations remain inconsistent compared to Western European standards.
Rest of Europe
The Rest of Europe, including countries such as Poland, Netherlands, Belgium, and the Nordic nations, collectively held about 10% of the regional market in 2024. These markets are witnessing steady growth fueled by infrastructure upgrades, smart city initiatives, and demand for compact scaffolding systems in urban environments. Poland and the Czech Republic, in particular, are investing heavily in residential housing and public facilities, while Scandinavian countries focus on green building and workplace safety. The rental model dominates in these regions, especially among SMEs seeking affordable, temporary access solutions. Market players are focusing on product innovation to meet varying compliance standards.
Market Segmentations:
By Type:
- Traditional Mobile Scaffold Towers
- Modular Rolling Scaffolding
- Adjustable Height Rolling Scaffolding
- Cantilever Rolling Scaffolding
- Others
By Material:
- Aluminium
- Steel
- Composite Materials
By Application:
- Construction
- Maintenance and Repairs
- Industrial Operations
- Warehousing and Logistics
- Others
By End User:
- Residential Construction
- Commercial Construction
- Industrial Sectors
- Municipal and Infrastructure Projects
- Others
By Geography:
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
Competitive Landscape
The Europe Rolling/Mobile Scaffolding market features a moderately fragmented competitive landscape, with a mix of regional specialists and pan-European players. Key companies such as Euroscaffold Netherlands, Altrad Group, ZARGES, GBM Italy, and Hünnebeck GmbH maintain strong market positions through product innovation, extensive distribution networks, and strategic partnerships. These companies compete primarily on safety standards, material quality, modularity, and ease of assembly. Local players like Altrex and Munk Günzburger Steigtechnik focus on serving niche regional demands with tailored solutions and responsive customer support. Several players are expanding their rental services to cater to cost-sensitive clients and SMEs. Technological advancements, such as integration of lightweight materials and ergonomic designs, continue to shape competitive dynamics. Furthermore, ongoing efforts to align products with evolving EU safety regulations give a competitive edge to manufacturers that prioritize compliance. Mergers, acquisitions, and facility expansions remain key strategies for growth and market consolidation among leading players.
Key Player Analysis
- Euroscaffold Netherlands
- GBM Italy
- Altrad Group
- Altrex
- ZARGES
- Hünnebeck GmbH
- TUBESCA
- Munk Günzburger Steigtechnik
- SARAYLI LTD.
- Mauderer Alutechnik
Recent Developments
- In May 2025, Layher continues its focus on lightweight aluminium scaffolding systems, particularly for the European and North American markets, with a strong emphasis on advanced, modular, and mobile solutions. While no specific new product launches are mentioned in the provided information for 2025, Layher's ongoing research and development efforts are consistently highlighted for their contributions to quicker and safer assembly, especially concerning rolling and mobile scaffolding systems.
- In April 2025, PERI showcased further development and expansion of the PERI UP Scaffolding Kit, including the introduction of "PERI UP Public" components. These focus on quick installation and safety, specifically for public sector needs, with stairs and access points that meet strict safety standards and require minimal additional components. The modular logic allows more with fewer components, improving efficiency for rolling/mobile scaffolding use. The company also emphasized sustainability and introduced digital solutions (e.g., SYFIT, VEMAVENTURI) for management and safety on construction sites.
- In January 2025, BrandSafway showcased several innovations at the World of Concrete 2025, including enhancements to the QuikDeck® Suspended Access System, new multi-level platform options, and the launch of Flexi Deck, a lightweight, manually movable slab formwork system designed for faster early dismantling and improved site coverage.
Market Concentration & Characteristics
The Europe Rolling/Mobile Scaffolding Market exhibits moderate market concentration, with several established players dominating key national markets while regional manufacturers serve niche demands. It features a mix of global brands and specialized companies that focus on high-quality, safety-compliant scaffolding systems. Market characteristics include a strong emphasis on lightweight materials, modular construction, and ease of mobility to support rapid deployment across varied construction environments. Demand remains consistent in residential and commercial renovation projects, particularly in countries with aging infrastructure. Companies compete on safety standards, regulatory compliance, durability, and rental service offerings. Germany, the UK, and France account for the largest market shares, reflecting their active construction sectors and strict safety mandates. The rental model continues to grow, driven by cost-conscious contractors and small to mid-sized enterprises. Innovation in ergonomic design and digital planning tools supports competitive differentiation. The market responds steadily to EU directives, with safety and sustainability shaping product development and procurement preferences.
Report Coverage
The research report offers an in-depth analysis based on Type, Material, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to witness steady growth driven by increasing demand for renovation and infrastructure upgrade projects across Europe.
- Adoption of lightweight and modular scaffolding systems will continue to rise due to ease of transport and installation.
- Rental-based scaffolding services will gain traction among SMEs and contractors seeking cost-efficient solutions.
- Stringent safety regulations across European countries will encourage wider use of compliant and secure mobile scaffolding systems.
- Urbanization and expansion of smart city initiatives will support demand for mobile scaffolding in tight and complex project environments.
- Use of aluminium and composite materials will increase due to their durability, sustainability, and corrosion resistance.
- Technological advancements such as quick-lock systems and ergonomic features will shape future product innovation.
- Growth in industrial maintenance activities will further boost the need for mobile scaffolding with flexible height and mobility features.
- Market competition will intensify as both global and regional players invest in product differentiation and service expansion.
- Eastern and Southern Europe will present new growth opportunities as awareness and adoption improve among smaller construction firms.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Urban Infrastructure Development
Accelerated urbanization across Europe is driving demand for modern construction and renovation projects, particularly in residential and commercial sectors. This trend increases the need for safe, mobile, and flexible access systems like rolling/mobile scaffolding, especially in complex or confined architectural environments.
Stringent Worker Safety Regulations
European agencies enforce strict occupational safety standards, prompting the adoption of advanced mobile scaffolding systems with features such as guardrails and lockable wheels. Compliance with these regulations is essential, leading organizations to invest in safer, more ergonomic scaffolding solutions.
Growth in Refurbishment and Maintenance Projects
Europe’s aging building stock and industrial facilities require frequent maintenance, repair, and retrofitting. Rolling scaffolding offers quick assembly and mobility, making it ideal for refurbishment projects in operational or restricted urban environments.
Adoption of Lightweight and Sustainable Materials
The shift toward aluminium and composite scaffolding is driven by the need for easy transport, reduced labor fatigue, and alignment with sustainability goals. These materials support faster setup and repositioning, appealing to contractors focused on efficiency and environmental responsibility.
Expansion of Rental-Based Scaffolding Services
Cost-sensitive SMEs and contractors increasingly prefer renting scaffolding systems to avoid high upfront investments. The growth of rental networks across Europe is making advanced rolling/mobile scaffolding more accessible, supporting broader market adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe Rolling/Mobile Scaffolding, and what is its projected size in 2032?
At what Compound Annual Growth Rate (CAGR) is the Europe Rolling/Mobile Scaffolding market projected to grow between 2025 and 2032?
Which Europe Rolling/Mobile Scaffolding market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Europe Rolling/Mobile Scaffolding market?
Who are the leading companies in the Europe Rolling/Mobile Scaffolding market?
Which region commanded the largest share of the Europe Rolling/Mobile Scaffolding market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Traditional Mobile Scaffold Towers
- 1.2.2 Modular Rolling Scaffolding
- 1.2.3 Adjustable Height Rolling Scaffolding
- 1.2.4 Cantilever Rolling Scaffolding
- 1.2.5 Others
- 1.3 By Material
- 1.3.1 Aluminium
- 1.3.2 Steel
- 1.3.3 Composite Materials
- 1.4 By Application
- 1.4.1 Construction
- 1.4.2 Maintenance and Repairs
- 1.4.3 Industrial Operations
- 1.4.4 Warehousing and Logistics
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 261.41 million → 2032: USD 437.14 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Rolling/Mobile Scaffolding Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Rolling/Mobile Scaffolding Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Rolling/Mobile Scaffolding Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Rolling/Mobile Scaffolding Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Rolling/Mobile Scaffolding Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Rolling/Mobile Scaffolding Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Rolling/Mobile Scaffolding Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Rolling/Mobile Scaffolding Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 261.41 million → 2032: USD 437.14 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Rolling/Mobile Scaffolding Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Traditional Mobile Scaffold Towers
- 12.3.7.2 Modular Rolling Scaffolding
- 12.3.7.3 Adjustable Height Rolling Scaffolding
- 12.3.7.4 Cantilever Rolling Scaffolding
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Aluminium
- 12.4.7.2 Steel
- 12.4.7.3 Composite Materials
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Construction
- 12.5.7.2 Maintenance and Repairs
- 12.5.7.3 Industrial Operations
- 12.5.7.4 Warehousing and Logistics
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Rolling/Mobile Scaffolding End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Rolling/Mobile Scaffolding Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Rolling/Mobile Scaffolding Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Rolling/Mobile Scaffolding Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Euroscaffold Netherlands
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Altrad Group
- 18.4 GBM Italy
- 18.5 ZARGES
- 18.6 Altrex
- 18.7 Hünnebeck GmbH
- 18.8 TUBESCA
- 18.9 Munk Günzburger Steigtechnik
- 18.10 Mauderer Alutechnik
- 18.11 SARAYLI LTD.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

