
Market Overview
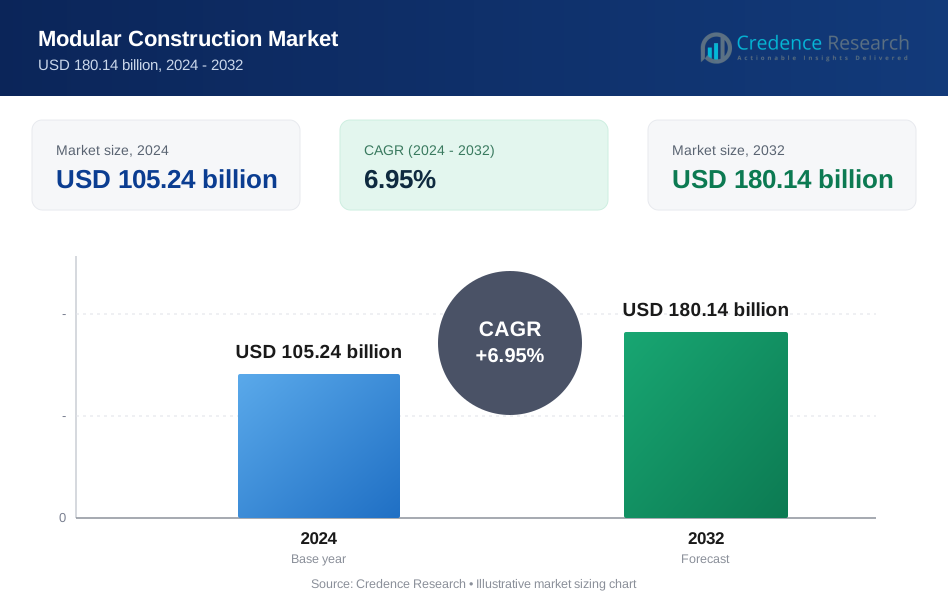
Modular Construction Market size was valued USD 105.24 billion in 2024 and is anticipated to reach USD 180.14 billion by 2032, at a CAGR of 6.95% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Modular Construction Market Size 2024 | USD 105.24 Billion |
| Modular Construction Market, CAGR | 6.95% |
| Modular Construction Market Size 2032 | USD 180.14 Billion |
The modular construction market such as Premier Modular Limited, Skanska, LEUSBERG GmbH & Co KG, DuBox, Bouygues Construction, CIMC Modular Building Systems Holdings Co., Ltd., Wernick Group, LAING O’ROURKE, Red Sea International, and Sekisui House Ltd. aggressively expand their modular capabilities to address rising demand for scalable, sustainable construction. These firms leverage off-site production, digital design integration, and global partnerships to strengthen their competitive positions. Regionally, Asia-Pacific leads the global modular construction market, commanding approximately 47 % of revenue share, driven by rapid urbanization, strong manufacturing capabilities, and supportive government housing policies.
Market Insights
- The modular construction market size reached USD 105.24 billion in 2024 and is projected to hit USD 180.14 billion by 2032, registering a CAGR of 6.95% during the forecast period.
- Rising demand for faster project delivery, labor efficiency, and sustainable building methods drives broader adoption of volumetric and panelized modular systems across residential and commercial segments.
- Advanced manufacturing automation, BIM-enabled design, and standardized modular platforms shape the key market trends, enabling reduced construction time and improved cost predictability.
- Competitive intensity increases as major players expand global capacity and invest in digital fabrication, though challenges such as high initial setup costs and transportation constraints restrain wider penetration.
- Asia-Pacific dominates with nearly 47% market share, benefiting from large-scale urban development and strong factory-based production capacity, while the residential segment continues to lead overall adoption due to rapid housing demand.
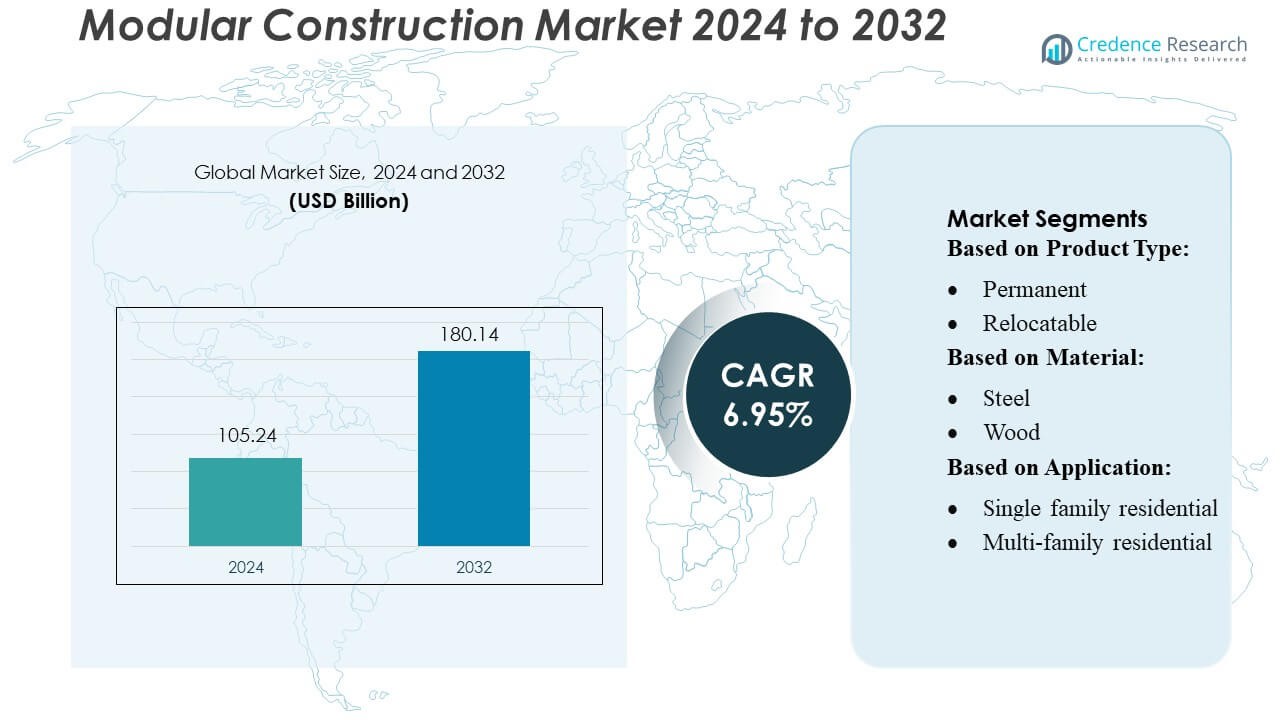
Market Segmentation Analysis:
By Product Type
The permanent modular segment dominates the modular construction market, accounting for an estimated 65 % share, driven by growing demand for high-quality, long-lifespan structures across residential, healthcare, and commercial sectors. Its market leadership stems from improved structural integrity, reduced lifecycle costs, and the ability to integrate advanced building systems with factory precision. Relocatable modular units capture the remaining share, supported by rising adoption in temporary offices, classrooms, and disaster-relief facilities; however, their growth is comparatively slower due to shorter service life and fewer customization capabilities.
- For instance, Novartis Cambridge Campus Expansion project, Skanska prefabricated mechanical, plumbing, lab gas, telecom-data, and electrical systems into custom rack modules in their warehouse, cutting 5,600 high-risk labor hours and saving eight weeks from the project schedule.
By Material
Steel leads the material segmentation with an estimated 45 % share, supported by its superior strength-to-weight ratio, high recyclability, and ability to support multi-story modular buildings. Demand for steel modules continues to rise as developers prioritize durability, fire resistance, and long-term structural stability. Wood follows as a fast-growing material, driven by sustainability concerns and lower construction costs, particularly in low-rise residential applications. Concrete modules hold a moderate share, favored for sound insulation and thermal performance, while materials like aluminum, polyurethane, and glass fiber serve niche, lightweight, and specialty design requirements.
- For instance, KLEUSBERG GmbH & Co. KG (the company often confused with “Leusberg”) delivered a modular administration building in Zwickau comprising 236 steel modules, which were assembled into an 8,800 m² structure in just 28 days.
By Application
The multi-family residential segment holds the largest market share at roughly 35 %, supported by urban housing shortages, faster project timelines, and improved cost efficiency delivered by modular manufacturing. Developers increasingly prefer modular methods to meet demand for affordable and mid-segment housing with consistent quality. Single-family residential units follow, driven by customization flexibility and reduced on-site labor needs. Offices, hospitality, and retail segments continue expanding due to rapid commercial project deployment. Healthcare and educational buildings also show strong uptake as modular designs allow scalable expansions, controlled manufacturing environments, and accelerated facility readiness.
Key Growth Drivers
Rapid Project Delivery and Cost Efficiency Accelerated construction timelines remain a primary growth driver in the modular construction market, as off-site manufacturing reduces on-site disruptions, labor requirements, and weather-related delays. Developers increasingly adopt modular solutions to shorten project schedules by up to 30–50% while lowering overall costs. The ability to conduct site preparation and module fabrication simultaneously enhances productivity and enables earlier revenue generation for commercial and residential projects. These efficiencies are particularly attractive for time-sensitive sectors such as healthcare, hospitality, and multifamily housing, where speed-to-market is a critical competitive advantage.- For instance, DuBox facility produces 16 volumetric concrete modules per day, shifting 85% of work from on-site to factory conditions. This approach cut manpower requirements by 30% during the Red Sea Global project.
- For instance, Bagneux modular middle school project, Bouygues prefabricated over 100 wooden modules off-site using roughly 131 kg/m² of bio-sourced materials.
Key Trends & Opportunities
Technological Advancements in Modular Design and Automation Digitalization is reshaping modular construction, with BIM-integrated workflows, automated fabrication, and advanced robotics enhancing precision and quality. Manufacturers increasingly use 3D volumetric design, digital twins, and AI-driven planning tools to reduce errors, optimize material use, and streamline supply chains. These technologies enable mass customization, faster prototyping, and improved collaboration between architects and engineers. As automation scales, production facilities achieve higher throughput, providing opportunities for developers to deliver large-scale residential, commercial, and institutional projects with consistent performance and minimized rework costs.- For instance, CIMC Modular Building Systems (CIMC MBS) flagship factory in Jiangmen, staffed by 4,000 employees, outputs around 8,000 modules annually. CIMC uses patented high-strength bolt connection technology in its steel-structure modules, enabling buildings that exceed 100 meters in height.
- For instance, Peterborough Hospital, Wernick installed a two-storey building using 22 modules, adding 20 beds including en-suite facilities, alongside reception, pantry, offices, and utility rooms.
Key Challenges
Transportation Limitations and Logistics Complexity Transportation constraints remain a major challenge for modular construction, as volumetric units require specialized handling, oversized-load permits, and well-coordinated logistics. Distance between manufacturing plants and job sites affects cost efficiency, and navigating narrow roads or urban environments can lead to delays. Additionally, damage risks during transport increase insurance costs and require reinforced packaging. These logistical hurdles limit modular construction’s scalability in remote or congested regions. Overcoming these challenges will require strategic factory locations, advanced transportation planning, and innovations in module sizing and assembly. Regulatory Barriers and Lack of Standardization The modular construction market faces compliance challenges due to inconsistent building codes, zoning requirements, and permitting processes across regions. Traditional regulations often do not account for off-site manufacturing, causing approval delays and increased administrative burden. Variations in industry standards-such as fire safety, structural design, and module certification-further complicate cross-border or multi-state operations. Developers and manufacturers must navigate fragmented regulatory ecosystems, which slows adoption and increases project risk. Establishing unified standards and modular-friendly policies will be essential for accelerating market growth and improving industry-wide efficiency.Regional Analysis
North America
North America holds an estimated 35–38% share of the modular construction market, driven by strong adoption in healthcare, education, and multifamily housing. The region benefits from high labor costs and skilled labor shortages, which make off-site construction an attractive alternative for reducing project timelines and improving cost efficiency. Government support for sustainable building practices and increasing investments in modular commercial spaces further strengthen growth. The U.S. leads regional demand with rising interest in permanent modular solutions for residential and institutional applications, while Canada sees expanding uptake in remote and industrial infrastructure projects.
Europe
Europe accounts for roughly 28–30% of the global market, supported by stringent environmental regulations, increasing green-building certifications, and high demand for energy-efficient construction. Countries such as the U.K., Germany, and the Netherlands lead adoption as modular methods align with carbon-reduction targets and circular economy principles. The region sees strong growth in modular residential buildings due to urban housing shortages and government-backed affordable housing programs. Advanced manufacturing technologies and well-established quality standards further enhance market penetration, enabling modular builders to deliver high-performance structures with reduced waste and faster completion timelines.
Asia-Pacific
Asia-Pacific represents the fastest-growing region with an estimated 30–32% share, driven by rapid urbanization, infrastructure expansion, and large-scale residential development across China, Japan, and Australia. Governments increasingly promote modular construction to meet rising housing demand and improve construction productivity. China leads the region with extensive adoption of high-rise modular buildings, while Japan benefits from precision manufacturing and advanced modular engineering. Growing investments in commercial and hospitality projects, along with disaster-resilient building requirements, further accelerate regional growth. The scalability and speed of modular solutions make them particularly suitable for densely populated urban environments.
Latin America
Latin America holds a smaller but expanding share of around 4–5%, supported by the growing need for affordable housing, disaster-relief structures, and rapid commercial expansions. Countries such as Brazil, Mexico, and Chile increasingly adopt modular solutions to address construction delays, budget constraints, and labor shortages. The region shows rising interest in relocatable units for mining camps, remote industrial sites, and educational facilities. Although infrastructure limitations and funding constraints slow broader adoption, improving governmental focus on efficient building methods and private-sector investment in modular technologies contribute to steady market growth.
Middle East & Africa
The Middle East & Africa region captures approximately 3–4% share, with growth concentrated in the Gulf countries where large-scale infrastructure and hospitality projects drive demand. Modular construction supports rapid project deployment, especially for worker accommodations, hotels, and healthcare facilities. The UAE and Saudi Arabia lead adoption as part of smart city and megaproject developments that prioritize speed and cost efficiency. In Africa, modular solutions gain traction for schools, clinics, and housing projects in remote areas. Despite challenges related to manufacturing capacity and skilled labor, increasing public-private partnerships support gradual market expansion.
Market Segmentations:
By Product Type:
- Permanent
- Relocatable
By Material:
- Steel
- Wood
By Application:
- Single family residential
- Multi-family residential
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The modular construction market features a diverse competitive landscape led by Premier Modular Limited, Skanska, LEUSBERG GmbH & Co KG, DuBox, Bouygues Construction, CIMC Modular Building Systems Holdings Co., Ltd., Wernick Group, LAING O'ROURKE, Red Sea International, and Sekisui House Ltd. The modular construction market exhibits a highly competitive landscape driven by rising demand for faster project delivery, cost efficiency, and sustainability-focused building solutions. Companies compete through advancements in off-site manufacturing, integration of digital design technologies, and improved structural engineering capabilities that support large-scale and multi-story modular projects. The industry continues to shift toward automated production lines, precision-driven fabrication, and standardized module platforms that enable scalability across regions. Strategic partnerships, cross-border expansion, and investments in R&D further strengthen competitive positions, while firms increasingly prioritize low-carbon materials and waste-reduction practices to meet regulatory and client expectations. As competition intensifies, market participants differentiate through specialized offerings in residential, healthcare, commercial, and remote-site applications, along with service models that ensure faster installation and reduced lifecycle costs.
Key Player Analysis
- Premier Modular Limited
- Skanska
- LEUSBERG GmbH & Co KG
- DuBox
- Bouygues Construction
- CIMC Modular Building Systems Holdings Co., Ltd.
- Wernick Group
- LAING O'ROURKE
- Red Sea International
- Sekisui House Ltd.
Recent Developments
- In July 2025, New Holland Construction W100D compact wheel loader was launched, featuring a redesigned, operator-centric cab focused on comfort and control, and a compact design for high productivity.
- In January 2025, Sunbelt Modular Inc. acquired BRITCO Structures, USA (BUSA), a Texas-based manufacturer of modular buildings known for complex commercial projects. This acquisition, which was finalized aligns with Sunbelt's strategy of providing custom modular solutions.
- In January 2025, Volvo CE introduces New Generation Excavators in Southeast Asia to enhance efficiency, productivity and safety of the customers. The New Generation 5 models include: EC210, EC220, EC230, EC300 and EC360 and they will be sold throughout the region starting January 2025.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will adopt more automated and robotics-driven modular manufacturing to improve precision and reduce labor dependency.
- Demand for sustainable and low-carbon modular materials will rise as governments strengthen green building regulations.
- Digital twins and BIM-integrated workflows will become standard tools for optimizing module design and project planning.
- Urban housing shortages will accelerate the use of modular systems for affordable and rapid residential development.
- Large infrastructure and healthcare projects will increasingly shift to modular due to faster timelines and predictable quality.
- Cross-border module supply chains will expand as firms standardize components for global deployment.
- Hybrid modular–traditional construction models will gain traction to address complex architectural requirements.
- Investors will show growing interest in modular platforms as stable, scalable, and repeatable construction solutions.
- Smart-building technologies will be integrated directly into modules during factory assembly.
- Companies will focus on circular design principles to enhance recyclability and reduce construction waste.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Project Delivery and Cost Efficiency
Off-site modular manufacturing enables simultaneous site preparation and module fabrication, reducing construction timelines by up to 30–50% and lowering labor costs. This efficiency is especially attractive for sectors where speed-to-market is critical, such as healthcare, hospitality, and multifamily housing.
Demand for Sustainable and Energy-Efficient Buildings
Controlled factory environments minimize material waste and support the integration of green technologies, helping developers and governments meet regulatory and ESG targets. Modular construction's ability to use recyclable materials and reduce lifecycle emissions appeals to environmentally conscious clients.
Growing Urbanization and Housing Shortages
High-density urban areas face acute housing shortages and rising land costs, prompting developers to adopt modular systems for scalable, affordable, and rapid residential construction. Government incentives and public housing initiatives further accelerate adoption in urban centers.
Technological Advancements in Modular Design and Automation
The integration of BIM, digital twins, and automated fabrication enhances design precision, reduces errors, and streamlines supply chains. These technologies enable mass customization and higher throughput, making large-scale modular projects more feasible and cost-effective.
Expansion into Healthcare and Commercial Sectors
The need for quickly deployable infrastructure in healthcare, offices, and hospitality is driving modular adoption, as these sectors benefit from fast installation, flexible layouts, and scalable expansion capabilities, particularly during emergencies or rapid market shifts.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Modular Construction Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Modular Construction Market projected to grow between 2025 and 2032?
Which Modular Construction Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Modular Construction Market?
Who are the leading companies in the Modular Construction Market?
Which region commanded the largest share of the Modular Construction Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Steel
- 1.2.2 Wood
- 1.2.3 Concrete
- 1.2.4 Aluminum
- 1.2.5 Polyurethane
- 1.2.6 Glass Fiber
- 1.3 By Application
- 1.3.1 Single family residential
- 1.3.2 Multi-family residential
- 1.3.3 Offices
- 1.3.4 Healthcare
- 1.3.5 Hospitality
- 1.3.6 Education
- 1.4 By Product Type
- 1.4.1 Permanent
- 1.4.2 Relocatable
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 105.24 billion → 2032: USD 180.14 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Modular Construction Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Modular Construction Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Modular Construction Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Modular Construction Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Modular Construction Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Modular Construction Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Modular Construction Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Modular Construction Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 105.24 billion → 2032: USD 180.14 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Modular Construction Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Steel
- 12.3.7.2 Wood
- 12.3.7.3 Concrete
- 12.3.7.4 Aluminum
- 12.3.7.5 Polyurethane
- 12.3.7.6 Glass Fiber
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Single family residential
- 12.4.7.2 Multi-family residential
- 12.4.7.3 Offices
- 12.4.7.4 Healthcare
- 12.4.7.5 Hospitality
- 12.4.7.6 Education
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Permanent
- 12.5.7.2 Relocatable
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Modular Construction End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Modular Construction Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Modular Construction Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Modular Construction Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Premier Modular Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Skanska
- 18.4 LEUSBERG GmbH & Co KG
- 18.5 DuBox
- 18.6 Bouygues Construction
- 18.7 CIMC Modular Building Systems Holdings Co., Ltd.
- 18.8 Wernick Group
- 18.9 LAING O'ROURKE
- 18.10 Red Sea International
- 18.11 Sekisui House Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

