
Market Overview
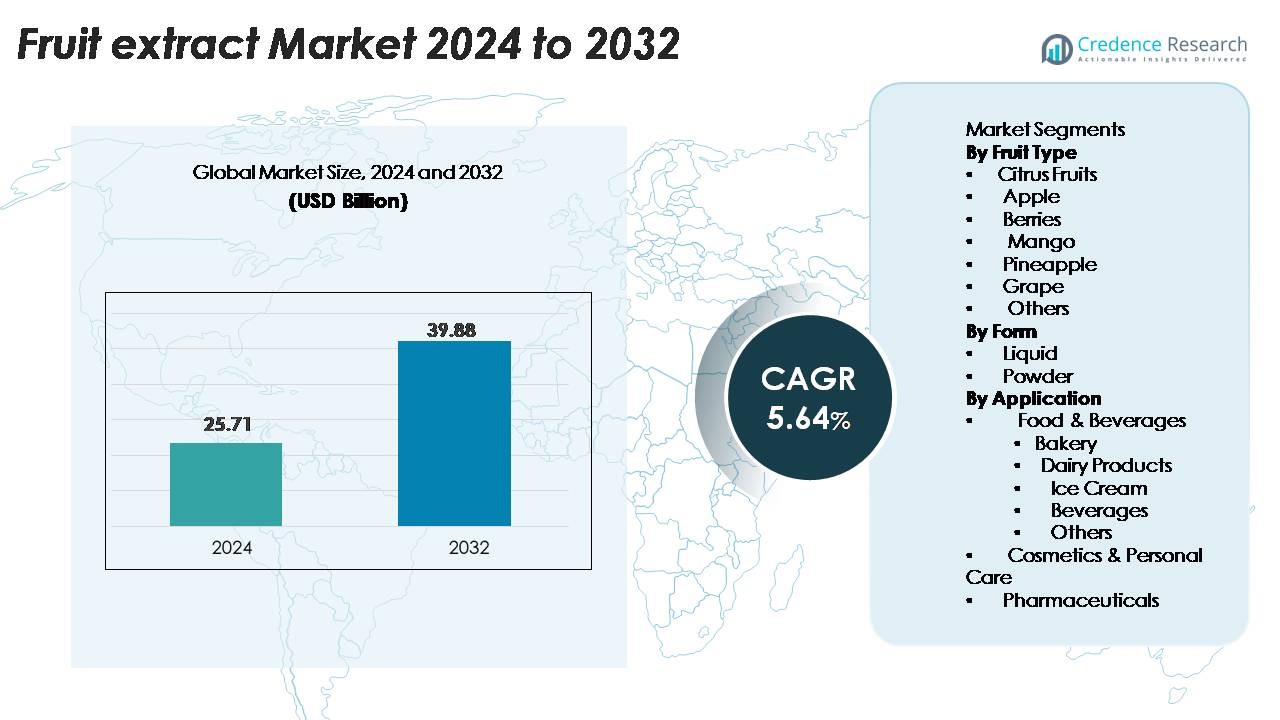
The Fruit Extract Market was valued at USD 25.71 billion in 2024 and is anticipated to reach USD 39.88 billion by 2032, registering a CAGR of 5.64% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fruit Extract Market Size 2024 | USD 25.71 Billion |
| Fruit Extract Market , CAGR | 5.64% |
| Fruit Extract Market Size 2032 | USD 39.88 Billion |
Top players in the fruit extract market include Symrise, Döhler GmbH, AGRANA Beteiligungs-AG, International Flavors & Fragrances Inc., Sensient Technologies Corporation, Kerr by Ingredion, Naturalin Bio-Resources, ABC Fruits, Citrofrut, and TBF Group. These companies focus on clean-label ingredients, advanced extraction methods, and strong supply chains to meet rising demand from beverage, nutraceutical, and cosmetic manufacturers. Asia Pacific leads the market with a 25.7% share, driven by large fruit production, expanding food processing industries, and growing preference for natural flavors in India, China, and Japan. North America and Europe remain strong due to high consumption of functional beverages and strict regulatory support for natural additives.
Market Insights
- The market reached USD 25.71 billion in 2024 and will hit USD 39.88 billion by 2032, at a CAGR of 5.64%.
- Clean-label demand drives heavy use of natural flavors, colors, and sweeteners in food, beverages, nutraceuticals, and cosmetics. Brands replace artificial additives with fruit-based concentrates to meet safety norms.
- Citrus holds the largest fruit type share at 30%, supported by use in juices, gummies, syrups, and skincare. Liquid extracts lead form share at 55%, while beverages remain the top application, holding 35%.
- Top players invest in solvent-free extraction, microencapsulation, and organic sourcing. Partnerships with farmers secure raw materials and reduce price swings. Global suppliers compete on purity, flavor strength, and traceability.
- Asia Pacific leads with 7% share, backed by strong fruit production and beverage processing. Europe follows with 28.4% due to clean-label rules, while North America holds 32.6% with high nutraceutical adoption.
Market Segmentation Analysis:
By Fruit Type
Citrus fruits lead the fruit type segment with the highest market share due to strong demand in flavoring, nutraceuticals, and vitamin-rich beverages. Citrus extracts contain natural antioxidants and vitamin C, which supports use in immunity-boosting products. Food manufacturers use orange, lemon, and lime extracts for clean-label formulations and sugar-free flavor enhancement. Berries show growing use in functional drinks and skincare because of high anthocyanin content. Apple, mango, pineapple, and grape extracts remain popular across confectionery and bakery applications. Rising consumer preference for natural flavoring supports steady expansion across all sub-categories.
- For instance, Citrus extracts naturally contain valuable compounds like vitamin C and flavonoids, and Symrise standardizes its products to ensure these beneficial components are present in a consistent, functional amount.
By Form
Liquid extracts hold the dominant share as they blend easily in beverages, syrups, sauces, and personal care emulsions. Beverage producers prefer liquid form because it delivers stronger aroma, faster solubility, and long shelf stability. Bakery and dairy brands add liquid fruit concentrates to maintain taste consistency and natural coloring. Powder extracts grow at a steady pace due to better transport convenience, longer storage life, and suitability for dry mixes, supplements, and instant drinks. Sports nutrition and pharmaceutical manufacturers increasingly adopt spray-dried powders for capsule fillings and functional blends.
- For instance, "Döhler GmbH produces orange liquid concentrate (typically around 65 °Brix), which is used to create juices and smoothies. When reconstituted to a single-strength juice (approximately 2 to 12 °Brix), the product typically has a pH range of 3.3 to 4.0, and Döhler uses advanced techniques to ensure uniform flavor and consistency in the final beverages."
By Application
Food and beverages represent the leading application segment with the largest share, driven by high use in juices, dairy, ice creams, confectionery, and ready-to-drink products. Beverage production remains the dominant sub-segment due to strong demand for flavored, fortified, and clean-label drinks. Bakery and dairy producers adopt fruit extracts for natural sweetness, coloring, and antioxidant benefits. Cosmetics and personal care companies use fruit-based actives in anti-aging, exfoliating, and skin-brightening formulations. Pharmaceutical manufacturers utilize extracts for supplements, gummies, and syrups focused on digestion, immunity, and detox benefits.
Key Growth Drivers
Rising Demand for Natural and Clean-Label Ingredients
Consumers now avoid artificial flavors, synthetic colors, and chemical additives. This shift increases the use of natural fruit extracts as flavoring, coloring, and sweetening agents. Food producers reformulate drinks, confectionery, dairy, and bakery items to gain “clean-label” claims. Retailers promote products with no preservatives and natural taste enhancers, which pushes higher extract usage. Extracts help brands meet regulatory limits on artificial additives in many countries. Growing vegan and plant-based lifestyles also support this move. Natural extracts offer aroma retention, shelf stability, and sugar reduction benefits. This wide appeal makes clean-label adoption one of the strongest demand drivers in the market.
- For instance, Symrise produces a range of natural citrus concentrates and flavorings which are used by food and beverage manufacturers to meet consumer demand for natural and clean-label products.
Growth of Functional Food, Nutraceuticals, and Immunity-Boosting Products
Functional food and beverage consumption continues to rise worldwide. Fruit extracts contain vitamins, polyphenols, and antioxidants, supporting immunity, heart health, digestion, and detoxification. Producers add citrus, berry, and grape extracts to supplements, gummies, capsules, and wellness drinks. Health-focused consumers prefer natural sources over synthetic vitamins, which increases fruit extract use in nutraceuticals. The post-pandemic shift toward preventive health also boosts demand. Sports nutrition brands add concentrated powders for recovery and endurance. Botanical combinations with fruit extracts help in weight management and gut health. This growth makes functional nutrition a stable and long-term demand driver.
- For instance,"Döhler GmbH supplies grape seed extracts that are often standardized to high concentrations, typically ranging from 70% to over 95% proanthocyanidins (or 700 to 950 mg/g), which are widely used in capsules and wellness drinks.
Rising Use in Cosmetics, Personal Care, and Pharmaceutical Formulations
Fruit extracts are widely used in skincare, haircare, and oral care products. They offer natural acids, enzymes, and antioxidants that support anti-aging, brightening, exfoliation, and skin repair. Companies add berry, citrus, grape seed, and apple actives in serums, creams, scrubs, and shampoos. The clean beauty trend encourages chemical-free ingredient replacements. Extract-based actives help brands gain organic, vegan, and dermatologically safe claims. Pharmaceutical producers use fruit extracts in syrups, gummies, chewables, and digestion-related formulations. Higher R&D spending in herbal medicine and plant-based therapeutics also strengthens market expansion. Together, these applications widen commercial opportunities beyond foods.
Key Trends & Opportunities
Growing Penetration of Organic and Sustainable Extracts
Demand for organic fruit extracts continues to rise. Consumers expect pesticide-free, non-GMO, and environmentally responsible sourcing. Producers invest in traceable supply chains and organic certifications for juices, concentrates, and powders. Cold-pressing, freeze-drying, and solvent-free extraction help retain nutrients and aroma. Cosmetic and personal care brands promote organic claims to attract premium buyers. Sustainable farming partnerships with growers reduce waste and improve raw material quality. Brands explore upcycling of fruit peels and seeds for antioxidants and natural colorants. This sustainability shift creates premium pricing, brand differentiation, and certification-based market opportunities.
- For instance, Naturalin Bio‑Resources Co. produces organic cactus extract with 5:1 concentration and standardized 3 % piscidic acid, using solvent-free extraction to maintain nutrient integrity.
Innovation in Extraction and Processing Technologies
Companies adopt advanced extraction technologies to improve yield, flavor strength, and nutrient retention. Techniques like supercritical CO₂ extraction, membrane filtration, and enzymatic processing deliver higher purity and solvent-free output. Spray-drying improves stability and shelf life for powdered extracts. Continuous R&D supports sugar-reduced concentrates with richer flavor profiles. Ready-to-use microencapsulated extracts help beverage and bakery makers maintain aroma in heat-processed foods. These innovations allow expansion into functional beverages, infant food, and medical nutrition. Improved processing efficiency also reduces manufacturing cost and energy consumption, creating competitive advantage.
- For instance, Symrise employs its patented SymTrap extraction technology, which includes the use of supercritical CO₂ for certain applications like ginger, to produce natural botanical extracts. For berry extracts, such as from bilberries (Vaccinium myrtillus), Symrise uses the SymTrap process to achieve a standardized anthocyanin content of up to 25% or 36%, concentrating the compounds from trace amounts.
Key Challenges
Raw Material Price Volatility and Supply Chain Instability
Fruit extract production depends on seasonal harvests and climate conditions. Floods, droughts, and temperature swings reduce fruit yield and increase procurement cost. Price volatility affects citrus, berries, grapes, and tropical fruits the most. Transportation delays and cold-chain failures cause raw material spoilage. Manufacturers must manage storage, freezing, and inventory to prevent shortages. Many countries rely on imported raw fruits or concentrates, which increases currency and freight cost risk. These uncertainties create inconsistent supply and margin pressure for processors and end-use companies.
Strict Regulatory Standards and Quality Compliance
Fruit extracts used in food, supplements, and personal care face strict purity and labeling requirements. Governments enforce limits on pesticide residues, heavy metals, and microbial contamination. Organic and clean-label products require expensive certification and auditing. Differing regulatory frameworks across regions increase complexity for exporters. Any deviation in taste, aroma, or color also affects brand consistency. Companies must invest in testing, traceability, and food safety systems, increasing production cost. Smaller producers face difficulty meeting these standards, which limits market entry and growth.
Regional Analysis
North America
North America holds the largest share of the fruit extract market at around 32.6% in 2024. The region benefits from strong consumer demand for natural ingredients in food, beverages, and personal care products. Expanding use of botanical extracts in nutraceuticals and functional foods also fuels market growth. The U.S. leads due to established manufacturing infrastructure and regulatory support for clean-label ingredients. Canada’s rising preference for antioxidant-rich fruit extracts in cosmetics further supports regional expansion. Growing adoption across industries ensures North America maintains its leadership through ongoing innovation and product diversification.
Europe
Europe accounts for nearly 28.4% of the global fruit extract market in 2024. Increasing focus on health-conscious lifestyles and sustainable sourcing practices drives regional demand. Countries like Germany, France, and the U.K. show strong consumption of fruit-based nutraceuticals and organic food products. Regulatory emphasis on natural formulations and consumer preference for chemical-free ingredients also strengthen growth. The cosmetics and personal care industries actively integrate fruit extracts in anti-aging and skin-care products, enhancing market expansion. Rising investment in sustainable agriculture and clean-label trends reinforces Europe’s competitive position in the global market.
Asia-Pacific
Asia-Pacific captures about 25.7% share of the fruit extract market in 2024. The region’s growth is driven by expanding food processing and cosmetics industries, coupled with rising disposable incomes. China, India, and Japan lead consumption due to strong awareness of plant-based health supplements and traditional herbal formulations. Increasing penetration of natural ingredients in beverages and functional foods supports sustained market expansion. Local manufacturers invest in extraction technology to improve yield and purity, catering to export demand. Rapid urbanization and consumer preference for natural health products position Asia-Pacific as the fastest-growing region globally.
Latin America
Latin America represents nearly 7.9% share of the global fruit extract market in 2024. The region benefits from abundant raw material availability and growing interest in natural, organic products. Brazil, Mexico, and Chile dominate production due to their extensive fruit cultivation and export potential. Expanding applications in dietary supplements, skincare, and natural flavorings support market development. Government efforts to promote agro-industrial innovation and sustainability further encourage extraction industry growth. Rising export demand for tropical fruit extracts positions Latin America as a key supply hub for global manufacturers.
Middle East & Africa
The Middle East and Africa account for around 5.4% share of the global fruit extract market in 2024. Demand is rising as consumers shift toward natural wellness and plant-based nutrition products. The United Arab Emirates and South Africa lead due to strong import networks and expanding cosmetic and beverage industries. Growing awareness of herbal and fruit-based health benefits drives adoption in local markets. Efforts to develop regional extraction facilities and improve agricultural output are strengthening domestic production. Increasing participation of international companies in joint ventures supports long-term market development.
Market Segmentations:
By Fruit Type
- Citrus Fruits
- Apple
- Berries
- Mango
- Pineapple
- Grape
- Others
By Form
- Liquid
- Powder
By Application
- Food & Beverages
- Bakery
- Dairy Products
- Ice Cream
- Beverages
- Others
- Cosmetics & Personal Care
- Pharmaceuticals
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The fruit extract market features a mix of global ingredient manufacturers, regional processors, and specialized botanical extract suppliers. Leading companies focus on expanding production capacity, improving extraction purity, and developing organic and clean-label product lines. Many players invest in cold-pressed, enzymatic, and solvent-free technologies to improve nutrient retention and flavor strength. Strategic acquisitions and partnerships with fruit growers help secure raw material supply and control quality. Major brands also target high-growth segments such as functional beverages, nutraceuticals, cosmetics, and herbal pharmaceuticals. Product innovation includes microencapsulated powders for better stability in heat-processed foods and high-concentration liquids for ready-to-drink formats. Companies expand their distribution networks across Asia Pacific, North America, and Europe to serve multinational food and beverage clients. Sustainability commitments, traceability systems, and organic certifications provide competitive advantage in premium markets. As consumer preference shifts toward natural ingredients, competition intensifies in flavor enhancement, sugar reduction, and antioxidant-rich formulations.
Key Player Analysis
- Symrise (Germany)
- Citrofrut (Mexico)
- Naturalin Bio-Resources Co. (China)
- Kerr by Ingredion (U.S.)
- Döhler GmbH (Germany)
- AGRANA Beteiligungs-AG (Austria)
- International Flavors & Fragrances Inc. (U.S.)
- ABC Fruits (India)
- TBF Group (Ukraine)
- Sensient Technologies Corporation (U.S.)
Recent Developments
- In February 2023, AUSTRIA JUICE GmbH, one of the key fruit extract and flavors manufacturing companies, launched its latest organic juice concentrate, including a new pomegranate berry mix and lime guava drink at BioFach 2023.
- In May 2022, Agrana AG, a global food and beverage ingredients company, collaborated with wholesale company RWA Raiffeisen Ware Austria AG to install a 556-kWp solar array on a fruit concentrate plant in Lower Austria.
Report Coverage
The research report offers an in-depth analysis based on Fruit type, Form, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Manufacturers will increase investment in advanced extraction technologies to improve yield and purity.
- Demand for natural‑label and clean‑label products will drive greater adoption of fruit extracts.
- Functional beverages and snacks will incorporate fruit extracts to meet health‑conscious consumer needs.
- Regions in Asia‑Pacific and Latin America will record faster growth due to rising disposable incomes and changing diets.
- Cosmetic and personal‑care brands will expand use of fruit extracts for antioxidant and skin‑benefit claims.
- Supply‑chain sustainability will become a key competitive differentiator in the fruit extract sector.
- Organic and exotic fruit‑extract variants will gain premium positioning in high‑end food and beverage segments.
- Producers will diversify into novel fruits and under‑utilised parts (such as peel or seeds) to reduce waste and cost.
- Partnerships between growers, extractors, and formulators will increase to secure raw‑material quality and consistency.
- Regulatory emphasis on ingredient transparency and safety will push extract suppliers to adopt stricter standards and certifications.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Fruit Extract Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Fruit Extract Market projected to grow between 2025 and 2032?
Which Fruit Extract Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Fruit Extract Market?
Who are the leading companies in the Fruit Extract Market?
Which region commanded the largest share of the Fruit Extract Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 25.71 billion → 2032: USD 39.88 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fruit Extract Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fruit Extract Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Fruit Extract Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Fruit Extract Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fruit Extract Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fruit Extract Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fruit Extract Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fruit Extract Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 25.71 billion → 2032: USD 39.88 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fruit Extract Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fruit Extract Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Fruit Extract Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Fruit Extract Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

