
Functional Drinks Market Overview:
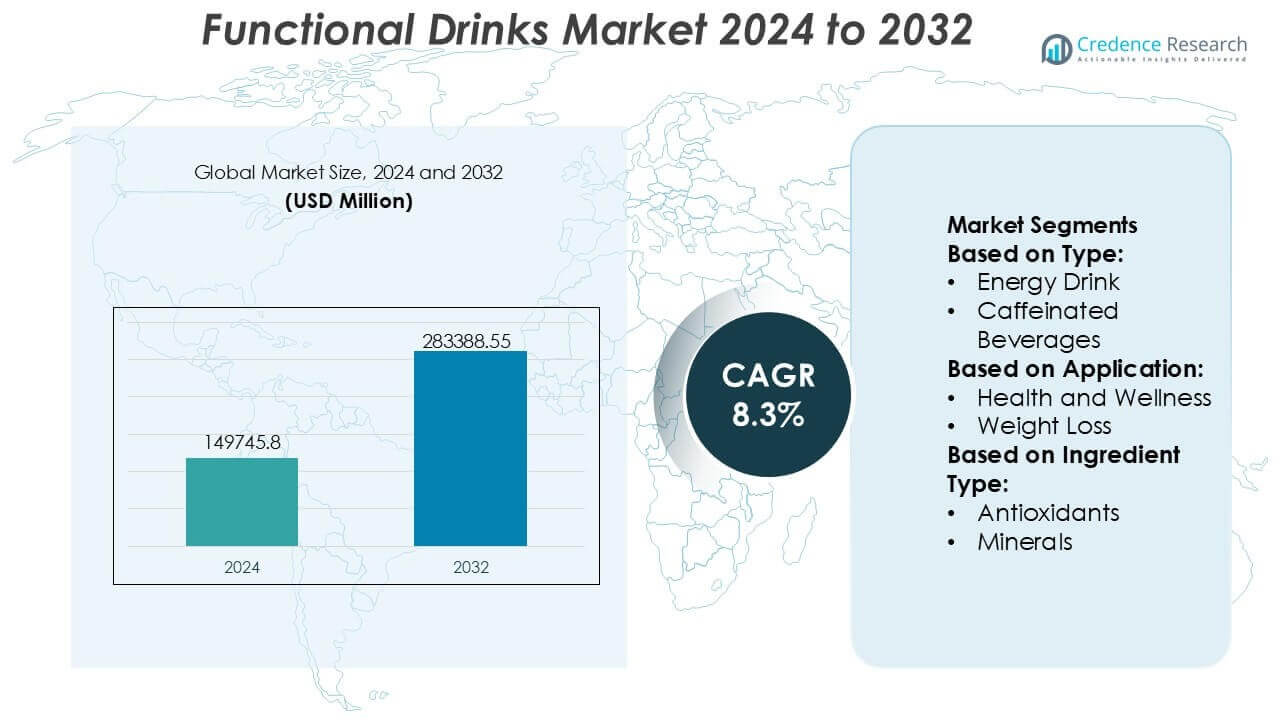
Functional Drinks Market size was valued USD 149745.8 million in 2024 and is anticipated to reach USD 283388.55 million by 2032, at a CAGR of 8.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Functional Drinks Market Size 2024 | USD 149745.8 million |
| Functional Drinks Market, CAGR | 8.3% |
| Functional Drinks Market Size 2032 | USD 283388.55 million |
Functional Drinks Market Insights
- Market growth is primarily driven by rising health awareness, demand for preventive nutrition, and increased consumption of energy drinks, enhanced water, and probiotic beverages, with energy drinks emerging as the dominant segment due to performance and convenience appeal.
- Key market trends include clean-label reformulations, reduced-sugar offerings, plant-based ingredients, and personalized functional beverages targeting immunity, digestion, and mental wellness.
- The competitive landscape is shaped by global beverage leaders and nutrition-focused players competing through brand strength, innovation, lifestyle marketing, and extensive distribution networks.
- Regionally, North America leads with an exact 38% market share, supported by advanced retail infrastructure and fitness culture, while Asia-Pacific shows rapid growth driven by urbanization and rising disposable incomes.
Functional Drinks Market Segmentation Analysis:
By Type
The Functional Drinks Market by type demonstrates broad diversification, with Energy Drinks emerging as the dominant sub-segment, accounting for approximately 32% market share. This leadership is driven by rising demand for instant energy, mental alertness, and performance enhancement among young adults, professionals, and fitness enthusiasts. Strong caffeine content, taurine, B-vitamins, and convenient on-the-go formats support adoption. Meanwhile, probiotic drinks and enhanced water show steady growth due to gut-health awareness and hydration trends, while nutraceutical and dairy-based beverages gain traction among aging populations seeking targeted health benefits.
- For instance, Keurig Dr Pepper, Inc. has expanded its functional beverage portfolio using brewing and formulation technologies capable of maintaining caffeine stability above 200 milligrams per serving and shelf-life performance exceeding 270 days under ambient conditions, while its advanced hot-fill and cold-fill bottling lines operate at speeds beyond 1,200 bottles per minute, enabling scalable production of energy and enhanced hydration drinks with consistent nutrient integrity.
By Application
By application, Health and Wellness represents the dominant sub-segment with nearly 68% market share, supported by increasing preventive healthcare awareness and lifestyle-driven consumption. Consumers increasingly prefer functional drinks that support immunity, digestion, energy balance, and overall vitality as part of daily routines. Urbanization, rising disposable incomes, and greater access to health information accelerate this trend. In contrast, the Weight Loss segment, while smaller, benefits from growing interest in metabolism-boosting, appetite-control, and low-calorie functional beverages, particularly among fitness-focused consumers and weight-management programs.
- For instance, Suntory Holdings Limited has advanced health-focused beverage innovation through its proprietary research platforms, developing functional formulations containing quantified active ingredients such as 1,000 milligrams of polyphenols per bottle and amino-acid blends exceeding 5 grams per serving, while leveraging precision fermentation and extraction technologies that operate at production scales above 100,000 kiloliters annually to ensure consistent functional efficacy across wellness-oriented drink portfolios.
By Ingredient Type
By ingredient type, Vitamins lead the segment with an estimated 29% market share, driven by their broad acceptance, regulatory familiarity, and association with immunity, energy, and metabolic health. Fortification with vitamin B-complex, C, and D remains common across energy drinks, juices, and enhanced water. Antioxidants and probiotics also record strong adoption due to demand for gut health and anti-aging benefits. Meanwhile, super-fruit extracts and botanical flavors gain momentum as consumers seek clean-label, plant-based, and naturally functional ingredient profiles.
Key Growth Drivers
Rising Health and Preventive Nutrition Awareness
Growing consumer awareness of preventive healthcare significantly drives demand for functional drinks. Consumers increasingly seek beverages that deliver targeted health benefits such as immunity support, digestive health, hydration, and energy enhancement. Functional drinks offer a convenient alternative to pills and supplements, aligning with busy lifestyles. Rising incidences of lifestyle-related disorders further reinforce demand for low-sugar, fortified, and clean-label beverages. As health literacy improves across both developed and emerging economies, consumers actively evaluate ingredient functionality, strengthening long-term adoption of nutrient-enriched and condition-specific drink formulations.
- For instance, Living Essentials Marketing, LLC has demonstrated technical leadership through its liquid energy formulations, delivering precisely 200 milligrams of caffeine in a 57-milliliter shot, combined with quantified B-vitamin content measured in microgram ranges, while operating high-speed filling and packaging systems capable of producing several billion units annually with tight tolerance controls to ensure consistent potency, stability, and shelf integrity across large-scale preventive nutrition product lines.
Product Innovation and Ingredient Fortification
Continuous innovation in formulations strongly supports market expansion. Manufacturers actively introduce drinks fortified with probiotics, adaptogens, plant-based proteins, antioxidants, and botanical extracts to address evolving wellness needs. Advances in flavor masking, natural sweeteners, and bioavailability enhancement improve sensory appeal without compromising health benefits. Innovation also extends to format diversification, including ready-to-drink, powdered, and concentrated shots. This steady pipeline of differentiated products enables brands to target niche health concerns while sustaining consumer interest in premium and functional beverage categories.
- For instance, PepsiCo, Inc. has advanced ingredient fortification through beverages delivering probiotic cultures exceeding 1 billion colony-forming units per serving, plant-based protein levels above 10 grams per bottle, and electrolyte blends containing more than 500 milligrams of sodium per liter, supported by proprietary microencapsulation and blending technologies validated across pilot-scale and commercial lines capable of running over 1,500 bottles per minute with precise nutrient dosing control.
Expansion of Fitness, Sports, and Active Lifestyles
The growing adoption of fitness-oriented and active lifestyles accelerates demand for functional drinks. Sports nutrition, energy enhancement, hydration optimization, and muscle recovery beverages gain traction among athletes, gym-goers, and wellness-focused consumers. Urbanization and rising participation in recreational sports further amplify consumption. Functional drinks positioned around endurance, mental focus, and post-exercise recovery benefit from strong cross-appeal across age groups. This driver is reinforced by increasing influence of fitness professionals, digital wellness platforms, and social media-driven health trends.
Key Trends & Opportunities
Shift Toward Clean-Label and Natural Functional Beverages
Consumers increasingly favor clean-label functional drinks formulated with recognizable, natural, and minimally processed ingredients. Demand grows for beverages free from artificial colors, preservatives, and synthetic additives, encouraging manufacturers to reformulate using plant-based extracts and natural sweeteners. Transparency in sourcing and labeling enhances brand trust and purchase intent. This trend creates opportunities for premium positioning, especially in immunity, digestive health, and detox categories, where consumers closely scrutinize ingredient integrity and nutritional claims.
- For instance, AriZona Beverages USA has scaled clean-label beverage production using formulations containing 23 grams of real brewed tea solids per liter and fruit juice inclusions measured at 40 grams per serving, supported by aseptic bottling lines capable of processing more than 900 bottles per minute, while maintaining product shelf stability beyond 240 days without artificial preservatives through precise thermal control and oxygen-reduction filling technologies.
Growth of Personalized and Targeted Nutrition Drinks
Personalized nutrition emerges as a major opportunity within the functional drinks market. Brands increasingly tailor products to specific demographic groups, health conditions, and lifestyle needs, such as age-specific nutrition, cognitive support, or stress management. Functional drinks positioned for women’s health, senior nutrition, and mental wellness gain visibility. Digital health tools and data-driven insights further support customization, enabling brands to align formulations with individual wellness goals and differentiate offerings in a competitive marketplace.
- For instance, Amway Corp has advanced targeted nutrition through its Nutrilite drink formulations delivering 20 grams of plant-based protein per serving, vitamin C content measured at 75 milligrams per dose, and iron fortification quantified at 9 milligrams per serving, supported by digital nutrition assessment platforms that process millions of individual health profiles annually to recommend personalized drink combinations with precise nutrient alignment.
Rising Demand Across Emerging Markets
Emerging economies present strong growth opportunities due to rising disposable incomes, urbanization, and expanding health awareness. Consumers in these regions increasingly adopt functional beverages as part of daily nutrition routines. Improved retail infrastructure, e-commerce penetration, and localized flavor innovations support wider accessibility. Manufacturers investing in affordable, region-specific formulations benefit from expanding middle-class populations seeking convenient and functional dietary solutions beyond traditional beverages.
Key Challenges
Regulatory Complexity and Health Claim Restrictions
Regulatory frameworks governing functional drinks vary widely across regions, creating compliance challenges for manufacturers. Strict controls on health claims warning against misleading labeling require extensive scientific validation and documentation. Differences in permissible ingredients and fortification levels further complicate product launches across multiple markets. Navigating evolving regulations increases development timelines and compliance costs, particularly for innovative formulations, potentially limiting speed-to-market and restraining smaller players with limited regulatory expertise.
High Competition and Consumer Skepticism
Intense competition across functional beverage categories creates challenges in differentiation and brand credibility. A growing number of products with overlapping health claims increases consumer skepticism regarding efficacy. Over-marketing and exaggerated benefit claims erode trust, forcing brands to invest heavily in education, clinical validation, and transparent communication. Price sensitivity in mass markets further pressures margins, requiring manufacturers to balance functional value, taste, affordability, and authenticity to sustain long-term consumer loyalty.
Regional Analysis
North America
North America dominates the functional drinks market with an estimated 38% market share, driven by high consumer awareness of preventive health, strong purchasing power, and advanced product availability. The region shows strong demand for energy drinks, probiotic beverages, and enhanced water, supported by well-established retail and e-commerce channels. Consumers actively seek clean-label, low-sugar, and performance-oriented drinks aligned with fitness and wellness lifestyles. Innovation in functional ingredients, along with aggressive product marketing and brand penetration, sustains market leadership across the United States and Canada.
Europe
Europe accounts for approximately 26% of the global functional drinks market, supported by rising demand for natural, organic, and nutritionally balanced beverages. Consumers show strong preference for products focused on digestive health, immunity, and weight management. Regulatory emphasis on ingredient transparency and health claims encourages high-quality formulations. Western Europe leads consumption due to mature health-conscious populations, while Eastern Europe demonstrates steady adoption. Growing interest in plant-based and sugar-free functional drinks, combined with expanding health retail formats, continues to support regional market growth.
Asia-Pacific
Asia-Pacific holds around 29% market share, making it the fastest-growing regional market for functional drinks. Rapid urbanization, rising disposable incomes, and increasing health awareness drive strong consumption across China, India, Japan, and Southeast Asia. Traditional functional ingredients, such as herbal extracts and fermented components, align well with regional dietary habits. The region sees high demand for energy drinks, fortified juices, and nutraceutical beverages. Expanding retail infrastructure and aggressive product localization further strengthen Asia-Pacific’s position as a key growth engine.
Latin America
Latin America represents nearly 4% of the functional drinks market, with growth supported by increasing urban populations and rising awareness of lifestyle-related health concerns. Brazil and Mexico lead regional consumption, driven by demand for energy and vitamin-fortified beverages. While price sensitivity remains a constraint, affordable functional drink offerings and growing penetration of modern retail channels support adoption. Increasing influence of fitness culture and younger demographics also contributes to demand, particularly for hydration, energy, and immunity-focused beverages.
Middle East & Africa
The Middle East & Africa region accounts for about 3% market share, supported by gradual improvements in health awareness and urban lifestyles. Demand is strongest in Gulf countries due to higher income levels and expanding fitness and wellness culture. Functional drinks focused on hydration, energy, and immunity perform well in hot climates. However, limited product availability and lower awareness in parts of Africa restrain growth. Ongoing investments in retail infrastructure and health-focused consumer education are expected to support steady regional expansion.
Functional Drinks Market Segmentations:
By Type:
- Energy Drink
- Caffeinated Beverages
By Application:
- Health and Wellness
- Weight Loss
By Ingredient Type:
- Antioxidants
- Minerals
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the functional drinks market players such as Keurig Dr Pepper, Inc., Suntory Holdings Limited, Living Essentials Marketing, LLC, PepsiCo, Inc., AriZona Beverages USA, Amway Corp, Monster Beverage Corporation, Taisho Pharmaceutical Holdings Co. Ltd., The Coca-Cola Company, Red Bull GmbH. the functional drinks market is highly dynamic and marked by intense rivalry among global, regional, and niche brands. Companies compete primarily on product innovation, functional efficacy, taste optimization, and brand positioning to capture health-conscious consumers. Leading participants leverage strong distribution networks and marketing capabilities to scale energy, hydration, and wellness-focused beverages, while also expanding into clean-label and reduced-sugar formulations. Smaller players differentiate through targeted health benefits, natural ingredients, and localized flavor profiles. Continuous investment in research, packaging innovation, and digital engagement remains critical, as consumer expectations increasingly demand transparency, convenience, and scientifically supported functional claims.
Key Player Analysis
- Keurig Dr Pepper, Inc.
- Suntory Holdings Limited
- Living Essentials Marketing, LLC
- PepsiCo, Inc.
- AriZona Beverages USA
- Amway Corp
- Monster Beverage Corporation
- Taisho Pharmaceutical Holdings Co. Ltd.
- The Coca-Cola Company
- Red Bull GmbH
Recent Developments
- In March 2025, PepsiCo, Inc. has announced its definitive agreement to acquire poppi, a leading prebiotic soda brand. PepsiCo continues to diversify its beverage portfolio with functional, health-conscious options to meet evolving consumer demand.
- In February 2025, Coca-Cola launched Simply Pop, a new prebiotic soda line under the Simply brand. The product line features five flavors: Citrus Punch, Fruit Punch, Lime, Pineapple Mango, and Strawberry.
- In January 2025, Celsius Holdings, Inc. introduced CELSIUS HYDRATION™, a new line of electrolyte-based powder sticks to support hydration with zero sugar, B vitamins, essential electrolytes and the refreshing, fruit-forward flavors of CELSIUS energy drinks.
- In April 2024, GURU Organic Energy Corp. launched its new Peach Mango Punch in Canada with a big national marketing push, focusing on its blend of natural, plant-based ingredients, low calories, and benefits for focus, following its success in the U.S..
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Ingredient Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Functional drinks will increasingly integrate science-backed ingredients to deliver targeted health benefits such as immunity, gut health, and cognitive support.
- Clean-label formulations with natural sweeteners and recognizable ingredients will become a standard expectation rather than a premium feature.
- Sugar reduction and low-calorie innovations will accelerate as consumers prioritize metabolic and weight management health.
- Personalised and condition-specific functional beverages will gain traction across age, gender, and lifestyle segments.
- Plant-based and vegan functional drinks will expand as dietary preferences shift toward sustainable nutrition choices.
- Advances in bioavailability and nutrient delivery technologies will enhance functional efficacy and consumer trust.
- E-commerce and direct-to-consumer channels will play a larger role in product discovery and repeat purchases.
- Emerging markets will see faster adoption driven by urbanisation and growing health awareness.
- Functional energy and hydration drinks will increasingly target mental focus, stress relief, and everyday wellness needs.
- Regulatory scrutiny will intensify, encouraging clearer labelling, substantiated claims, and higher product transparency.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Functional Drinks Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Functional Drinks Market projected to grow between 2024 and 2032?
Which Functional Drinks Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Functional Drinks Market?
Who are the leading companies in the Functional Drinks Market?
Which region commanded the largest share of the Functional Drinks Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 149,745.8 million → 2032: USD 283,388.55 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Functional Drinks Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Functional Drinks Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Functional Drinks Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Functional Drinks Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Functional Drinks Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Functional Drinks Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Functional Drinks Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Functional Drinks Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 149,745.8 million → 2032: USD 283,388.55 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Functional Drinks Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Functional Drinks Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Functional Drinks Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Functional Drinks Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

