
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Energy Drinks Market Size 2024 | USD 9012.7 million |
| Energy Drinks Market, CAGR | 6.8% |
| Energy Drinks Market Size 2032 | USD 15255.44 million |
Market Overview:
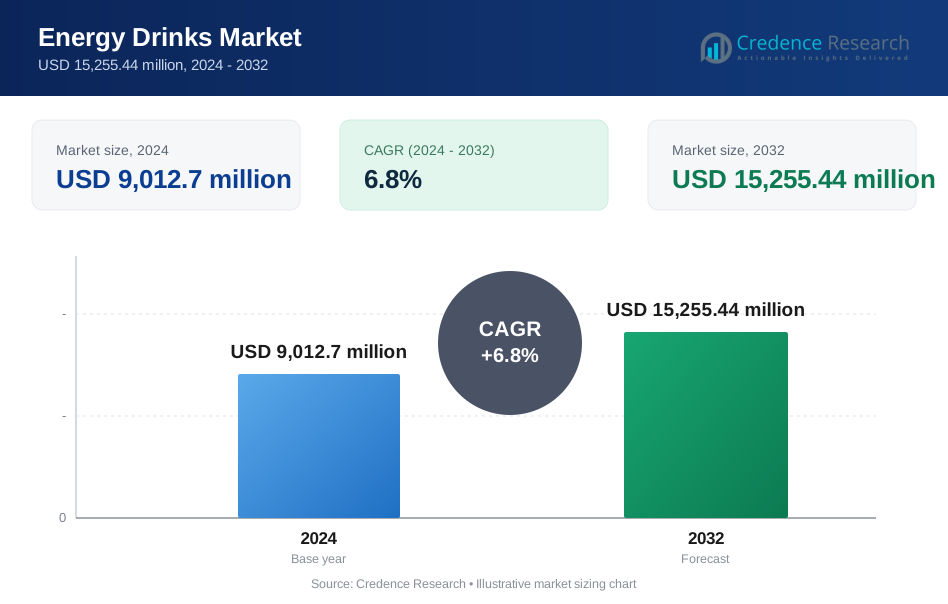
The Energy Drinks Market is projected to grow from USD 9012.7 million in 2024 to an estimated USD 15255.44 million by 2032, with a compound annual growth rate (CAGR) of 6.8% from 2024 to 2032.
Key drivers propelling the energy drinks market growth include a surge in demand for convenient energy-boosting products tailored to fast-paced urban lifestyles, where high-performance beverages provide both physical endurance and enhanced mental alertness. The market’s appeal is further bolstered by the proliferation of sports and fitness activities globally, with athletes and active consumers seeking instant energy and recovery benefits. Additionally, the market has been shaped by increasing product diversification, including sugar-free, organic, and plant-based energy drinks that align with evolving consumer health trends. Strategic marketing initiatives, such as partnerships with athletes, influencers, and e-sports personalities, have elevated brand visibility and consumer engagement. The expanding availability of energy drinks through various distribution channels, including online platforms and supermarkets, further strengthens market reach. Furthermore, heightened interest in digital gaming and e-sports has positioned energy drinks as an integral part of the gaming community, reinforcing their popularity among younger demographics.
Regionally, North America remains a dominant market due to heightened consumer awareness, strong purchasing power, and well-established distribution networks. The United States, in particular, continues to drive market expansion, reflecting a deep-rooted emphasis on health, wellness, and performance-oriented products. Europe trails closely, led by countries like Germany, the U.K., and France, where premium product offerings and innovative formulations have captured the interest of health-conscious consumers. Meanwhile, the Asia-Pacific region is expected to witness the fastest growth, driven by a combination of rapid urbanization, a burgeoning young consumer base, and a growing focus on active lifestyles. Key markets such as China, India, and Japan are experiencing a notable uptick in demand, supported by changing dietary habits, increased sports participation, and rising disposable incomes.
Market Drivers:
Increasing Health and Wellness Awareness:
A significant driver for the energy drinks market is the growing emphasis on health and wellness worldwide. Consumers are increasingly focused on maintaining active and balanced lifestyles, which has led to a heightened interest in functional beverages that offer immediate energy boosts and support physical and cognitive performance. For instance, according to a report 69% of consumers in India look for healthy ingredients in food and beverages, and 54% actively monitor their diet to manage weight. Energy drinks are perceived as more than just refreshments; they are viewed as products that enhance mental alertness, endurance, and overall well-being. The shift towards healthier lifestyles has prompted manufacturers to innovate by introducing sugar-free, low-calorie, and organic formulations, further appealing to health-conscious individuals.
Rising Demand from the Sports and Fitness Community:
The expanding sports and fitness culture globally has been another crucial factor driving the growth of the energy drinks market. As more individuals adopt active routines, the demand for energy drinks as performance enhancers has soared. Professional athletes, fitness enthusiasts, and even casual gym-goers view these beverages as effective solutions for quick energy replenishment and post-exercise recovery. For instance, Powerade has partnered with top athletes like Steven Adams and Kevin Pillar to promote their energy drinks, highlighting their benefits for athletic performance. The market has seen a surge in endorsements by sports personalities and partnerships with sports events, which enhance consumer perception of energy drinks as integral to athletic performance and endurance. Such marketing initiatives, combined with product innovations aimed at boosting stamina, hydration, and nutrient replenishment, have positioned energy drinks as essential items within the fitness realm.
Increasing Consumer Demand for Convenience:
The modern lifestyle, characterized by demanding schedules and busy routines, has fueled a growing need for convenient, ready-to-consume energy-boosting products. Energy drinks, known for their ease of availability and rapid consumption, are increasingly favored by individuals seeking quick fixes to combat fatigue and boost productivity throughout the day. The shift towards convenience is further supported by broad distribution networks that ensure energy drinks are accessible across a variety of channels, including supermarkets, convenience stores, vending machines, and online platforms. This heightened convenience factor aligns with consumer expectations for instant energy and functional benefits, driving consistent growth in the market.
Influence of Digital Culture and Gaming Communities:
The energy drinks market has also benefited greatly from the rise of digital culture and e-sports, positioning itself as a prominent presence within the gaming and streaming communities. Gamers, who often require sustained focus and high energy levels during competitive play, are increasingly turning to energy drinks as their beverage of choice. Companies have responded with targeted marketing strategies, such as collaborating with popular gaming influencers and sponsoring e-sports tournaments, to further embed their brands within the digital space. For instance, G Fuel has become a staple in the gaming community, partnering with top gaming influencers and sponsoring major e-sports events, This cultural phenomenon has contributed to the rising popularity of energy drinks among younger consumers, who are captivated by both the performance benefits and the branding tailored to their interests and lifestyles.
Market Trends:
Product Innovation and Diversification:
The energy drinks market is experiencing a significant trend towards the development of innovative and diversified product offerings that cater to specific consumer needs. As competition intensifies, manufacturers are introducing a broad range of alternatives, such as natural, organic, and plant-based energy drinks, to appeal to health-conscious consumers who are increasingly wary of artificial ingredients and high sugar content. Additionally, brands are incorporating adaptogens, nootropics, and other functional ingredients designed to reduce stress and enhance cognitive function. This shift reflects a move away from conventional, high-caffeine, and high-sugar energy drinks in favor of more holistic and balanced energy solutions.
Growth of Sugar-Free and Low-Calorie Options:
A growing trend in the energy drinks market is the surge in demand for sugar-free and low-calorie products. With rising health concerns and increased awareness about the negative effects of excessive sugar consumption, many consumers are seeking healthier alternatives to traditional energy drinks. As a result, brands are reformulating existing products and launching new sugar-free varieties to capture this expanding consumer segment. This trend is particularly prominent in regions such as North America and Europe, where public health initiatives and government regulations on sugar content have significantly influenced consumer choices. By offering healthier options, brands can address regulatory pressures while catering to a wider audience that prioritizes healthier energy-boosting beverages.
Sustainability and Eco-Friendly Practices:
Sustainability has become a key trend in the energy drinks market, as consumers increasingly seek products that align with their environmental values. Brands are responding by adopting eco-friendly packaging, such as recyclable cans and reduced plastic usage, while also sourcing ingredients sustainably. For instance, Red Bull has committed to using 100% recyclable aluminum cans and has implemented measures to reduce its carbon footprint. Several energy drink companies are investing in carbon-neutral production processes and integrating sustainability into their marketing strategies. This growing emphasis on environmental responsibility resonates with younger, eco-conscious consumers, who are more likely to support brands that contribute positively to global sustainability efforts. In addition to environmental benefits, these practices enhance brand image and build consumer loyalty among socially responsible buyers.
Digital Marketing and Personalization:
Digital marketing strategies and personalized branding are transforming the way energy drinks are marketed and consumed. Brands are increasingly leveraging social media platforms, influencer partnerships, and sponsorships in e-sports to directly engage with tech-savvy, younger consumers. Personalized marketing campaigns, along with the launch of limited-edition flavors often developed in collaboration with influencers, have proven effective in fostering consumer loyalty and increasing brand visibility. Furthermore, the rise of online retail channels has made energy drinks more accessible, allowing consumers to purchase products with ease and convenience. These digital engagement strategies help position energy drinks as part of a modern lifestyle, driving growth and further establishing the category as more than just a functional beverage.
Market Restraints and Challenges:
Health Concerns and Regulatory Pressures:
One of the primary challenges facing the energy drinks market is the growing concern about the health risks associated with excessive consumption of high-caffeine and high-sugar beverages. Studies linking energy drinks to increased heart rate, blood pressure, and other adverse health effects have raised alarms, particularly among vulnerable populations such as adolescents and individuals with pre-existing health conditions. This has led to heightened scrutiny from health organizations and governments. Regulatory measures, including limits on caffeine content, warning labels, and age restrictions on sales, are becoming more common, particularly in regions like Europe and North America. Such regulations may limit market growth and restrict product formulations, compelling manufacturers to adjust their product offerings to comply with evolving standards.
Intense Competition and Market Saturation:
The energy drinks market is highly competitive, with numerous global and regional players vying for market share. This intense competition, coupled with low barriers to entry, has led to market saturation, particularly in mature markets like North America and Europe. Many brands face the challenge of differentiating their products in an overcrowded marketplace, which often leads to price wars, reduced profit margins, and increased promotional spending. Smaller companies may struggle to compete with well-established brands that benefit from strong consumer loyalty, distribution networks, and significant marketing budgets. As the market matures, companies must find innovative ways to stand out and maintain consumer interest.
Negative Public Perception and Brand Image Issues:
Despite the growing popularity of energy drinks, there remains a persistent negative perception surrounding the product category. Public concerns about the high caffeine and sugar content, coupled with reports of adverse health effects, can damage consumer trust and brand reputation. For instance, incidents involving excessive consumption or misuse of energy drinks, particularly among young people, have led to public backlash and media scrutiny. As a result, brands must invest in transparent communication about product ingredients, benefits, and potential risks to address consumer concerns and rebuild confidence. Failure to address these issues can hinder the growth potential of energy drink brands in key markets.
Market Segmentation Analysis:
The energy drinks market is divided into several segments based on product type, format, flavor, categories, nature, and distribution channel, each offering unique opportunities for growth.
By Product Type
Energy drinks are primarily segmented into caffeinated and de-caffeinated beverages. Caffeinated beverages dominate the market due to the high demand for quick energy boosts, while de-caffeinated options are gaining traction among consumers seeking energy without the stimulant effects of caffeine.
By Format
Energy drinks are available in various formats, including shots, powder, and ready-to-drink (RTD) beverages. The RTD segment holds the largest market share due to its convenience, while the powder format is popular among fitness enthusiasts who prefer customizable energy levels. Shots are gaining popularity for their quick and concentrated energy delivery.
By Flavor
The energy drink market offers a wide range of flavors, catering to diverse consumer preferences. Popular options include citrus, berries, mocha, pomegranate, and watermelon, among others. Flavored drinks are leading the segment as consumers increasingly seek variety and enjoyable taste profiles, while unflavored products are preferred by those looking for simpler options.
By Categories
Energy drinks are classified into natural energy drinks, sports drinks, non-alcoholic beverages, functional beverages, and non-carbonated packaged drinks. Natural energy drinks and functional beverages are experiencing strong growth as consumers lean towards healthier, performance-enhancing options.
By Nature
Energy drinks are available in both organic and conventional variants, with the organic segment gaining traction due to rising health awareness.
By Distribution Channel
Energy drinks are sold through both B2B (business-to-business) and B2C (business-to-consumer) channels. B2C is the dominant channel, driven by online retail and widespread availability in supermarkets and convenience stores.
Segmentation:
By Product Type:
- Caffeinated Beverage
- De-caffeinated Beverage
By Format:
- Shots
- Powder
- Ready-To-Drink (RTD)
By Flavor:
- Unflavored
- Flavored
- Citrus
- Berries
- Mocha
- Pomegranate
- Apple
- Mint
- Blends (Mix)
- Cola
- Watermelon
- Chocolate
- Others
By Categories:
- Natural Energy Drink
- Sports Drink
- Non-Alcoholic Beverage
- Functional beverages
- Non-carbonated packaged drinks
By Nature:
- Organic
- Conventional
By Distribution Channel:
- B2B
- B2C
Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The global energy drinks market is characterized by varying demand and consumption patterns across different regions, driven by distinct consumer preferences, health trends, and market maturity.
North America
North America is the largest market for energy drinks, accounting for a significant share of the global market. The region's market dominance can be attributed to the high demand for energy-boosting beverages among consumers with fast-paced lifestyles, particularly in the U.S. The growing focus on health and wellness has led to the increased popularity of sugar-free, low-calorie, and functional energy drinks. Additionally, sports and fitness trends, coupled with the rising interest in digital gaming and e-sports, have further fueled energy drink consumption. North America holds approximately 40% of the global market share, with major brands like Red Bull, Monster, and PepsiCo continuing to expand their product offerings to cater to diverse consumer needs.
Europe
Europe is another key region for the energy drinks market, contributing around 30% to the global market share. The demand for energy drinks in Europe is driven by countries like the U.K., Germany, and France, where health-conscious consumers are increasingly seeking products with natural ingredients, reduced sugar content, and functional benefits. Regulatory measures in Europe also influence product formulations, encouraging manufacturers to innovate with healthier and organic options. As a result, the market in Europe is shifting towards premium and natural energy drinks, which are projected to experience steady growth in the coming years.
Asia-Pacific
The Asia-Pacific region is experiencing the fastest growth in the energy drinks market, expected to expand at a robust CAGR over the next several years. This region, which includes emerging markets like China, India, and Japan, is driven by a rapidly growing urban population, increased disposable incomes, and a rising interest in sports and fitness. Young, health-conscious consumers are increasingly drawn to energy drinks as functional beverages that support an active lifestyle. The market share of Asia-Pacific is currently estimated at around 20%, with the potential for significant growth as consumer awareness about energy drinks continues to rise.
Latin America
Latin America accounts for approximately 5-7% of the global energy drinks market. While the region's energy drink consumption is still developing, countries like Brazil and Mexico show strong demand for energy drinks, particularly among younger populations. The increasing popularity of sports activities and a shift toward healthier, low-sugar options are expected to drive future growth in this region.
Middle East & Africa
The Middle East and Africa together hold a smaller portion of the global energy drinks market, contributing around 5%. Growth in this region is primarily driven by increasing urbanization and higher disposable incomes, particularly in countries like Saudi Arabia and the UAE. While the market is still in a nascent stage, it is expected to grow steadily as consumer lifestyles evolve and demand for convenience products increases.
Key Player Analysis:
- Asia Brewery Incorporated
- Carlsberg A/S
- Coca-Cola Co.
- Dali foods group
- Kabisa B.V.
- Kraft Foods Inc.
- LT Group Inc.
- Monster Beverage Corp.
- NEALKO ORAVAN, spol s.r.o
- Nestlé S.A.
- Otsuka Pharmaceutical Co.
- PepsiCo Inc.
- Red Bull GmbH
- Shenzhen Eastroc Beverage Co. Ltd.
- Suntory Holdings Ltd.
- The Gatorade Company, Inc.
Competitive Analysis:
The energy drinks market is highly competitive, with several well-established global brands leading the industry. Key players include Red Bull, Monster Beverage Corporation, PepsiCo (with its Rockstar Energy brand), and The Coca-Cola Company (with its energy drink portfolio). These companies dominate the market by offering a wide range of products, backed by extensive marketing campaigns, sponsorships, and distribution networks. Innovation is a crucial factor, with leading brands constantly introducing new flavors, formulations, and health-conscious options, such as sugar-free and organic variants, to meet evolving consumer preferences. Emerging brands are also entering the market, focusing on niche segments like natural energy drinks, functional beverages, and plant-based options to capture the growing demand for healthier alternatives. The competition is further intensified by regional players in emerging markets, who offer cost-effective solutions to cater to local tastes. Competitive pricing, brand loyalty, and marketing strategies remain key drivers in this fast-evolving market.
Recent Developments:
- In April 2024, GURU Organic Energy Corp., a leading Canadian organic energy drink brand, introduced its new Peach Mango Punch flavor in Canada. The product, which is low in calories and crafted from natural ingredients, aims to improve focus and cognitive performance. It contains caffeine and plant-based components and is certified organic, free from sucralose and aspartame. Key ingredients such as L-theanine, monk fruit, and stevia contribute to its health benefits and natural sweetness, aligning with the brand's commitment to offering healthier alternatives.
- In February 2024, Red Bull GmbH unveiled its Summer Edition Curuba Elderflower flavor in a 250ml can. The drink, which combines curuba and elderflower, is available in multiple formats, including a sugar-free version. The introduction of this flavor, as part of the brand's "Editions" range, helped Red Bull expand its customer base by 50%. Additionally, the company launched an 8x250ml mixed sugar-free multipack to address growing consumer demand for low-sugar options.
- In January 2024, Celsius Holdings, Inc. extended its market presence into Canada, the UK, and Ireland through strategic partnerships with PepsiCo, Inc. and Suntory Beverage & Food Great Britain and Ireland. PepsiCo became the exclusive distributor in Canada, continuing an agreement formed in 2022 in the U.S., while Suntory Beverage & Food Limited was selected for exclusive sales and distribution across the UK, Isle of Man, Channel Islands, and the Republic of Ireland.
- In 2023, Monster Beverage Corporation acquired Bang Energy, strengthening its position in the Asia-Pacific energy drink market. This acquisition includes Bang’s Phoenix facility, enabling Monster to tap into the region's rapidly expanding consumer base and further solidifying its global footprint.
- In 2023, professional bodybuilder Chris Bumstead launched Bum Energy, an energy drink featuring reduced caffeine content and unique ingredients. This new product offers consumers a distinctive option in the energy drink market, catering to those seeking a different experience with less caffeine.
Market Concentration & Characteristics:
The energy drinks market is characterized by moderate to high concentration, with a few dominant players holding significant market shares. Major brands like Red Bull, Monster Beverage, and PepsiCo (Rockstar) lead the market, leveraging strong brand recognition, extensive distribution networks, and substantial marketing budgets. These players maintain their competitive edge through continuous product innovation, strategic partnerships, and global reach. However, the market also contains a growing number of niche brands focusing on health-conscious, organic, and functional energy drinks, which are gaining traction among consumers. As a result, while the market remains largely controlled by established giants, there is room for new entrants targeting specific segments such as plant-based, low-calorie, or sugar-free energy drinks. The industry is characterized by fierce competition, rapid innovation, and a high degree of product differentiation, with brands striving to cater to evolving consumer preferences and expand their reach across diverse geographical regions.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type, By Format, By Flavor, By Categories, By Nature and By Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The energy drinks market is expected to continue growing at a steady pace, driven by increasing consumer demand for functional beverages that enhance physical and mental performance.
- Health-conscious choices will shape product innovation, with greater demand for low-calorie, sugar-free, organic, and plant-based energy drinks.
- The expansion of e-sports and gaming culture will fuel energy drink consumption among younger demographics, particularly in North America and Asia-Pacific.
- Market players will invest heavily in sustainable packaging and environmentally friendly production methods to align with consumer preferences for eco-conscious products.
- The rise in fitness and wellness trends will increase demand for energy drinks with added functional benefits, such as recovery aids and natural ingredients.
- New entrants focusing on niche markets, such as energy drinks for specific health conditions or alternative energy sources, will gain traction.
- Regional expansion into emerging markets, particularly in Asia-Pacific and Latin America, will provide new growth opportunities.
- The increasing popularity of ready-to-drink (RTD) formats will continue, driven by consumer demand for convenience.
- Strategic partnerships with influencers and athletes will remain a core marketing strategy for brands to engage with target audiences.
- Regulatory challenges related to caffeine content and health concerns may impact product formulations and advertising strategies in certain regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the energy drinks industry by 2032?
What are the key drivers of growth in the energy drinks market?
Which regions are leading the energy drinks market?
What challenges does the energy drinks market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Energy Drinks Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Energy Drinks Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9,012.7 million → 2032: USD 15,255.44 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Energy Drinks Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Energy Drinks Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Energy Drinks Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Energy Drinks Market Drivers
- 3.3 Energy Drinks Market Restraints & Challenges
- 3.4 Energy Drinks Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Energy Drinks Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Energy Drinks Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Energy Drinks category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Energy Drinks Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Energy Drinks Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Energy Drinks market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Energy Drinks Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Energy Drinks Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Energy Drinks Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Energy Drinks (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Energy Drinks Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Energy Drinks Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Energy Drinks Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Energy Drinks Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Energy Drinks Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Energy Drinks Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Energy Drinks Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Energy Drinks Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Energy Drinks Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
