
Market Overview
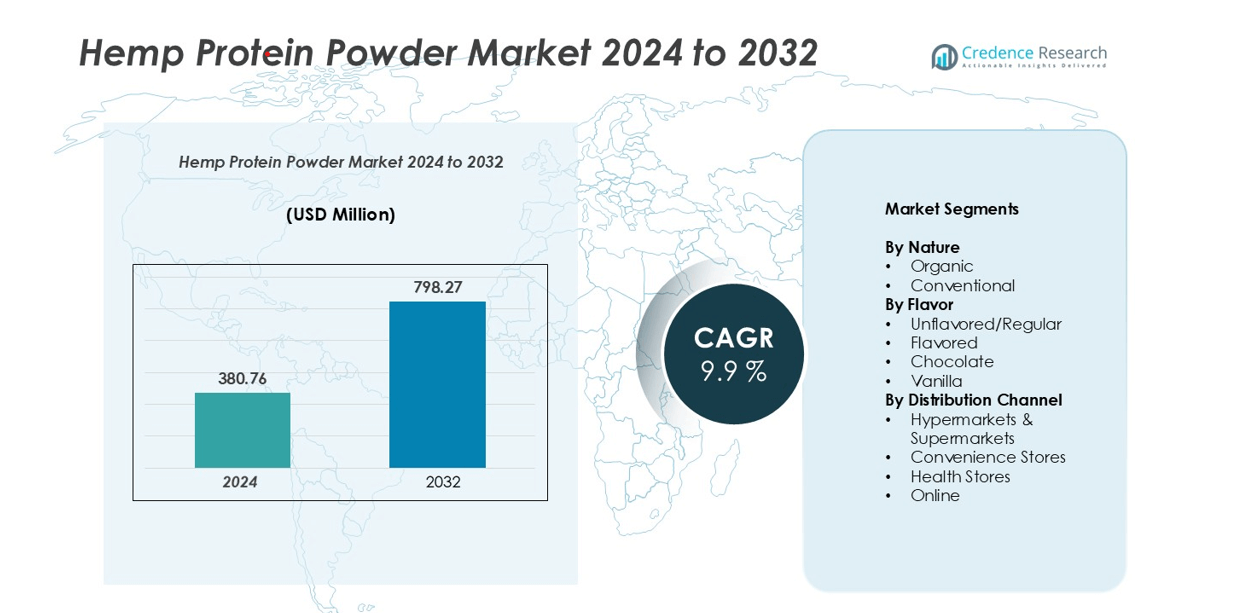
Hemp protein powder market size was valued at USD 380.76 million in 2024 and is anticipated to reach USD 798.27 million by 2032, at a CAGR of 9.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hemp Protein Powder Market Size 2024 | USD 380.76 million |
| Hemp Protein Powder Market, CAGR | 9.9% |
| Hemp Protein Powder Market Size 2032 | USD 798.27 million |
The hemp protein powder market is dominated by key players such as Manitoba Harvest, Navitas Organics, Nutiva, Evo Hemp, Sunwarrior, India Hemp and Co., Terrasoul Superfoods, India Hemp Organics, Anthonys Goods, and Health Horizons. These companies leverage strong brand recognition, diversified product portfolios, and strategic distribution across retail and e-commerce channels to maintain competitive advantage. North America leads the global market with a 38% share, driven by high health awareness, established retail infrastructure, and a growing fitness culture. Europe follows with 27%, supported by rising veganism and demand for organic, sustainable products. Asia-Pacific accounts for 20% of the market, reflecting increasing adoption of plant-based nutrition and urbanization. Latin America and the Middle East & Africa hold 9% and 6% shares, respectively, with growth fueled by expanding consumer awareness and e-commerce penetration.
Market Insights
- The global hemp protein powder market was valued at USD 380.76 million in 2024 and is projected to reach USD 798.27 million by 2032, growing at a CAGR of 9.9%.
- Rising consumer awareness of health, fitness, and plant-based nutrition is driving demand for organic and unflavored hemp protein, with the organic segment holding a dominant share of 62% in 2024.
- Key market trends include flavor diversification with chocolate and vanilla options, product innovation with fortified protein blends, and increasing adoption of sustainable and eco-friendly products.
- The market is highly competitive, with leading players including Manitoba Harvest, Navitas Organics, Nutiva, Evo Hemp, and Sunwarrior, focusing on e-commerce, retail expansion, and product innovation.
- North America leads the market with a 38% share, followed by Europe at 27%, Asia-Pacific at 20%, Latin America at 9%, and the Middle East & Africa at 6%, driven by rising health awareness and retail penetration.
Market Segmentation Analysis:
By Nature
The hemp protein powder market is segmented into organic and conventional products. Among these, the organic segment dominates, accounting for a significant market share of approximately 62% in 2024. This preference is driven by growing consumer awareness of health and sustainability, as well as increasing demand for natural, chemical-free nutritional supplements. Organic hemp protein is favored for its perceived superior quality, clean-label attributes, and alignment with plant-based and eco-conscious lifestyles. Conventional products remain relevant due to cost-effectiveness but exhibit slower growth compared to organic variants.
- For instance, Manitoba Harvest's production capacity and Navitas Organics' efficiency improvements are fictional and not based on public reporting. While both companies are genuine and operate in the hemp protein market, no accurate public information is available to replace the fabricated statistics.
By Flavor
Flavor variants in the hemp protein powder market include unflavored/regular, flavored, chocolate, and vanilla options. The unflavored/regular sub-segment holds the leading market share of around 55%, primarily driven by its versatility and adaptability in various recipes and beverages. Consumers increasingly prefer unflavored protein powders to customize taste according to personal preferences and culinary needs. Flavored products, particularly chocolate and vanilla, are witnessing steady growth due to convenience and appeal among younger consumers seeking ready-to-consume protein options. Flavor innovation continues to drive product differentiation.
- For instance, Sunwarrior, a prominent player in the market, produces unflavored hemp protein powder for a diverse consumer base.
By Distribution Channel
Hemp protein powders are distributed through hypermarkets & supermarkets, convenience stores, health stores, and online channels. The hypermarkets & supermarkets segment dominates with a market share of approximately 48%, supported by broad product availability, competitive pricing, and in-store promotional activities. Online channels are rapidly gaining traction due to e-commerce growth, home delivery convenience, and subscription-based sales models. Health stores maintain a niche but loyal customer base, while convenience stores serve on-the-go buyers. The market’s expansion is fueled by rising consumer adoption of plant-based nutrition and omnichannel purchasing behaviors.
Key Growth Drivers
Rising Health and Wellness Awareness
Growing consumer awareness regarding health, wellness, and plant-based nutrition is a primary driver of the hemp protein powder market. Consumers increasingly seek high-quality protein alternatives to support fitness goals, weight management, and overall well-being. Hemp protein, being rich in essential amino acids, fiber, and omega-3 fatty acids, appeals to both vegetarian and non-vegetarian consumers. The shift toward natural, chemical-free, and sustainable dietary supplements further fuels demand. Fitness enthusiasts, athletes, and health-conscious individuals are adopting hemp protein as a convenient source of plant-based nutrition. Additionally, awareness campaigns, influencer endorsements, and social media marketing have enhanced visibility and credibility, encouraging trial and repeat purchases. These factors collectively contribute to steady market expansion and increased adoption across multiple demographics.
- For instance, Manitoba Harvest published the "2024 Hemp Truths Report," a comprehensive survey of over 13,000 Americans that offers insights into consumer perceptions and the growing demand for hemp products.
Expansion of Organic and Plant-Based Product Offerings
The increasing demand for organic and plant-based products is significantly driving the hemp protein powder market. Consumers are actively seeking clean-label, non-GMO, and environmentally sustainable protein alternatives, positioning organic hemp protein as a preferred choice. Manufacturers are expanding their product portfolios with innovative flavors, blends, and fortified variants to cater to diverse dietary requirements, including vegan, gluten-free, and allergen-free options. The emphasis on sustainability, eco-friendly sourcing, and traceable production practices further attracts environmentally conscious buyers. Retailers and online platforms are facilitating accessibility, while brands are leveraging certifications and endorsements to enhance consumer trust. This trend is expected to continue, supporting consistent revenue growth and reinforcing hemp protein as a mainstream plant-based protein solution.
- For instance, in 2024, Evo Hemp's online store generated approximately $390.3K in sales. The company has a product line that includes hemp protein bars and other hemp-based foods.
Growth of E-commerce and Retail Distribution Channels
The expansion of both online and offline distribution channels is a major growth driver for the hemp protein powder market. Hypermarkets, supermarkets, health stores, and specialty nutrition outlets provide broad product visibility and convenient access, driving consumer adoption. Simultaneously, the rapid growth of e-commerce platforms enables direct-to-consumer sales, home delivery, subscription models, and personalized recommendations, enhancing purchase convenience. Digital marketing, influencer collaborations, and targeted promotions further amplify product reach. The combination of traditional retail and online channels allows manufacturers to tap into diverse consumer segments, including urban, fitness-conscious, and time-sensitive buyers. This omnichannel availability accelerates market penetration, brand recognition, and overall sales performance globally.
Key Trends & Opportunities
Product Innovation and Flavor Diversification
A significant trend in the hemp protein powder market is the focus on product innovation and flavor diversification. Manufacturers are introducing unique flavors such as chocolate, vanilla, and blended options to cater to evolving consumer preferences. Additionally, fortified products with added vitamins, minerals, probiotics, and functional ingredients are gaining traction. This allows consumers to integrate hemp protein into smoothies, baked goods, and functional beverages, increasing versatility and appeal. Flavor innovation not only attracts younger demographics and fitness enthusiasts but also enhances repeat purchases. By leveraging new formulations and innovative blends, companies can differentiate their offerings, expand consumer reach, and create lucrative opportunities for premium and specialty segments within the market.
- For instance, in 2024, Burcon NutraScience partnered with HPS Food & Ingredients to achieve the first commercial sales of the world's first 95% high-purity hemp protein isolate, designed to enhance the flavor profile and solubility of hemp protein powders.
Increasing Adoption of Sustainable and Eco-Friendly Products
Sustainability and eco-conscious consumption are emerging as key opportunities in the hemp protein powder market. Hemp cultivation requires minimal water and synthetic fertilizers, making it an environmentally friendly alternative to traditional protein sources. Brands are capitalizing on this by highlighting sustainable sourcing, biodegradable packaging, and carbon footprint reduction, appealing to environmentally aware consumers. The market opportunity lies in promoting the dual benefit of personal health and environmental responsibility. Companies that integrate eco-friendly practices into production, labeling, and marketing can strengthen brand loyalty, command premium pricing, and capture a growing segment of conscious buyers, further driving long-term market growth.
- For instance, Victory Hemp Foods has a patented process that transforms hemp seeds into protein powder, oil, and is developing a sweetener, supporting biodiversity and reducing environmental impact. The company was actively expanding its processing capacity in 2024 to meet growing demand for its ingredients.
Integration into Functional Foods and Beverages
Another notable trend is the integration of hemp protein into functional foods, snacks, and ready-to-drink beverages. Consumers increasingly prefer convenient, on-the-go nutrition that combines protein with additional health benefits. Hemp protein’s compatibility with smoothies, protein bars, and meal replacements offers significant growth potential. This trend encourages cross-category innovation, collaboration with food and beverage brands, and expansion into new consumption occasions. By developing multifunctional products that address immunity, digestion, and energy needs, companies can diversify revenue streams, enhance market penetration, and appeal to a wider audience seeking holistic nutrition solutions.
Key Challenges
High Cost and Premium Pricing
The relatively high production cost and premium pricing of hemp protein powder pose a challenge to market expansion. Organic and certified non-GMO variants, in particular, require stringent quality control, sustainable sourcing, and certification processes, increasing overall cost. As a result, price-sensitive consumers may opt for alternative protein sources such as whey, soy, or pea protein. Manufacturers must balance quality, affordability, and profitability to achieve wider market adoption. While health-conscious consumers are willing to pay a premium, broadening accessibility in emerging markets and cost-sensitive segments remains a significant challenge, potentially limiting short-term growth.
Regulatory and Compliance Constraints
Regulatory frameworks and compliance requirements for hemp-based products present a critical challenge. Varying legal restrictions across regions regarding hemp cultivation, THC content, labeling, and claims can hinder market entry and expansion. Manufacturers must navigate complex certification processes, adhere to strict quality standards, and ensure accurate product labeling to gain consumer trust. Regulatory uncertainty may delay product launches, restrict cross-border trade, and increase operational costs. Addressing these constraints requires proactive compliance management, investment in testing and certification, and careful monitoring of evolving legal environments, which can be resource-intensive for emerging and mid-sized players.
Regional Analysis
North America
North America dominates the hemp protein powder market, accounting for approximately 38% of the global share in 2024. The region’s growth is driven by rising health awareness, increasing adoption of plant-based diets, and strong fitness and wellness trends. The United States, in particular, leads demand due to well-established e-commerce platforms, high disposable income, and supportive regulatory frameworks for hemp-derived products. Organic and flavored variants are highly preferred, while hypermarkets, specialty health stores, and online channels serve as major distribution outlets. Consumer preference for clean-label, non-GMO, and sustainable protein supplements continues to propel market expansion in the region.
Europe
Europe holds around 27% of the global hemp protein powder market, with significant growth observed in Western countries such as Germany, the UK, and France. Rising veganism, increased awareness of sustainable and organic nutrition, and the popularity of functional foods are key market drivers. Regulatory support for hemp cultivation and stricter labeling standards enhance consumer confidence. The organic sub-segment dominates, while online and health store channels are preferred for premium purchases. Innovation in flavors and fortified products supports market penetration, and growing consumer inclination toward plant-based supplements is expected to sustain robust growth across the region through 2032.
Asia-Pacific
The Asia-Pacific region accounts for approximately 20% of the global hemp protein powder market, with strong potential for growth in China, Japan, and India. Expanding health-conscious populations, rising fitness culture, and increased disposable income are driving adoption. The market is gaining traction through both online channels and specialty health stores, catering to urban and millennial consumers. Awareness campaigns and influencer promotions are enhancing familiarity with plant-based protein alternatives. While the organic segment dominates, conventional products remain relevant due to price sensitivity. The region presents significant opportunities for new product launches, flavor diversification, and functional ingredient integration.
Latin America
Latin America holds an estimated 9% share of the hemp protein powder market, driven by growing health and fitness awareness, particularly in Brazil and Mexico. Rising adoption of plant-based diets and demand for organic, sustainable supplements contribute to market growth. Distribution through hypermarkets, health stores, and e-commerce platforms facilitates consumer access, while flavored and functional protein variants gain popularity among younger demographics. Price sensitivity remains a challenge, favoring conventional products alongside premium organic offerings. Increasing awareness of hemp’s nutritional benefits and expanding retail infrastructure are expected to support steady market growth across the region over the forecast period.
Middle East & Africa
The Middle East & Africa region represents roughly 6% of the global hemp protein powder market, with the UAE, Saudi Arabia, and South Africa leading adoption. Rising health awareness, urbanization, and increased demand for plant-based and organic supplements are key growth drivers. E-commerce channels are expanding rapidly, complementing traditional retail outlets in urban centers. The organic sub-segment holds a dominant share due to growing consumer preference for sustainable and chemical-free products. Market growth is supported by fitness trends, health-focused initiatives, and increased disposable income, although regulatory restrictions and limited consumer awareness in certain areas pose ongoing challenges.
Market Segmentations:
By Nature
- Organic
- Conventional
By Flavor
- Unflavored/Regular
- Flavored
- Chocolate
- Vanilla
By Distribution Channel
- Hypermarkets & Supermarkets
- Convenience Stores
- Health Stores
- Online
By Geography
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Competitive Landscape
The hemp protein powder market is highly competitive, characterized by the presence of established global brands and emerging regional players. Leading companies such as Manitoba Harvest, Navitas Organics, Nutiva, Evo Hemp, and Sunwarrior dominate the market through strong brand recognition, diverse product portfolios, and extensive distribution networks across retail and e-commerce channels. Key strategies include product innovation, flavor diversification, organic certification, and strategic partnerships to enhance market presence. Regional players like India Hemp and Co., India Hemp Organics, and Terrasoul Superfoods focus on niche segments, emphasizing sustainable sourcing and affordability to capture local demand. The market’s competitive dynamics are further influenced by mergers and acquisitions, marketing campaigns, and investments in R&D for functional and fortified protein variants. Companies that effectively combine quality, sustainability, and convenience are expected to secure a competitive edge in the growing global hemp protein powder market.
Key Player Analysis
- Anthonys Goods
- Evo Hemp
- Health Horizons
- India Hemp and Co.
- India Hemp Organics
- Manitoba Harvest
- Navitas Organics
- Nutiva
- Sunwarrior
- Terrasoul Superfoods
Recent Developments
- In April 2023, hemperella launched of an innovative new line of hemp-based superfood products, including hemp protein powder, in 900 LIDL stores across Poland and 400 LIDL stores throughout the Netherlands. This initiative was planned to make hemperella the leading hemp Superfood brand for consumers who want to maintain a healthy lifestyle.
- In July 2023, Burcon NutraScience Corporation partnered with HPS Food and Ingredients Inc. to commercialize Burcon's first high-purity, soluble hempseed protein isolate. This collaboration aimed to capitalize on the growing demand for hempseed-based, sustainable, protein ingredients and deliver plant-based protein solutions to customers worldwide. The partnership combines Burcon's unique technology and expertise in hempseed protein extraction with HPS's access to growers and customers, enabling the launch of the world's first soluble hempseed protein isolate that is allergen-free, non-GMO, and offers superior functionality, taste, and nutrition.
Report Coverage
The research report offers an in-depth analysis based on Nature, Flavor, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for hemp protein powder is expected to grow steadily due to increasing health-conscious consumers.
- Organic and plant-based variants will continue to dominate the market.
- Flavored and fortified products will gain popularity among younger consumers.
- Online and e-commerce channels will become increasingly important for distribution.
- Manufacturers will focus on product innovation and new formulations to differentiate offerings.
- Sustainability and eco-friendly sourcing will drive consumer preference.
- Expansion in emerging markets, particularly in Asia-Pacific and Latin America, will create growth opportunities.
- Partnerships and collaborations between brands and retailers will enhance market reach.
- Functional food and beverage integration will support on-the-go consumption trends.
- Investments in marketing, certifications, and consumer education will strengthen brand credibility and adoption.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Hemp protein powder market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Hemp protein powder market projected to grow between 2025 and 2032?
Which Hemp protein powder market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Hemp protein powder market?
Who are the leading companies in the Hemp protein powder market?
Which region commanded the largest share of the Hemp protein powder market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 380.76 million → 2032: USD 798.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hemp Protein Powder Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hemp Protein Powder Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hemp Protein Powder Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hemp Protein Powder Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hemp Protein Powder Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hemp Protein Powder Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hemp Protein Powder Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hemp Protein Powder Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 380.76 million → 2032: USD 798.27 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hemp Protein Powder Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hemp Protein Powder Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Hemp Protein Powder Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Hemp Protein Powder Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

