
Canadian toy sales rebounded on games and building sets
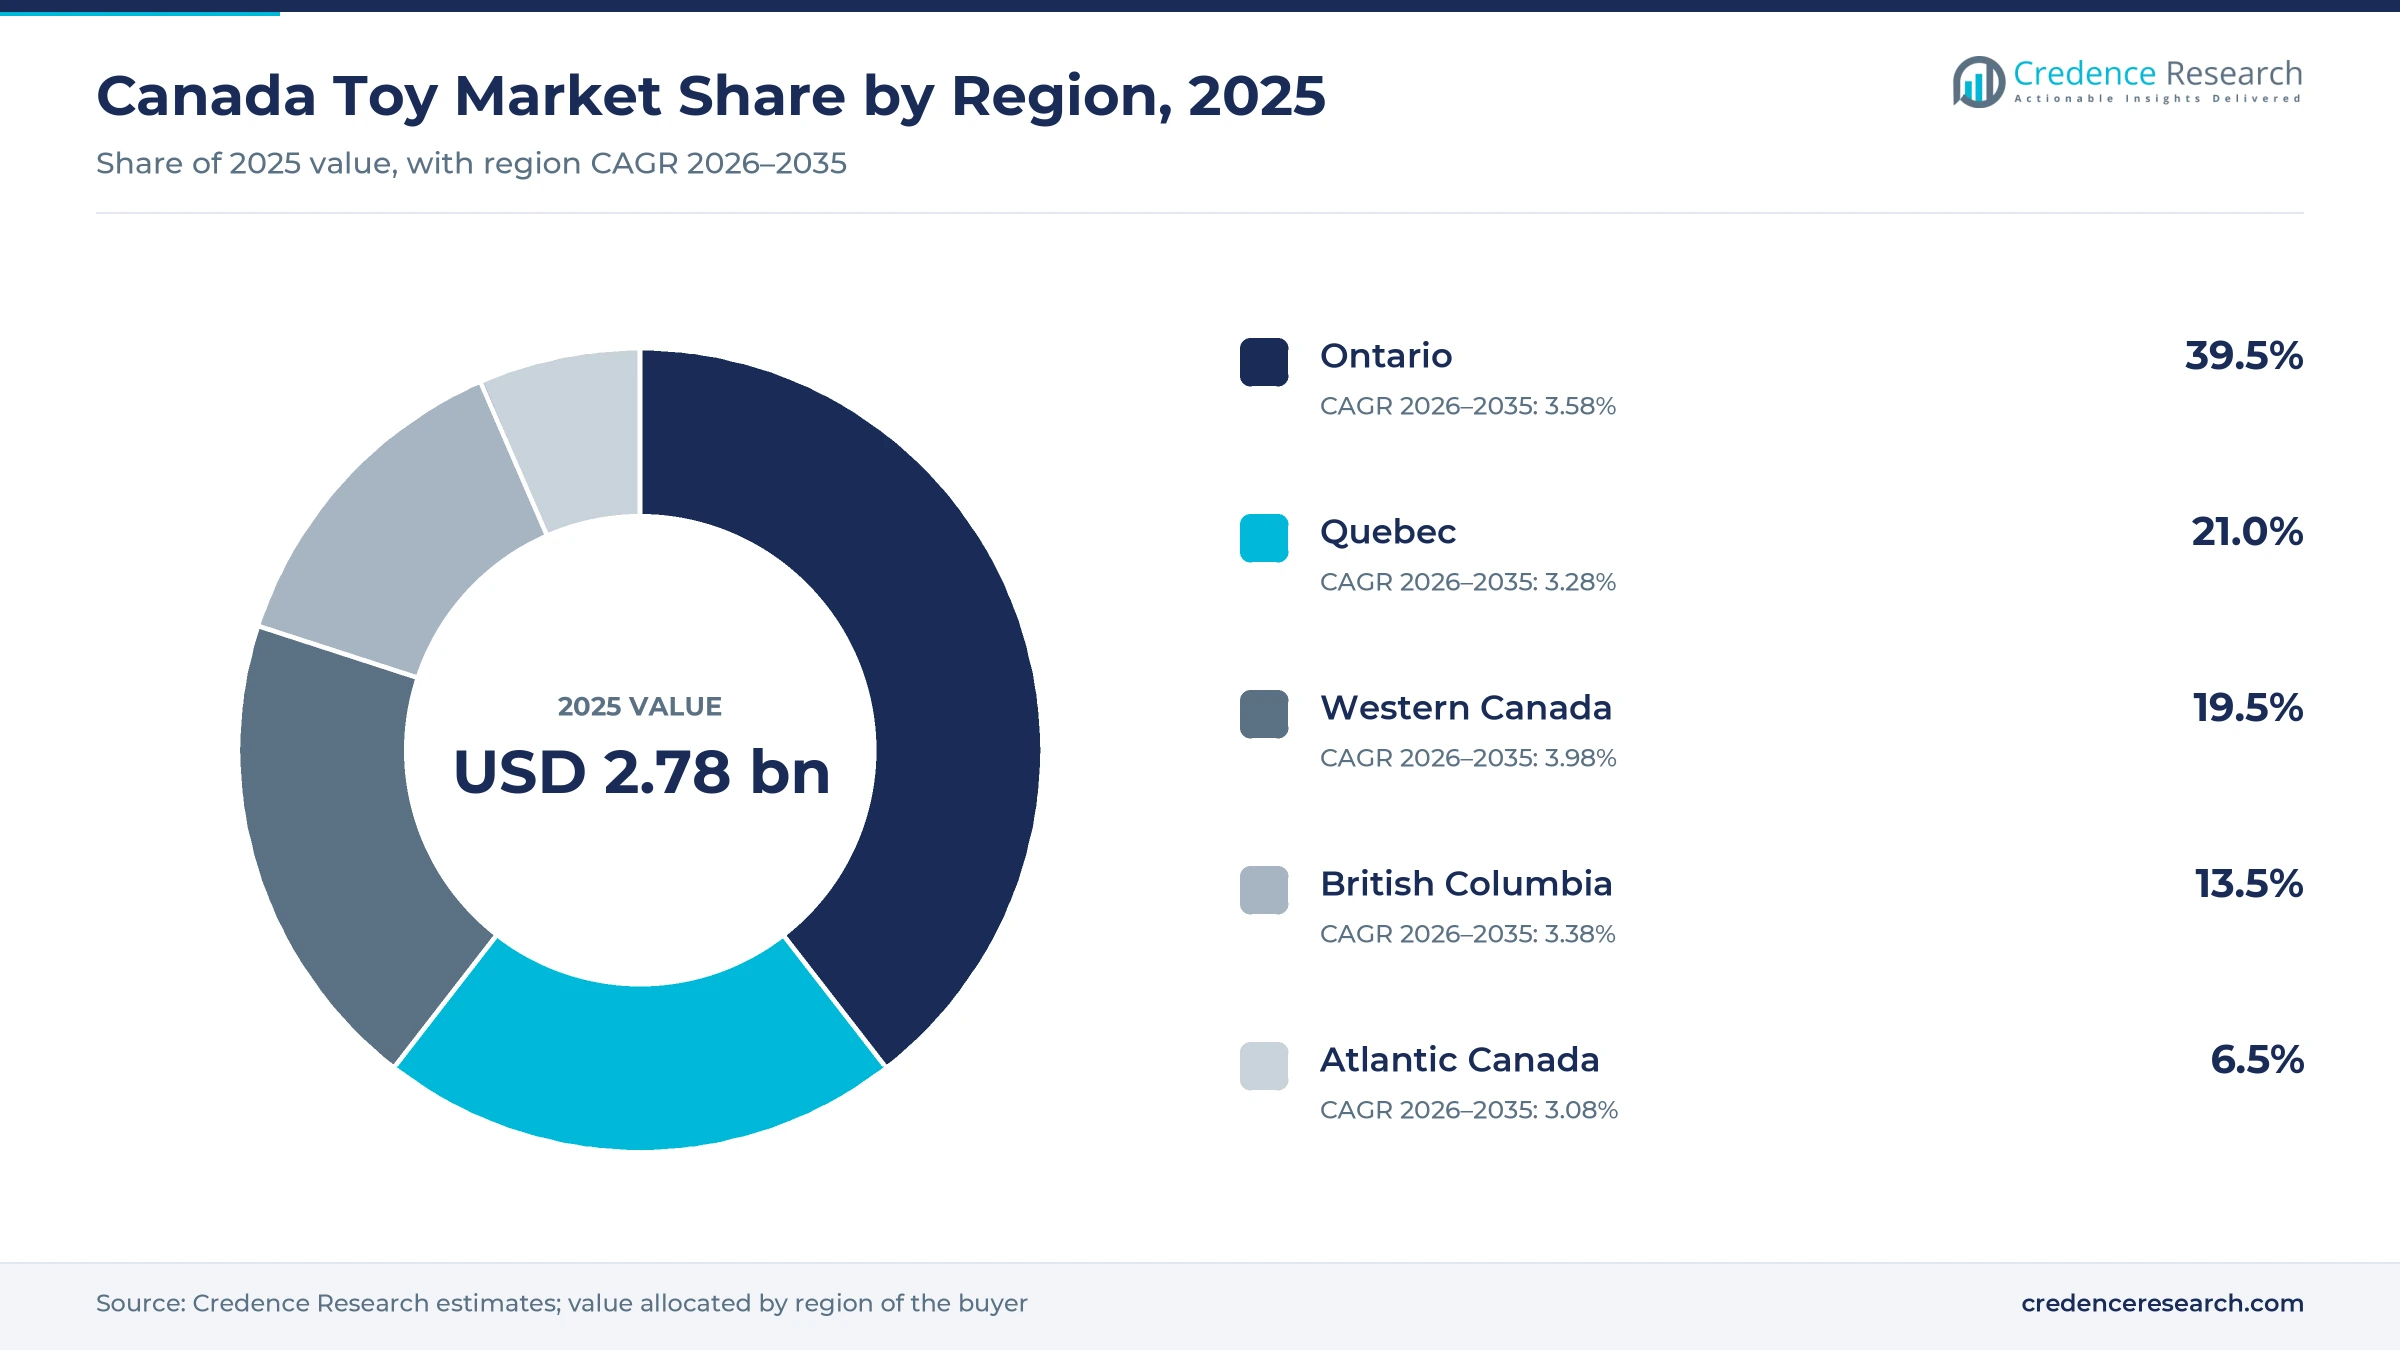
The Canada toy market was valued at USD 2.78 billion in 2025 and is projected to increase from USD 2.88 billion in 2026 to USD 3.94 billion by 2035, registering a CAGR of 3.54% during 2026–2035. Spending rests on about 6.26 million children aged 0 to 14 and on adults who now buy building sets, trading cards and collectibles for themselves. Ontario held the largest regional share, 39.5% in 2025, because it holds close to four in 10 Canadians, while Western Canada is the fastest-growing region at 3.98% a year. Tracked retail sales climbed 14% in 2025 as games and puzzles surged, which ended two weak years for the sector. The retail map changed at the same time because ToysRUs Canada entered creditor protection in February 2026, and LEGO began moving from 12 to 15 Canadian stores. Button battery rules that Health Canada listed in September 2026 also tightened product design for electronic play.
How big is the toy industry in Canada and who buys?
The estimate counts retail spending in Canada on building sets, games and puzzles, vehicles, action figures, dolls, plush, infant and preschool items, and outdoor play products. Parents and grandparents remain the core buyers, but adults purchasing for themselves now shape the premium end, and sales peak in the holiday quarter across mass, specialty and online retailers.
Video game software, consoles and digital subscriptions fall outside the estimate, as do juvenile furniture and car seats. Most supply is imported by brand subsidiaries and national distributors, which sell through mass merchants, warehouse clubs, specialty chains, independents and online marketplaces in English and French.
Canada Toy Market Insights
- The Canada toy market grows from USD 2.78 billion in 2025 to USD 3.94 billion by 2035, a 3.54% CAGR, with price, mix and adult buyers doing most of the work.
- Ontario held the largest regional share at 39.5% in 2025, while Western Canada grows fastest at 3.98% a year on its younger provincial age profile.
- Building & Construction Sets led product types with 19.3% of 2025 value after tracked category sales rose 25% to about C$516 million in that year.
- ToysRUs Canada sought creditor protection in February 2026 and an Ontario court approved a breakup in June 2026, which moved sales toward other chains.
- LEGO is raising its Canadian store count from 12 to 15 by the end of 2026, the largest expansion of its national retail network in five years.
Building sets lead while games and puzzles grow fastest
Building sets lead as games and puzzles post the sharpest rise
Based on product type, the market is categorized into building and construction sets, plush and other toys, games and puzzles, vehicles and action figures, outdoor and sports toys, infant and preschool toys, and dolls. Building & Construction Sets led with 19.3% of 2025 value because tracked sales rose 25% to about C$516 million, according to Retail Insider in August 2026. Games & Puzzles grow fastest at 4.76% a year as tracked sales jumped 56% to about C$464 million in 2025. Outdoor items lost ground earlier, falling 19% in 2023 in Canadian Toy Association data, which keeps that category below its former top rank.
School-age children lead while adult buyers add the fastest growth
Based on age group, the market is categorized into 0 to below three years, 3 to below five years, 5 to below 12 years, 12 to 18 years, and 18+ years. The 5 to Below 12 Years band led with 43.0% of 2025 value because this band covers seven of the 15 single-year ages among the 6,261,162 residents aged 0 to 14 that Statistics Canada counted on July 1, 2025. The 18+ Years band grows fastest at 4.99% a year as adult collectors support premium sets, a shift that Radio Canada International linked in 2025 to an 18% first-half sales rise. Canadian births of 365,737 in 2024 keep the youngest bands steady.
Stores still lead, but online toy buying gains share
Based on distribution channel, the market is categorized into online and offline sales. Offline led with 68.0% of 2025 value because mass merchants, warehouse clubs and specialty chains still carry the holiday assortment, and Mastermind Toys kept 48 stores after its 2023 rescue, according to Radio Canada International. Online sales grow fastest at 4.54% a year as ToysRUs Canada shrank to a 22-store network by February 2026, according to Retail Insider. Radio Canada International also quoted a Canadian Toy Association board member linking big-box losses to e-commerce, Walmart and Amazon.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Building & Construction Sets | 19.3% | Games & Puzzles | 4.76% |
| By Age Group | 5 to Below 12 Years | 43.0% | 18+ Years | 4.99% |
| By Distribution Channel | Offline | 68.0% | Online | 4.54% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Hobby buying and licensing lift spending per child
Games, puzzles and trading cards pull in new buyers
Tabletop play has become the sector's strongest source of new spending because it sells to families and adult hobbyists alike. Tracked toy sales rose 14% to about C$2.68 billion in 2025, according to Retail Insider, and games and puzzles led that gain with a 56% rise to about C$464 million. The Toy Association reported in January 2026 that games and puzzles rose 30% across 12 major toy markets, so the Canadian result ran well ahead of the wider surge. Ravensburger opened Canadian offices in Montreal and Toronto in February 2020, which gave the puzzle maker a direct line to hundreds of local retailers. As a result, Games & Puzzles reach 4.76% a year in this forecast.
Adult collectors widen the market beyond childhood
Adult purchases matter more each year because they add buyers while the child population stays flat. Statistics Canada counted 6,261,162 residents aged 0 to 14 on July 1, 2025, unchanged from a year earlier, so child numbers alone cannot explain the growth. Radio Canada International tied the 18% rise in first-half 2025 sales partly to adult collectors, and CTV News reported the same pattern in August 2025. The Toy Association added in January 2026 that collectibles rose 32% and reached a share of almost 19% of global dollar sales. Building sets also posted strong Canadian growth during 2025, and those premium kits appeal strongly to older hobbyists. Credence Research therefore gives the 18+ Years band the fastest rate at 4.99% a year.
Licensed properties and film releases drive holiday sales
Entertainment tie-ins raise spending because each release creates a dated reason to buy before the holiday quarter. The Toy Association reported in January 2026 that licensed toys rose 15% in 2025 and reached 37% of global sales, the highest share yet recorded. Toronto-based Spin Master released PAW Patrol The Dino Movie on Aug. 14, 2026, and Retail Insider noted that the film and its merchandise were also launching in Canada. Moose Toys won Top New Brand at the Canadian Toy Awards on Nov. 18, 2025, for its Mr. Beast Lab line, which shows how quickly creator properties now convert. Tracked action figure sales rose 13% in 2025, as these properties reached shelves.
Child care spaces and new families support early play
Public child care spending supports early-years demand because each new licensed space needs learning materials, and working parents have more room in household budgets. Ottawa announced up to C$36.8 billion in extended funding in March 2025, with Ontario receiving C$16.77 billion and Quebec C$9.83 billion over the five years to 2030-31. The Canadian Press reported in June 2026 that about 173,500 of the 250,000 targeted spaces existed, and that a further C$5.4 billion was coming over two years. Births also rose 3.7% to 365,737 in 2024, according to Statistics Canada, which steadies demand among the youngest buyers. Tracked sales of infant play products and preschool lines recovered 6% in 2025.
Retail is shifting from big boxes to brand stores and online
Shift from big-box chains to brand stores and specialists
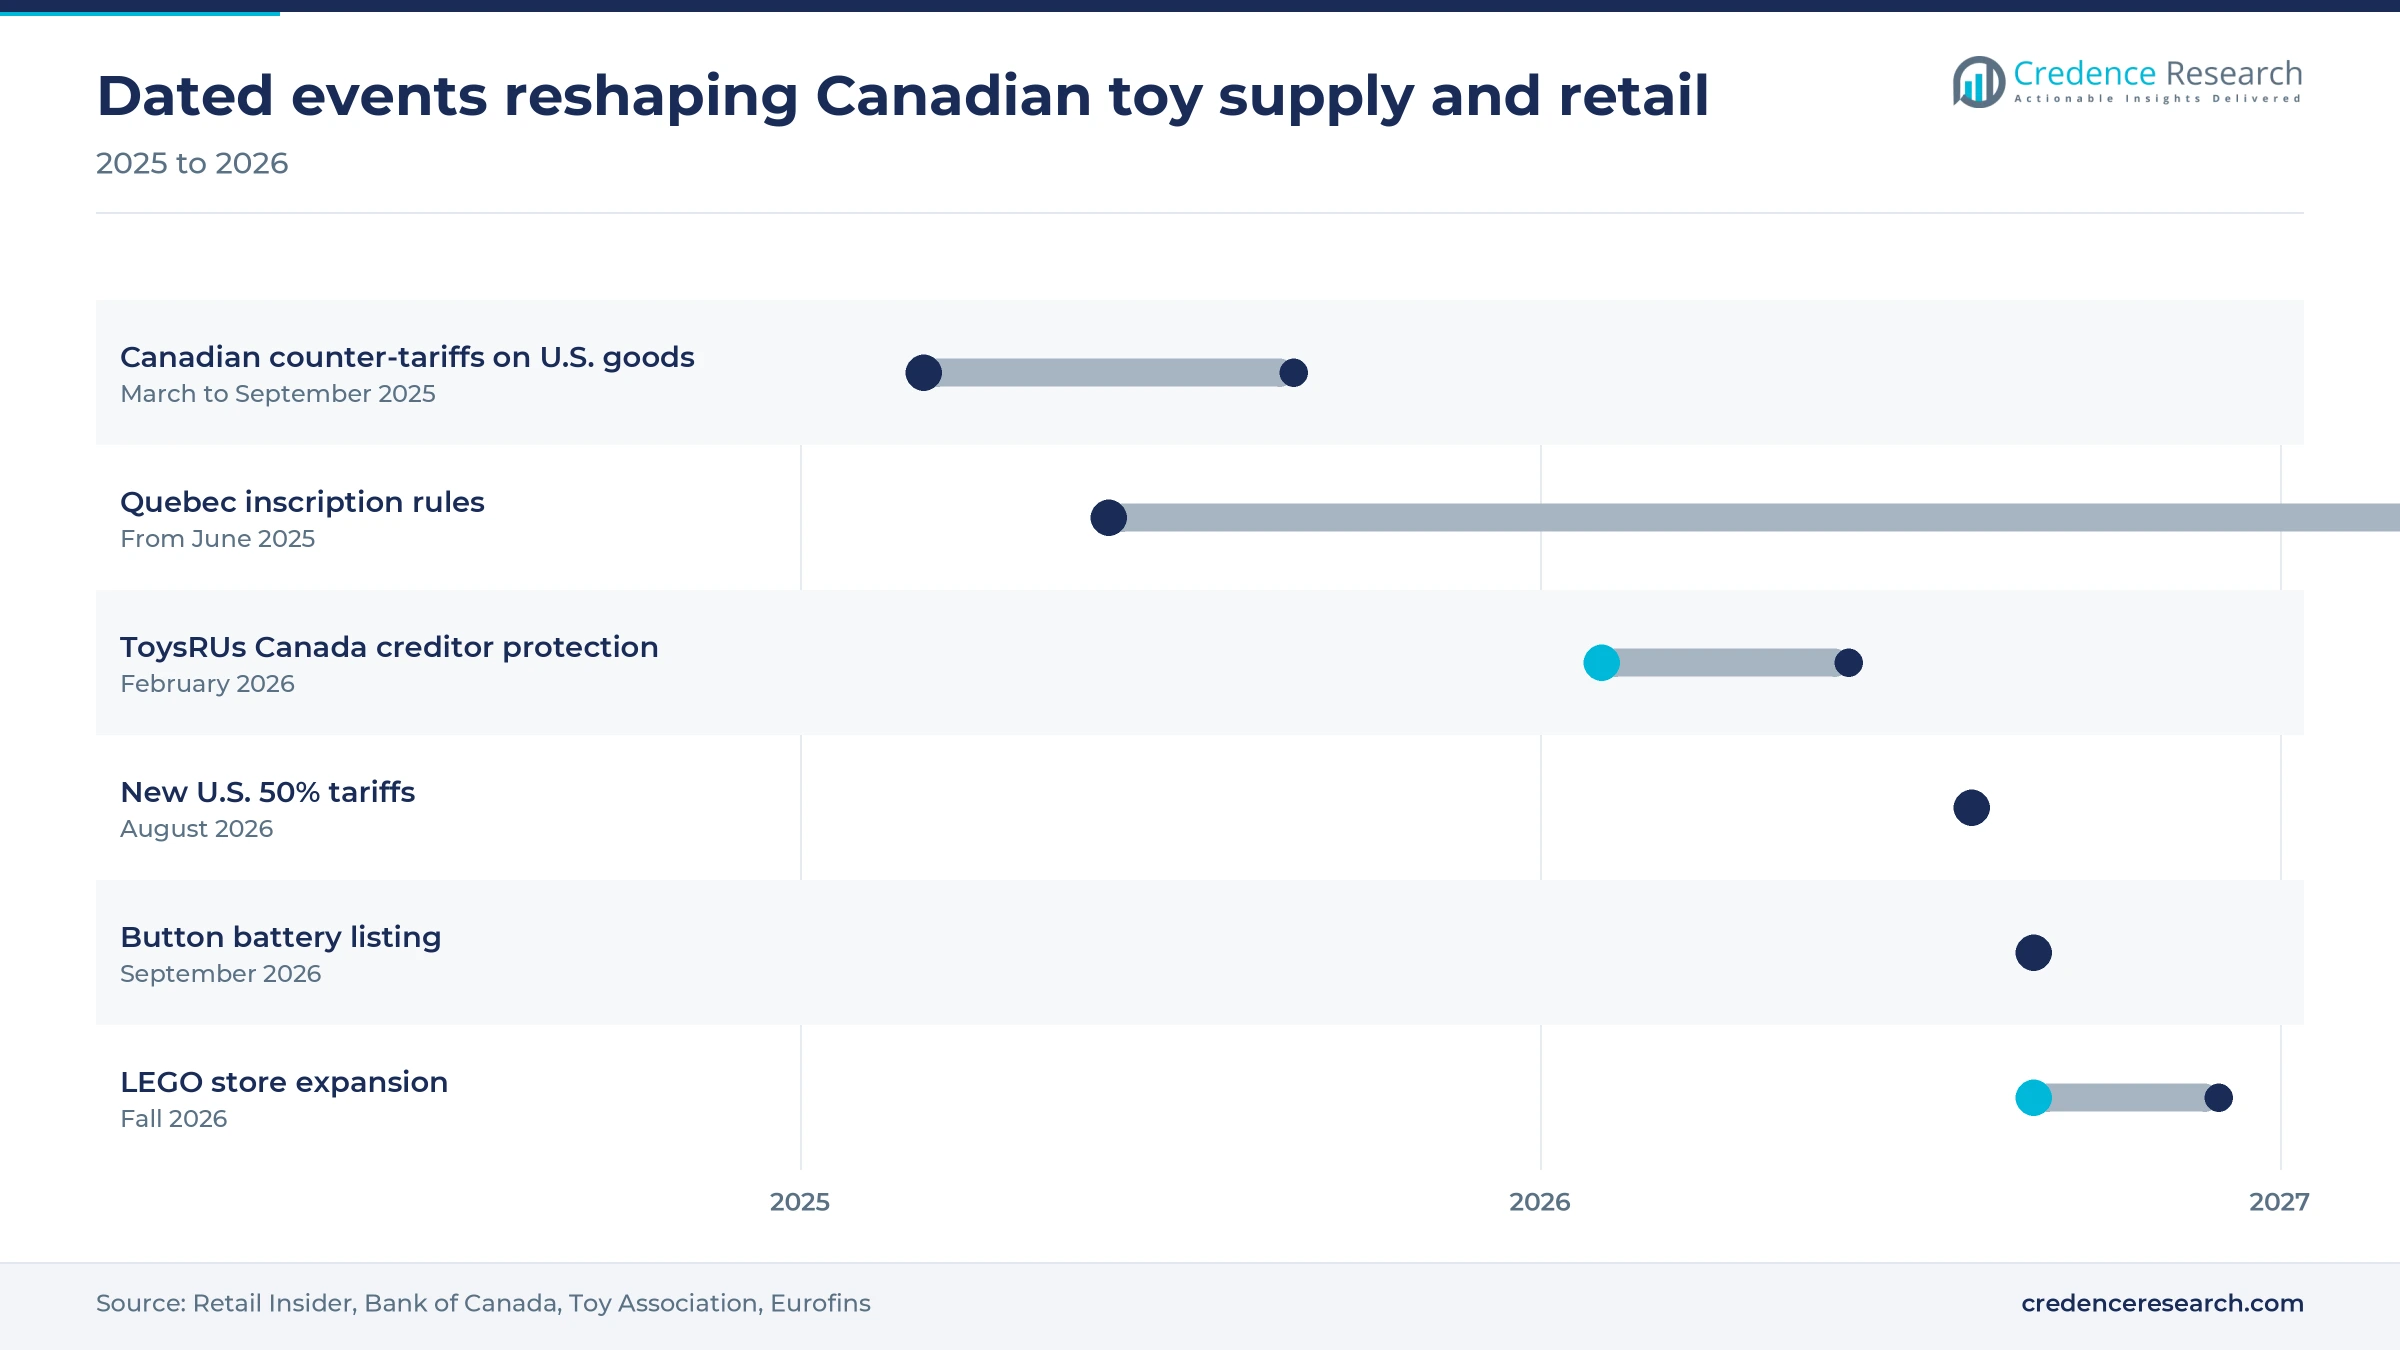
The national retail structure is moving away from large toy-only boxes toward smaller branded and specialist formats. ToysRUs Canada closed its last British Columbia store in Langley on Jan. 13, 2026, and sought creditor protection that February, according to Retail Insider. An Ontario court then approved a breakup in June 2026 that left 10 store leases with a Doug Putman company and the brand with Ad Populum. LEGO moved the opposite way, opening a 2,637-square-foot store at CF Toronto Eaton Centre in October 2026, according to iPhone in Canada, on its path from 12 to 15 stores. Mastermind Toys meanwhile survived its 2023 insolvency with 48 stores under Unity Acquisitions.
Rise of AI companions and tighter scrutiny of smart play
Connected play is moving from novelty into mainstream debate as talking products reach Canadian shoppers. The Canadian Press reported on Nov. 26, 2025, that Curio's Gabbo, Grem and Grok plush characters were drawing warnings from Ottawa and Toronto child development specialists. That report also said the office of federal AI minister Evan Solomon was monitoring how AI is built into children's products. The Toy Association barred AI companion chatbot products from Toy Fair 2026, citing safety concerns, which signals caution among established suppliers. Demand for AI-enabled companions therefore remains a small part of the plush and other category, and privacy disclosure is likely to decide which smart products win retail listings in Canada.
Opportunity in replacing lost ToysRUs shelf space
The contraction of a national specialist opens a clear shelf-space opportunity for distributors and independents. Retail Insider counted a 22-store network in February 2026, down from more than 80 stores at its peak, and Saskatchewan and British Columbia have now lost the banner. Kroeger Marketing and TOMY International announced a partnership on May 11, 2026, covering mass, specialty, online and independent retail, including John Deere, Kirby and Lamaze lines. An Ontario court approved the June 2026 breakup, with 10 store leases going to one buyer, so that demand must be won back store by store. Western Canada offers the clearest regional gap in the Canada toy market because the chain now keeps few western locations.
Opportunity in bilingual packs and safer electronic designs
Compliance strength is becoming a selling point, which creates an opening for suppliers able to meet Canadian rules early. Quebec's product inscription changes took effect on June 1, 2025, according to DLA Piper, with generic terms on packs required in French and a sell-through period for older stock ending June 1, 2027. Health Canada then listed button and coin battery products on Sept. 18, 2026, with no transition period, according to Eurofins, requiring toys to meet ASTM F963-23. Kroeger Marketing already sells bilingual market execution as a service for TOMY. Quebec holds 21.0% of 2025 value, so bilingual packs protect a large regional share of national sales for smaller importers.
Tariffs, recalls and retailer failures test the sector
Trade disputes keep landed costs unpredictable
Trade policy remains the sector's largest cost risk because most supply crosses at least one contested border. Canada's 25% counter-tariffs of March 4, 2025, pushed tariffed goods' online prices about 6% above a control group by mid-June, according to the Bank of Canada, before most were removed on Sept. 1, 2025, and prices fell back. The Toy Association reported that certain toys face new 50% U.S. tariffs from Aug. 22, 2026, although heading 9503 toys sit outside Canada's proposed retaliatory list for Sept. 8. Importers must therefore recheck each product code after every tariff change.
A flat child population limits unit growth
Demographics cap unit sales because the core child audience has stopped growing. Statistics Canada reported a total fertility rate of 1.26 in 2025, matching the record low of 2024, which limits demand among young children. Infant and preschool suppliers feel this first, since tracked sales fell 8% in 2023 and 7% in 2024. Higher-priced sets and adult lines offset part of this pressure, although they raise exposure to discretionary spending cycles.
Recalls expose online marketplaces and small importers
Product safety enforcement is a recurring cost, especially for small importers selling through online marketplaces. Health Canada found all six magnet products sampled in its 2021-2022 compliance project failed the Toys Regulations, including items sold through Amazon Canada and Walmart Canada, although the sample was not random. Health Canada published a July 31, 2025, recall of about 1,977 Tegu Floating Stacker units after one Canadian magnet report. Recalls therefore raise testing and refund costs, which weigh most on small importers with thin margins and limited compliance staff.
Retail failures leave suppliers with unpaid balances
Retail insolvency hurts suppliers directly because holiday inventory is often shipped on credit terms. Retail Insider reported in January 2026 that claims against ToysRUs Canada totaled about C$35 million, including more than C$4 million sought by suppliers for unpaid merchandise. Mastermind Toys had already closed 18 of its 66 stores in its 2023 restructuring, a sign that this retail pressure is not new. Vendors can answer with tighter credit checks and wider account lists, although that lengthens selling cycles and raises service costs for smaller brands.
Ontario anchors demand as western provinces grow fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Ontario | 1.10 | 39.5% | 3.58% |
| Quebec | 0.58 | 21.0% | 3.28% |
| Western Canada | 0.54 | 19.5% | 3.98% |
| British Columbia | 0.38 | 13.5% | 3.38% |
| Atlantic Canada | 0.18 | 6.5% | 3.08% |
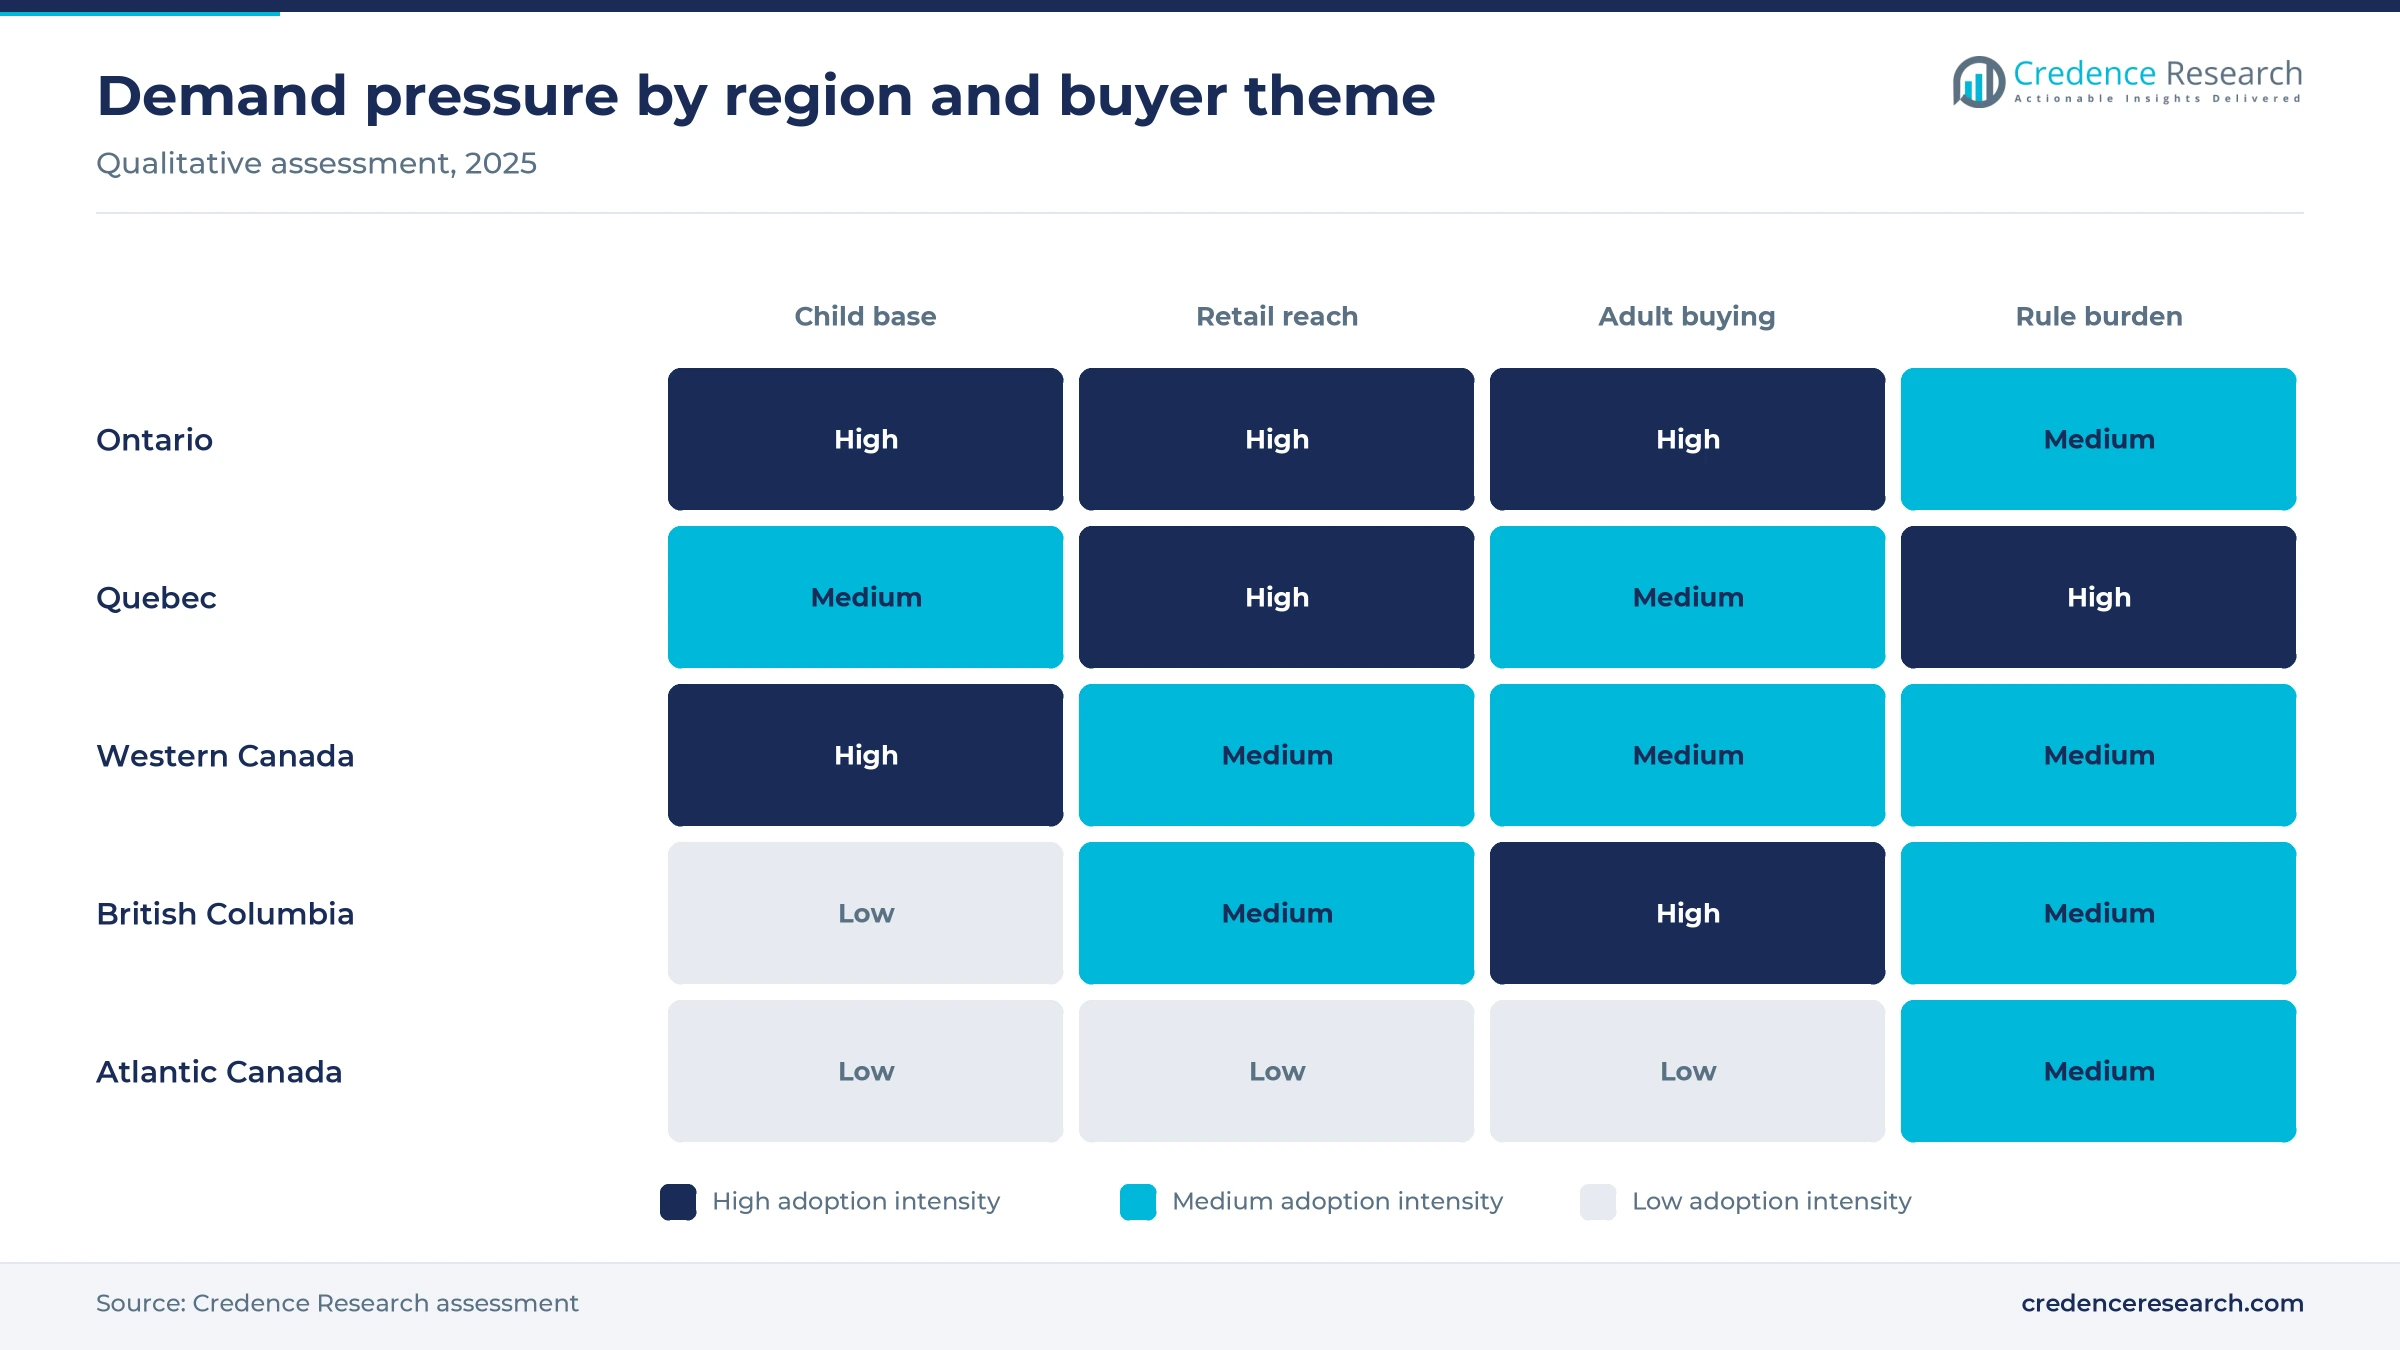
Ontario holds the largest buyer base and the most retail change
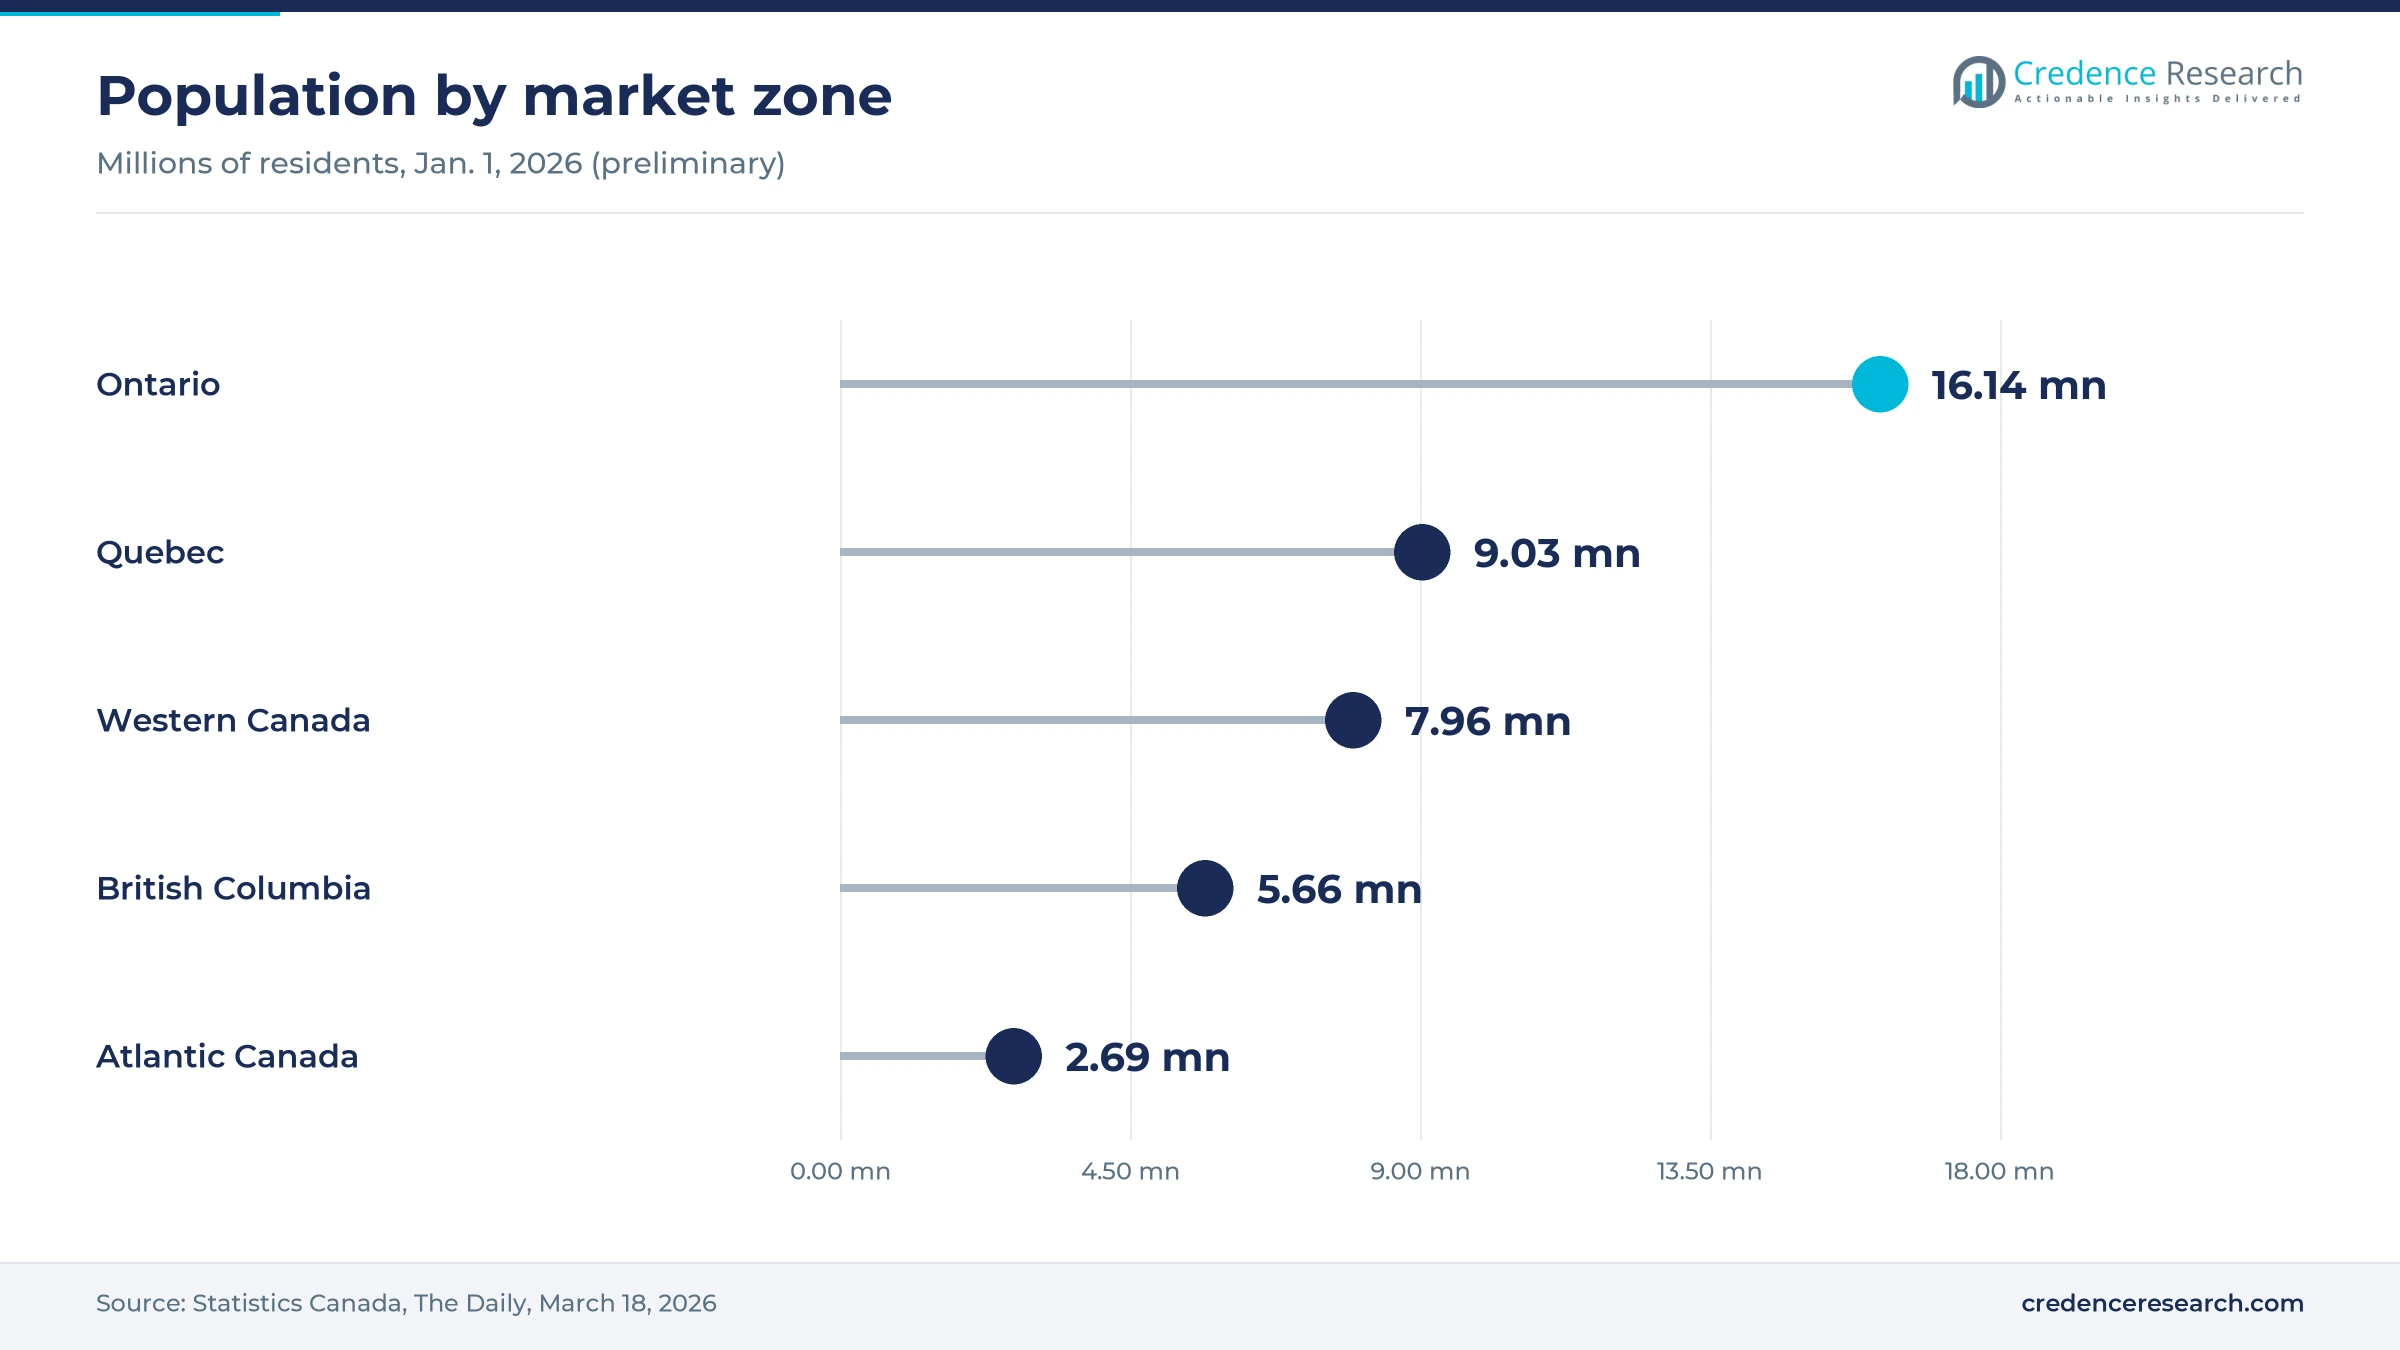
Ontario held 39.5% of 2025 value and grows at 3.58% a year, because Statistics Canada counted 16,136,480 residents there on Jan. 1, 2026, the largest provincial total. The province also receives C$16.77 billion of extended federal child care funding. Three new LEGO stores at CF Markville, CF Toronto Eaton Centre and Square One were planned for fall 2026, which concentrates premium brand retail in the Greater Toronto Area. Spin Master also keeps its head office in Toronto, inside this zone.
Quebec combines a large market with distinct language rules
Quebec held 21.0% of 2025 value and grows at 3.28% a year, a slower pace because its packaging rules raise the cost of serving smaller import lines. Statistics Canada counted 9,033,887 residents on Jan. 1, 2026, and The Canadian Press reported in September 2026 that Quebec births rose in 2025 for the first time since 2021. French inscription rules changed on June 1, 2025, according to DLA Piper. Ravensburger also runs a Montreal office, which gives the zone a major puzzle supplier.
Western Canada grows fastest on younger prairie families
Western Canada held 19.5% of 2025 value and grows fastest at 3.98% a year because the zone has higher fertility than most of the country. Statistics Canada reported 2025 fertility rates of 1.58 in Saskatchewan and 1.50 in Manitoba, against 1.26 nationally, and Alberta alone had 5,048,151 residents on Jan. 1, 2026. Retail coverage is thinner, however, because ToysRUs left Saskatchewan in January 2026, according to Retail Insider. That gap gives mass merchants and online sellers more of the regional basket.
British Columbia loses a banner but keeps strong spending
British Columbia held 13.5% of 2025 value and grows at 3.38% a year, slightly below the national rate because its fertility rate was only 1.04 in 2025, according to Statistics Canada. The province counted 5,658,528 residents on Jan. 1, 2026, which keeps it a major market despite that low birth base. ToysRUs closed its last full-line store there in Langley on Jan. 13, 2026, according to Retail Insider, after three Metro Vancouver closures in 2025, which moved shoppers toward other formats.
Atlantic Canada remains the smallest and slowest zone
Atlantic Canada held 6.5% of 2025 value and grows at 3.08% a year, the slowest pace in the country, because its child population is small and aging. Statistics Canada reported 2025 fertility rates of 1.07 in Nova Scotia, 1.08 in Newfoundland and Labrador, and 1.21 in New Brunswick, all at record lows. The four provinces together held about 2.69 million residents on Jan. 1, 2026, which makes this the smallest region by demand. Distance also raises delivery costs, so regional shoppers rely on national mass merchants and online orders.
Openings and insolvencies reshaped retail
| Development | Status and market relevance |
|---|---|
| In October 2026, LEGO opened a 2,637-square-foot store at CF Toronto Eaton Centre, its second Greater Toronto Area opening that fall | Part of a move from 12 to 15 Canadian stores by the end of 2026 |
| In September 2026, Health Canada added button and coin battery products to Table 3 of its general prohibitions process | Effective immediately, with toys required to meet ASTM F963-23 |
| In June 2026, an Ontario court approved the breakup of ToysRUs Canada, with 10 store leases going to a Doug Putman company | The brand went to Ad Populum, and later store plans remain uncertain |
| In May 2026, Kroeger Marketing and TOMY International announced a Canadian distribution partnership covering mass, specialty and independent retail | Initial lines include John Deere, Kirby and Lamaze |
| In November 2025, the Canadian Toy Association presented its first Canadian Toy Awards to ZURU and Moose Toys | Winners were chosen using retail sales performance data |
Connected play and new rules are changing product design
- AI plush companions such as Curio's Gabbo talk with children through a Wi-Fi connection, and Canadian specialists warned about them in November 2025.
- Button battery compartments in toys must now meet ASTM F963-23 in Canada, a rule that Health Canada listed on Sept. 18, 2026.
- Magnet strength limits under the Toys Regulations remain a common failure point, as all six products sampled in Health Canada's 2021-2022 project showed.
- Bilingual pack design has become a production requirement for Quebec, because generic terms must appear in French under rules effective June 1, 2025.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Global brands and Toronto-based Spin Master set the pace
Competition centers on licensed properties, retail shelf space and new product speed, and the leaders differ by category. LEGO anchors premium building with its growing store network, while Mattel brought its Brick Shop building line in 2025 and holds the top Canadian products in vehicles and dolls through Hot Wheels and the Barbie Dreamhouse, according to Retail Insider. Toronto-based Spin Master spans PAW Patrol, Melissa & Doug, Rubik's and GUND, and it dropped planned price increases after receiving about USD 38 million in tariff refunds late in the second quarter of 2026. Ravensburger competes in puzzles from Montreal and Toronto, and ZURU won Top Rising Manufacturer at the 2025 Canadian Toy Awards. National distributors such as Kroeger Marketing give foreign brands bilingual retail access. The Canadian Toy Association, founded in 1932, represents manufacturers, importers and distributors, and it hosts the sector's annual gala in Mississauga.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Spin Master | Canadian brand owner | Toronto-based owner of PAW Patrol, Melissa & Doug, Rubik's and GUND lines |
| Mattel | Global brand owner | Hot Wheels and Barbie Dreamhouse were top Canadian sellers in their categories in 2025 |
| LEGO Group | Global brand and retailer | Expanding its Canadian store network from 12 to 15 by the end of 2026 |
| Ravensburger | Global puzzle and games maker | Operates Canadian offices in Montreal and Toronto since February 2020 |
| ZURU | Global brand owner | Named Top Rising Manufacturer at the 2025 Canadian Toy Awards |
| Moose Toys | Global brand owner | Its Mr. Beast Lab line won Top New Brand in November 2025 |
| TOMY International | Global brand owner | Expanding in Canada from May 2026 through a distribution partnership |
| Kroeger Marketing | Canadian distributor | Provides logistics, merchandising and bilingual execution for TOMY lines |
Value growth depends on older buyers, not more children
Credence Research's view is that Canadian toy value growth now depends more on who buys than on how many children there are. The 2025 surge in games and puzzles should not be extrapolated, because trading card cycles can reverse and earlier categories have fallen sharply, as outdoor items did in 2023. Steadier growth is more likely from premium building lines, licensed collectibles and adult buyers. Retail consolidation is the variable to watch, because the end of a national toy specialist hands negotiating power to a small number of mass and online sellers.
How Credence Research built the 2025 market estimate
The report uses 2025 as the base year and forecasts values through 2035. Credence Research built the market value from retail tracking data published by the Canadian Toy Association, adjusted upward because the tracking service estimates it covers about 69% of the market, and converted at the Bank of Canada average 2025 exchange rate. Segment and regional shares are Credence Research estimates, informed by category sales and Statistics Canada population and fertility data. Other sources include federal agencies, company releases and Canadian news publishers. No interviews or surveys were conducted by Credence Research for this edition.
Premium play and fewer big-box stores shape demand to 2035
Through 2035, the market rises from USD 2.88 billion in 2026 to USD 3.94 billion, with growth led by price, premium mix and adult purchasing rather than more young children. Western Canada should keep the fastest regional pace, and online sellers should keep gaining as physical toy specialists shrink and brand stores cover only the largest cities. U.S. tariff disputes and Canadian rule changes will decide landed costs in most years. The global sales of play products cycle will still influence product launches, and backyard play equipment should stabilize after its earlier decline.
Frequently Asked Questions
How big is the Canada toy market?
How did toys in Canada sell in 2025?
Which are the main Canadian toy companies?
What is the Canadian Toy Association?
How is the Canada baby toys category performing?
What is happening in the Canada smart toys category?
Where do people buy toys in Canada online and in stores?
Which region leads the Canada toy market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Building & Construction Sets
- 1.2.2 Plush, Arts & Other Toys
- 1.2.3 Games & Puzzles
- 1.2.4 Vehicles & Action Figures
- 1.2.5 Outdoor & Sports Toys
- 1.2.6 Infant & Preschool Toys
- 1.2.7 Dolls
- 1.3 By Age Group
- 1.3.1 5 to Below 12 Years
- 1.3.2 18+ Years
- 1.3.3 3 to Below 5 Years
- 1.3.4 0 to Below 3 Years
- 1.3.5 12 to 18 Years
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 2.78 billion → 2035: USD 3.94 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Canada Toy Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Canada Toy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Canada Toy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Canada Toy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Canada Toy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Canada Toy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Canada Toy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Canada Toy Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 2.78 billion → 2035: USD 3.94 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Canada Toy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Building & Construction Sets
- 12.3.7.2 Plush, Arts & Other Toys
- 12.3.7.3 Games & Puzzles
- 12.3.7.4 Vehicles & Action Figures
- 12.3.7.5 Outdoor & Sports Toys
- 12.3.7.6 Infant & Preschool Toys
- 12.3.7.7 Dolls
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Age Group - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 5 to Below 12 Years
- 12.4.7.2 18+ Years
- 12.4.7.3 3 to Below 5 Years
- 12.4.7.4 0 to Below 3 Years
- 12.4.7.5 12 to 18 Years
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Canada Toy Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Canada Toy Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Canada Toy Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Spin Master
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Mattel
- 17.4 LEGO Group
- 17.5 Ravensburger
- 17.6 ZURU
- 17.7 Moose Toys
- 17.8 TOMY International
- 17.9 Kroeger Marketing
- 17.10 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

