
Market Overview
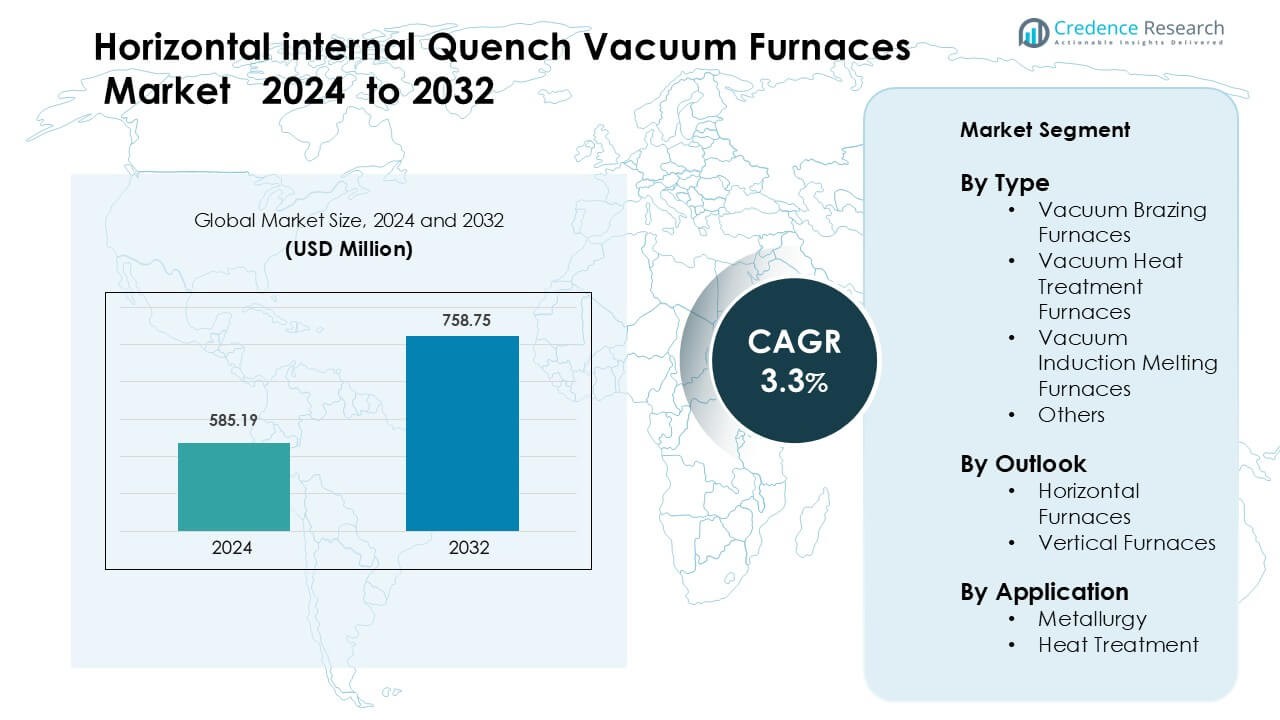
Horizontal internal Quench Vacuum Furnaces Market was valued at USD 585.19 million in 2024 and is anticipated to reach USD 758.75 million by 2032, growing at a CAGR of 3.3 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Horizontal internal Quench Vacuum Furnaces Market Size 2024 | USD 585.19 Million |
| Horizontal internal Quench Vacuum Furnaces Market, CAGR | 3.3% |
| Horizontal internal Quench Vacuum Furnaces Market Size 2032 | USD 758.75 Million |
The Horizontal Internal Quench Vacuum Furnaces Market is shaped by key players such as Centorr Vacuum Industries, Shanghai Gehang Vacuum Technology Co., Ltd, IVA SCHMETZ GmbH, Ipsen, T-M Vacuum Products, Inc, ALD Vacuum Technologies, Thermal Technology, ECM Technologies, Camco Furnace, and SECO/WARWICK, INC. These companies compete by offering advanced quench uniformity, automated controls, and high-precision processing for aerospace, automotive, and tooling applications. Product portfolios focus on distortion-free heat treatment, high repeatability, and cleaner processing for complex alloys. North America leads the market with about 38% share, supported by strong aerospace production, modernized heat-treatment facilities, and high adoption of digital furnace technology.
Market Insights
- Horizontal internal Quench Vacuum Furnaces Market was valued at USD 585.19 million in 2024 and is anticipated to reach USD 758.75 million by 2032, growing at a CAGR of 3.3 % during the forecast period.
- Rising demand for distortion-free heat treatment in aerospace, automotive, and tooling drives adoption, with heat-treatment applications holding nearly 58% share due to strict tolerance and cleanliness needs.
- Automation, predictive-maintenance software, and digitally controlled quenching shape key trends as manufacturers shift toward Industry 4.0–enabled furnace systems.
- Competition intensifies among Centorr Vacuum Industries, Ipsen, ALD Vacuum Technologies, ECM Technologies, and others as they expand product reliability, quench uniformity, and energy-efficient furnace designs.
- North America leads with 38% share, followed by Europe at 29%, while Asia-Pacific grows fastest. Vacuum heat-treatment furnace types dominate the type segment with 54% share, supported by high-precision alloy processing.
Market Segmentation Analysis:
By Type
Vacuum heat treatment furnaces lead this segment with about 54% share in 2024. These systems gain strong demand due to precise temperature control, uniform quenching, and suitability for high-strength alloy processing. Manufacturers in aerospace and automotive sectors rely on these furnaces to improve hardness, fatigue resistance, and microstructural stability in critical components. Vacuum brazing furnaces follow because of rising use in compact heat exchangers and turbine assemblies, while vacuum induction melting furnaces support controlled alloy production. Other types hold a smaller share and serve niche thermal-processing needs.
- For instance, Carbolite Gero offers vacuum chamber furnaces (used in brazing) with hot zones that can reach up to 3,000 °C, allowing extremely clean and precise brazed joints for critical aerospace heat exchanger components.
By Outlook
Horizontal furnaces dominate the outlook segment with nearly 63% share in 2024. Users prefer the horizontal layout because loading is simpler, cycle uniformity is higher, and maintenance access is easier for heavy industrial components. The design supports large parts such as shafts, gears, and structural fittings, which strengthens adoption in high-volume facilities. Vertical furnaces grow steadily due to their space-saving footprint and suitability for long components, but horizontal systems remain the preferred choice for precision heat treatment across regulated industries.
- For instance, Solar Manufacturing’s HCB-84144-2EQ horizontal car bottom vacuum furnace has a work zone of 54″ × 54″ × 144″ and can carry up to 50,000 lb of load, enabling treatment of very large industrial shafts and forgings.
By Application
Heat treatment leads this segment with around 58% share in 2024. The process benefits from horizontal internal quench vacuum furnaces because these systems deliver consistent hardening, reduced distortion, and clean processing for alloy steels and superalloys. Demand rises from aerospace, tool manufacturing, and automotive suppliers seeking improved fatigue life and dimensional accuracy. Metallurgy follows with applications in alloy refining and microstructure control. Growth continues as industries push for higher component strength, tighter tolerances, and contamination-free processing conditions.
Key Growth Drivers
Growing Use of Clean and Distortion-Free Heat Treatment
Demand rises as manufacturers require clean, oxide-free surfaces and low-distortion processing for high-precision metal components. Horizontal internal quench vacuum furnaces support these needs through controlled heating, rapid quenching, and contamination-free environments that maintain part geometry. Aerospace, automotive, toolmaking, and energy sectors adopt these systems to enhance fatigue strength and dimensional stability in gears, shafts, turbine parts, and cutting tools. The shift toward tighter tolerance standards strengthens reliance on vacuum technology over conventional furnaces. Companies upgrade to improve part quality, meet global standards, and support production of lightweight, high-performance alloys used in advanced engineering applications.
- For instance, Ipsen’s VFS HIQ (Horizontal Internal Quench) vacuum furnace offers quench pressures up to 12 bar, enabling very fast, uniform cooling without oxidation ideal for aerospace turbine components.
Rising Demand from Aerospace and Automotive Manufacturing
Aerospace and automotive suppliers drive strong adoption due to the need for high-strength, heat-treated components capable of operating under extreme loads. These industries rely on vacuum furnaces for critical parts such as turbine blades, structural fasteners, injection components, and transmission systems. Increased investment in electric vehicles and fuel-efficient aircraft also boosts demand for advanced alloys and precision thermal processing. Horizontal internal quench systems offer uniform quenching and repeatability, helping manufacturers meet strict certification and quality requirements. Growing production volumes and modernization of existing heat-treatment lines further reinforce market expansion across global manufacturing hubs.
- For instance, Ipsen shipped a TurboTreater horizontal vacuum furnace with a 36″ × 36″ × 48″ (914 mm × 914 mm × 1,219 mm) work‑zone and a load capacity of 3,000 lb (1,361 kg) to process aerospace fasteners; the furnace meets Nadcap and AMS 2750E thermal‑profile requirements.
Expansion of Advanced Material and Alloy Production
The rise of superalloys, specialty steels, and high-performance metal composites supports wider use of vacuum furnaces due to their need for precise, contamination-free thermal cycles. Research labs and industrial producers use horizontal internal quench systems to achieve controlled microstructure development and enhanced mechanical properties. Growth in renewable energy, defense, medical implants, and electronics intensifies the need for materials with superior strength, wear resistance, and thermal stability. The furnace design enables high consistency for both R&D and large-scale manufacturing. As industries shift toward high-value materials, demand strengthens for advanced thermal-processing infrastructure that supports innovation and metal performance upgrades.
Key Trends and Opportunities
Shift Toward Automation and Digital Process Control
Manufacturers adopt automation, sensors, and digital controllers to achieve consistent thermal cycles, reduce errors, and support real-time monitoring. Horizontal internal quench vacuum furnaces increasingly integrate predictive-maintenance software and data-logging tools that improve quality tracking and operational efficiency. Smart automation reduces labor requirements and ensures repeatability for complex aerospace and automotive parts. The trend aligns with Industry 4.0, where AI-assisted temperature profiling and load management improve throughput. As energy costs rise, automated systems also help optimize heating efficiency. This digital transition strengthens furnace reliability while enabling factories to meet global quality and traceability standards.
- For instance, the TITAN H6 model (horizontal) has a work-zone of 915 mm × 1,220 mm × 915 mm, supports quench pressures up to 2 bar, and integrates a high-definition touchscreen control system for precise process logging.
Growing Adoption in Emerging Manufacturing Regions
Asia-Pacific, Eastern Europe, and Latin America see rising investment in precision engineering, automotive plants, aerospace component manufacturing, and tooling industries. These regions expand their heat-treatment capacities due to growing exports, industrialization, and establishment of new metal-processing clusters. Horizontal internal quench vacuum furnaces offer a critical upgrade for companies shifting from conventional furnaces to advanced vacuum systems. Lower labor costs and government support for industrial automation enhance adoption. As local suppliers scale operations, opportunities emerge for furnace manufacturers to provide customized systems that fit regional material standards and production volumes. This broadens long-term market penetration.
- For instance, SECO/WARWICK’s Chinese branch has ramped up its local production it now produces up to 8-10 vacuum furnaces annually in its 10,000 m² Tianjin facility, supporting the surge in demand in China.
Increasing Demand for Lightweight and High-Performance Parts
Industries adopt lightweight alloys to improve energy efficiency, reduce emissions, and increase mechanical performance. Horizontal internal quench vacuum furnaces support reliable heat treatment for aluminum, titanium, nickel-based alloys, and advanced steels. The opportunity grows as electric vehicles, aerospace platforms, wind-energy equipment, and medical devices require components with superior strength-to-weight ratios. Growth in 3D-printed metal parts also expands the need for precise post-processing. Vacuum furnaces help stabilize microstructures and achieve high repeatability for additive-manufactured parts. Rising research investment and product innovation create long-term demand for advanced heat-treatment solutions.
Key Challenges
High Capital Cost and Complex Installation Requirements
Horizontal internal quench vacuum furnaces require significant capital investment, which limits adoption among small and mid-sized manufacturers. Installation involves specialized infrastructure, including heavy-duty power lines, controlled gas systems, cooling units, and reinforced floor structures. These requirements increase total project cost and extend setup timelines. Companies also face expenses related to operator training, process optimization, calibration, and periodic certification. Budget constraints in emerging economies slow replacement of older furnace systems. High ownership costs remain a major barrier despite long-term operational advantages, creating hesitation among manufacturers planning facility upgrades or modernization.
Skilled Workforce Shortage and Operational Complexity
Operation of advanced vacuum furnaces requires trained technicians capable of managing temperature cycles, quench parameters, leak checks, and digital monitoring systems. Many regions lack a skilled workforce familiar with precision heat-treatment processes. Improper handling can lead to inconsistent results, part distortion, and safety risks. Manufacturers struggle to maintain continuous production due to limited technical expertise and high turnover among experienced operators. The complexity of horizontal internal quench systems increases reliance on automation and specialized training programs. Workforce shortages slow adoption and reduce efficiency in facilities transitioning from traditional thermal-processing methods to modern vacuum technologies.
Regional Analysis
North America
North America holds the largest share at about 38% in 2024, driven by strong adoption in aerospace, defense, and automotive manufacturing. The region benefits from strict heat-treatment standards that require distortion-free processing and uniform quenching, boosting demand for advanced horizontal internal quench vacuum furnaces. The U.S. leads production due to a dense base of aircraft engine suppliers, tool manufacturers, and precision-metal facilities. Investments in modernizing heat-treatment lines and expanding EV component production strengthen market growth. Canada follows with steady uptake in metallurgical R&D and specialty alloy processing, supporting long-term furnace installations.
Europe
Europe commands nearly 29% share in 2024, supported by strong industrial capabilities in Germany, France, Italy, and the U.K. Aerospace engine makers, automotive suppliers, and precision engineering firms rely on vacuum furnaces to enhance alloy performance and ensure regulatory compliance. The region sees high adoption due to strict quality norms for fatigue resistance and microstructure control. Growth continues as Europe expands electric mobility, renewable-energy systems, and high-value metal component manufacturing. Increased focus on energy-efficient furnace designs also supports equipment upgrades. Eastern Europe adds to demand through rising heat-treatment outsourcing and new metallurgical facilities.
Asia-Pacific
Asia-Pacific accounts for around 25% share in 2024 and shows the fastest growth due to industrial expansion in China, Japan, South Korea, and India. Rising production of automotive parts, electronics, machinery, and aerospace components fuels furnace adoption across manufacturing hubs. China leads with large-scale metal processing and rapid investment in advanced material technologies. Japan and South Korea support demand through precision engineering and high-strength alloy development. India’s growing aerospace and automotive sectors also contribute to market expansion. Increasing adoption of distortion-free heat treatment and modernization of local heat-treatment facilities enhance regional growth potential.
Latin America
Latin America holds about 5% share in 2024, with gradual adoption driven by automotive parts manufacturing, mining equipment production, and industrial component processing in Brazil and Mexico. Growth remains steady as manufacturers upgrade from conventional furnaces to vacuum-based systems to improve component cleanliness and dimensional accuracy. The region benefits from expanding investment in metallurgical research and export-oriented manufacturing. Mexico’s close integration with North American supply chains supports higher adoption of advanced heat-treatment equipment. Although market size remains modest, rising industrial automation and new metalworking facilities create opportunities for future furnace installations.
Middle East & Africa
The Middle East & Africa region represents nearly 3% share in 2024, supported by increasing demand in energy, aerospace maintenance, and heavy industrial components. Countries such as the UAE and Saudi Arabia invest in advanced manufacturing as part of industrial diversification plans, driving uptake of vacuum furnaces for high-reliability metal parts. South Africa contributes through mining equipment and metallurgical processing. Adoption continues to rise as industries shift toward precision machining and cleaner heat-treatment practices. Despite slower growth than other regions, targeted investments in high-performance components strengthen long-term market potential.
Market Segmentations:
By Type
- Vacuum Brazing Furnaces
- Vacuum Heat Treatment Furnaces
- Vacuum Induction Melting Furnaces
- Others
By Outlook
- Horizontal Furnaces
- Vertical Furnaces
By Application
- Metallurgy
- Heat Treatment
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Horizontal Internal Quench Vacuum Furnaces Market features strong participation from leading furnace manufacturers such as Centorr Vacuum Industries, Shanghai Gehang Vacuum Technology Co., Ltd, IVA SCHMETZ GmbH, Ipsen, T-M Vacuum Products, Inc, ALD Vacuum Technologies, Thermal Technology, ECM Technologies, Camco Furnace, and SECO/WARWICK, INC. These companies compete by enhancing quench uniformity, improving energy efficiency, and integrating advanced automation and digital controls. Key players focus on aerospace, automotive, tooling, and specialty alloy applications where precision heat treatment and distortion-free processing remain essential. Many manufacturers expand portfolios with customizable chamber sizes, faster cooling systems, and predictive-maintenance software to meet global quality standards. Strategic collaborations, new product launches, and service-based maintenance programs strengthen market presence. Companies also invest in R&D to support advanced alloys and additive manufacturing post-processing, which increases furnace demand. As industries modernize heat-treatment operations, competition intensifies around reliability, repeatability, and long-term operating efficiency.
Key Player Analysis
- Centorr Vacuum Industries
- Shanghai Gehang Vacuum Technology Co., Ltd
- IVA SCHMETZ GmbH
- Ipsen
- T-M Vacuum Products, Inc
- ALD Vacuum Technologies
- Thermal Technology
- ECM Technologies
- Camco Furnace
- SECO/WARWICK, INC
Recent Developments
- In November 2024, Ipsen announced modernization of its VHFC high-vacuum furnaces for Siemens AG and the delivery of three new VHFC high-vacuum brazing systems to Siemens plants in Goa (India) and Wuxi (China). These systems support energy-infrastructure components such as vacuum interrupters and reflect broader investment in high-vacuum and internal-quench-type furnace technology used in grid and power equipment supply chains.
- In 2024, Shanghai Gehang Vacuum Technology appeared as a vacuum-equipment exhibitor at the Heat Treatment 2024 international specialized exhibition, highlighting its vacuum furnace and quenching portfolio to Eurasian customers. Participation in this dedicated heat-treatment show supports brand visibility in horizontal and internal-quench vacuum furnace projects across automotive and general engineering markets.
Report Coverage
The research report offers an in-depth analysis based on Type, Outlook, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise as industries seek cleaner and distortion-free heat-treatment processes.
- Aerospace and automotive production growth will support wider furnace adoption.
- Advanced alloys and superalloys will increase the need for precise thermal-processing systems.
- Digital controls and automation will become standard across new furnace installations.
- Predictive maintenance tools will improve uptime and reduce operational failures.
- Energy-efficient furnace designs will gain preference due to tightening sustainability norms.
- Asia-Pacific will expand its share as manufacturing investments increase.
- Additive manufacturing growth will drive demand for accurate post-processing heat treatment.
- Customizable furnace designs will help meet diverse part sizes and performance needs.
- Long-term upgrades in global heat-treatment facilities will strengthen replacement demand.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Use of Clean and Distortion-Free Heat Treatment
Manufacturers in aerospace, automotive, and tooling industries increasingly require clean, oxide-free surfaces and low-distortion processing for high-precision metal components. Horizontal internal quench vacuum furnaces provide controlled heating and rapid quenching in contamination-free environments, supporting the production of high-quality, dimensionally stable parts.
Rising Demand from Aerospace and Automotive Manufacturing
The need for high-strength, heat-treated components in aerospace and automotive sectors is driving adoption of these furnaces. Their ability to deliver uniform quenching and repeatability helps manufacturers meet strict certification and quality requirements for critical parts such as turbine blades and transmission systems.
Expansion of Advanced Material and Alloy Production
The growth of superalloys, specialty steels, and high-performance composites requires precise, contamination-free thermal cycles. Horizontal internal quench vacuum furnaces enable controlled microstructure development and enhanced mechanical properties, supporting innovation in industries like renewable energy, defense, and medical devices.
Shift Toward Automation and Digital Process Control
Manufacturers are integrating automation, sensors, and digital controllers into furnace systems to achieve consistent thermal cycles, reduce errors, and enable real-time monitoring. This trend improves operational efficiency, supports predictive maintenance, and aligns with Industry 4.0 initiatives, making advanced furnaces more attractive for modern production lines.
Increasing Demand for Lightweight and High-Performance Parts
Industries such as electric vehicles, aerospace, and medical devices are adopting lightweight alloys to improve energy efficiency and mechanical performance. Horizontal internal quench vacuum furnaces are essential for reliable heat treatment of these advanced materials, supporting the trend toward lightweight, high-strength components.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Horizontal Internal Quench Vacuum Furnaces Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Horizontal Internal Quench Vacuum Furnaces Market projected to grow between 2025 and 2032?
Which Horizontal Internal Quench Vacuum Furnaces Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Horizontal Internal Quench Vacuum Furnaces Market?
Who are the leading companies in the Horizontal Internal Quench Vacuum Furnaces Market?
Which region commanded the largest share of the Horizontal Internal Quench Vacuum Furnaces Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Vacuum Brazing Furnaces
- 1.2.2 Vacuum Heat Treatment Furnaces
- 1.2.3 Vacuum Induction Melting Furnaces
- 1.2.4 Others
- 1.3 By Outlook
- 1.3.1 Horizontal Furnaces
- 1.3.2 Vertical Furnaces
- 1.4 By Application
- 1.4.1 Metallurgy
- 1.4.2 Heat Treatment
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 585.19 million → 2032: USD 758.75 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Horizontal Internal Quench Vacuum Furnaces Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Horizontal Internal Quench Vacuum Furnaces Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Horizontal Internal Quench Vacuum Furnaces Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Horizontal Internal Quench Vacuum Furnaces Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Horizontal Internal Quench Vacuum Furnaces Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Horizontal Internal Quench Vacuum Furnaces Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Horizontal Internal Quench Vacuum Furnaces Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Horizontal Internal Quench Vacuum Furnaces Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 585.19 million → 2032: USD 758.75 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Horizontal Internal Quench Vacuum Furnaces Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Vacuum Brazing Furnaces
- 12.3.7.2 Vacuum Heat Treatment Furnaces
- 12.3.7.3 Vacuum Induction Melting Furnaces
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Outlook - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Horizontal Furnaces
- 12.4.7.2 Vertical Furnaces
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Metallurgy
- 12.5.7.2 Heat Treatment
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Horizontal Internal Quench Vacuum Furnaces End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Horizontal Internal Quench Vacuum Furnaces Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Horizontal Internal Quench Vacuum Furnaces Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Horizontal Internal Quench Vacuum Furnaces Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Centorr Vacuum Industries
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Shanghai Gehang Vacuum Technology Co., Ltd
- 18.4 IVA SCHMETZ GmbH
- 18.5 Ipsen
- 18.6 T-M Vacuum Products, Inc
- 18.7 ALD Vacuum Technologies
- 18.8 Thermal Technology
- 18.9 ECM Technologies
- 18.10 Camco Furnace
- 18.11 SECO/WARWICK, INC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

