
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Suppliers Market Size 2024 | USD900,050 million |
| Automotive Suppliers Market, CAGR | 3.66% |
| Automotive Suppliers Market Size 2032 | USD1,199,931 million |
Market Overview
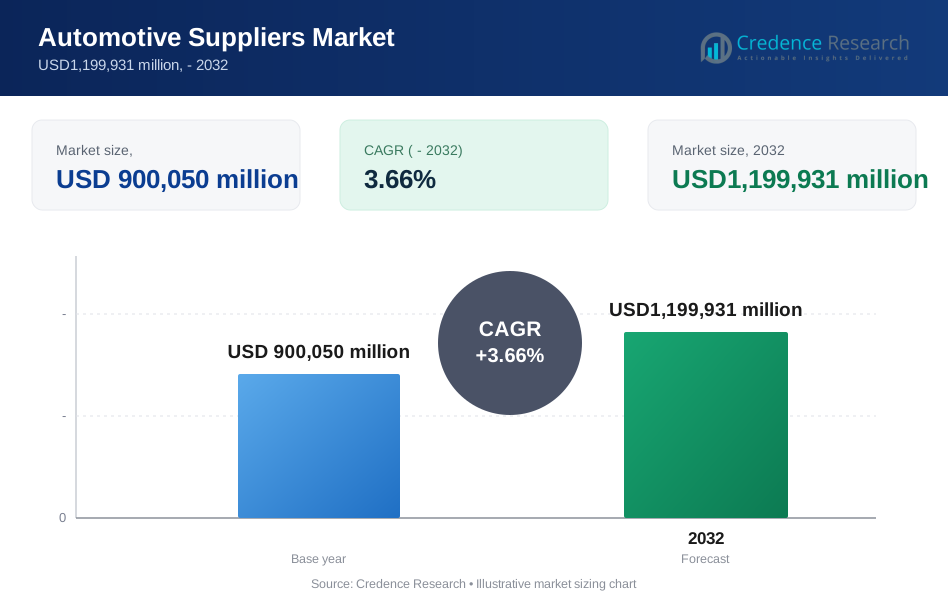
The Global Automotive Suppliers Market is projected to grow from USD900,050 million in 2024 to an estimated USD1,199,931 million by 2032, with a compound annual growth rate (CAGR) of 3.66% from 2025 to 2032.
The market is primarily driven by the global shift toward vehicle electrification, stricter emission regulations, and increasing demand for advanced driver-assistance systems (ADAS). Suppliers are accelerating innovation in powertrain electrification, battery modules, thermal management, and smart mobility solutions to meet OEM requirements and regulatory mandates. A key trend shaping the market is the integration of digital supply chain solutions and automation to improve production efficiency and responsiveness. Additionally, rising investments in sustainable manufacturing and circular economy practices are enhancing the competitive positioning of top-tier suppliers.
Geographically, Asia Pacific dominates the market due to its large automotive production base, rapid electrification in China, and strong presence of key component manufacturers. North America and Europe follow, driven by innovation in EV and ADAS technologies. Prominent players in the global automotive suppliers market include Robert Bosch GmbH, Continental AG, DENSO Corporation, Magna International, ZF Friedrichshafen AG, Aptiv PLC, and Valeo SA.
Market Insights
- The Global Automotive Suppliers Market is projected to grow from USD900,050 million in 2024 to USD1,199,931 million by 2032, registering a CAGR of 3.66% from 2025 to 2032.
- The market shows steady growth driven by OEM reliance on specialized suppliers for electrification, safety, and connectivity components.
- The rising adoption of electric vehicles fuels demand for advanced powertrain components, battery systems, and lightweight materials.
- Stricter emission norms and growing implementation of ADAS technologies are key factors accelerating innovation among suppliers.
- Significant investment is required to meet evolving OEM expectations, posing entry barriers for smaller suppliers and increasing consolidation.
- Asia Pacific dominates the market with a 42% share in 2024, supported by strong production bases in China, Japan, and South Korea.
- These regions contribute over 40% combined, focusing on EV technology, autonomous systems, and sustainability-led automotive innovations.
Market Drivers
Transition to Electrification and Powertrain Innovation Fuels Component Demand
The growing shift from internal combustion engines to electric vehicles is a major force driving the Global Automotive Suppliers Market. OEMs are outsourcing the development of electric drivetrains, battery management systems, and charging infrastructure components to specialized suppliers. It encourages high-value collaborations and long-term supply agreements that improve revenue visibility for key vendors. The demand for efficient, compact, and lightweight electrical components continues to rise with expanding EV production. Suppliers are investing in advanced battery modules, thermal management systems, and e-axles to secure strategic positioning. It strengthens the value chain and fosters technical specialization across multiple regions.
- For instance, government incentives and subsidies for EV adoption have significantly boosted investments in powertrain technologies, with countries like Norway, Germany, and China leading the charge.
Stringent Emission Norms Accelerate Technological Upgrades
Tightening global emission regulations are compelling automotive manufacturers to source more sustainable and compliant components. Suppliers are under increasing pressure to deliver low-emission technologies such as start-stop systems, hybrid modules, and exhaust gas after-treatment solutions. The market benefits from investments in eco-friendly materials and advanced fuel efficiency systems. It propels demand for lightweight alloys, carbon fiber composites, and emission-reducing sensors. Governments across key automotive markets are enforcing stricter carbon reduction targets, influencing supplier R\&D and procurement strategies. The Global Automotive Suppliers Market aligns itself with regulatory trends to maintain competitiveness.
- For instance, the North American automotive exhaust aftertreatment systems market has seen rapid expansion due to stringent emission regulations, particularly in the U.S. and Canada.
Rising Demand for Advanced Safety and Connectivity Solutions
Consumer demand for safer and smarter vehicles is driving the integration of advanced driver-assistance systems (ADAS) and connected technologies. Suppliers are developing radar modules, lidar sensors, ECU hardware, and V2X communication systems to meet OEM requirements. It boosts the importance of electronics and software capabilities within the traditional mechanical supply landscape. Investments in cybersecurity and over-the-air update technologies are growing. The surge in autonomous driving initiatives further accelerates innovation in sensor fusion and control units. The market rewards suppliers that demonstrate agility in integrating digital technologies.
Digital Transformation and Smart Manufacturing Boost Efficiency
Automotive suppliers are embracing Industry 4.0 tools to optimize production efficiency and ensure quality consistency. Automation, AI-based defect detection, and predictive maintenance are becoming standard across modern manufacturing facilities. It helps reduce operational costs and enhances scalability amid fluctuating global demand. Suppliers are deploying digital twins, IoT-enabled equipment, and real-time data analytics to improve throughput and flexibility. These advancements support faster response times to OEM customization needs and regulatory updates. The Global Automotive Suppliers Market benefits from digital transformation as it raises transparency, accelerates innovation cycles, and supports global expansion.
Market Trends
Increased Focus on Software-Defined Vehicle Components
The Global Automotive Suppliers Market is witnessing a major shift toward software-defined vehicles, transforming the traditional component landscape. Suppliers are now integrating embedded software into control units, sensors, and vehicle platforms to support advanced functionalities. It reflects a growing need for over-the-air updates, digital cockpit features, and vehicle personalization. The boundary between mechanical and digital systems continues to blur, pushing suppliers to expand software development capabilities. Strategic partnerships with tech firms and cloud providers are enabling this transition. The trend demands significant investment in cybersecurity, real-time computing, and software lifecycle management.
- For instance, in 2023, Bosch invested USD 3,400 million into software and electronics R&D for connected vehicle solutions, including embedded control systems and software-defined platforms.
Expansion of Supply Chain Localization and Regionalization
Geopolitical instability and supply chain disruptions are encouraging suppliers to localize manufacturing and diversify sourcing strategies. Companies are expanding operations closer to OEM assembly plants to minimize lead times and reduce logistical risks. It enables faster delivery, better inventory control, and stronger compliance with regional trade regulations. The trend is especially visible in North America and Europe, where policy incentives favor domestic production. Suppliers are redesigning their global footprint to increase resilience and agility. The Global Automotive Suppliers Market benefits from this approach by strengthening its value chain across major automotive hubs.
- For instance, in 2022, Magna International announced a USD 500 million investment to open four new facilities in the U.S. and Mexico to support localized production and just-in-time delivery for key OEMs.
Sustainability and Circular Economy Strategies Gain Momentum
Sustainability initiatives are shaping how suppliers design, source, and manufacture automotive components. Demand is rising for recycled materials, energy-efficient production methods, and low-carbon processes. Suppliers are embedding lifecycle analysis into their product development to align with OEM sustainability goals. It drives innovation in green materials, such as bio-based plastics and recycled aluminum alloys. Regulatory pressure and consumer preference for environmentally responsible vehicles further reinforce this trend. The Global Automotive Suppliers Market is adapting by incorporating circular economy principles into procurement and product strategies.
Consolidation and Strategic Alliances to Drive Innovation
The growing complexity of vehicle platforms is accelerating mergers, acquisitions, and joint ventures within the supplier ecosystem. Companies are joining forces to gain scale, share R\&D costs, and access emerging technologies. It supports the development of integrated solutions for electrification, automation, and connectivity. Large Tier 1 suppliers are acquiring niche firms with specialized capabilities in semiconductors, software, and sensors. These alliances enhance competitiveness and reduce time-to-market for new technologies. The Global Automotive Suppliers Market is evolving into a more collaborative environment that encourages innovation through shared expertise.
Market Challenges
Volatility in Raw Material Prices and Supply Chain Disruptions
Fluctuating prices of raw materials such as steel, aluminum, semiconductors, and rare earth elements create cost pressures for suppliers. It disrupts procurement planning and reduces profit margins, especially for firms locked into long-term supply contracts. Global supply chain disruptions caused by geopolitical conflicts, natural disasters, and port congestions compound these challenges. Suppliers face delays in component delivery, affecting their ability to meet OEM production schedules. It forces many to invest in buffer inventories and dual-sourcing strategies, increasing operational complexity. The Global Automotive Suppliers Market must build greater resilience to absorb these shocks and ensure consistent delivery.
- For instance, global vehicle production faced an overcapacity of 111 million units between 2020 and 2030, highlighting the industry's struggle with supply-demand imbalances
Technological Shifts Outpacing Supplier Capabilities
Rapid advancements in electrification, autonomous systems, and digital integration present challenges for traditional suppliers. Many lack the internal expertise or capital to adapt their portfolios to align with these new technologies. It creates a widening gap between legacy component makers and tech-savvy entrants. The need to upgrade infrastructure, retrain the workforce, and comply with emerging standards puts pressure on small and mid-sized players. Partnerships and innovation ecosystems offer partial relief but demand strategic agility and long-term vision. The Global Automotive Suppliers Market must address these capability gaps to stay relevant in a fast-changing environment.
Market Opportunities
Growing Demand for Electric and Autonomous Vehicle Components
The shift toward electric and autonomous vehicles creates substantial opportunities for suppliers to expand into high-value, technology-driven segments. Demand is rising for battery systems, thermal management solutions, power electronics, and advanced sensor technologies. Suppliers that invest in R\&D and form strategic alliances with OEMs can capture significant market share in these emerging areas. It encourages the development of modular, scalable platforms that support multiple vehicle architectures. The Global Automotive Suppliers Market stands to benefit from the accelerating adoption of EVs and autonomous systems across global regions. Companies that align with next-generation mobility trends can secure long-term growth.
Expansion into Software and Digital Service Integration
The increasing digitalization of vehicles opens new revenue streams for suppliers specializing in software, data analytics, and connectivity solutions. Suppliers can develop embedded software, telematics systems, and cybersecurity frameworks to support OEMs’ evolving digital ecosystems. It creates cross-industry collaboration opportunities with cloud providers, semiconductor firms, and mobility service platforms. The ability to deliver integrated hardware-software solutions enhances supplier value and strengthens customer retention. The Global Automotive Suppliers Market can leverage these opportunities to move beyond traditional components and into long-term service-oriented models. This shift supports recurring revenue and deeper integration within OEM product lifecycles.
Market Segmentation Analysis
By Product Type
The Global Automotive Suppliers Market segments by product type into powertrain components, chassis systems, interior components, exterior components, electrical and electronic components, and safety systems. Powertrain components hold a significant share due to their essential role in both conventional and electric vehicles. Electrical and electronic components are growing rapidly with rising demand for connectivity, infotainment, and driver-assistance systems. Safety systems such as airbags, sensors, and braking modules remain a focus area due to regulatory mandates. Interior and exterior components see steady demand aligned with design upgrades and consumer comfort expectations. Chassis systems continue to evolve with lightweight materials and modular designs.
By Vehicle Type
The market segments by vehicle type into passenger cars, commercial vehicles, and others. Passenger cars represent the dominant segment due to high production volumes and consumer demand for technologically advanced features. Commercial vehicles also contribute significantly, driven by logistics, infrastructure development, and fleet modernization. The “others” category includes specialty and off-road vehicles, which offer niche growth potential for suppliers focusing on rugged and performance components.
By Sales Channel
Sales channel segmentation includes OEM market, aftermarket, and retail. OEMs lead the segment, with suppliers deeply integrated into global manufacturing supply chains. The aftermarket is expanding due to increased vehicle parc and consumer demand for cost-effective repair and replacement parts. Retail channels support smaller-scale distribution, especiallyfor DIY maintenance and regional markets
By Propulsion
By propulsion, the market covers IC engine, electric vehicles, and hybrid vehicles. While IC engine vehicles still command a major share, electric vehicles are witnessing the fastest growth. Hybrid vehicles serve as a transitional segment, driving demand for dual-system components. The Global Automotive Suppliers Market is adapting to propulsion shifts by diversifying product lines and investing in electrification technologies.
Segments
Based on Product Type
- Powertrain Component
- Chassis Systems
- Interior Components
- Exterior Components
- Electrical and Electronic Components
- Safety Systems
Based on Vehicle Type
- Passenger Cars
- Commercial Vehicles
- Others
Based on Sales Channel
- OEM Market
- Aftermarket
- Retail
Based on Propulsion
- IC Engine
- Electric Vehicles
- Hybrid Vehicles
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
Asia Pacific Automotive Suppliers Market
Asia Pacific holds the largest share in the Global Automotive Suppliers Market, accounting for nearly 42% of the total market in 2024. The region benefits from its strong automotive manufacturing base, particularly in China, Japan, South Korea, and India. It supports high-volume production and export of components, driven by cost advantages, skilled labor, and government support. China dominates regional growth with a focus on electric vehicles and advanced electronics. Japan and South Korea contribute through innovation in safety systems, powertrains, and electronics. Suppliers across the region are expanding capabilities in software integration and digital platforms to meet evolving OEM demands.
North America Automotive Suppliers Market
North America represents approximately 23% of the Global Automotive Suppliers Market in 2024, driven by technological advancements and a mature automotive ecosystem. The U.S. leads the region with significant investment in electric vehicle development, autonomous systems, and connected car infrastructure. It maintains strong supplier-OEM collaboration, particularly in Michigan and other automotive hubs. Canada and Mexico contribute through manufacturing specialization and supply chain integration. The region supports high-value components such as ADAS modules, electric drivetrains, and cybersecurity systems. Suppliers are aligning with federal incentives and sustainability regulations to enhance competitive advantage.
Europe Automotive Suppliers Market
Europe holds around 21% market share and stands out for its focus on sustainability, innovation, and high-end automotive engineering. Germany, France, and Italy drive the region’s supplier strength through a network of Tier 1 and Tier 2 manufacturers. The European market emphasizes decarbonization, electric mobility, and safety compliance, creating strong demand for advanced components. It supports leading OEMs with precision-engineered systems and regulatory-aligned solutions. Suppliers in the region are investing in lightweight materials and battery technologies. The Automotive Suppliers Market in Europe is shifting toward circular production models and digital supply chains.
Middle East & Africa Automotive Suppliers Market
The Middle East & Africa region holds a modest share of nearly 6% in the Global Automotive Suppliers Market. It is gaining traction with rising vehicle demand in urban centers and increased focus on local assembly operations. Gulf countries are investing in mobility infrastructure and electric vehicle adoption, supporting supplier expansion. South Africa remains a key market for automotive exports and regional distribution. Suppliers target this region with cost-effective components and aftermarket products. It creates opportunities for scaling production and improving localization efforts in response to regional policy shifts.
Latin America Automotive Suppliers Market
Latin America contributes around 5% to the Global Automotive Suppliers Market, with Brazil and Mexico serving as key hubs. Mexico’s integration into North American supply chains supports OEM production and tiered supplier operations. Brazil continues to build a strong domestic market driven by its large vehicle fleet and OEM partnerships. The region shows growing interest in electrification and sustainability, though at a slower pace than developed markets. Suppliers are focusing on expanding their aftermarket presence and improving logistics capabilities. It presents moderate growth potential with evolving regulatory and economic environments.
Key players
- Aisin Seiki Co., Ltd.
- Continental AG
- Denso Corporation
- Faurecia S.A.
- Hyundai Mobis Co., Ltd.
- Lear Corporation
- Magna International Inc.
- Robert Bosch GmbH
- Valeo S.A.
- ZF Friedrichshafen AG
Competitive Analysis
The Global Automotive Suppliers Market is highly competitive, with established Tier 1 suppliers dominating across multiple component categories. Leading players such as Robert Bosch GmbH, Denso Corporation, and ZF Friedrichshafen AG maintain strong global footprints supported by integrated manufacturing, R\&D capabilities, and OEM partnerships. It drives competition through constant innovation in electrification, safety systems, and digital technologies. Companies like Continental AG and Magna International Inc. focus on autonomous driving and smart mobility solutions, expanding their role beyond traditional hardware. Strategic mergers, acquisitions, and joint ventures remain common, enabling suppliers to diversify offerings and access new markets. The market rewards agility, scale, and technological leadership, encouraging continuous investment in next-generation vehicle platforms.
Recent Developments
- In December 2024, Continental AG confirmed its decision to spin off the Automotive division, planning a listing on the Frankfurt Stock Exchange by end of 2025. This information was publicly disclosed by both WSJ and Continental’s official site.
- On April 11, 2025, General Motors presented Magna with a 2024 Supplier of the Year and Overdrive Award at GM's 33rd annual Supplier of the Year event in Phoenix, Arizona.
Market Concentration and Characteristics
The Global Automotive Suppliers Market exhibits moderate to high market concentration, with a few dominant Tier 1 companies holding significant global shares. It features a structured hierarchy of suppliers categorized into Tier 1, Tier 2, and Tier 3 levels based on their proximity to OEMs and technological capabilities. Leading players maintain long-term partnerships with major automakers, offering integrated systems and advanced modules across powertrain, safety, and electronics. The market is characterized by high capital intensity, strong R&D focus, and increasing reliance on software and digital solutions. It shows a trend toward consolidation, as large suppliers acquire niche firms to expand technology portfolios and geographical reach. Regulatory compliance, innovation speed, and operational scalability define competitive success in this environment.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Vehicle Type, Sales Channel, Propulsion and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Suppliers will prioritize electric drivetrain components, battery systems, and thermal management technologies as global EV adoption accelerates.
- Embedded software and over-the-air update capabilities will become core offerings, shifting value from hardware to integrated solutions.
- Increased demand for sensors, control units, and perception systems will elevate the importance of suppliers in autonomous vehicle development.
- OEMs will expect suppliers to implement green manufacturing, low-emission materials, and lifecycle carbon tracking as standard operations.
- Localization strategies will strengthen supplier bases in Asia Pacific, North America, and Eastern Europe, enhancing agility and risk mitigation.
- Suppliers will expand their presence in the aftermarket through digital platforms, predictive maintenance tools, and personalized component offerings.
- Collaborations with tech firms, startups, and OEMs will foster rapid development of connected mobility and AI-driven vehicle features.
- Suppliers will invest in Industry 4.0 technologies to enhance production visibility, reduce downtime, and optimize operational costs.
- Growing reliance on automotive-grade semiconductors will lead suppliers to form direct partnerships with chipmakers to secure supply stability.
- Market consolidation will continue as large players acquire smaller firms to diversify portfolios and scale capabilities across propulsion and digital systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Transition to Electrification and Powertrain Innovation
The shift from internal combustion engines to electric vehicles is driving demand for advanced powertrain components, battery modules, and thermal management systems. OEMs are increasingly outsourcing these technologies to specialized suppliers, fostering high-value collaborations and long-term supply agreements.
Stringent Emission Norms and Regulatory Compliance
Tightening global emission regulations are compelling automakers to source low-emission and sustainable components, accelerating supplier innovation in start-stop systems, hybrid modules, and emission-reducing technologies. This regulatory pressure is pushing suppliers to invest in eco-friendly materials and advanced fuel efficiency systems.
Growth in Advanced Safety and Connectivity Solutions
The rising integration of ADAS, radar, lidar, and V2X communication systems is increasing the importance of electronics and software capabilities among suppliers. Consumer demand for safer and smarter vehicles is driving suppliers to develop advanced sensors, control units, and cybersecurity solutions.
Digital Transformation and Smart Manufacturing
Suppliers are adopting Industry 4.0 tools, automation, and digital supply chain solutions to improve production efficiency, reduce operational costs, and enhance responsiveness to OEM customization needs. This digital transformation supports faster innovation cycles and global expansion.
Supply Chain Localization and Resilience
Geopolitical instability and recent supply chain disruptions are prompting suppliers to localize manufacturing and diversify sourcing strategies. This trend enables faster delivery, better inventory control, and compliance with regional trade regulations, strengthening the value chain and reducing risk.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the Global Automotive Suppliers Market in 2023, and what is the projected size by 2032 with CAGR?
What are the major factors driving growth in the automotive suppliers market?
Which regions are leading in the automotive suppliers market?
Who are the leading players in the global automotive suppliers market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Propulsion
- 1.2.1 IC Engine
- 1.2.2 Electric Vehicles
- 1.2.3 Hybrid Vehicles
- 1.3 By Product Type
- 1.3.1 Powertrain Components
- 1.3.2 Chassis Systems
- 1.3.3 Interior Components
- 1.3.4 Exterior Components
- 1.3.5 Electrical and Electronic Components
- 1.3.6 Safety Systems
- 1.4 By Vehicle Type
- 1.4.1 Passenger Cars
- 1.4.2 Commercial Vehicles
- 1.4.3 Others
- 1.5 By Sales Channel
- 1.5.1 OEM Market
- 1.5.2 Aftermarket
- 1.5.3 Retail
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 900,050 million → 2032: USD1,199,931 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Suppliers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Suppliers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Suppliers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Suppliers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Suppliers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Suppliers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Suppliers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Suppliers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 900,050 million → 2032: USD1,199,931 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Suppliers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Propulsion - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 IC Engine
- 12.3.7.2 Electric Vehicles
- 12.3.7.3 Hybrid Vehicles
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Powertrain Components
- 12.4.7.2 Chassis Systems
- 12.4.7.3 Interior Components
- 12.4.7.4 Exterior Components
- 12.4.7.5 Electrical and Electronic Components
- 12.4.7.6 Safety Systems
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Passenger Cars
- 12.5.7.2 Commercial Vehicles
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 OEM Market
- 12.6.7.2 Aftermarket
- 12.6.7.3 Retail
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Suppliers Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automotive Suppliers Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automotive Suppliers Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Robert Bosch GmbH
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Continental AG
- 17.4 DENSO Corporation
- 17.5 Magna International Inc.
- 17.6 ZF Friedrichshafen AG
- 17.7 Aptiv PLC
- 17.8 Valeo S.A.
- 17.9 Aisin Seiki Co., Ltd.
- 17.10 Faurecia S.A.
- 17.11 Lear Corporation
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

