
Hydraulic Hose Market Overview:
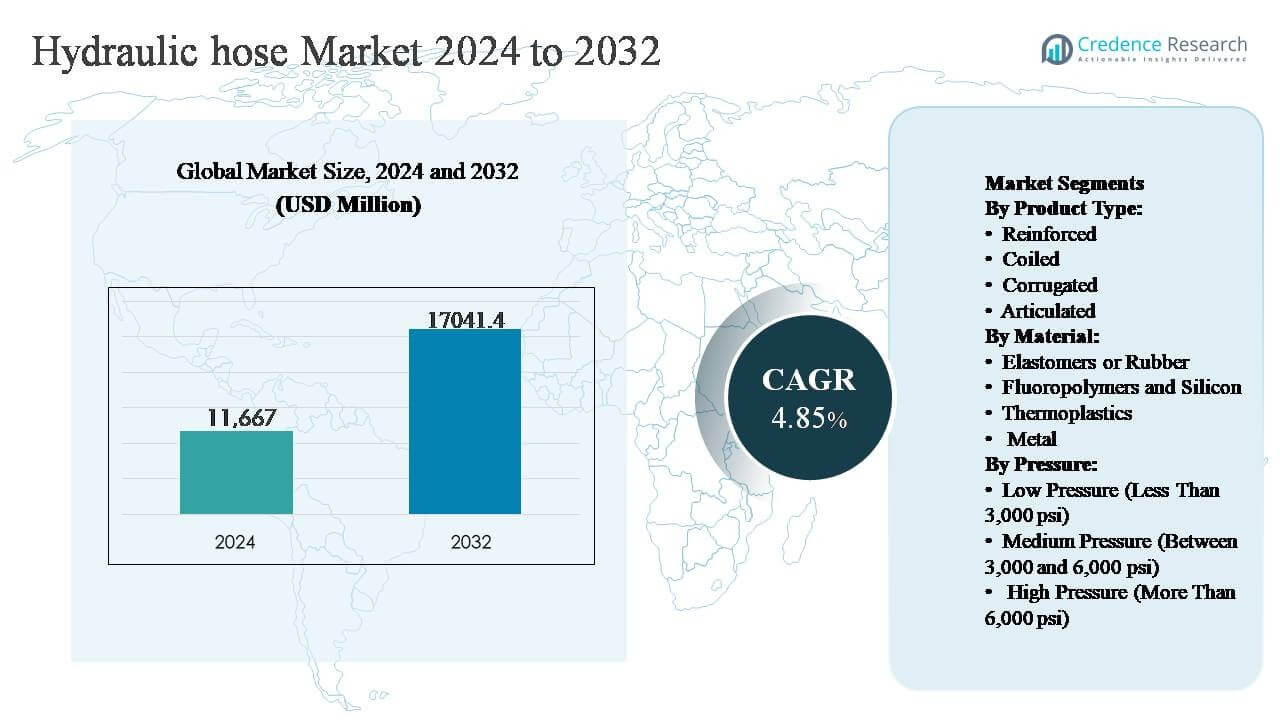
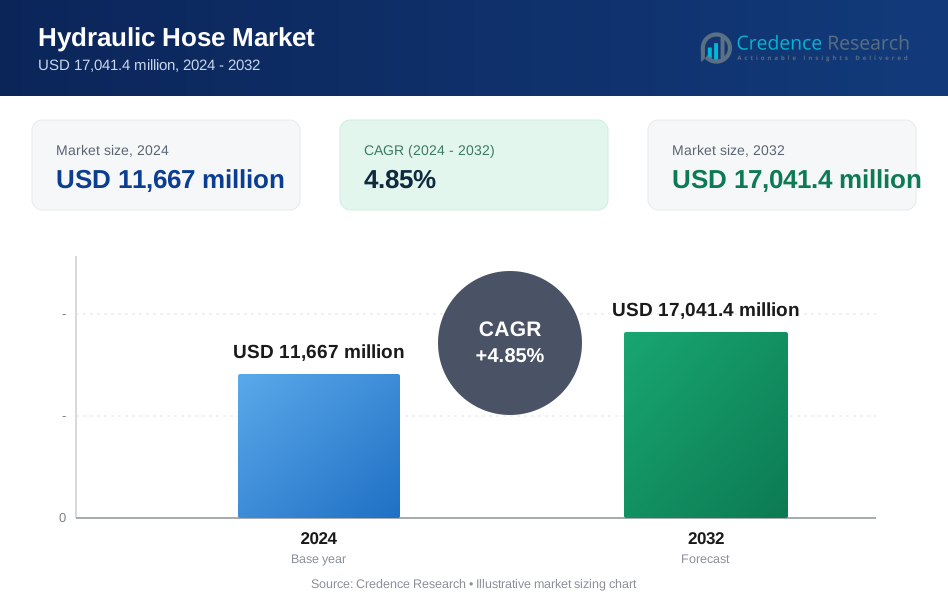
The global hydraulic hose market was valued at USD 11,667 million in 2024 and is projected to reach USD 17,041.4 million by 2032, expanding at a compound annual growth rate (CAGR) of 4.85% over the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hydraulic Hose Market Size 2024 | USD 11,667 million |
| Hydraulic Hose Market, CAGR | 4.85% |
| Hydraulic Hose Market Size 2032 | USD 17,041.4 million |
Hydraulic Hose Market Insights
- Market growth is primarily driven by rising demand from construction, agriculture, mining, and industrial machinery, where hydraulic systems remain essential for power transmission, along with strong replacement demand due to wear, safety compliance, and preventive maintenance practices.
- Key trends include increasing adoption of reinforced and medium-pressure hoses, which together account for the largest segment share, and growing use of advanced elastomer and thermoplastic materials to improve durability, flexibility, and operational efficiency.
- The competitive landscape is moderately consolidated, led by global players with extensive OEM partnerships and aftermarket networks, while regional manufacturers compete through cost efficiency, localized production, and faster service responsiveness.
- Regionally, Asia-Pacific dominates with about 34% market share, followed by North America at 28% and Europe at 24%, while Latin America and the Middle East & Africa collectively contribute the remaining share, supported by mining, energy, and infrastructure activity.
Hydraulic Hose Market Segmentation Analysis:
By Product Type:
By product type, reinforced hydraulic hoses represent the dominant sub-segment, accounting for the largest market share due to their superior pressure-handling capability, durability, and wide applicability across construction, mining, agriculture, and industrial machinery. Reinforced hoses, typically embedded with steel wire or textile braiding, are preferred for demanding hydraulic systems requiring reliability under continuous load cycles. Coiled hoses maintain relevance in compact equipment and mobile applications where flexibility and space efficiency are critical. Corrugated and articulated hoses serve niche applications involving vibration absorption, misalignment compensation, and specialized fluid transfer requirements.
- For instance, Parker Hannifin 451TC ToughCover™ reinforced hydraulic hose is that it is rated for a constant working pressure up to 3,000 psi and meets the SAE 100R17 specification, demonstrating reliability in heavy-duty mobile hydraulics.
By Material:
By material, elastomers or rubber-based hydraulic hoses dominate the market, driven by their excellent flexibility, abrasion resistance, cost-effectiveness, and compatibility with a broad range of hydraulic fluids. These hoses are extensively deployed in mobile and stationary hydraulic systems across multiple industries. Thermoplastic hoses are gaining traction due to their lightweight structure, chemical resistance, and suitability for medium- to high-pressure applications, particularly in automation and material handling. Fluoropolymers, silicon, and metal hoses remain specialized solutions, favored in extreme-temperature, corrosive, or hygienic environments requiring enhanced performance characteristics.
- For instance, Gates’ MegaSys® MXT™ rubber hydraulic hose is engineered for working pressures up to 6,000 psi and validated through impulse testing to 600,000 cycles-three times the industry standard to support long service life in severe-duty environments."
By Pressure:
By pressure rating, medium-pressure hydraulic hoses (3,000-6,000 psi) hold the dominant market share, supported by their extensive use in construction equipment, agricultural machinery, industrial presses, and manufacturing systems. This segment benefits from balanced performance, cost efficiency, and compatibility with standard hydraulic systems. Low-pressure hoses continue to serve fluid transfer, lubrication, and return-line applications where flexibility is prioritized over strength. High-pressure hoses, though smaller in share, are essential for heavy-duty mining, oil & gas, and advanced industrial equipment, where safety, reliability, and burst resistance are critical drivers.
Key Growth Drivers
Expansion of Construction, Mining, and Infrastructure Equipment
Rising global investment in infrastructure development and resource extraction is a primary driver for the hydraulic hose market. Construction machinery such as excavators, loaders, cranes, and concrete equipment relies extensively on hydraulic systems for power transmission and motion control, creating sustained demand for high-performance hoses. Mining operations further intensify usage due to harsh operating conditions that require abrasion-resistant and high-pressure hydraulic hoses. Large-scale transportation projects, urbanization initiatives, and energy infrastructure expansion continue to stimulate equipment deployment and replacement, directly supporting hose consumption. Additionally, aging machinery fleets across both developed and emerging economies are increasing maintenance and retrofit activity, reinforcing steady aftermarket demand for hydraulic hoses designed to withstand demanding operational cycles.
- For instance, Caterpillar’s Next Generation 336 hydraulic excavator integrates hydraulic circuits operating at system pressures exceeding 5,000 psi, requiring reinforced hose assemblies qualified for continuous-duty performance in earthmoving applications.
Growth in Agricultural Mechanization and Industrial Automation
Increasing mechanization in agriculture is significantly driving hydraulic hose demand, as modern tractors, harvesters, and irrigation systems rely on hydraulics for efficient operation. The shift toward higher productivity farming, labor optimization, and precision agriculture has expanded the installed base of hydraulic equipment, particularly in emerging markets. In parallel, industrial automation across manufacturing, material handling, and logistics sectors is boosting adoption of hydraulic systems for presses, injection molding machines, and automated production lines. These applications require reliable medium- and high-pressure hoses with long service life, positioning hydraulic hoses as critical components supporting industrial productivity and operational efficiency.
- For instance, John Deere’s 8R Series tractors are equipped with closed-center, pressure-and-flow-compensated hydraulic systems delivering flow rates up to 321 liters per minute at operating pressures of 225 bar, requiring reinforced hoses capable of sustaining continuous high-duty cycles during field operations.
Rising Replacement Demand and Equipment Lifecycle Management
The hydraulic hose market benefits strongly from recurring replacement demand driven by wear, fatigue, and safety compliance requirements. Hydraulic hoses operate under constant pressure fluctuations, temperature variations, and mechanical stress, necessitating periodic replacement to prevent system failures and downtime. Industries increasingly prioritize preventive maintenance and asset lifecycle management, accelerating replacement cycles for hoses in both mobile and stationary equipment. Regulatory focus on workplace safety and equipment reliability further reinforces timely hose replacement, particularly in high-risk environments such as mining, oil & gas, and heavy manufacturing. This replacement-driven demand provides stable revenue streams independent of new equipment sales.
Key Trends & Opportunities
Shift Toward Lightweight and High-Performance Materials
A key trend shaping the hydraulic hose market is the increasing adoption of lightweight, high-performance materials such as advanced elastomers and thermoplastics. Equipment manufacturers seek hoses that reduce overall system weight while maintaining pressure resistance and durability, particularly in mobile machinery and automation systems. Thermoplastic hoses offer improved chemical resistance, lower permeability, and easier recyclability, making them attractive alternatives to traditional rubber hoses in selected applications. This shift presents opportunities for manufacturers to differentiate products through material innovation, improved hose longevity, and enhanced performance in demanding environments.
- For instance, Eaton’s Synflex® 35FE thermoplastic hydraulic hose is engineered for operating pressures up to 4,000 psi while delivering a significantly lower mass per meter compared with conventional steel-reinforced rubber hoses, enabling easier routing in articulated machinery.
Growing Focus on Customization and Application-Specific Solutions
End users are increasingly demanding hydraulic hoses tailored to specific operating conditions, pressure requirements, and environmental constraints. This trend is driving opportunities for customized hose assemblies, specialized reinforcement designs, and application-specific coatings. OEM partnerships and value-added services such as hose routing optimization, condition monitoring, and pre-assembled hose kits are gaining importance. Suppliers that offer engineering support and application expertise are well-positioned to capture higher-margin opportunities, particularly in sectors such as construction, agriculture, and industrial automation where equipment diversity is high.
- For instance, As part of its Connected Hydraulics initiative, Bosch Rexroth’s CytroConnect platform utilizes intelligent sensors within units like the CytroBox to monitor operating pressures up to 315 bar (with individual sensors capable of 350 bar) and temperature in real time, enabling condition-based maintenance and predictive analytics in industrial automation systems."
Key Challenges
Volatility in Raw Material Prices
Fluctuations in the prices of raw materials such as rubber, synthetic polymers, steel wire, and specialty compounds pose a significant challenge for hydraulic hose manufacturers. Cost volatility impacts production planning, pricing strategies, and profit margins, especially in a market characterized by strong price competition. Sudden increases in material costs can limit manufacturers’ ability to pass through expenses to end users, particularly in long-term supply contracts. Managing supply chain risks, securing reliable sourcing, and maintaining cost efficiency remain critical challenges for sustaining profitability in the hydraulic hose market.
Operational Failures and Quality Compliance Risks
Hydraulic hose failures can result in equipment downtime, safety hazards, and environmental incidents, placing strong pressure on manufacturers to meet stringent quality and performance standards. Ensuring consistent hose quality across diverse operating conditions is technically demanding, particularly for high-pressure and extreme-environment applications. Compliance with regional safety regulations and industry standards adds complexity and cost to product development and testing. Manufacturers must continuously invest in quality control, testing infrastructure, and performance validation to mitigate failure risks, which can increase operational costs and lengthen product development cycles.
Regional Analysis
North America
North America accounts for approximately 28% of the global hydraulic hose market, supported by strong demand from construction, agriculture, mining, and oil & gas industries. The region benefits from a large installed base of heavy machinery and a mature aftermarket focused on preventive maintenance and replacement. High adoption of advanced hydraulic systems in industrial automation and material handling further supports demand. The United States dominates regional consumption due to ongoing infrastructure upgrades and sustained energy sector activity, while Canada contributes through mining and agricultural equipment demand. Emphasis on safety compliance and equipment reliability continues to drive steady hose replacement cycles.
Europe
Europe represents around 24% of the global hydraulic hose market, driven by well-established manufacturing, automotive, and industrial machinery sectors. Countries such as Germany, France, Italy, and the UK are key contributors due to their strong base of OEMs and industrial automation adoption. Strict safety standards and regulatory frameworks encourage the use of high-quality, certified hydraulic hoses, reinforcing replacement demand. Agricultural mechanization in Eastern Europe and ongoing infrastructure modernization further support market growth. The region also shows increasing preference for lightweight and energy-efficient hydraulic systems, influencing material innovation and product design within the hose market.
Asia-Pacific
Asia-Pacific holds the largest share of the hydraulic hose market at approximately 34%, driven by rapid industrialization, infrastructure expansion, and agricultural mechanization. China, India, Japan, and Southeast Asian countries contribute significantly due to large-scale construction projects, manufacturing growth, and rising equipment penetration. Expanding mining activities and increasing investments in transportation and urban infrastructure further stimulate demand. The region also benefits from cost-competitive manufacturing and a growing base of local equipment producers. High equipment utilization rates and expanding aftermarket networks support consistent replacement demand, positioning Asia-Pacific as the fastest-growing regional market.
Latin America
Latin America accounts for nearly 8% of the global hydraulic hose market, supported by demand from mining, agriculture, and construction sectors. Brazil, Mexico, and Chile are key markets, driven by mining operations, infrastructure development, and mechanized farming. While new equipment sales fluctuate with economic conditions, the aftermarket remains resilient due to continuous maintenance requirements for existing machinery fleets. Investments in energy, transportation, and industrial facilities provide incremental growth opportunities. However, market expansion is moderated by economic volatility and budget constraints, making replacement demand a critical contributor to overall regional consumption.
Middle East & Africa
The Middle East & Africa region represents approximately 6% of the global hydraulic hose market, driven primarily by oil & gas, mining, construction, and infrastructure development. Gulf countries contribute significantly due to ongoing investments in energy projects, industrial facilities, and large-scale construction. In Africa, mining activities and gradual mechanization in agriculture support steady demand. Harsh operating environments increase wear and tear on hydraulic systems, strengthening replacement demand for durable, high-pressure hoses. Although the market remains smaller in scale, long-term infrastructure and energy diversification initiatives support gradual growth across the region.
Hydraulic Hose Market Segmentations:
By Product Type:
- Reinforced
- Coiled
- Corrugated
- Articulated
By Material:
- Elastomers or Rubber
- Fluoropolymers and Silicon
- Thermoplastics
- Metal
By Pressure:
- Low Pressure (Less Than 3,000 psi)
- Medium Pressure (Between 3,000 and 6,000 psi)
- High Pressure (More Than 6,000 psi)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The hydraulic hose market features a moderately consolidated competitive landscape, characterized by the presence of global manufacturers alongside strong regional players. Leading companies compete on product durability, pressure performance, material innovation, and compliance with stringent safety standards. Major participants maintain extensive product portfolios covering low-, medium-, and high-pressure applications to serve diverse end-use industries such as construction, agriculture, mining, oil & gas, and industrial manufacturing. Competitive differentiation increasingly depends on engineering expertise, customization capabilities, and value-added services, including hose assembly, maintenance support, and rapid aftermarket availability. Global players leverage advanced manufacturing facilities, broad distribution networks, and long-term OEM partnerships to strengthen market positioning. Meanwhile, regional manufacturers compete through cost competitiveness, localized production, and faster delivery. Continuous investment in R&D, quality assurance, and application-specific solutions remains central to sustaining competitive advantage.
Key Player Analysis
- Parker Hannifin Corporation
- Gates Corporation
- Bridgestone Corporation
- Eaton Corporation
- Alfagomma
- Semperit
- Sumitomo Riko
- RYCO Hydraulics
- Ouya Hose
Recent Developments
- In September 2025 ,Parker’s India division highlighted the Limber 6K spiral hose as an innovative class of hose meeting ISO 18752 DC specifications in -12 and -16 sizes, emphasizing performance in demanding conditions.
- In July 2024,Gates Corporation introduced a new series of thermoplastic hydraulic hoses designed for high-pressure applications with improved durability and lightweight characteristics, targeting automotive and construction sectors.
- In March 2024, Parker Hannifin announced the Hannifin HyDraulic X-tra series, a new line of high-pressure hydraulic hoses designed for enhanced durability and abrasion resistance suited to heavy-duty industrial uses. This development was reported as a notable product launch in the hydraulic hose and fittings market.
Report Coverage
The research report offers an in-depth analysis based on Product type, Material, Pressure and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for hydraulic hoses will continue to rise with sustained growth in construction, infrastructure, and industrial equipment deployment.
- Replacement and aftermarket sales will remain a stable revenue contributor due to strict safety standards and preventive maintenance practices.
- Medium- and high-pressure hoses will gain wider adoption as equipment performance requirements increase across industries.
- Reinforced hose designs will retain dominance due to durability and reliability in demanding operating conditions.
- Manufacturers will increasingly focus on lightweight and high-performance materials to improve efficiency and equipment compatibility.
- Custom-engineered hose assemblies will see higher demand as end users seek application-specific solutions.
- Integration of condition monitoring and predictive maintenance solutions will enhance hose lifecycle management.
- Asia-Pacific will remain the fastest-growing region supported by infrastructure expansion and industrialization.
- OEM partnerships will strengthen as equipment manufacturers seek long-term supply reliability and technical support.
- Continuous investment in quality, compliance, and product innovation will be critical to maintaining competitive positioning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the hydraulic hose market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the hydraulic hose market projected to grow between 2024 and 2032?
Which hydraulic hose segment held the largest share in 2024?
What are the primary factors fueling the growth of the hydraulic hose market?
Who are the leading companies in the hydraulic hose market?
Which region commanded the largest share of the hydraulic hose market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11,667 million → 2032: USD 17,041.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hydraulic Hose Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hydraulic Hose Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hydraulic Hose Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hydraulic Hose Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hydraulic Hose Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hydraulic Hose Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hydraulic Hose Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hydraulic Hose Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11,667 million → 2032: USD 17,041.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hydraulic Hose Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hydraulic Hose Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Hydraulic Hose Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Hydraulic Hose Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

