
Market Overview:
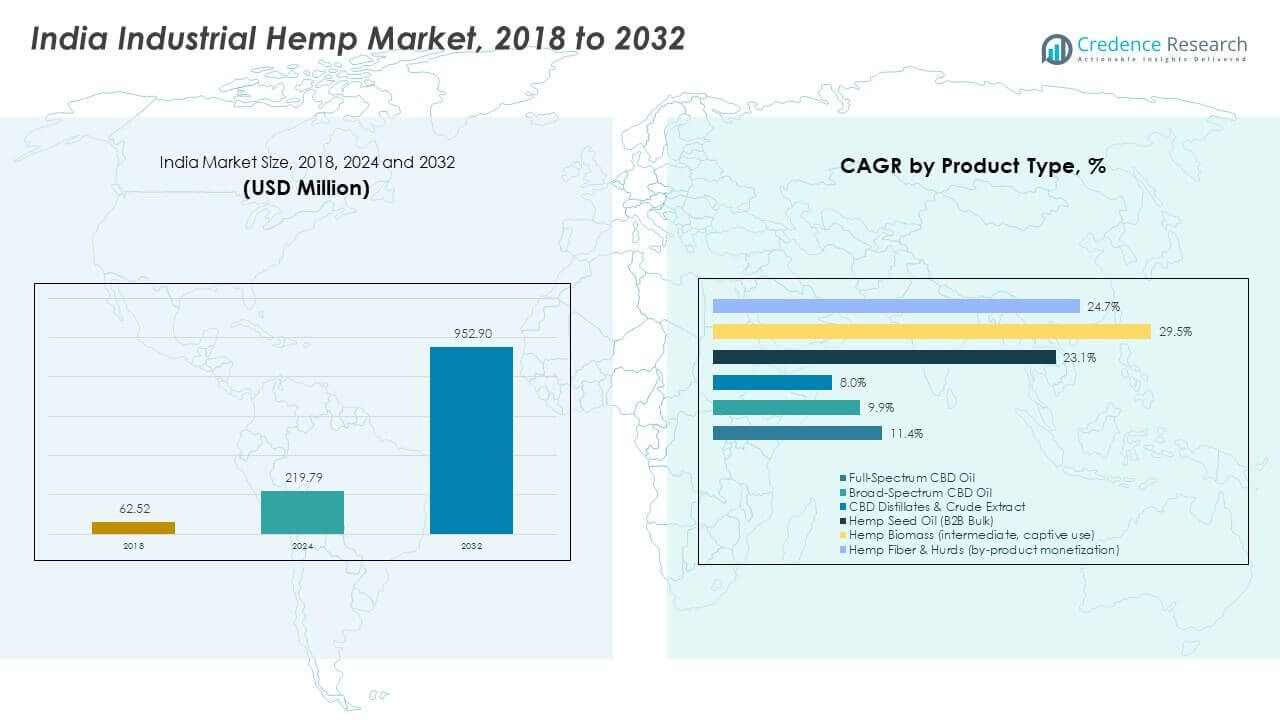
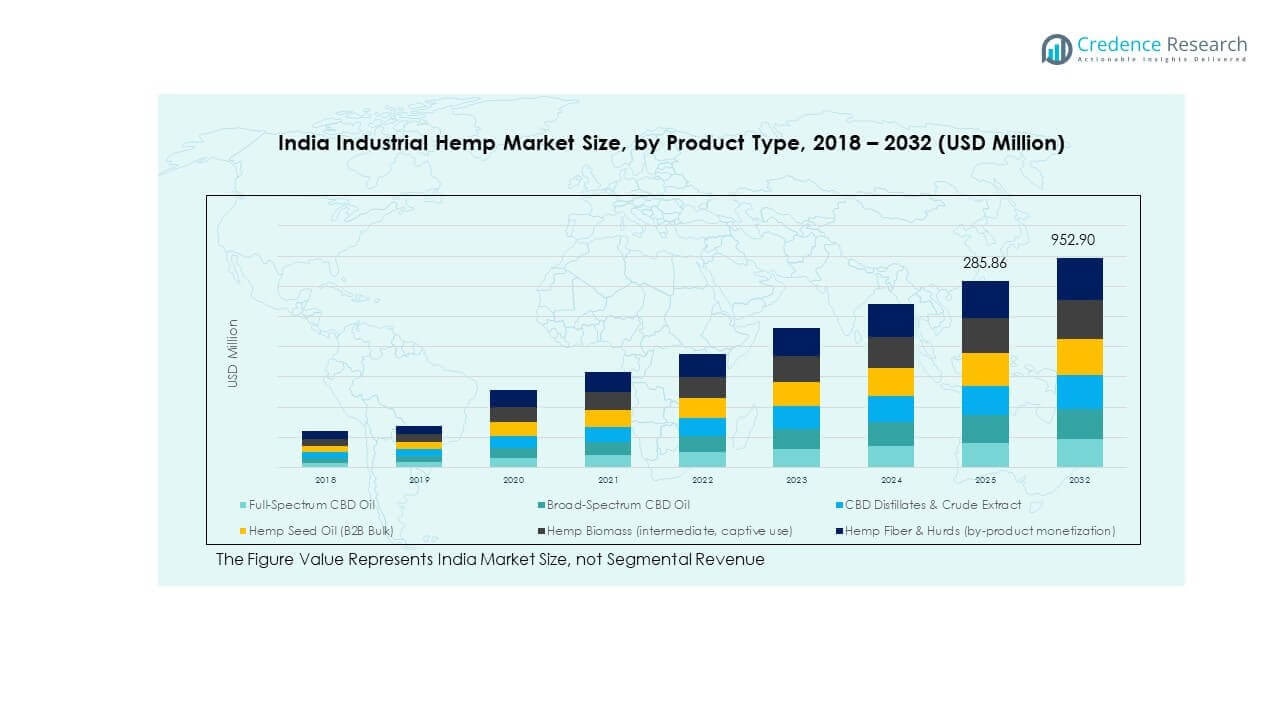
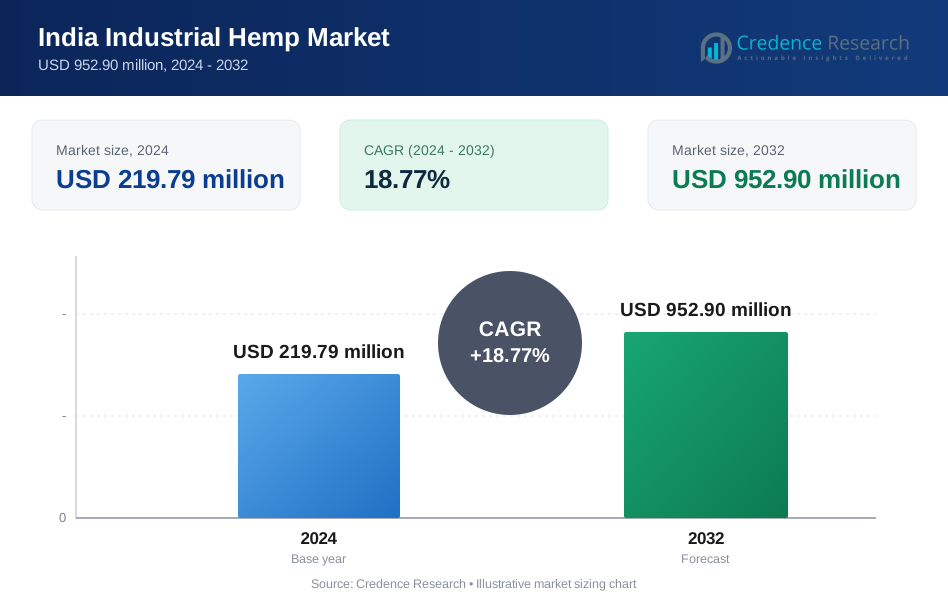
The India Industrial Hemp Market size was valued at USD 62.52 million in 2018 to USD 219.79 million in 2024 and is anticipated to reach USD 952.90 million by 2032, at a CAGR of 18.77% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Industrial Hemp Market Size 2024 | USD 219.79 Million |
| India Industrial Hemp Market, CAGR | 18.77% |
| India Industrial Hemp Market Size 2032 | USD 952.90 Million |
Market growth is driven by demand for sustainable raw materials across multiple industries. Textile producers adopt hemp fiber for durability and lower water use. Wellness brands use hemp extracts for personal care and nutrition products. Builders prefer hempcrete for insulation and carbon reduction goals. Farmers gain from crop diversification and higher income stability. Government support improves licensing clarity and research access. Startups scale processing and branding. Consumer awareness of eco-friendly products supports steady demand growth nationwide.
Northern hill states lead due to favorable climate and early policy support. Uttarakhand anchors cultivation and research through pilot programs. Northern plains emerge with processing hubs near textile clusters. Central states expand acreage due to suitable land and logistics access. Western India supports downstream manufacturing and exports. Northeastern regions show early-stage potential with supportive agro conditions. Southern states focus on value-added products and wellness brands. Regional strengths together build a balanced national supply chain.
Market Insights:
- The India Industrial Hemp Market was valued at USD 62.52 million in 2018, reached USD 219.79 million in 2024, and is projected to hit USD 952.90 million by 2032, expanding at a CAGR of 18.77%, driven by regulated cultivation, B2B demand, and downstream processing growth.
- Northern India leads with ~42% share, supported by early policy adoption and licensed cultivation, followed by Western India at ~28% due to processing and manufacturing hubs, and Southern India at ~20% driven by research, wellness brands, and formulation activity.
- Eastern and Northeastern India is the fastest-growing region, holding ~10% share, supported by favorable agro-climatic conditions, pilot cultivation programs, and rising interest in biomass and research-grade supply.
- By product mix, Full-spectrum CBD oil accounts for ~34% share, reflecting strong pharmaceutical and nutraceutical demand, while Broad-spectrum CBD oil holds ~22% share due to formulation flexibility and compliance alignment.
- CBD distillates and crude extracts contribute ~20%, supported by B2B processing demand, while hemp seed oil and hemp fiber & hurds together represent ~24%, driven by food ingredients, industrial use, and by-product monetization.
Market Drivers:
Rising Demand For Sustainable And Low-Impact Raw Materials
Manufacturers seek materials with lower environmental impact. Hemp offers low water use and soil benefits. Textile firms value fiber strength and breathability. Construction players prefer hemp-based insulation solutions. Food brands use hemp seeds for plant nutrition. Personal care companies adopt hemp for natural formulations. These factors support steady demand expansion. The India Industrial Hemp Market benefits from sustainability-focused procurement choices.
- For instance, Bombay Hemp Company states industrial hemp requires about 300–500 liters of water per kg of fiber, versus over 2,000 liters for cotton. The firm supplies hemp fiber, seeds, and hurd to apparel, nutrition, and construction users.
Supportive Policy Framework And State-Level Pilot Programs
Several states allow regulated hemp cultivation. Policy clarity reduces legal risk for farmers. Licensing frameworks support controlled production. Research institutions promote agronomic best practices. State pilots encourage private sector entry. Farmers gain confidence through official backing. Investment interest rises across value chains. Regulatory momentum strengthens long-term market growth.
- For instance, the Uttarakhand Industrial Hemp Policy allows licensed cultivation of hemp with THC content capped at 0.3%. The state works with GB Pant University to support agronomy and farmer training under approved pilots.
Growing Farmer Interest In Crop Diversification And Income Stability
Farmers seek alternatives to water-intensive crops. Hemp fits diverse agro-climatic zones. The crop supports soil health and rotation benefits. Stable offtake contracts reduce income volatility. Processing units create assured demand. Training programs improve cultivation quality. Input costs remain competitive for small growers. These factors drive wider farmer adoption.
Expansion Of Downstream Processing And Domestic Manufacturing Capacity
Processing capacity improves raw material utilization. Fiber decortication units reduce supply bottlenecks. Extraction facilities support wellness applications. Domestic manufacturing cuts import reliance. Integrated value chains enhance margin retention. Startups invest in branded finished goods. Scale improves cost competitiveness across segments. Industrial readiness accelerates overall market development.
Market Trends:
Shift Toward Value-Added And Branded Hemp-Based Products
Companies move beyond raw fiber sales. Brands focus on finished textiles and wellness items. Packaging highlights natural and ethical sourcing. Urban consumers favor traceable products. Branding supports premium pricing strategies. Online channels improve product reach. Retail presence expands in major cities. This trend reshapes competitive positioning.
- For instance, HempStreet operates over 100 doctor-led clinics across India and sells hemp-based wellness products through digital channels. The firm follows prescription-based distribution aligned with state regulations.
Growing Focus On Research-Led Cultivation And Seed Optimization
Producers invest in better seed genetics. Research improves yield consistency and fiber quality. Controlled THC compliance remains a priority. Data-driven farming supports predictability. Collaboration with universities increases field trials. Knowledge transfer raises farm-level efficiency. Standardized inputs reduce variability. Scientific farming practices gain traction.
- For instance, CSIR-IHBT developed certified industrial hemp varieties for fiber and seed with THC below 0.3%. Field trials improved plant uniformity and supported controlled cultivation models.
Integration Of Hemp In Green Construction And Circular Economy Models
Builders explore hempcrete for insulation use. Green certifications support material adoption. Circular economy goals align with hemp use. Waste reduction strengthens project viability. Developers seek low-carbon building inputs. Demonstration projects build market confidence. Policy discussions support sustainable construction. This trend opens new application areas.
Emergence Of Export-Oriented Manufacturing And Niche Applications
Manufacturers target international buyers for fiber products. Quality compliance supports export readiness. Niche uses include composites and specialty textiles. Certifications enhance global acceptance. Trade fairs improve buyer connections. Export focus supports scale economics. Product differentiation gains importance. Global exposure shapes product standards.
Market Challenges Analysis:
Complex Regulatory Interpretation And Uneven State-Level Enforcement
Regulatory clarity varies across regions. Interpretation differences create compliance risk. Licensing timelines delay project execution. Enforcement gaps affect investor confidence. Transport rules remain inconsistent. Documentation burdens small producers. Legal ambiguity raises operating costs. The India Industrial Hemp Market faces coordination challenges across jurisdictions.
Limited Processing Infrastructure And Skilled Workforce Availability
Processing facilities remain regionally concentrated. Logistics costs rise for distant farms. Skilled technicians remain in short supply. Equipment costs challenge small operators. Quality inconsistency affects buyer trust. Training programs lack uniform reach. Capital access limits rapid scale-up. Infrastructure gaps slow value chain maturity.
Market Opportunities:
Expansion Of Hemp-Based Wellness, Nutrition, And Personal Care Segments
Consumer interest in natural wellness rises. Hemp ingredients support clean-label positioning. Nutrition brands adopt plant-based formulations. Personal care firms value functional properties. Product innovation improves market differentiation. Domestic demand supports scale expansion. Distribution networks widen product access. This opportunity supports high-margin growth paths.
Development Of Integrated Farm-To-Finished-Goods Business Models
Vertical integration improves supply control. Direct sourcing enhances traceability claims. Integrated models reduce margin leakage. Branding benefits from origin transparency. Investors favor scalable integrated platforms. Export readiness improves under unified control. Partnerships support rapid execution. This structure strengthens long-term competitiveness.
Market Segmentation Analysis:
By Product Type
Full-spectrum CBD oil leads demand due to broad cannabinoid profiles and strong therapeutic acceptance. CBD distillates gain traction for consistent potency and formulation flexibility. CBD isolates serve applications requiring precise dosing and zero THC tolerance. Hemp biomass and extracts support large-scale B2B demand from processors and researchers. Product preference depends on regulatory fit and downstream application needs.
- For instance, BOHECO supplies licensed hemp biomass for industrial and research use. The company maintains batch testing and traceability to meet regulatory standards.
By Value Chain Integration
Cultivation-only players focus on licensed farming and raw material supply. Cultivation and processing models improve value capture and supply reliability. Fully integrated cultivation, extraction, and formulation structures offer quality control and cost efficiency. This integration supports traceability and compliance assurance. Scale favors integrated operators with technical and regulatory expertise.
By End-Use Application (B2B)
Pharmaceuticals and nutraceuticals represent a core demand segment due to clinical research and formulation use. Wellness and personal care brands adopt hemp inputs for natural positioning. Food and beverage ingredient buyers focus on controlled and compliant inputs. Research and formulation labs drive early-stage and pilot demand. End-use diversity supports steady volume absorption.
By Business Model
Contract manufacturing supports brands without in-house capability. Private label supply enables faster market entry for buyers. Direct B2B sales strengthen long-term buyer relationships. Export-oriented supply targets regulated overseas markets. The India Industrial Hemp Market balances domestic demand with export ambitions.
By Compliance and Quality Grade
Pharmaceutical grade commands strict testing and documentation. Food grade supports regulated consumption applications. Industrial grade serves research and non-ingestible uses. Quality segmentation shapes pricing and buyer selection criteria.
Segmentation:
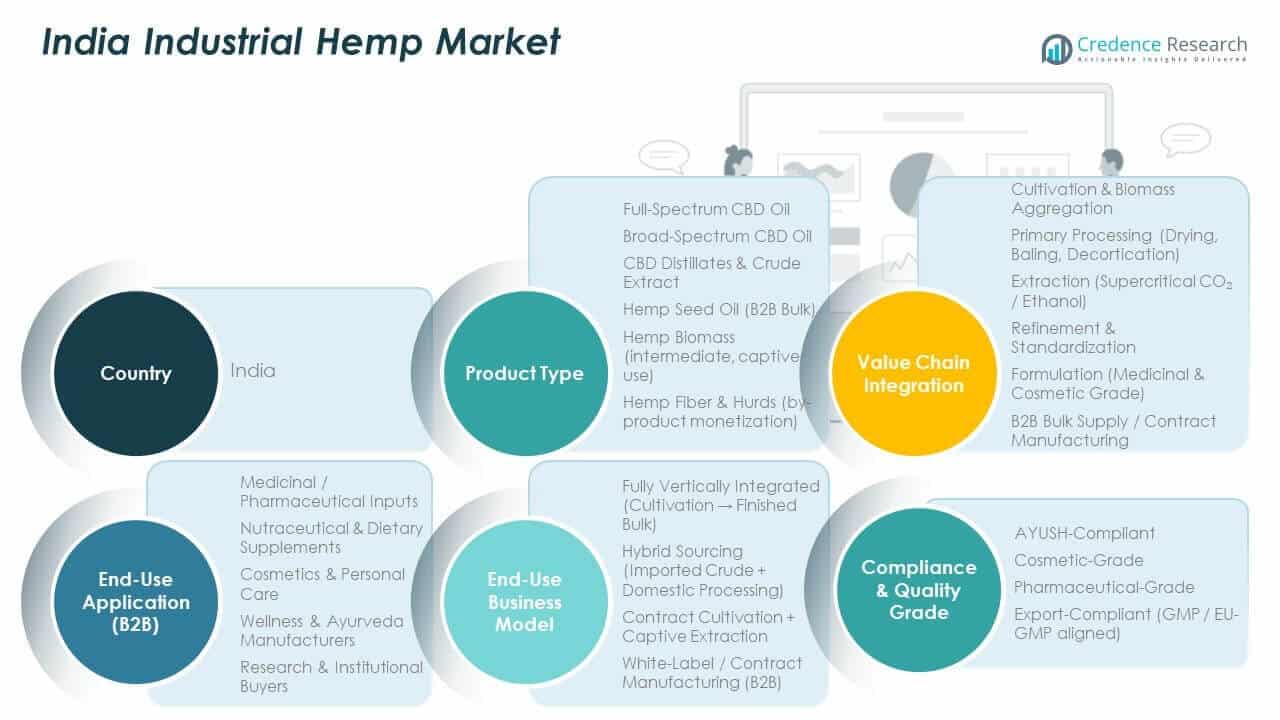
- By Product Type
- Full-spectrum CBD oil
- CBD distillates
- CBD isolates
- Hemp biomass and extracts
- By Value Chain Integration
- Cultivation only
- Cultivation and processing
- Integrated cultivation, extraction, and formulation
- By End-Use Application (B2B)
- Pharmaceuticals and nutraceuticals
- Wellness and personal care
- Food and beverage ingredients
- Research and formulation labs
- By Business Model
- Contract manufacturing
- Private label supply
- Direct B2B sales
- Export-oriented supply
- By Compliance and Quality Grade
- Pharmaceutical grade
- Food grade
- Industrial grade
- By Geography
- North India
- West India
- South India
- East and Northeast India
Regional Analysis:
Northern India Dominates With The Largest Market Share
Northern India accounted for nearly 42% market share in the India Industrial Hemp Market in 2024. Uttarakhand and Himachal Pradesh lead due to early regulatory approvals and licensed cultivation programs. Favorable climate supports consistent crop quality and yield. Processing units located near cultivation zones reduce logistics dependency. Pharmaceutical and nutraceutical buyers prefer this region for compliant sourcing. Farmer participation remains high due to structured state support. The region continues to anchor national supply volumes.
Western And Southern India Hold Strong Secondary Positions
Western India captured around 28% market share, driven by Maharashtra and Gujarat. The region benefits from established agribusiness infrastructure and extraction facilities. Industrial clusters support contract manufacturing and private label supply. Southern India held close to 20% market share, led by Karnataka and Tamil Nadu. Research institutions and wellness brands drive downstream demand. Processing and formulation activities expand steadily. Urban consumption hubs support B2B offtake growth.
Eastern And Northeastern India Represent Emerging Markets
Eastern and Northeastern India together accounted for nearly 10% market share. These regions gain traction through pilot cultivation programs and policy experimentation. Agro-climatic conditions favor fiber and biomass quality. Infrastructure remains limited but attracts early-stage investment. Local startups explore food ingredients and research supply. Government initiatives encourage farmer onboarding. This region shows potential for gradual share expansion over the forecast period.
Key Player Analysis:
- BOHECO (Bombay Hemp Company)
- HempStreet
- Vedi Herbals
- Atrimed Biotech
- India Hemp Organics
- HempCann Solutions
- Cannazo India
- Satliva
- CannaMeds India
- Avesthagen (Hemp Division)
Competitive Analysis:
The India Industrial Hemp Market shows a moderately consolidated competitive structure with a mix of startups and diversified biotech firms. Key players focus on controlled cultivation, extraction capability, and compliance management. Companies compete on product purity, traceability, and consistency rather than price alone. Vertical integration strengthens cost control and supply assurance. Strategic partnerships with farmers improve raw material access. R&D investment supports formulation depth and application expansion. Branding remains limited in B2B channels, which favors long-term supply contracts. It relies on regulatory alignment and operational discipline to sustain competitiveness.
Recent Developments:
- In December 2025, BOHECO announced a major strategic shift towards physical retail to drive its next phase of growth. The company, which has historically operated as a digital-first brand, revealed plans to open over 16 new brick-and-mortar stores within the next two years. This expansion includes the operations of its flagship 1,070 sq. ft. store on Brigade Road, Bengaluru, and a wider footprint across Delhi-NCR and Hyderabad. Additionally, BOHECO highlighted its growing international presence with successful exports to South Korea and new strategic tie-ups in Brazil, the Middle East, Thailand, and Australia.
- In July 2025, Vedi Herbals was announced as an Associate Sponsor for the Vegan India Conference 2025, reinforcing its brand positioning in the plant-based wellness sector. Furthermore, in August 2024, the brand expanded its portfolio beyond medicinal cannabis by aggressively entering the hemp body goods market. This expansion includes a new range of hemp-based body washes, liquid soaps, and personal care products that blend cannabis leaf extracts with traditional Ayurvedic herbs, marking a diversification from their core prescription-based medicines.
- In March 2025, CannaMeds India reinforced its status as India's leading aggregator and marketplace for CBD and hemp products by expanding its digital catalogue to include exclusive bundles and new brands. As a primary retail platform, it recently listed high-potency products like the "Magiccann Extra Strong" gummies and "Cannazo Uplift" series, facilitating access to prescription-based cannabis medicines for patients across India. The platform has continued to scale its "journey guide" consultation services to assist users in obtaining legal medical prescriptions.
- In February 2025, Avesthagen announced a major strategic partnership between its subsidiary, The Avestagenome Project®, and the Tata Institute for Genetics and Society (TIGS). While primarily focused on genetics, this alliance utilizes Avesthagen's extensive biobank and research capabilities often cross-leveraged with their bioactive and medical cannabis research to study rare genetic disorders. Additionally, in October 2024, the company appointed Dr. Nilgiriwala as Vice President of Research & Development, signaling a renewed push in their R&D initiatives for precision diagnostics and bioactive product development.
- In November 2023 (with strategic execution continuing into 2024), HempStreet secured $1 million in a pre-Series A funding round led by Waahlin Holdings to fuel its global expansion and product development. The company announced plans to enter the Latin American and North American markets in 2024, launching a new line of clinically backed, Ayurveda-inspired cannabis medications to treat primary and secondary dysmenorrhea. This expansion is supported by key international partnerships with entities such as MGC Pharma (UK), Gynica (Israel), and UIDI (Brazil).
Report Coverage:
The research report offers an in-depth analysis based on product type, value chain integration, end-use application, business model, compliance grade, and geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Regulated cultivation frameworks will strengthen operational confidence across states.
- Vertical integration will gain preference for quality and compliance control.
- Pharmaceutical and nutraceutical demand will anchor B2B volume stability.
- Research-driven cultivation practices will improve yield consistency.
- Export-oriented supply models will expand under compliant sourcing.
- Contract manufacturing will support faster brand entry.
- Processing infrastructure will spread beyond early adopter states.
- Wellness applications will diversify formulation demand.
- Traceability systems will shape buyer selection criteria.
- Policy clarity will remain central to long-term expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Sustainable and Low-Impact Raw Materials
Manufacturers across textiles, construction, and personal care are increasingly seeking eco-friendly alternatives, and hemp offers lower water usage, soil benefits, and reduced carbon footprint compared to conventional crops. This sustainability advantage is driving adoption in India’s industrial sectors.
Supportive Policy Framework and State-Level Pilot Programs
Several Indian states have introduced regulated hemp cultivation policies, reducing legal risks for farmers and encouraging private sector investment. State-backed pilot programs and licensing clarity are accelerating market entry and expansion.
Expansion of Downstream Processing and Domestic Manufacturing
Growth in domestic processing capacity, including fiber decortication and extraction facilities, is improving raw material utilization and supporting the development of value-added products. This infrastructure expansion is enabling India to reduce import reliance and enhance supply chain integration.
Growing Farmer Interest in Crop Diversification and Income Stability
Hemp provides farmers with an alternative to water-intensive crops, supports soil health, and offers stable offtake contracts, reducing income volatility. State support and training programs are further encouraging farmer participation and acreage expansion.
Shift Toward Value-Added and Branded Hemp-Based Products
Indian companies are moving beyond raw material sales to develop branded textiles, wellness, and personal care products, leveraging traceability and natural positioning to capture premium market segments and expand urban and export demand.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for India Industrial Hemp Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the India Industrial Hemp Market projected to grow between 2024 and 2032?
Which India Industrial Hemp Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the India Industrial Hemp Market?
Who are the leading companies in the India Industrial Hemp Market?
Which region commanded the largest share of the India Industrial Hemp Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Full-spectrum CBD oil
- 1.2.2 CBD distillates
- 1.2.3 CBD isolates
- 1.2.4 Hemp biomass and extracts
- 1.3 By Value Chain Integration
- 1.3.1 Cultivation only
- 1.3.2 Cultivation and processing
- 1.3.3 Integrated cultivation, extraction, and formulation
- 1.4 By End-Use Application (B2B)
- 1.4.1 Pharmaceuticals and nutraceuticals
- 1.4.2 Wellness and personal care
- 1.4.3 Food and beverage ingredients
- 1.4.4 Research and formulation labs
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 219.79 million → 2032: USD 952.90 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Industrial Hemp Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Industrial Hemp Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Industrial Hemp Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Industrial Hemp Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Industrial Hemp Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Industrial Hemp Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Industrial Hemp Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Industrial Hemp Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 219.79 million → 2032: USD 952.90 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Industrial Hemp Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Full-spectrum CBD oil
- 12.3.7.2 CBD distillates
- 12.3.7.3 CBD isolates
- 12.3.7.4 Hemp biomass and extracts
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Value Chain Integration - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cultivation only
- 12.4.7.2 Cultivation and processing
- 12.4.7.3 Integrated cultivation, extraction, and formulation
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-Use Application (B2B) - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pharmaceuticals and nutraceuticals
- 12.5.7.2 Wellness and personal care
- 12.5.7.3 Food and beverage ingredients
- 12.5.7.4 Research and formulation labs
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 India Industrial Hemp End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 India Industrial Hemp Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 India Industrial Hemp Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 India Industrial Hemp Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BOHECO (Bombay Hemp Company)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 HempStreet
- 18.4 Vedi Herbals
- 18.5 Atrimed Biotech
- 18.6 India Hemp Organics
- 18.7 HempCann Solutions
- 18.8 Cannazo India
- 18.9 Satliva
- 18.10 CannaMeds India
- 18.11 Avesthagen (Hemp Division)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

