
Market Overview
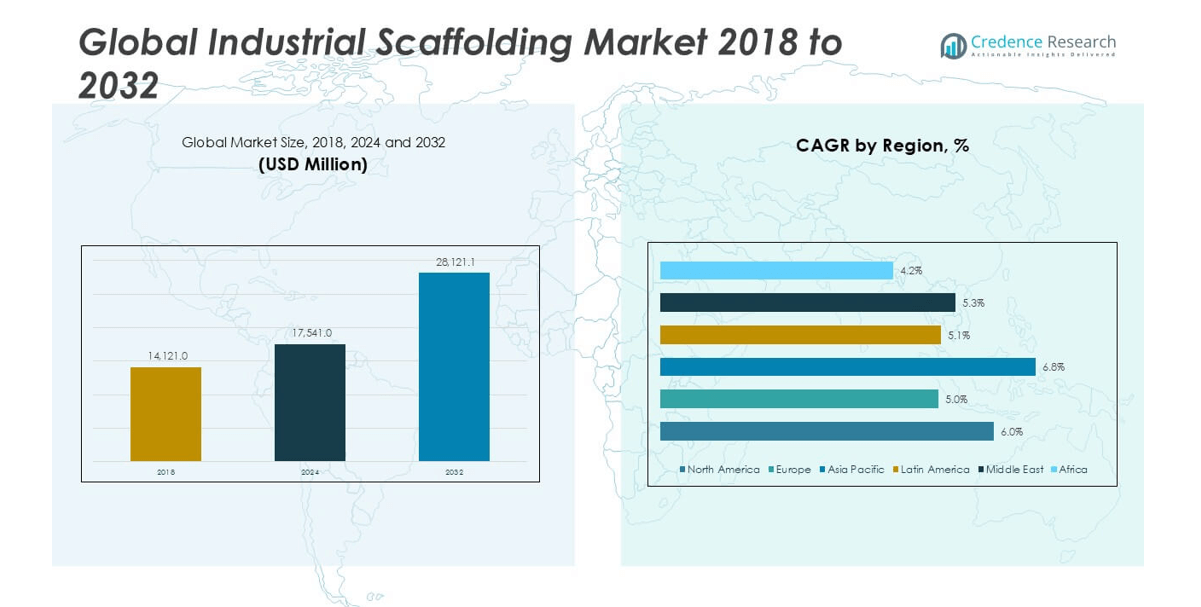
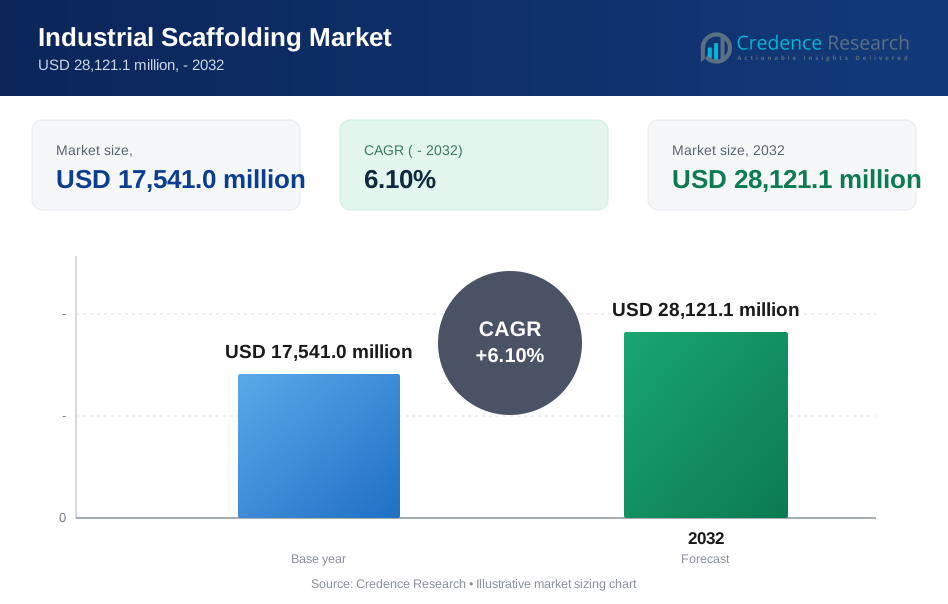
Global Industrial Scaffolding market size was valued at USD 14,121.0 million in 2018, reached USD 17,541.0 million in 2024, and is anticipated to reach USD 28,121.1 million by 2032, at a CAGR of 6.10% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Industrial Scaffolding Market Size 2024 | USD 17,541.0 million |
| Industrial Scaffolding Market, CAGR | 6.10% |
| Industrial Scaffolding Market Size 2032 | USD 28,121.1 million |
The global industrial scaffolding market is led by prominent players including PERI GmbH, Layher Holding GmbH & Co. KG, BrandSafway, ULMA Construction, Altrad Group, Waco International, Tata Projects, Lindner Group, Interserve (Tilbury Douglas), and Devco. These companies collectively hold a significant share of global revenue, driven by their strong product portfolios, rental services, and large-scale project capabilities. Asia Pacific dominates the market with a 49.4% share in 2018, fueled by rapid industrialization, infrastructure projects, and investments in oil, gas, and power sectors. North America and Europe follow, supported by strict safety regulations and high maintenance activity across industrial plants, refineries, and power generation facilities.
Market Insights
- The global industrial scaffolding market was valued at USD 14,121.0 million in 2018, reached USD 17,541.0 million in 2024, and is projected to reach USD 28,121.1 million by 2032, growing at a CAGR of 6.10%.
- Growth is driven by rising infrastructure projects, refinery maintenance, and power plant construction, boosting demand for supported and modular scaffolding systems which together account for over 60% of the market share.
- Key trends include adoption of modular scaffolding for faster assembly, digital monitoring solutions, and increased use of rental services to reduce upfront costs for contractors.
- The market is moderately consolidated, with players like PERI GmbH, Layher, BrandSafway, and Altrad Group focusing on product innovation, sustainability, and global service networks to stay competitive.
- Asia Pacific leads with 49.4% share, followed by North America and Europe, driven by industrialization, urban development, and strict safety compliance standards supporting scaffolding adoption.
Market Segmentation Analysis:
By Type of Scaffolding
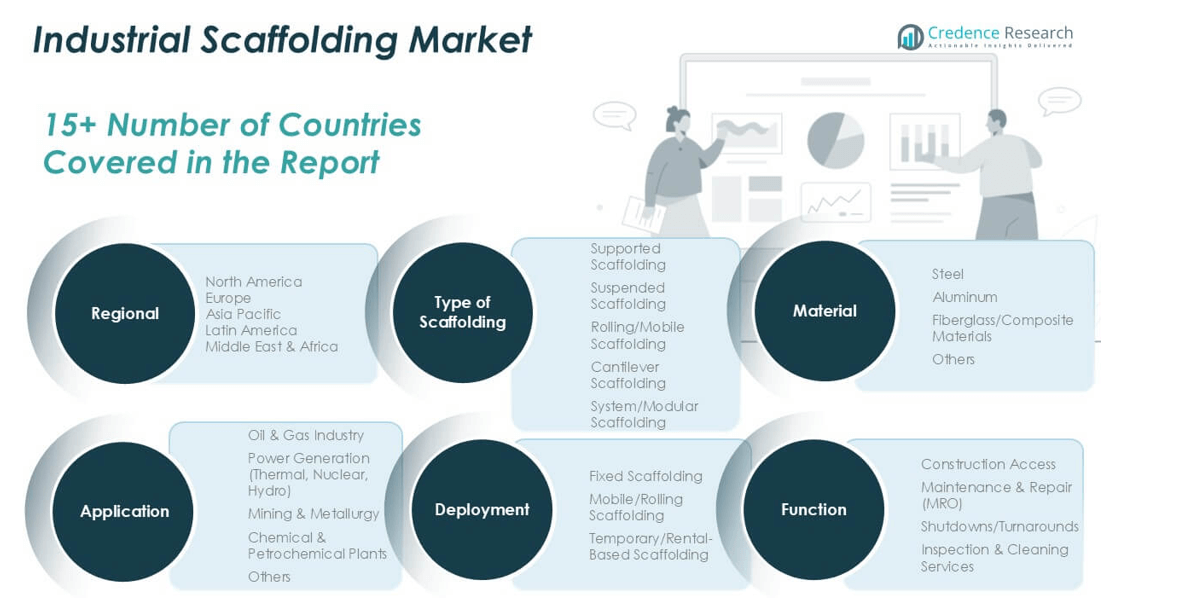
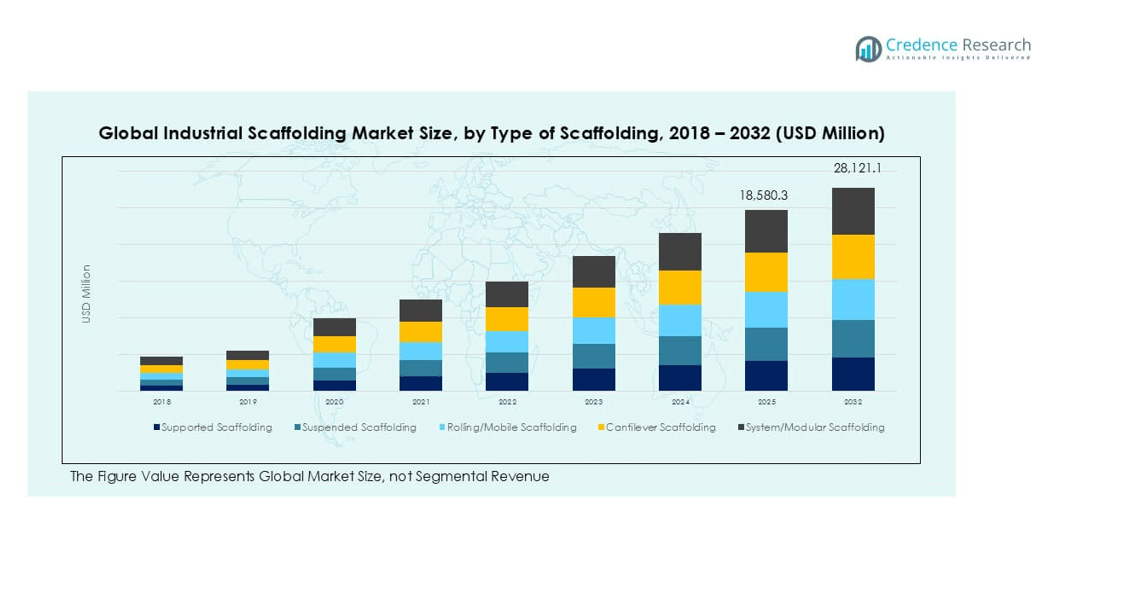
Supported scaffolding holds the largest share in the global industrial scaffolding market, accounting for over 45% of total demand. Its dominance is driven by its versatility, high load-bearing capacity, and easy installation, making it ideal for construction, maintenance, and industrial projects. System/modular scaffolding follows, favored for large-scale industrial plants due to its quick assembly and safety features. Rolling/mobile scaffolding sees rising adoption in maintenance applications requiring frequent relocation. Suspended and cantilever scaffolding remain niche but essential for high-rise construction and specialized industrial tasks, supported by the need for safe elevated access solutions.
- For instance, under EN 12810/12811 standards, some modular/all-round scaffold decks are rated to carry 6.0 kN/m² vertical load on 0.73 m span decks
By Application
The oil & gas industry represents the dominant application segment, capturing nearly 40% market share, supported by continuous maintenance and turnaround projects in refineries and offshore platforms. Power generation projects, including thermal and nuclear plants, contribute significantly as governments invest in grid modernization and new capacity additions. Mining and metallurgy projects drive demand for durable scaffolding to support heavy equipment maintenance and smelter operations. Chemical and petrochemical plants require corrosion-resistant solutions to ensure worker safety. Other applications, such as infrastructure and shipbuilding, also provide steady opportunities with growing global construction activity.
- For instance, for major turnarounds at refineries, such as at Zeeland Refinery in the Netherlands, BrandSafway and other industrial access companies provide scaffolding to enable safe access for inspection and repair within compressed shutdown schedules.
By Material
Steel scaffolding dominates the market with over 60% share, driven by its strength, reusability, and ability to withstand heavy loads in challenging environments. It is the preferred material for large-scale oil, gas, and power generation projects requiring stability and durability. Aluminum scaffolding is gaining traction for projects demanding lightweight, portable solutions, particularly in maintenance and quick-assembly tasks. Fiberglass/composite materials serve niche applications in chemical plants where non-conductive and corrosion-resistant properties are critical. Other materials hold limited use but are finding opportunities in specialized environments requiring custom solutions.
Market Overview
Infrastructure Expansion and Industrialization
Rapid industrialization and urban infrastructure development drive demand for industrial scaffolding worldwide. Large-scale projects in transportation, commercial construction, and smart cities require extensive scaffolding for structural support and worker safety. Emerging economies in Asia-Pacific, including India and China, are investing heavily in road networks, industrial parks, and high-rise buildings. Industrial scaffolding plays a critical role in supporting these projects with modular, reusable, and cost-efficient solutions. The consistent growth of infrastructure pipelines ensures long-term demand for scaffolding systems across multiple sectors.
- For instance, PERI supplied a significant amount of formwork and scaffolding for the construction of Istanbul Airport, ensuring safe access and structural stability. The company's PERI UP scaffolding systems were used to install 15,500 square meters of movable working platforms to process the terminal's massive 220,000-square-meter slab area
Maintenance and Repair Activities in Oil & Gas and Power Plants
Regular maintenance in oil refineries, offshore platforms, and power generation facilities fuels steady scaffolding demand. Turnaround projects, shutdowns, and inspection cycles require large scaffolding setups to access high-risk and elevated areas safely. Governments’ focus on extending the operational life of existing assets boosts maintenance budgets. Industrial scaffolding providers benefit from this recurring demand by offering rental services, prefabricated systems, and quick-assembly modular solutions to minimize downtime and enhance worker productivity during maintenance operations.
- For instance, BrandSafway provided scaffolding and other access solutions during refinery turnarounds in Europe, helping maintenance teams complete inspections and repairs within a shortened outage period
Focus on Worker Safety and Regulatory Compliance
Stringent safety regulations from OSHA, EU-OSHA, and other authorities push industries to adopt advanced scaffolding systems. These standards require safer platforms, guardrails, and fall protection, driving replacement of outdated systems with modern designs. Manufacturers are introducing lightweight, high-strength modular scaffolding that meets global safety norms. Compliance with safety requirements reduces workplace accidents and improves operational efficiency, encouraging investment in premium scaffolding solutions. This regulatory push creates consistent demand across construction, energy, and industrial sectors.
Key Trends & Opportunities
Adoption of Modular and Automated Scaffolding Systems
The market is witnessing rising adoption of modular scaffolding systems that allow faster assembly, disassembly, and reuse. Automated scaffolding platforms and robotic solutions are gaining traction in high-rise and industrial projects, reducing labor requirements and improving safety. Contractors prefer modular systems to cut project timelines and labor costs. This trend is creating opportunities for manufacturers to design lightweight, precision-engineered scaffolding with digital monitoring features that track load capacity and usage data in real time.
- For instance, PERI’s PERI UP Flex modular scaffolding system allows deck-by-deck assembly with load classes up to 6.0 kN/m², enabling safer work at heights over 40 m.
Growth in Rental and Leasing Services
Scaffolding rental services are expanding as companies seek cost-effective solutions for short-term projects and maintenance operations. Renting eliminates capital investment and reduces storage costs for contractors. Rental providers offer end-to-end services, including design, installation, and dismantling, enhancing convenience. The rising preference for pay-per-use models creates opportunities for scaffolding suppliers to expand their service networks and increase recurring revenue, particularly in emerging markets with limited capital availability.
- For instance, BrandSafway operates one of the largest scaffolding and access equipment rental operations globally, supporting refinery turnarounds and construction projects.
Key Challenges
High Initial Investment and Maintenance Costs
Purchasing and maintaining industrial scaffolding systems involve significant upfront costs, limiting adoption among small contractors. Steel systems require periodic inspection, cleaning, and refurbishment to meet safety standards, adding to operational expenses. This cost factor often drives contractors toward rental options, affecting direct sales revenue for manufacturers. Market players must offer flexible financing, leasing models, and durable products to address cost-sensitive buyers and maintain competitiveness.
Shortage of Skilled Labor for Installation
The industry faces a shortage of trained workers capable of assembling and dismantling scaffolding systems safely and efficiently. Improper installation increases accident risks and delays project timelines. Companies are investing in training programs, but the gap remains significant in developing regions. Manufacturers are responding with easy-to-assemble modular designs to reduce dependence on skilled labor. Addressing the labor shortage remains critical for sustaining market growth and ensuring compliance with safety standards.
Regional Analysis
North America
North America accounted for 19.7% of the global industrial scaffolding market in 2018, valued at USD 2,781.84 million. The market grew to USD 3,378.30 million in 2024 and is projected to reach USD 5,368.83 million by 2032, registering a CAGR of around 5.96%. Growth is driven by robust construction activity, oil and gas maintenance projects, and strict OSHA safety standards. High adoption of modular scaffolding systems supports efficiency in power generation and infrastructure upgrades. The U.S. dominates regional demand, supported by investments in industrial expansion, commercial building projects, and refinery maintenance cycles.
Europe
Europe represented 18.4% of the market in 2018 with a value of USD 2,598.26 million and is expected to reach USD 4,493.55 million by 2032 at a CAGR of nearly 4.97%. Demand is supported by stringent EU safety regulations and ongoing refurbishment of aging infrastructure. Growth in the renewable energy sector, including offshore wind installations, further drives scaffolding requirements. Germany, the UK, and France are key contributors due to strong industrial maintenance activity and urban infrastructure development. Manufacturers focus on lightweight, high-strength materials to comply with regional sustainability and worker safety guidelines.
Asia Pacific
Asia Pacific dominated the global market with a 49.4% share in 2018, valued at USD 6,975.77 million. The market is projected to reach USD 14,935.98 million by 2032, recording the fastest CAGR of about 6.75%. Rapid industrialization, urban infrastructure growth, and large-scale projects in China, India, and Southeast Asia fuel demand. Expanding oil and gas, power generation, and mining sectors support continuous scaffolding needs. Government investments in smart cities and manufacturing clusters boost adoption of modular and steel scaffolding systems, making Asia Pacific the key growth engine for global market expansion.
Latin America
Latin America held a 5.9% share in 2018, valued at USD 828.90 million, and is set to reach USD 1,506.45 million by 2032, growing at a CAGR of about 5%. Industrial scaffolding demand is driven by oil and gas projects in Brazil, Mexico, and Argentina, along with infrastructure upgrades. Mining and metallurgy sectors contribute significantly to growth, especially in Chile and Peru. Adoption of rental scaffolding services is rising as contractors look to minimize upfront costs. Manufacturers are targeting this region with cost-effective modular solutions to meet growing industrial maintenance requirements.
Middle East & Africa (MEA)
MEA contributed 6.6% of the global share in 2018, with a value of USD 936.2 million, and is anticipated to reach USD 1,816.3 million by 2032 at a CAGR of about 4.88%. Growth is supported by oil and gas exploration, petrochemical projects, and large-scale construction initiatives like NEOM in Saudi Arabia. Power plant expansions and infrastructure development across the UAE, South Africa, and Egypt also boost scaffolding demand. The region favors steel scaffolding due to its durability in harsh climates. Strategic collaborations with rental service providers support accessibility for mid-sized contractors.
Market Segmentations:
By Type of Scaffolding
- Supported Scaffolding
- Suspended Scaffolding
- Rolling/Mobile Scaffolding
- Cantilever Scaffolding
- System/Modular Scaffolding
By Application
- Oil & Gas Industry
- Power Generation (Thermal, Nuclear, Hydro)
- Mining & Metallurgy
- Chemical & Petrochemical Plants
- Others
By Material
- Steel
- Aluminum
- Fiberglass/Composite Materials
- Others
By Deployment
- Fixed Scaffolding
- Mobile/Rolling Scaffolding
- Temporary/Rental-Based Scaffolding
By Function
- Construction Access
- Maintenance & Repair (MRO)
- Shutdowns/Turnarounds
- Inspection & Cleaning Services
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The global industrial scaffolding market is moderately consolidated, with key players such as PERI GmbH, Layher Holding GmbH & Co. KG, BrandSafway, ULMA Construction, Altrad Group, Waco International, Tata Projects, Lindner Group, Interserve (Tilbury Douglas), and Devco dominating industry revenue. These companies focus on offering comprehensive solutions, including design, engineering, rental, and installation services. Innovation in modular and system scaffolding is a priority, enabling faster assembly and improved safety compliance. Strategic partnerships, mergers, and acquisitions are common to expand geographic reach and enhance service capabilities. Leading players invest in digital solutions such as 3D modeling and load monitoring systems to optimize project planning. Sustainability initiatives, including recyclable materials and lightweight designs, are gaining importance to meet customer and regulatory demands. The competitive environment encourages companies to differentiate through cost-effective rental models, advanced safety features, and global service networks, driving intense competition across major end-use sectors.
Key Player Analysis
- PERI GmbH
- Layher Holding GmbH & Co. KG
- BrandSafway
- ULMA Construction
- Altrad Group
- Waco International
- Tata Projects (Tata Group)
- Lindner Group
- Interserve (Tilbury Douglas)
- Devco
Recent Developments
- In July 2022, A major developer and provider of formwork and scaffolding systems, PERI Formwork Systems, Inc., has developed what would become a new industry standard for bridge construction. VPS ensures a safety and efficiency gap through a highly versatile system that is adjustable, rentable, and productive in forming bridge columns and caps.
- In July 2022, Doka, a key player in formwork solutions and services to the construction industry has taken its collaboration with the well-known American scaffolding company AT-PAC to the next level by making a significant investment in the US-based firm. The two companies first teamed up in 2020 to offer comprehensive solutions for building sites, and their partnership has only grown stronger since then.
- In July 2022, A Glasgow subsidiary named StepUp Scaffold UK from StepUp Scaffold Group in Memphis has completed the purchase of MP House ApS located near Copenhagen during July 2022. The company MP House stands as the dominant supplier of tools and equipment along with accessories to scaffolding operators based in Denmark.
- In April 2022, Layher Holding GmbH Co KG has introduced the Allround Scaffold, a name that reflects the company and perhaps represents the pinnacle of modular scaffolding solutions. The Modular Scaffolding System is essentially the Layher Allround Scaffolding. This system is comparable to Allround Performance, as it serves multiple purposes within a single framework. No matter how complex the designs, architectural styles, or strict safety standards may be, Allround Scaffolding consistently proves to be the quicker, safer, and more economical choice.
Report Coverage
The research report offers an in-depth analysis based on Type of Scaffolding, Application, Material, Deployment, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see strong demand from large-scale infrastructure and industrial expansion projects worldwide.
- Modular and system scaffolding will gain more share due to faster assembly and higher safety.
- Rental and leasing services will grow as contractors focus on reducing capital expenditure.
- Adoption of digital solutions like 3D modeling and load monitoring will increase project efficiency.
- Steel scaffolding will remain the preferred material, but aluminum and composites will gain traction for lightweight needs.
- Asia Pacific will continue leading growth, supported by rapid urbanization and government investments.
- Oil, gas, and power generation maintenance projects will ensure recurring demand for scaffolding services.
- Sustainability initiatives will push manufacturers to use recyclable materials and eco-friendly designs.
- Competition will intensify as key players expand service networks and global presence through partnerships.
- Training and skilled labor development will be critical to ensure safe and efficient installations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Infrastructure Expansion and Industrialization
Rapid industrialization and large-scale infrastructure projects, especially in Asia Pacific, are driving demand for industrial scaffolding to support construction, urban development, and smart city initiatives.
Recurring Maintenance in Oil, Gas, and Power Sectors
Continuous maintenance, turnaround, and inspection activities in refineries, power plants, and offshore platforms require extensive scaffolding setups, ensuring steady market demand.
Stringent Safety and Regulatory Compliance
Strict safety regulations from authorities like OSHA and EU-OSHA are pushing industries to upgrade to advanced scaffolding systems with enhanced safety features, fueling market growth.
Growth of Rental and Leasing Services
The increasing preference for rental and leasing models allows contractors to minimize capital expenditure and access modern scaffolding solutions, expanding the market among cost-sensitive buyers.
Adoption of Modular and Digital Scaffolding Solutions
The shift toward modular scaffolding systems and digital monitoring technologies enables faster assembly, improved safety, and better project efficiency, attracting both large and small contractors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Industrial Scaffolding market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Industrial Scaffolding market projected to grow between 2025 and 2032?
Which Global Industrial Scaffolding market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Industrial Scaffolding market?
Who are the leading companies in the Global Industrial Scaffolding market?
Which region commanded the largest share of the Global Industrial Scaffolding market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Steel
- 1.2.2 Aluminum
- 1.2.3 Fiberglass/Composite Materials
- 1.2.4 Others
- 1.3 By Deployment
- 1.3.1 Fixed Scaffolding
- 1.3.2 Mobile/Rolling Scaffolding
- 1.3.3 Temporary/Rental-Based Scaffolding
- 1.4 By Application
- 1.4.1 Oil & Gas Industry
- 1.4.2 Power Generation (Thermal, Nuclear, Hydro)
- 1.4.3 Mining & Metallurgy
- 1.4.4 Chemical & Petrochemical Plants
- 1.4.5 Others
- 1.5 By Type of Scaffolding
- 1.5.1 Supported Scaffolding
- 1.5.2 Suspended Scaffolding
- 1.5.3 Rolling/Mobile Scaffolding
- 1.5.4 Cantilever Scaffolding
- 1.5.5 System/Modular Scaffolding
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 17,541.0 million → 2032: USD 28,121.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Industrial Scaffolding Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Industrial Scaffolding Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Industrial Scaffolding Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Industrial Scaffolding Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Industrial Scaffolding Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Industrial Scaffolding Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Industrial Scaffolding Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Industrial Scaffolding Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 17,541.0 million → 2032: USD 28,121.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Industrial Scaffolding Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Steel
- 12.3.7.2 Aluminum
- 12.3.7.3 Fiberglass/Composite Materials
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Deployment - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fixed Scaffolding
- 12.4.7.2 Mobile/Rolling Scaffolding
- 12.4.7.3 Temporary/Rental-Based Scaffolding
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oil & Gas Industry
- 12.5.7.2 Power Generation (Thermal, Nuclear, Hydro)
- 12.5.7.3 Mining & Metallurgy
- 12.5.7.4 Chemical & Petrochemical Plants
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Type of Scaffolding - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Volume Forecast, 2018-2032
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Supported Scaffolding
- 12.6.7.2 Suspended Scaffolding
- 12.6.7.3 Rolling/Mobile Scaffolding
- 12.6.7.4 Cantilever Scaffolding
- 12.6.7.5 System/Modular Scaffolding
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Industrial Scaffolding End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Industrial Scaffolding Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Industrial Scaffolding Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Industrial Scaffolding Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 PERI GmbH
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Layher Holding GmbH & Co. KG
- 18.4 BrandSafway
- 18.5 ULMA Construction
- 18.6 Altrad Group
- 18.7 Waco International
- 18.8 Tata Projects
- 18.9 Lindner Group
- 18.10 Interserve (Tilbury Douglas)
- 18.11 Devco
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

