
Market Overview:
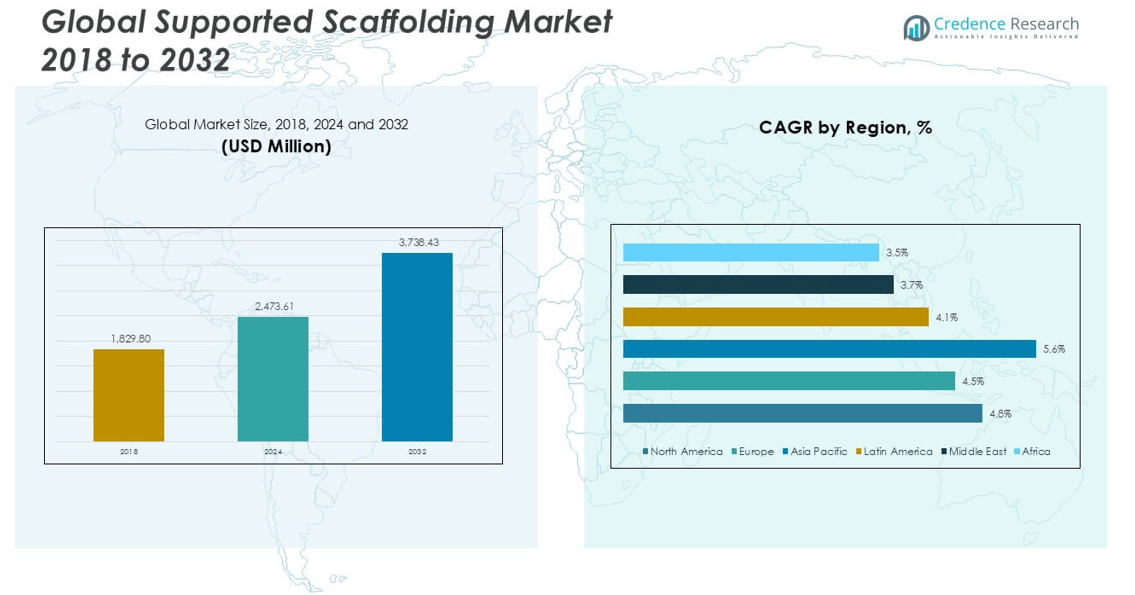
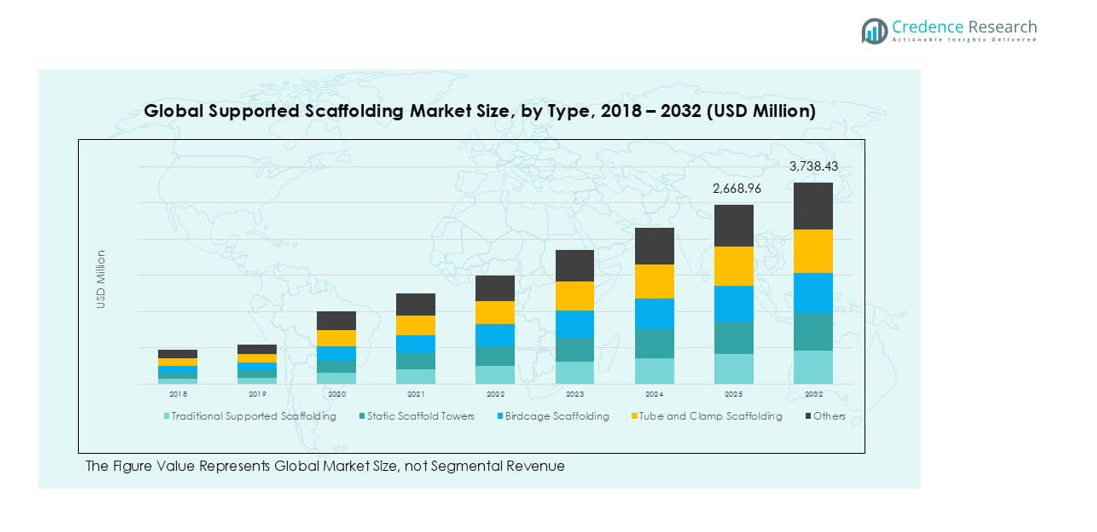
The Supported Scaffolding market size was valued at USD 1,829.80 million in 2018 and grew to USD 2,473.61 million in 2024. It is anticipated to reach USD 3,738.43 million by 2032, at a CAGR of 4.93% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Supported Scaffolding Market Size 2024 | USD 2,473.61 million |
| Supported Scaffolding Market, CAGR | 4.93% |
| Supported Scaffolding Market Size 2032 | USD 3,738.43 million |
The supported scaffolding market is led by key players such as Wellmade Scaffold Co. Ltd., Rapid Scaffolding (Engineering) Co. Ltd., Waco Kwikform Ltd., Turbo Scaffolding, and SB Scaffolding India Pvt. Ltd., all of which compete through product innovation, modular system offerings, and expansion into high-growth regions. These companies prioritize safety compliance, operational efficiency, and cost-effective solutions to strengthen their market positions. Regionally, Asia Pacific dominates the global market, accounting for 45.5% of the total share in 2024, driven by rapid urbanization, large-scale infrastructure development, and industrial expansion in countries such as China and India.
Market Insights
- The supported scaffolding market was valued at USD 2,473.61 million in 2024 and is projected to reach USD 3,738.43 million by 2032, growing at a CAGR of 4.93% during the forecast period.
- Growing construction activity across residential, commercial, and infrastructure sectors is driving market demand, particularly in developing economies where rapid urbanization is underway.
- Modular and lightweight scaffolding systems are gaining popularity due to ease of assembly and improved worker safety, while rental-based scaffolding services offer cost-effective and flexible solutions.
- Key players such as Wellmade Scaffold Co. Ltd., Waco Kwikform Ltd., and Rapid Scaffolding are expanding product lines and focusing on safety compliance and project-specific customization to remain competitive.
- Asia Pacific leads with a 45.5% market share in 2024, followed by North America at 28.2%; construction applications dominate usage, while steel scaffolding holds the highest segment share due to strength and durability.
Market Segmentation Analysis:
By Type
Traditional Supported Scaffolding dominates the type segment, accounting for the largest market share in 2024 due to its widespread use in residential and commercial construction projects. Its robust load-bearing capacity and cost-efficiency make it a preferred choice for various structural applications. Static scaffold towers and birdcage scaffolding are gaining traction in indoor and maintenance tasks, especially in industrial and institutional setups. Tube and clamp scaffolding, known for its flexibility in complex structures, serves niche requirements. The “Others” category includes emerging modular designs and hybrid systems tailored for specialized construction and maintenance operations.
- For instance, Wellmade Scaffold Co. Ltd. manufactures traditional frame scaffolding with a load capacity of 1,500 kg per frame set and exports over 200,000 frame units annually to over 55 countries.
By Material:
Steel supported scaffolding leads the material segment with the highest market share, driven by its superior strength, durability, and load-bearing capacity, making it ideal for heavy-duty construction. It is extensively used in high-rise building projects and infrastructure development. Aluminum scaffolding, valued for its lightweight nature and corrosion resistance, follows closely and finds widespread use in electrical and mechanical installations where mobility is essential. Bamboo and wood scaffolding, while declining in usage globally, continues to serve in traditional or low-budget construction across some developing regions due to its low cost and easy availability.
- For instance, Rapid Scaffolding (Engineering) Co. Ltd. produces hot-dip galvanized steel scaffolding with tensile strength exceeding 510 MPa and a tested load-bearing capacity of 24.5 kN per leg in their ringlock system.
By Application:
Construction remains the dominant application segment, holding the largest market share in 2024, fueled by continuous global urbanization, infrastructure expansion, and large-scale commercial real estate development. The demand for high safety standards and operational efficiency drives the use of supported scaffolding in this segment. Maintenance and repairs represent a growing share, particularly in aging infrastructure across developed economies. Shipbuilding and marine maintenance rely on scaffolding for dry-dock repairs and hull access. Electrical and mechanical trades increasingly use mobile supported scaffolds for installations. The “Others” category includes niche applications such as event staging and film set construction.
Market Overview
Rapid Urbanization and Infrastructure Development
The global rise in urbanization, particularly across Asia-Pacific and the Middle East, is driving demand for new residential, commercial, and infrastructure projects. Governments are heavily investing in public infrastructure, including bridges, highways, and high-rise buildings, requiring extensive use of supported scaffolding systems. The scalability and reliability of supported scaffolding make it an essential component in these projects, reinforcing its market growth. This ongoing urban expansion fosters long-term demand for both traditional and modern scaffolding solutions.
- For instance, Turbo Scaffolding supplied over 5,000 tons of heavy-duty scaffolding materials for metro rail and bridge development projects in Sydney between 2021 and 2023, supporting high-volume infrastructure execution.
Stringent Safety Regulations in Construction
Increasing enforcement of occupational safety standards and building codes across developed and developing countries is boosting the adoption of supported scaffolding. Regulatory bodies such as OSHA and their global counterparts are mandating safer work environments, leading construction companies to invest in high-quality, secure scaffolding systems. Supported scaffolding offers stable platforms for workers, reducing the risk of falls and structural failures. This regulatory pressure encourages the replacement of outdated systems with certified, modern supported scaffolding, thereby fueling market growth.
- For instance, Waco Kwikform introduced the "Kwikstage Advance" system with built-in toe boards and integrated access gates that comply with AS/NZS 1576 safety standards and have been deployed across 1,200+ commercial projects in Australia.
Technological Advancements and Modular Design Adoption
Innovations in modular scaffolding designs and the integration of lightweight, corrosion-resistant materials are significantly enhancing product efficiency and adaptability. These advancements allow faster assembly, disassembly, and greater customization for complex architectural requirements. The growing preference for prefabricated and easy-to-install scaffolding systems improves construction productivity and reduces labor costs. As construction projects become more design-intensive, the demand for innovative supported scaffolding solutions is expected to accelerate, offering manufacturers and suppliers opportunities for product differentiation.
Key Trends & Opportunities
Rising Demand from Industrial Maintenance Activities
There is an increasing need for scaffolding in industrial maintenance and repair applications, including in oil & gas, power generation, and manufacturing plants. Facilities with tall structures and complex machinery require reliable access solutions for routine inspection, cleaning, and servicing. Supported scaffolding provides a safe and flexible platform for such operations. This trend is expected to create steady, non-cyclical revenue streams for scaffolding providers beyond traditional construction projects, especially in developed markets with aging infrastructure.
- For instance, Instant Upright Ltd. supplied over 7,500 customized aluminum scaffolding towers to power generation and maintenance companies across Europe between 2020 and 2023 for turbine inspections and maintenance access.
Shift Towards Rental-Based Scaffolding Services
The market is witnessing a growing preference for renting over purchasing scaffolding systems, particularly among small to mid-sized contractors and temporary project operators. This shift is driven by cost-efficiency, flexibility, and the desire to avoid long-term storage and maintenance. Rental companies offering full-service packages, including installation and dismantling, are gaining prominence. This model presents a lucrative opportunity for service-based scaffolding businesses to scale their operations and build long-term client relationships across multiple industries.
- For instance, Entrepose Echafaudages operates a rental fleet of over 600,000 m² of scaffolding equipment across France and handled more than 2,000 rental contracts in 2023, including for refinery shutdowns and public infrastructure repairs.
Key Challenges
High Initial Setup and Maintenance Costs
Despite their durability and performance, supported scaffolding systems-especially steel and modular designs-require significant upfront investment. Small contractors and firms operating on tight budgets may find these costs prohibitive. In addition to the purchase, ongoing inspection, repair, and storage costs further burden the end users. These financial constraints can hinder the widespread adoption of modern supported scaffolding, particularly in emerging markets where cost sensitivity remains high.
Labor Shortages and Skill Gaps
The safe and effective use of supported scaffolding requires trained labor, especially during assembly and dismantling processes. However, the construction industry faces a growing shortage of skilled workers globally. This labor gap raises concerns about safety and efficiency at project sites. Delays in project timelines due to a lack of competent workers can reduce contractors’ willingness to adopt more sophisticated scaffolding systems, limiting market growth in both developed and developing regions.
Volatile Raw Material Prices
Fluctuations in the prices of raw materials such as steel and aluminum significantly impact the production costs of supported scaffolding. These materials form the backbone of most scaffolding systems, and price volatility-often influenced by geopolitical instability, trade regulations, or supply chain disruptions-poses a major challenge to manufacturers. This unpredictability can lead to higher end-user prices or squeezed profit margins, affecting the competitiveness and scalability of scaffolding products globally.
Regional Analysis
North America:
North America held a significant share of approximately 28.2% of the global supported scaffolding market in 2024, with a market size of USD 697.08 million, up from USD 523.95 million in 2018. The region is projected to reach USD 1,058.00 million by 2032, expanding at a CAGR of 5.0%. This growth is driven by robust demand in commercial construction, infrastructure renovation, and strict adherence to safety standards. The U.S. leads the regional market, supported by ongoing public and private investment in high-rise buildings, bridge repair, and industrial maintenance projects.
Europe:
Europe accounted for approximately 18.2% of the global market in 2024, with a market value of USD 450.75 million, rising from USD 352.15 million in 2018. The market is expected to grow to USD 621.41 million by 2032, registering a CAGR of 3.7%. Growth in this region is primarily fueled by regulatory compliance, historical building restoration projects, and increased focus on worker safety. Countries like Germany, the UK, and France dominate the market due to sustained infrastructure investments and demand for modular scaffolding in both urban and industrial environments.
Asia Pacific:
Asia Pacific emerged as the dominant regional market with the largest share of around 45.5% in 2024, reaching a value of USD 1,124.47 million, significantly up from USD 802.28 million in 2018. The market is projected to grow at the fastest CAGR of 5.7%, reaching USD 1,802.77 million by 2032. The region’s rapid urbanization, booming construction sector, and increasing industrial projects in China, India, and Southeast Asia are key growth drivers. Government-led infrastructure initiatives, along with expansion in real estate development, continue to propel demand for supported scaffolding systems.
Latin America:
Latin America represented approximately 4.4% of the global market in 2024, with a market size of USD 107.96 million, increasing from USD 80.93 million in 2018. It is projected to reach USD 143.12 million by 2032 at a CAGR of 3.2%. The market’s growth is supported by urban housing demand, rising investment in commercial infrastructure, and a gradual improvement in construction safety regulations. Brazil and Mexico remain the primary contributors, with growing adoption of cost-effective scaffolding solutions to support medium-scale infrastructure and industrial development.
Middle East:
The Middle East accounted for approximately 2.1% of the global supported scaffolding market in 2024, valued at USD 52.33 million, up from USD 43.11 million in 2018. It is projected to grow moderately to USD 64.13 million by 2032, at a CAGR of 2.2%. The market is driven by oil and gas infrastructure maintenance, urban construction in Gulf Cooperation Council (GCC) countries, and preparation for global events such as Expo 2020 legacy projects. However, the regional market faces challenges related to economic diversification and geopolitical instability.
Africa:
Africa contributed about 1.7% of the global market in 2024, with a value of USD 41.04 million, rising from USD 27.39 million in 2018. The market is anticipated to reach USD 49.01 million by 2032, growing at a CAGR of 1.8%. Market expansion in the region remains gradual due to limited infrastructure budgets and inconsistent enforcement of safety standards. However, increasing urban population, government-backed construction initiatives, and international funding for housing and transport development are slowly stimulating demand for supported scaffolding systems across select African economies such as South Africa, Nigeria, and Kenya.
Market Segmentations:
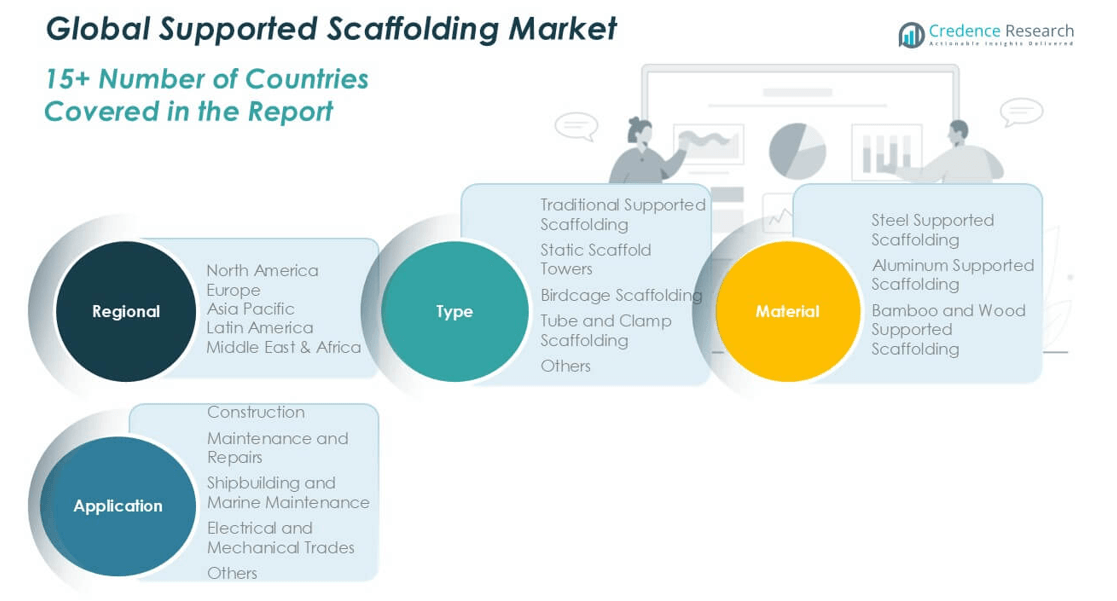
By Type:
- Traditional Supported Scaffolding
- Static Scaffold Towers
- Birdcage Scaffolding
- Tube and Clamp Scaffolding
- Others
By Material:
- Steel Supported Scaffolding
- Aluminum Supported Scaffolding
- Bamboo and Wood Supported Scaffolding
By Application:
- Construction
- Maintenance and Repairs
- Shipbuilding and Marine Maintenance
- Electrical and Mechanical Trades
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The supported scaffolding market features a moderately fragmented competitive landscape, with a mix of global players and regional manufacturers competing on product quality, pricing, and service offerings. Leading companies such as Wellmade Scaffold Co. Ltd., Rapid Scaffolding (Engineering) Co. Ltd., and Waco Kwikform Ltd. focus on expanding their product portfolios through innovation and modular design enhancements. Regional players like SB Scaffolding India Pvt. Ltd. and Turbo Scaffolding cater to local construction needs with cost-effective and customizable solutions. Strategic partnerships, joint ventures, and expansion into emerging markets are common growth strategies among key participants. Companies are also investing in rental services and digital project management tools to strengthen their competitive edge. The emphasis on compliance with international safety standards and sustainable manufacturing practices further shapes competition. Overall, the market remains dynamic, with ongoing advancements and a growing focus on value-added services offering new opportunities for differentiation and long-term growth.
Key Player Analysis
- Wellmade Scaffold Co. Ltd.
- Universal Building Supply Inc.
- BS L Scaffolding Ltd.
- Changli XMWY Formwork Scaffolding Co. Ltd.
- SB Scaffolding India Pvt. Ltd.
- Rapid Scaffolding (Engineering) Co. Ltd.
- Entrepose Echafaudages
- Instant Upright Ltd.
- Devco Australia
- Turbo Scaffolding
- Pacific Scaffold Pte Ltd.
- Waco Kwikform Ltd.
Recent Developments
- In July 2022,StepUp Scaffold UK, a Glasgow-based subsidiary of the StepUp Scaffold Group in Memphis (US), which offers scaffolding and access equipment in the UK market, has finalized the acquisition of MP House ApS, which is located just outside Copenhagen. MP House is a market leader in the supply of tools, equipment, and accessories to Danish scaffolding operators.
- In July 2022,Doka, a provider of formwork, solutions, and services to the construction industry, has reinforced its existing partnership with renowned American scaffolding manufacturer AT-PAC by acquiring a significant investment in the US-based company. Doka and AT-PAC developed an initial relationship in 2020 to provide comprehensive building site solutions, and the partnership has been increasing ever since.
Market Concentration & Characteristics
The Supported Scaffolding Market exhibits a moderately fragmented structure, characterized by the presence of both global manufacturers and regional suppliers competing across price, quality, and service reliability. It shows a high degree of regional concentration, with Asia Pacific accounting for the largest share due to extensive infrastructure development, strong construction demand, and favorable government policies in emerging economies. The market benefits from consistent demand across residential, commercial, and industrial applications, supported by regulatory compliance and rising safety standards. Leading players focus on offering modular, durable, and easy-to-install systems to meet evolving project needs. It continues to see strong activity in the rental and maintenance segments, especially in mature construction markets. Cost-efficiency, product customization, and on-site technical support remain key competitive differentiators. Manufacturers aim to expand through strategic partnerships and distribution networks to strengthen their global footprint. It demonstrates steady growth potential, driven by construction cycles, labor safety regulations, and demand for time-efficient project solutions.
Report Coverage
The research report offers an in-depth analysis based on Type, Material, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness steady growth driven by rising construction activity across urban infrastructure and commercial projects.
- Demand for modular and easy-to-assemble scaffolding systems will increase due to the need for faster project execution.
- Steel scaffolding will remain the dominant material type due to its strength, durability, and compatibility with large structures.
- Asia Pacific will continue to lead the market, supported by rapid urbanization and government investment in infrastructure.
- Rental-based scaffolding services will gain traction among small and medium contractors seeking cost-effective solutions.
- Regulatory focus on worker safety will push adoption of certified and compliant scaffolding systems.
- Manufacturers will expand product portfolios with lightweight materials like aluminum for specialized applications.
- Technological integration, including digital site monitoring and scaffolding design software, will support operational efficiency.
- Emerging markets in Latin America and Africa will create new opportunities through public housing and transport projects.
- Market competition will intensify as regional players invest in capacity expansion and distribution partnerships.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Urbanization and Infrastructure Development
Accelerated urban growth, especially in Asia Pacific and the Middle East, is fueling demand for new residential, commercial, and infrastructure projects, all of which require extensive use of supported scaffolding systems for safe and efficient construction.
Stringent Safety Regulations in Construction
Increasing enforcement of occupational safety standards and building codes globally is compelling construction companies to invest in certified, high-quality supported scaffolding, driving replacement of outdated systems and boosting market growth.
Technological Advancements and Modular Design Adoption
Innovations in modular scaffolding and the use of lightweight, corrosion-resistant materials are making scaffolding systems faster to assemble, more adaptable, and safer, which increases their adoption across complex and large-scale projects.
Growth in Rental-Based Scaffolding Services
The shift toward renting scaffolding systems, particularly among small and mid-sized contractors, is making supported scaffolding more accessible and cost-effective, expanding the market to a broader customer base.
Expansion of Industrial Maintenance Activities
Rising maintenance and repair needs in sectors such as oil & gas, power generation, and manufacturing are creating steady demand for supported scaffolding, providing non-cyclical revenue streams beyond traditional construction.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Supported Scaffolding, and what is its projected size in 2032?
Which Supported Scaffolding market segment held the largest share in 2024?
Who are the leading companies in the Supported Scaffolding market?
Which region commanded the largest share of the Supported Scaffolding market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Traditional Supported Scaffolding
- 1.2.2 Static Scaffold Towers
- 1.2.3 Birdcage Scaffolding
- 1.2.4 Tube and Clamp Scaffolding
- 1.2.5 Others
- 1.3 By Material
- 1.3.1 Steel Supported Scaffolding
- 1.3.2 Aluminum Supported Scaffolding
- 1.3.3 Bamboo and Wood Supported Scaffolding
- 1.4 By Application
- 1.4.1 Construction
- 1.4.2 Maintenance and Repairs
- 1.4.3 Shipbuilding and Marine Maintenance
- 1.4.4 Electrical and Mechanical Trades
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,473.61 million → 2032: USD 3,738.43 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Supported Scaffolding Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Supported Scaffolding Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Supported Scaffolding Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Supported Scaffolding Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Supported Scaffolding Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Supported Scaffolding Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Supported Scaffolding Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Supported Scaffolding Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,473.61 million → 2032: USD 3,738.43 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Supported Scaffolding Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Traditional Supported Scaffolding
- 12.3.7.2 Static Scaffold Towers
- 12.3.7.3 Birdcage Scaffolding
- 12.3.7.4 Tube and Clamp Scaffolding
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Steel Supported Scaffolding
- 12.4.7.2 Aluminum Supported Scaffolding
- 12.4.7.3 Bamboo and Wood Supported Scaffolding
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Construction
- 12.5.7.2 Maintenance and Repairs
- 12.5.7.3 Shipbuilding and Marine Maintenance
- 12.5.7.4 Electrical and Mechanical Trades
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Supported Scaffolding End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Supported Scaffolding Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Supported Scaffolding Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Supported Scaffolding Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Wellmade Scaffold Co. Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Rapid Scaffolding (Engineering) Co. Ltd.
- 18.4 Waco Kwikform Ltd.
- 18.5 Turbo Scaffolding
- 18.6 SB Scaffolding India Pvt. Ltd.
- 18.7 Entrepose Echafaudages
- 18.8 Instant Upright Ltd.
- 18.9 Universal Building Supply Inc.
- 18.10 Changli XMWY Formwork Scaffolding Co. Ltd.
- 18.11 BS L Scaffolding Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

