
Market Overview:
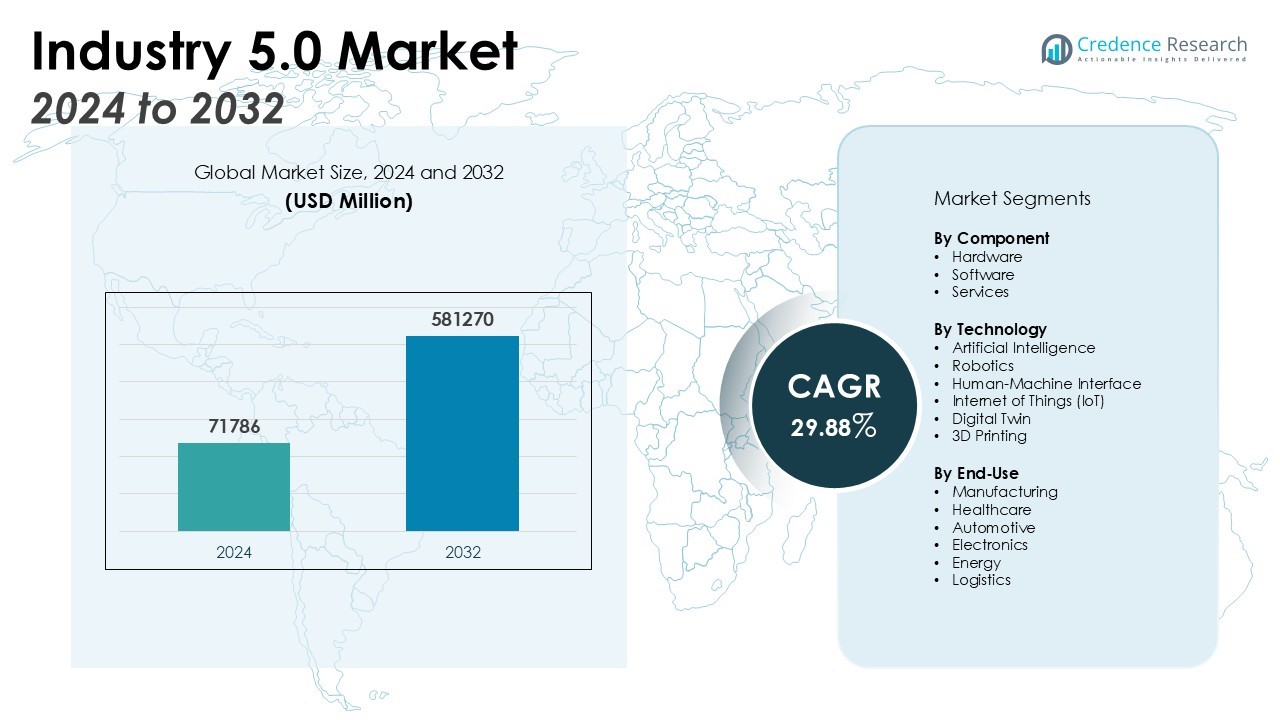
The Industry 5.0 Market size was valued at USD 71786 million in 2024 and is anticipated to reach USD 581270 million by 2032, at a CAGR of 29.88% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Industry 5.0 Market Size 2024 | USD 71786 Million |
| Industry 5.0 Market, CAGR | 29.88% |
| Industry 5.0 Market Size 2032 | USD 581270 Million |
Key drivers include rising demand for enhanced productivity, operational efficiency, and resilient supply chains. The shift toward sustainable manufacturing and the need to upskill workforces are prompting organizations to invest in human-machine collaboration and cognitive automation. Companies are leveraging data analytics, predictive maintenance, and smart sensors to minimize downtime and maximize resource utilization. The push for mass customization and flexible manufacturing further accelerates the adoption of Industry 5.0 frameworks. Heightened focus on workforce safety and adaptive manufacturing environments is also catalyzing investments in next-generation technologies.
Regionally, Europe leads the Industry 5.0 Market, supported by strong policy frameworks and investments in smart manufacturing. North America follows, driven by technological innovation and a robust industrial base. The Asia Pacific region is rapidly emerging, fueled by expanding industrial infrastructure and growing digital transformation initiatives. Strategic government incentives and growing collaboration between public and private sectors in these regions are further strengthening market momentum.
Market Insights:
- The Industry 5.0 Market reached USD 71,786 million in 2024 and is projected to achieve USD 581,270 million by 2032, reflecting robust long-term growth.
- Strong demand for productivity, efficiency, and supply chain resilience fuels widespread adoption of human-machine collaboration.
- Companies invest in sustainable manufacturing, integrating IoT, data analytics, and predictive maintenance to support green operations and compliance.
- Workforce upskilling and development of advanced digital skills remain central to successful Industry 5.0 deployment across sectors.
- Integration complexity, high initial costs, and cybersecurity risks present persistent challenges for companies modernizing legacy systems.
- Europe leads the market with 38% share due to regulatory support, R&D funding, and early adoption of collaborative robotics.
- North America and Asia Pacific contribute significant momentum, driven by technological innovation, skilled labor, and expanding industrial infrastructure.
Market Drivers:
Integration of Human-Centric Automation and Robotics Drives Innovation
The Industry 5.0 Market is advancing rapidly due to the convergence of human-centric automation and next-generation robotics. By enabling seamless collaboration between humans and machines, businesses achieve greater efficiency, adaptability, and product customization. Collaborative robots (cobots) empower operators to manage complex tasks while retaining creative control, supporting the transition from mass production to mass personalization. This synergy not only streamlines manufacturing but also enhances workplace safety and innovation, strengthening competitive positioning in evolving global markets.
Sustainable Manufacturing and Resource Efficiency Remain Core Priorities
Sustainability is a powerful driver within the Industry 5.0 Market, prompting organizations to integrate green manufacturing processes and adopt circular economy models. Real-time monitoring through IoT sensors and data analytics helps companies reduce energy consumption, cut waste, and comply with environmental standards. Predictive maintenance tools extend equipment life and minimize operational disruptions. These sustainable practices align with growing regulatory pressures and consumer demand for eco-friendly products, making them central to long-term market growth.
- For instance, Toyota, through a partnership with The Nature Conservancy, released 158million gallons of water to the Hardy River in 2023 to support restoration of the Colorado River Delta ecosystem.
Workforce Upskilling and Collaborative Solutions Enhance Value Creation
The shift to Industry 5.0 elevates the importance of workforce skills in leveraging new technologies. Organizations invest in upskilling employees in robotics, AI, and digital management tools, fostering continuous learning and adaptability. Human-machine collaboration requires proficiency in data-driven processes and creative problem-solving, maximizing the return on technology investments. This focus on workforce development ensures a smooth transition toward more automated and intelligent production environments.
- For instance, Siemens has launched the SiTecSkills Academy with 19 regional training centers across Germany, offering certified technical upskilling programs in digitalization for both internal and external partners, directly addressing current demand for workforce readiness in advanced manufacturing.
Need for Resilient, Flexible Supply Chains Accelerates Technology Adoption
Disruptions in global supply chains highlight the need for resilience and flexibility, driving adoption of advanced technologies in the Industry 5.0 Market. Companies utilize digital twins, AI-based analytics, and blockchain to improve supply chain transparency and responsiveness. Real-time data supports agile decision-making, helping organizations quickly adapt to market changes and maintain operational stability. This technological integration ensures sustainable growth and a strong market presence.
Market Trends:
Human-Robot Collaboration and Personalization Set New Benchmarks
The Industry 5.0 Market is defined by the rise of collaborative robots working alongside human operators to deliver personalized, high-value products. Companies invest in human-centric automation solutions to merge creative input with robotic precision, moving beyond traditional mass production models. The trend toward mass customization shapes new product development cycles, supporting smaller batch sizes and unique consumer requirements. Flexible manufacturing lines are being reconfigured to quickly adapt to rapid shifts in demand, leveraging advanced robotics and AI-driven systems. Manufacturers are using digital twins to simulate and optimize production environments, resulting in improved efficiency and responsiveness. This human-robot synergy elevates product quality, reduces errors, and ensures competitive agility in dynamic markets.
- For instance, Universal Robots has deployed over 100,000 collaborative robots globally in manufacturing environments.
Sustainable Manufacturing and Data-Driven Decision-Making Gain Momentum
Sustainability and data intelligence are prominent trends in the Industry 5.0 Market, driving investments in smart factories and circular production models. Companies deploy IoT devices, predictive maintenance platforms, and energy management solutions to minimize resource consumption and meet stringent environmental regulations. Real-time analytics enable firms to optimize operations, reduce downtime, and improve traceability across supply chains. Adoption of circular economy practices, such as recycling and closed-loop systems, supports waste reduction and responsible material usage. The integration of cloud and edge computing ensures seamless data flow and accelerated decision-making. These trends reflect the industry’s commitment to environmental stewardship and operational excellence, reinforcing Industry 5.0’s transformative impact.
- For instance, Siemens’ smart factory solutions at the Amberg Electronics Plant have enabled a reduction in production error rates to just 11.5 defects per million produced units.
Market Challenges Analysis:
Integration Complexity and High Initial Costs Impede Widespread Adoption
The Industry 5.0 Market faces challenges related to integrating advanced technologies with legacy systems, which makes seamless implementation difficult for many organizations. High upfront investment in robotics, AI, and IoT infrastructure often limits adoption among small and medium enterprises. Companies must address compatibility issues between new digital platforms and existing production lines, requiring specialized expertise and technical support. The risk of operational disruptions during the transition phase can deter some businesses from rapid modernization. Long ROI periods and budget constraints further compound these hurdles. Overcoming these obstacles is essential for organizations to unlock the full benefits of transformation.
Cybersecurity Risks and Workforce Adaptation Present Ongoing Concerns
Cybersecurity remains a critical challenge, given the increased connectivity of industrial assets and real-time data sharing within the Industry 5.0 Market. Vulnerabilities in connected systems can expose companies to data breaches, intellectual property theft, and operational sabotage. The growing reliance on digital tools requires robust security protocols and continuous monitoring. Workforce adaptation also poses a challenge, as employees must acquire new technical skills and embrace digital transformation. Resistance to change and skill gaps can slow down implementation and limit the effectiveness of human-machine collaboration. Organizations must prioritize cybersecurity and targeted upskilling to sustain progress.
Market Opportunities:
Expansion into Emerging Economies Unlocks Significant Growth Potential
The Industry 5.0 Market holds strong opportunities in emerging economies, where rapid industrialization and government initiatives support smart manufacturing. Businesses can tap into expanding sectors such as automotive, electronics, and healthcare to implement advanced solutions. The availability of cost-effective labor, combined with investments in infrastructure, creates favorable conditions for large-scale adoption. Companies can collaborate with local technology providers and research institutions to accelerate deployment and localization of new technologies. Rising consumer demand for personalized products drives further market penetration. Increased digital transformation across these high-growth regions is set to accelerate future adoption.
Innovation in Sustainable and Personalized Manufacturing Drives New Revenue Streams
The focus on sustainable manufacturing and personalized production offers companies the chance to create differentiated value propositions. The Industry 5.0 Market encourages development of environmentally friendly solutions, such as green robotics and closed-loop production systems. Businesses that invest in circular economy practices can reduce costs, comply with regulations, and appeal to eco-conscious consumers. Advances in AI and digital twins enable mass customization while maintaining efficiency. It creates opportunities for new service models and revenue streams, positioning organizations as leaders in next-generation manufacturing.
Market Segmentation Analysis:
By Component
The Industry 5.0 Market features strong growth across hardware, software, and services. Hardware leads, driven by the widespread adoption of collaborative robots, smart sensors, and advanced industrial IoT devices. Software continues to expand its share, enabling real-time analytics, digital twin management, and robust cybersecurity. Services such as consulting, integration, and ongoing maintenance ensure effective deployment and operational excellence throughout the market.
- For instance, Accenture posted $81.2 billion in new bookings in fiscal year 2024, marking the highest annual new bookings figure in the company's history and underlining robust demand for their digital transformation and integration services.
By Technology
Artificial intelligence and robotics remain at the forefront of the Industry 5.0 Market, powering next-generation automation, precision, and human-machine collaboration. Human-machine interfaces and digital twins enable predictive maintenance, enhanced visualization, and data-driven decision-making. IoT platforms connect devices and systems, supporting seamless information exchange and production optimization. 3D printing technology enhances mass customization and accelerates prototyping across industries.
By End-Use
The Industry 5.0 Market records significant adoption in manufacturing, healthcare, automotive, electronics, energy, and logistics. Manufacturing dominates due to its emphasis on mass customization, sustainability, and operational efficiency. Healthcare utilizes Industry 5.0 for robotics-assisted surgery, smart diagnostics, and personalized patient care. Automotive and electronics sectors integrate intelligent automation to improve product quality and streamline supply chains. The energy and logistics sectors implement Industry 5.0 solutions to strengthen reliability, optimize resources, and enable real-time operational monitoring.
- For instance, at Nadro, employees now use augmented reality glasses integrated with SAP Extended Warehouse Management; this allows real-time order fulfillment instructions and has enabled warehouse employees to pick significantly more items per shift than with previous manual processes.
Segmentations:
By Component
- Hardware
- Software
- Services
By Technology
- Artificial Intelligence
- Robotics
- Human-Machine Interface
- Internet of Things (IoT)
- Digital Twin
- 3D Printing
By End-Use
- Manufacturing
- Healthcare
- Automotive
- Electronics
- Energy
- Logistics
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Europe Maintains Market Leadership
Europe accounts for 38% of the Industry 5.0 Market, securing its leadership through advanced policy frameworks, sustained investment in digital transformation, and a highly developed manufacturing landscape. The region benefits from the European Union’s strategic focus on smart industry, workforce upskilling, and environmental sustainability. Countries such as Germany, France, and the Nordics demonstrate strong uptake of collaborative robotics, IoT, and AI-powered automation. Research funding and robust industry clusters accelerate the pace of technological innovation. Europe’s regulatory focus on circular economy principles and sustainable production further strengthens its market position.
North America Driven by Technological Innovation
North America represents 29% of the Industry 5.0 Market, propelled by continuous technological advancement, a diverse industrial base, and high levels of investment in next-generation manufacturing systems. The United States and Canada lead through integration of AI, robotics, and advanced analytics, optimizing productivity and boosting supply chain resilience. Regional businesses collaborate with technology startups and research organizations to foster innovation and digital adoption. A strong emphasis on workforce readiness and digital skills training supports rapid implementation of Industry 5.0 strategies. North America’s growth is reinforced by significant consumer demand for high-quality, customized products.
Asia Pacific Emerges as a High-Growth Region
Asia Pacific holds 24% of the Industry 5.0 Market, driven by aggressive industrialization, government incentives, and digital transformation across manufacturing sectors. Markets such as China, Japan, South Korea, and India heavily invest in smart manufacturing, automation, and cloud technologies. Local companies focus on building flexible production systems and leveraging real-time data to remain globally competitive. Regional policies encourage adoption of collaborative robotics and sustainable practices, positioning Asia Pacific as a major contributor to future Industry 5.0 growth.
Key Player Analysis:
- Siemens
- ABB
- FANUC CORPORATION
- Yaskawa Electric Corp
- Schneider Electric
- Emerson Electric Co
- Piher Sensing Systems
- Cisco Systems, Inc.
- Honeywell International Inc.
- 3D Systems
- Rockwell Automation
- Stratasys
Competitive Analysis:
The Industry 5.0 Market features a dynamic competitive landscape, with global technology leaders and specialized firms advancing human-machine collaboration and digital transformation. Key players include Siemens AG, ABB Ltd., Fanuc Corporation, KUKA AG, Schneider Electric, Rockwell Automation, and Mitsubishi Electric, each investing in robotics, artificial intelligence, and IoT solutions. These companies focus on product innovation, strategic partnerships, and acquisitions to expand their technological portfolios and market reach. Intense competition drives firms to deliver tailored automation, data analytics, and mass customization capabilities to their clients. Companies emphasize sustainability and workforce empowerment, aligning solutions with needs across manufacturing, healthcare, automotive, and energy sectors. The ongoing drive to integrate next-generation technologies and strengthen value-added services shapes competition in this evolving market.
Recent Developments:
- In June 2025, ABB launched several innovative robotics solutions at Automatica 2025, with a major highlight being the OmniCore™ modular platform, a transformative robotics control architecture designed to integrate AI-driven applications and streamline automation for various industries.
- In May 2025, ABB announced an agreement to acquire BrightLoop, a French firm specializing in power converters for off-highway vehicles and marine electrification.
- In May 2025, Honeywell announced an acquisition agreement for Johnson Matthey's Catalyst Technologies business for £1.8B, to strengthen its catalyst and process technologies portfolio.
Market Concentration & Characteristics:
The Industry 5.0 Market exhibits moderate to high market concentration, with a handful of global technology leaders driving innovation and adoption. It is characterized by rapid technological advancements, a strong focus on human-machine collaboration, and the integration of artificial intelligence, robotics, and IoT across multiple industries. Leading companies leverage extensive R&D capabilities and strategic partnerships to expand their product portfolios and market presence. The market favors solutions that enable mass customization, operational efficiency, and sustainable production. It attracts significant investment from both established players and new entrants, creating a competitive yet innovation-driven environment.
Report Coverage:
The research report offers an in-depth analysis based on Component, Technology, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Industry 5.0 Market will advance collaborative automation by combining human creativity with robotic precision.
- It will deepen human-centric design through adaptive robotics and smart interfaces to enable customized production.
- It will support sustainable practices by integrating circular economy principles and resource-efficient systems.
- It will expand workforce training programs to develop skills in AI, IoT, digital twins, and robotics.
- It will enhance industrial resilience by applying predictive maintenance and real-time operational insights.
- It will foster cross-industry partnerships among integrators, technology providers, and manufacturing enterprises.
- It will enable flexible manufacturing systems capable of mass customization in response to consumer preferences.
- It will accelerate adoption in emerging markets thanks to infrastructure investment and government incentives.
- It will increase demand for cybersecurity solutions to protect interconnected devices and sensitive data.
- It will evolve service-led models offering consulting, system integration, and lifecycle support for clients.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Integration of Human-Centric Automation and Robotics
The convergence of human-centric automation and next-generation robotics enables seamless collaboration between humans and machines, driving efficiency, adaptability, and mass customization in manufacturing and other sectors.
Sustainable Manufacturing and Resource Efficiency
Organizations are increasingly adopting green manufacturing processes, IoT-enabled monitoring, and predictive maintenance to reduce energy consumption, minimize waste, and comply with environmental regulations, fueling market growth.
Workforce Upskilling and Digital Skills Development
The need to upskill employees in robotics, AI, and digital management tools is central to successful Industry 5.0 deployment, ensuring organizations can fully leverage new technologies and maximize return on investment.
Demand for Resilient and Flexible Supply Chains
Disruptions in global supply chains have accelerated the adoption of digital twins, AI-based analytics, and blockchain, enabling real-time data-driven decision-making and operational stability.
Personalization and Mass Customization
The shift from mass production to mass personalization, enabled by collaborative robots and advanced digital technologies, is driving companies to invest in flexible manufacturing systems that can quickly adapt to changing consumer demands.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Industry 5.0 Market?
What factors are driving the growth of the Industry 5.0 Market?
What are the key segments within the Industry 5.0 Market?
What are some challenges faced by the Industry 5.0 Market?
Who are the major players in the Industry 5.0 Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Manufacturing
- 1.2.2 Healthcare
- 1.2.3 Automotive
- 1.2.4 Electronics
- 1.2.5 Energy
- 1.2.6 Logistics
- 1.3 By Component
- 1.3.1 Hardware
- 1.3.2 Software
- 1.3.3 Services
- 1.4 By Technology
- 1.4.1 Artificial Intelligence
- 1.4.2 Robotics
- 1.4.3 Human-Machine Interface
- 1.4.4 Internet of Things (IoT)
- 1.4.5 Digital Twin
- 1.4.6 3D Printing
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 71,786 million → 2032: USD 581,270 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Industry 5.0 Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Industry 5.0 Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Industry 5.0 Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Industry 5.0 Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Industry 5.0 Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Industry 5.0 Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Industry 5.0 Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Industry 5.0 Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 71,786 million → 2032: USD 581,270 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Industry 5.0 Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Manufacturing
- 12.3.7.2 Healthcare
- 12.3.7.3 Automotive
- 12.3.7.4 Electronics
- 12.3.7.5 Energy
- 12.3.7.6 Logistics
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.7.3 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Artificial Intelligence
- 12.5.7.2 Robotics
- 12.5.7.3 Human-Machine Interface
- 12.5.7.4 Internet of Things (IoT)
- 12.5.7.5 Digital Twin
- 12.5.7.6 3D Printing
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Industry 5.0 End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Industry 5.0 Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Industry 5.0 Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Industry 5.0 Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Siemens
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ABB
- 18.4 FANUC CORPORATION
- 18.5 Yaskawa Electric Corp
- 18.6 Schneider Electric
- 18.7 Emerson Electric Co
- 18.8 Cisco Systems, Inc.
- 18.9 Honeywell International Inc.
- 18.10 Rockwell Automation
- 18.11 Stratasys
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

