
Inhalation drugs market shifts toward low-carbon inhalers
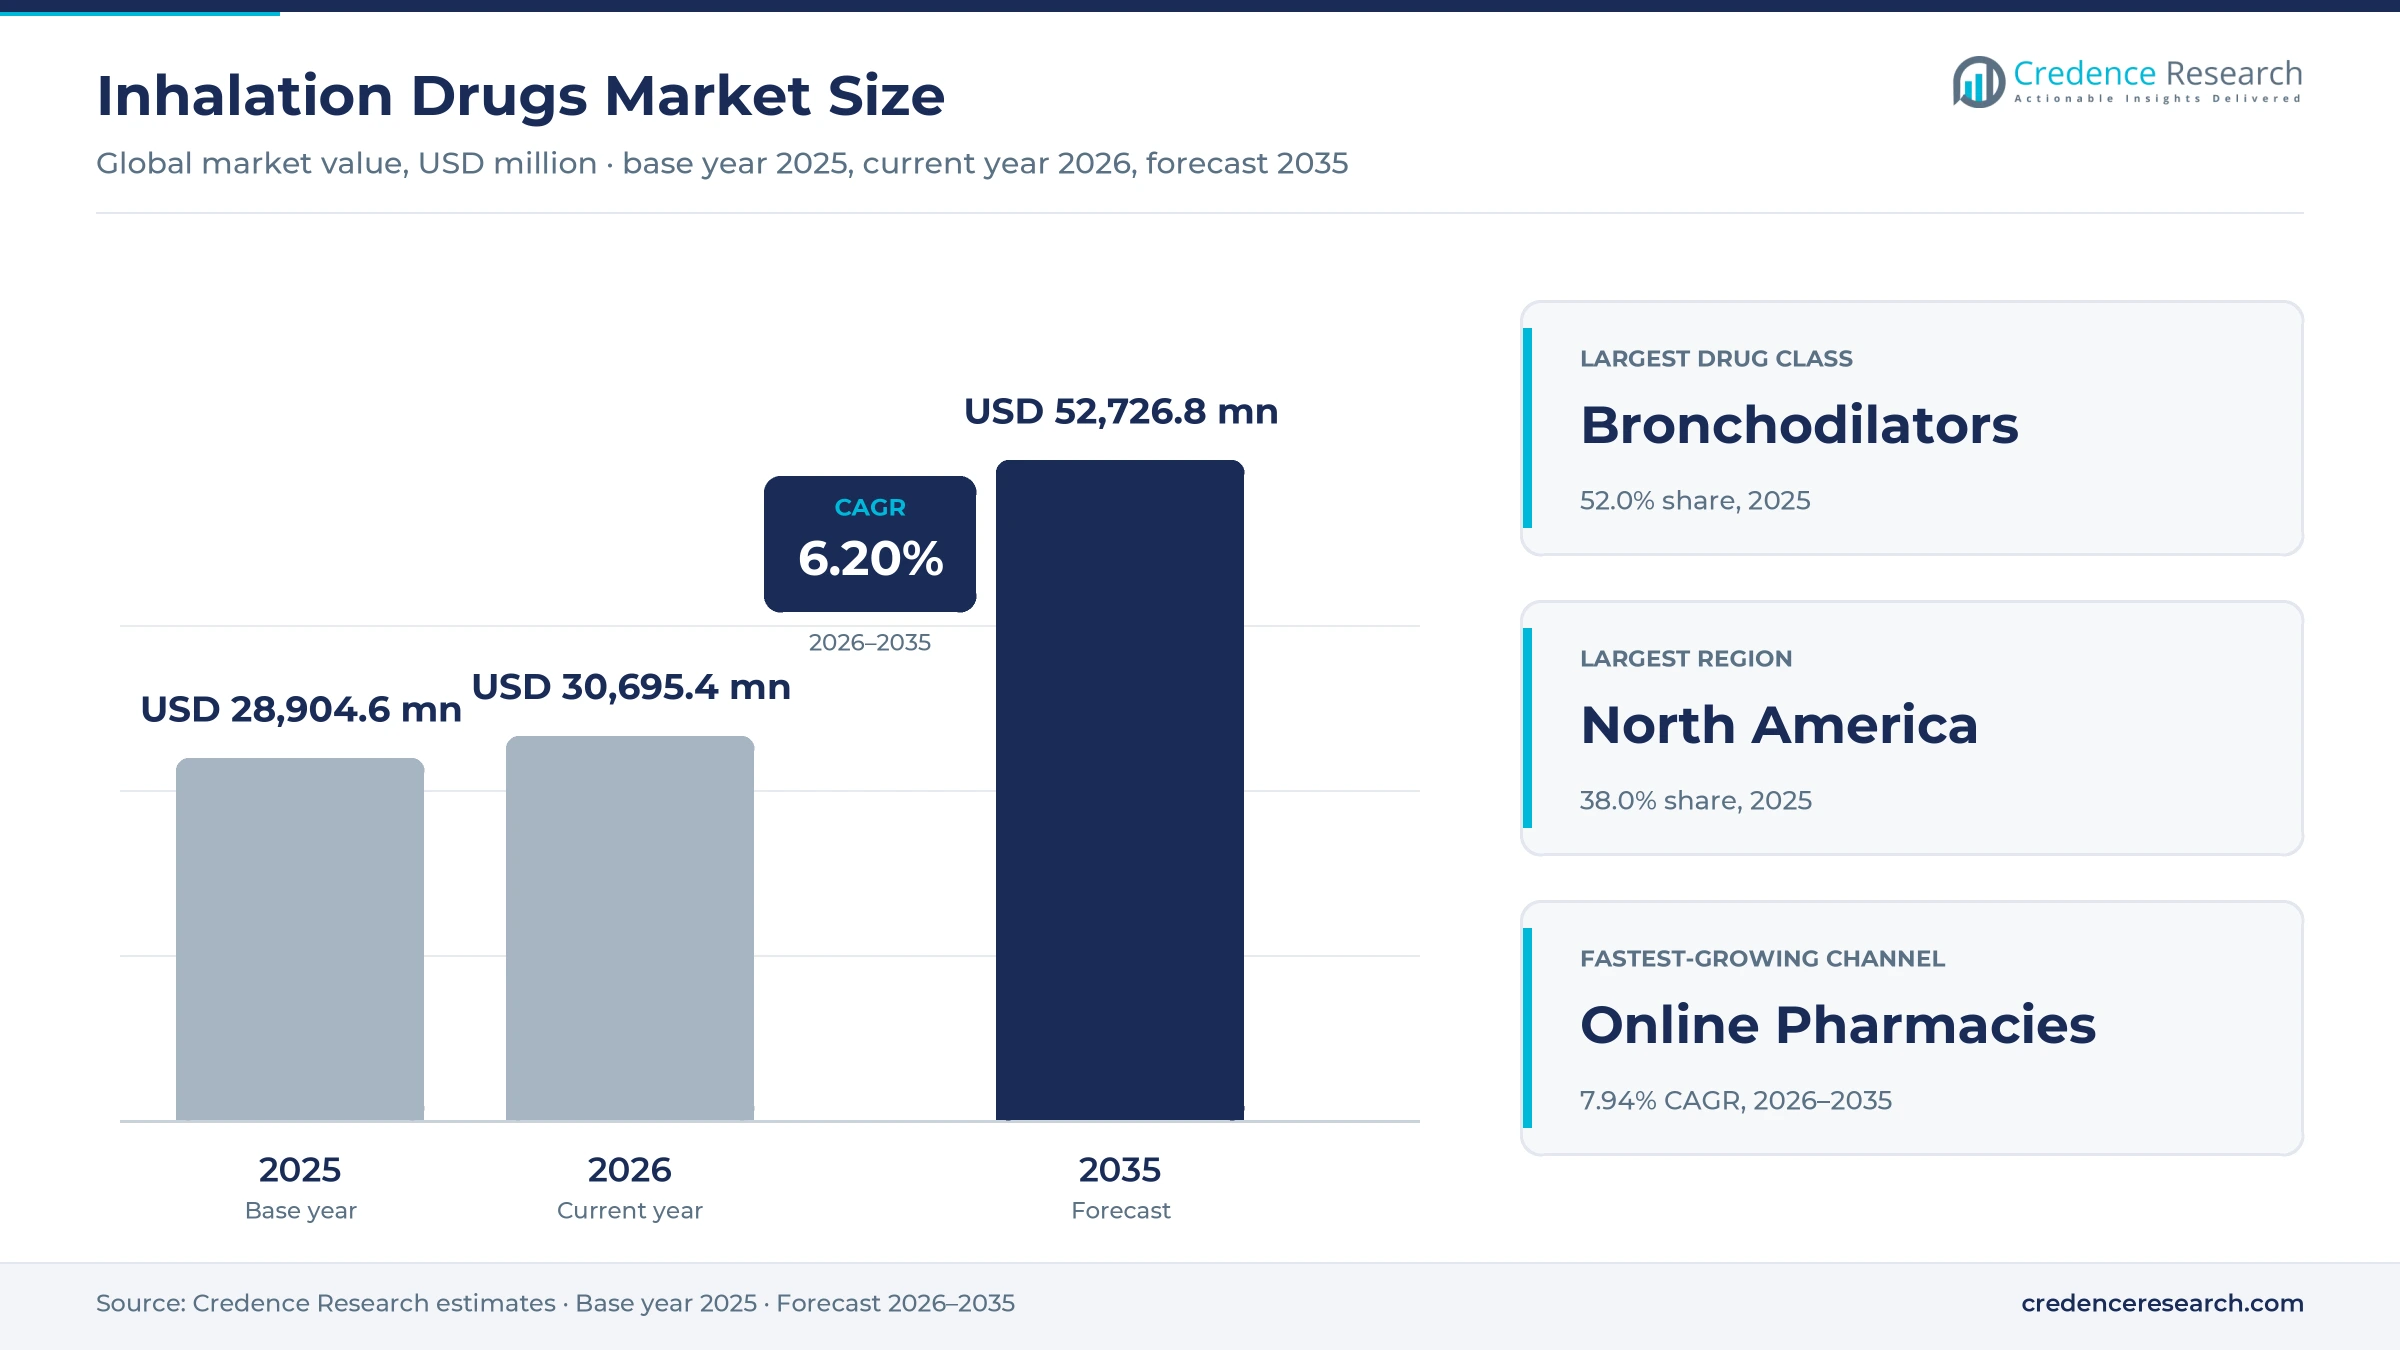
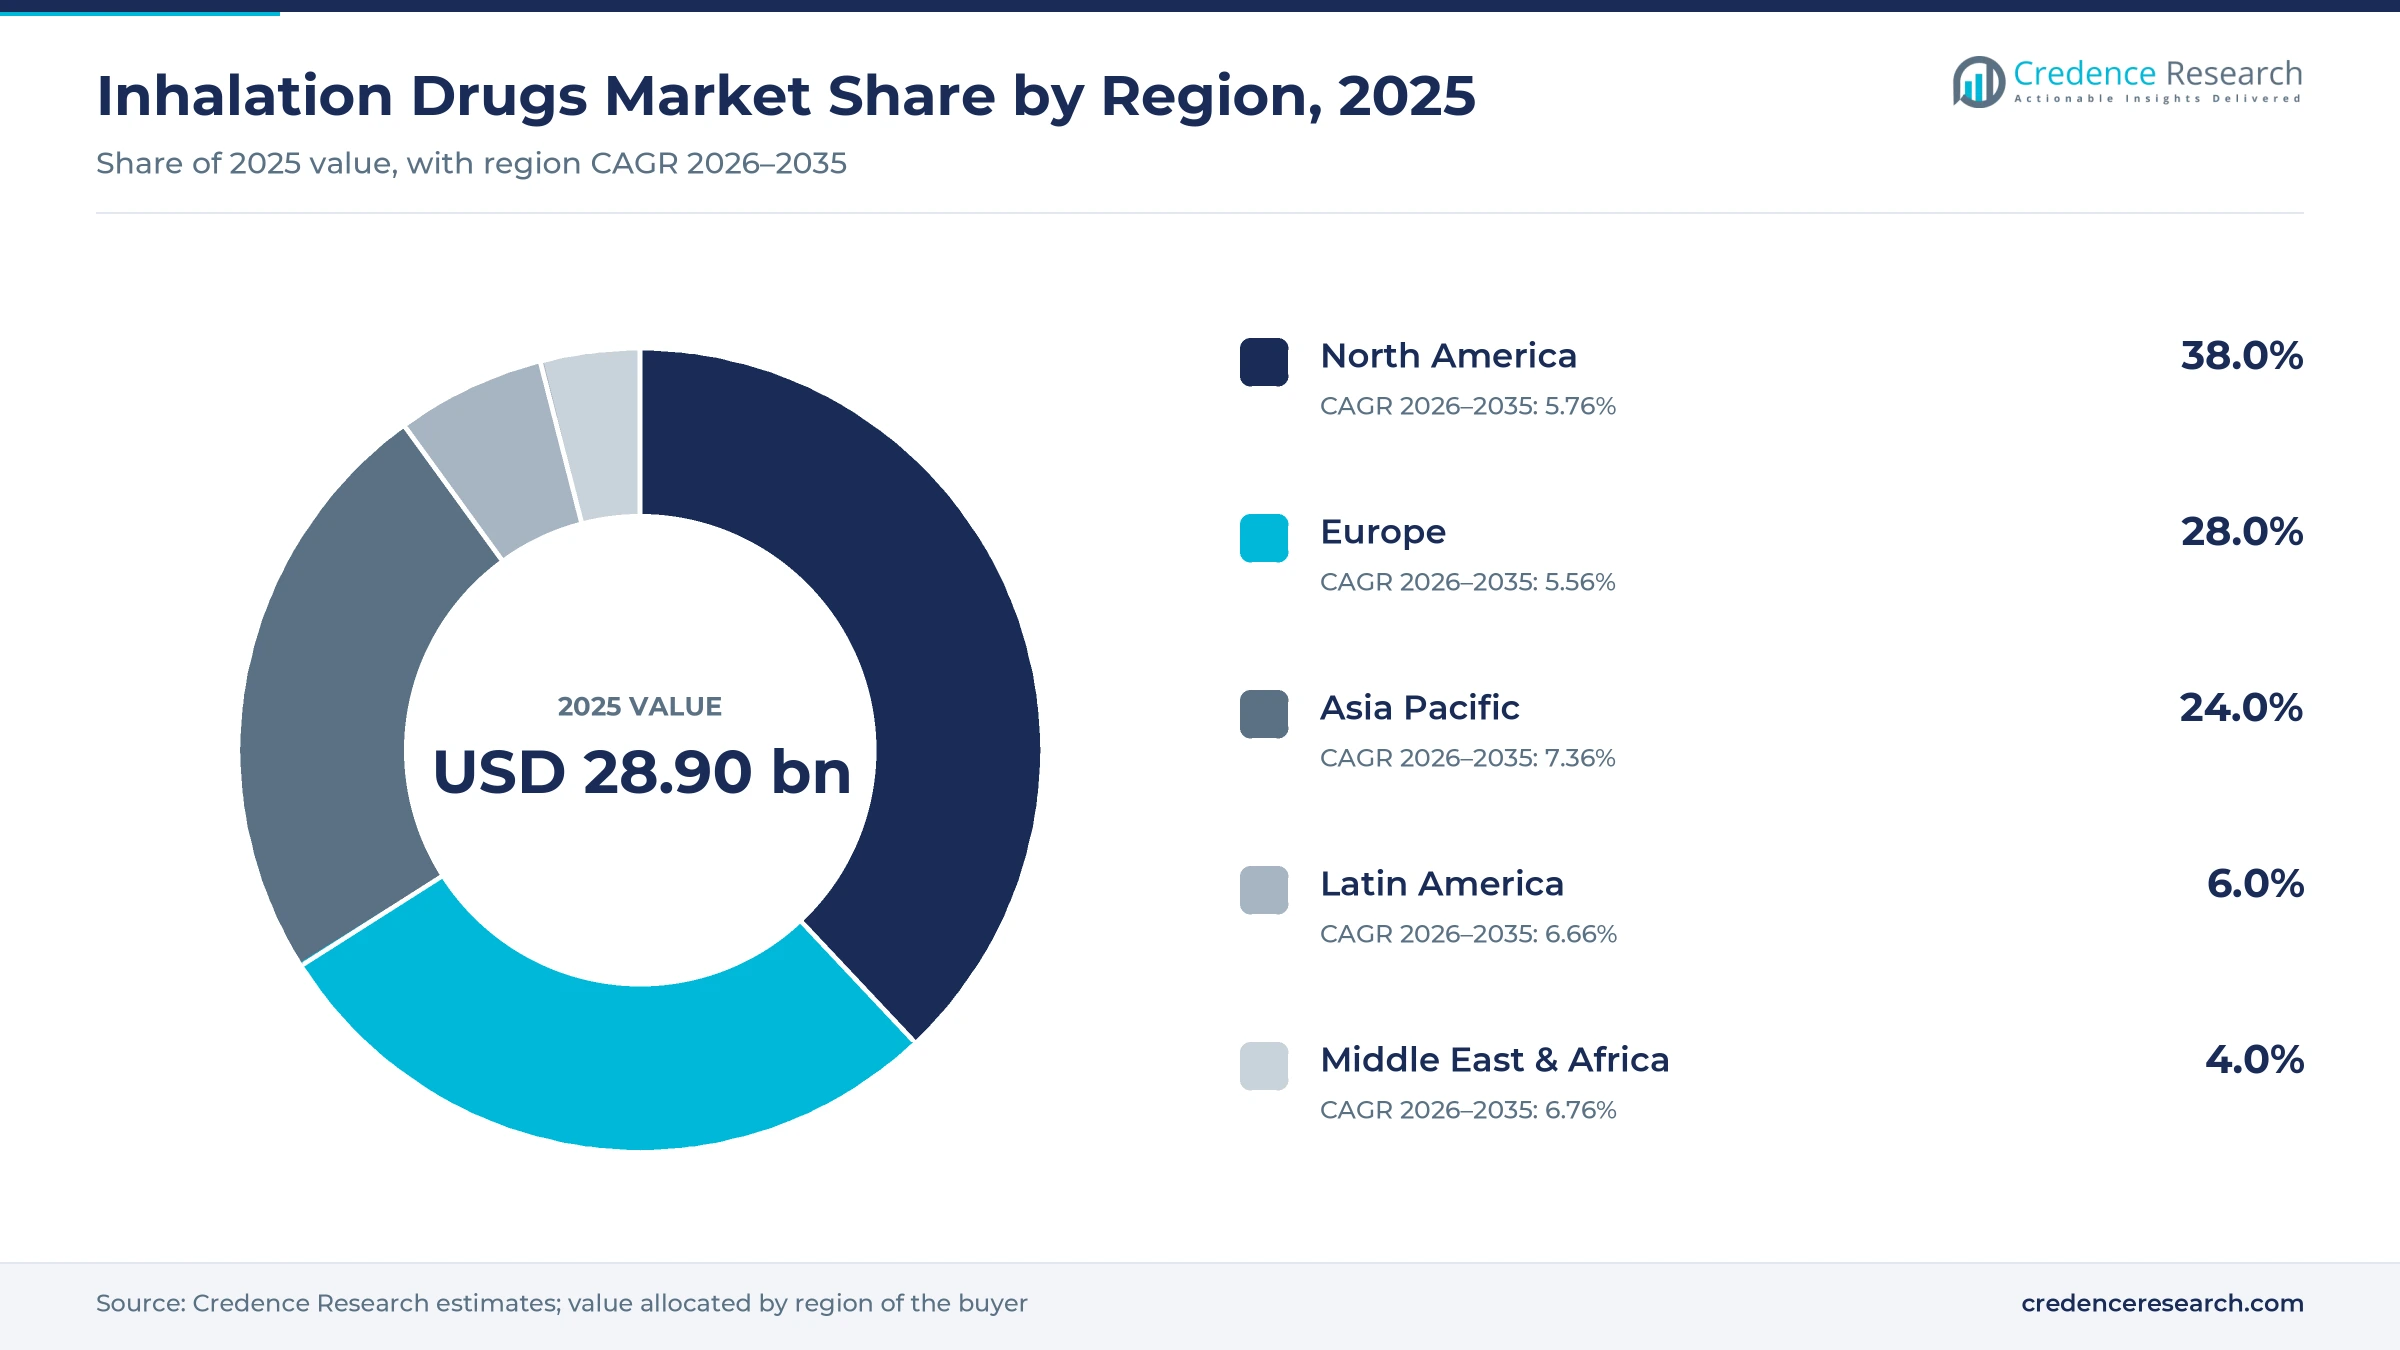
The global inhalation drugs market was valued at USD 28.90 billion in 2025 and is projected to increase from USD 30.70 billion in 2026 to USD 52.73 billion by 2035, registering a CAGR of 6.20% during 2026–2035. Demand comes from the large number of people living with chronic obstructive pulmonary disease and asthma, wider use of triple and dual combination inhalers, and new medicines that add mechanisms beyond classic bronchodilation. North America held the largest regional share, 38.0% in 2025, because branded combination inhalers carry high prices and broad insurance coverage. Asia Pacific is the fastest-growing region at 7.36% a year, as China and India diagnose more COPD and expand access to maintenance therapy. The technology picture changed in May 2025, when U.K. regulators approved the first inhaled respiratory medicine using a propellant with near-zero global warming potential. As a result, inhaler makers now plan portfolio-wide propellant changes.
Which inhaled medicines and channels does this analysis cover?
The analysis counts prescription and over-the-counter medicines delivered to the lungs, including bronchodilators, corticosteroids and other inhaled classes, in pressurized aerosol, spray and dry powder forms, valued at manufacturer selling prices. Patients fill most prescriptions through retail pharmacies, while hospitals buy rescue and nebulized products for inpatients.
Inhaler devices sold without a medicine, oxygen therapy and injected biologics for asthma sit outside the scope of this analysis. The value chain runs from active ingredient and propellant suppliers through originator and generic manufacturers to wholesalers, pharmacies and payers, which set formulary access and patient out-of-pocket costs.
Inhalation Drugs Market Insights
- The inhalation drugs market grows from USD 28.90 billion in 2025 to USD 52.73 billion by 2035, a 6.20% CAGR as COPD and asthma treatment widens worldwide.
- North America held 38.0% of global inhaled medicine value in 2025, supported by high prices for branded combination inhalers.
- Bronchodilators led drug classes with 52.0% of 2025 value, because nearly every COPD and asthma patient uses a reliever or long-acting product.
- In May 2025, U.K. regulators approved AstraZeneca Trixeo Aerosphere with HFO-1234ze(E), a propellant with 99.9% lower global warming potential.
- In October 2025, MSD completed its acquisition of Verona Pharma, adding the nebulized COPD medicine Ohtuvayre to a large respiratory pipeline.
Bronchodilators lead as dry powder products gain ground
Why do bronchodilators lead inhaled spending?
Based on drug class, the market is categorized into bronchodilators, corticosteroids and others. Bronchodilators led with a 52.0% share of 2025 value, because short-acting relievers and long-acting maintenance products form the base of COPD and asthma care. Long-acting bronchodilators also appear in most dual and triple combination inhalers sold today. Others grow fastest at 6.95% a year, as new mechanisms such as phosphodiesterase inhibitors reach patients.
How are dry powder products gaining share?
Based on type, the market is categorized into aerosol, inhalation spray and dry powder formulation. Aerosol products led with a 45.0% share of 2025 value, because pressurized metered dose inhalers remain the most common reliever format worldwide. Dry Powder Formulation grows fastest at 6.63% a year, as health systems seek low-carbon options and patients adopt breath-actuated devices. Spray products serve nasal and soft mist uses with specific patient groups.
Why do respiratory diseases dominate demand?
Based on indication, the market is categorized into respiratory diseases and non-respiratory diseases. Respiratory Diseases led with 88.0% of 2025 value, because COPD, asthma and cystic fibrosis account for most inhaled prescriptions. Non-Respiratory Diseases grow fastest at 7.08% a year, as inhaled routes reach pulmonary hypertension and other systemic uses. Respiratory care still sets the scale of the market through 2035.
Where do patients fill inhaled prescriptions?
Based on distribution channel, the market is categorized into hospital pharmacies, retail pharmacies and drug stores, and online pharmacies. Retail Pharmacies & Drug Stores led with a 58.0% share of 2025 value, because patients refill maintenance inhalers monthly near home. Online Pharmacies grow fastest at 7.94% a year, as online pharmacy platforms offer home delivery and automatic refills for chronic patients.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Drug Class | Bronchodilators | 52.0% | Others | 6.95% |
| By Type | Aerosol | 45.0% | Dry Powder Formulation | 6.63% |
| By Indication | Respiratory Diseases | 88.0% | Non-Respiratory Diseases | 7.08% |
| By Distribution Channel | Retail Pharmacies & Drug Stores | 58.0% | Online Pharmacies | 7.94% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
COPD and asthma burden keeps inhaled therapy essential
How does the global COPD burden sustain demand?
The global COPD burden sustains demand, because inhaled maintenance therapy is the standard of care for symptomatic patients. The World Health Organization reports that COPD is the third leading cause of death worldwide, causing 3.4 million deaths in 2023, about 6% of all deaths. Nearly 90% of COPD deaths in people under 70 occur in low- and middle-income countries. As a result, wider diagnosis in these countries adds many new patients who need long-acting bronchodilators and combination inhalers. Tobacco smoking accounts for over 70% of COPD cases in high-income countries, according to the same agency.
Why does the large asthma population keep reliever use high?
The large asthma population keeps reliever and controller use high, because most patients need daily or as-needed inhaled medicine. The World Health Organization estimates that asthma affected 363 million people in 2023 and caused 442,000 deaths. Most of these deaths occur in low- and lower-middle-income countries, where under-diagnosis and under-treatment remain common. In turn, programs that expand access to inhaled corticosteroids create large volume growth for affordable generic products, especially in South Asia and Africa.
How are new mechanisms widening COPD treatment options?
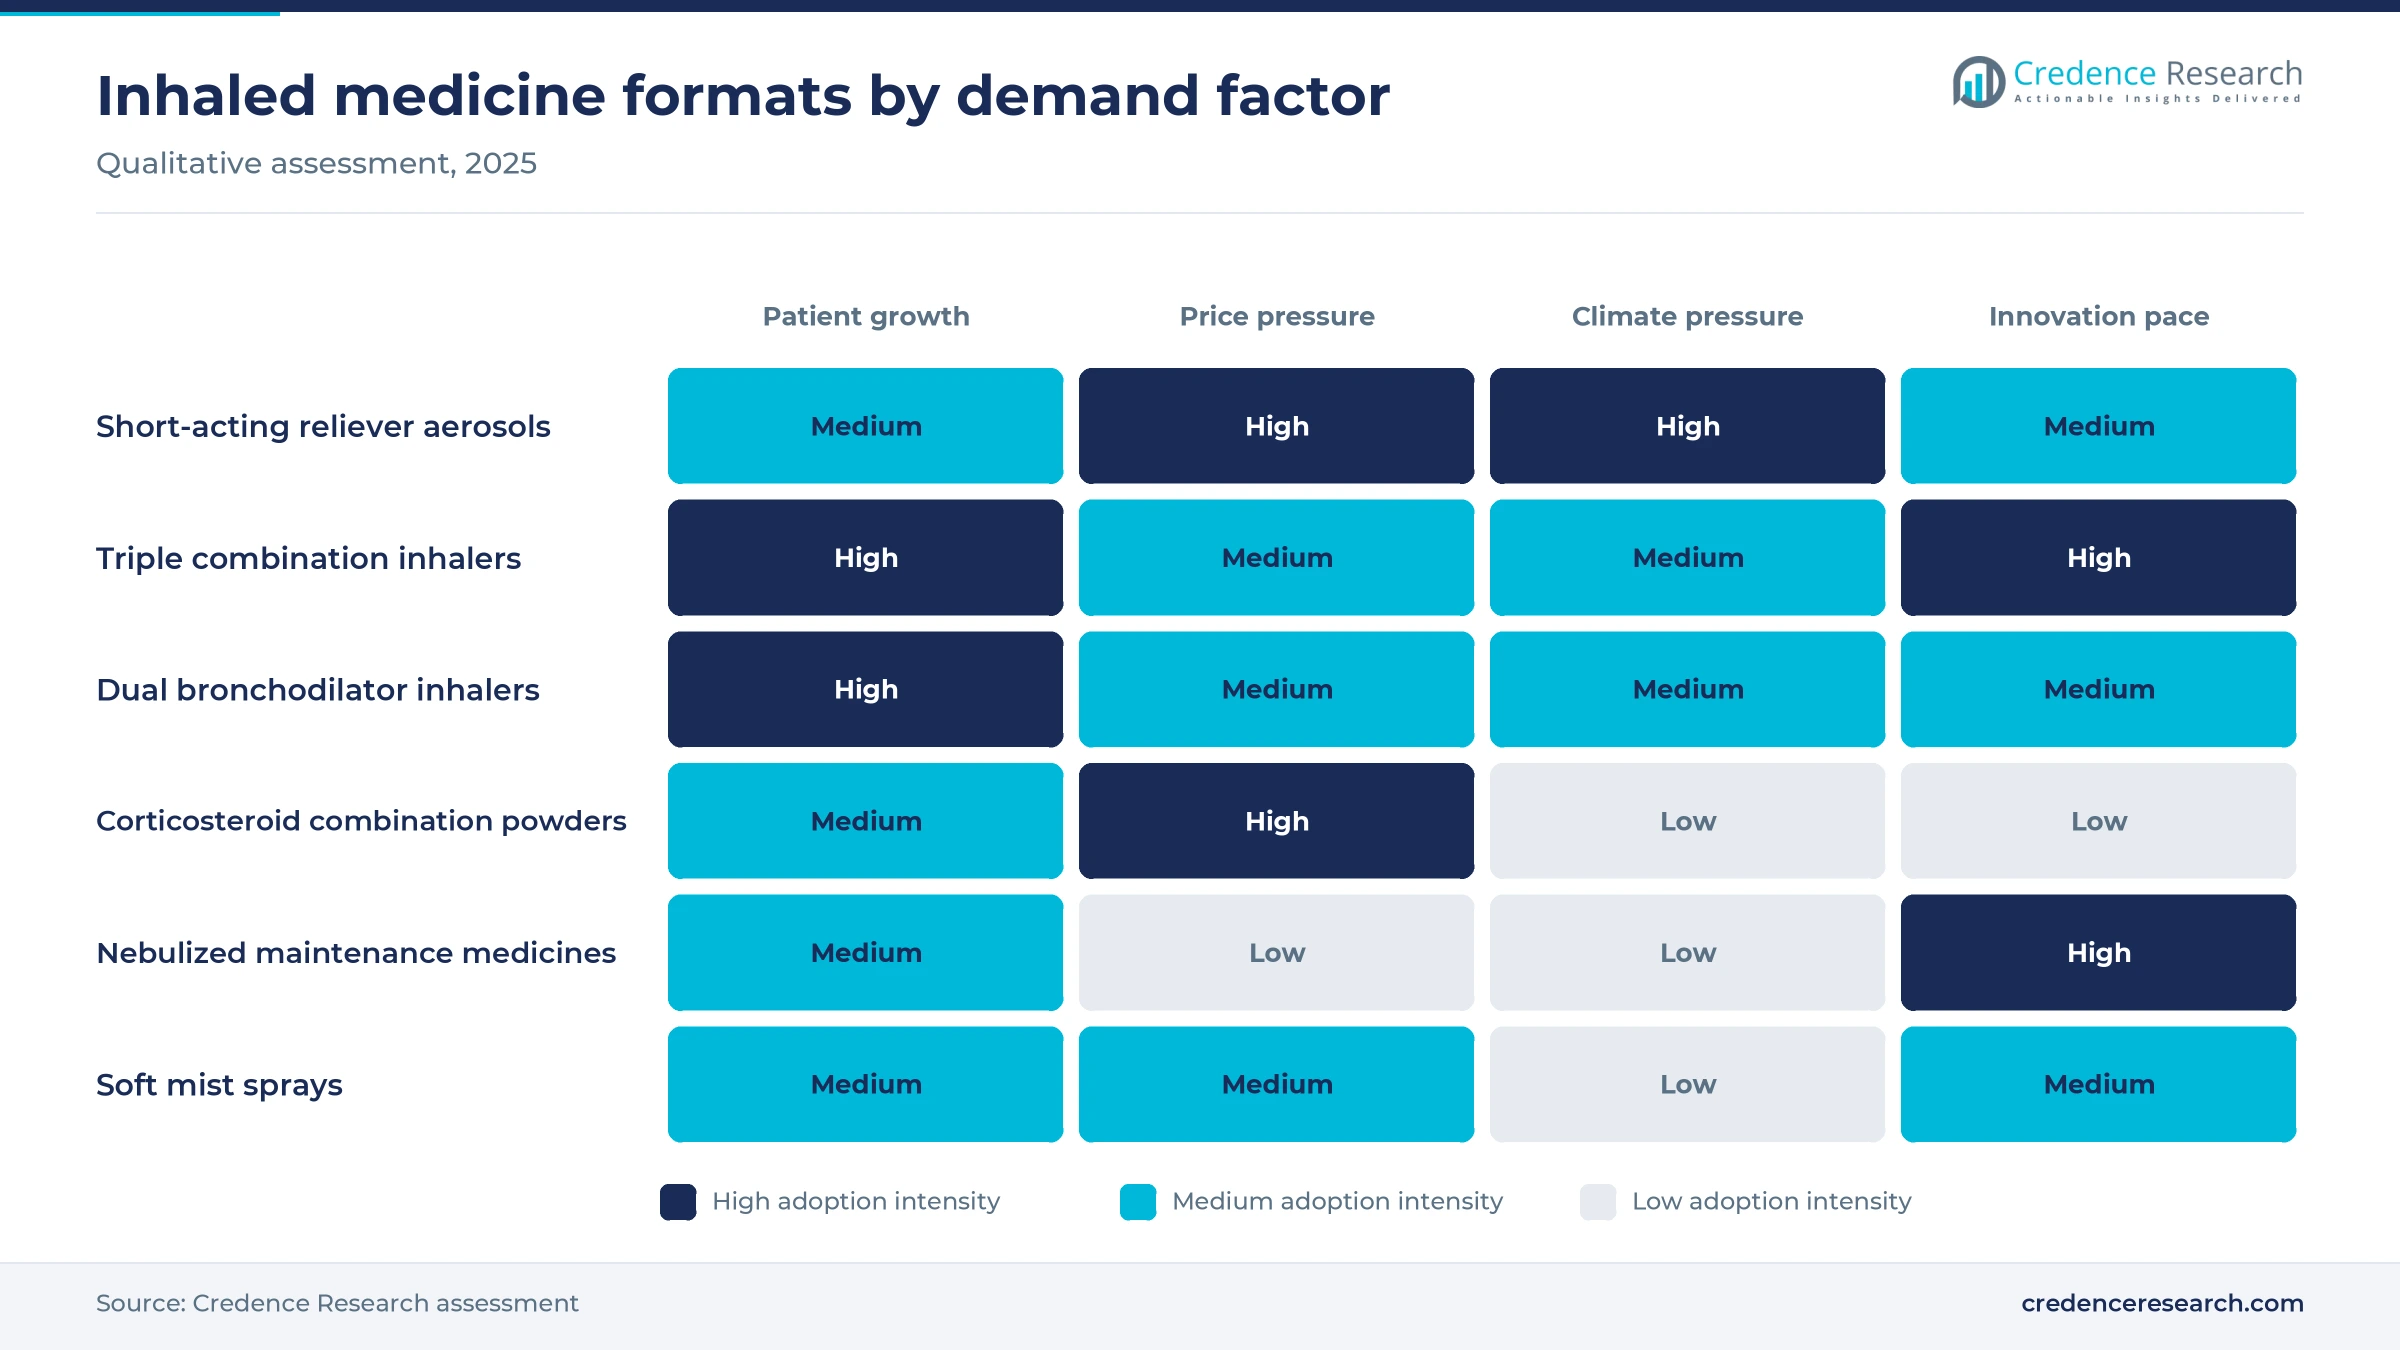
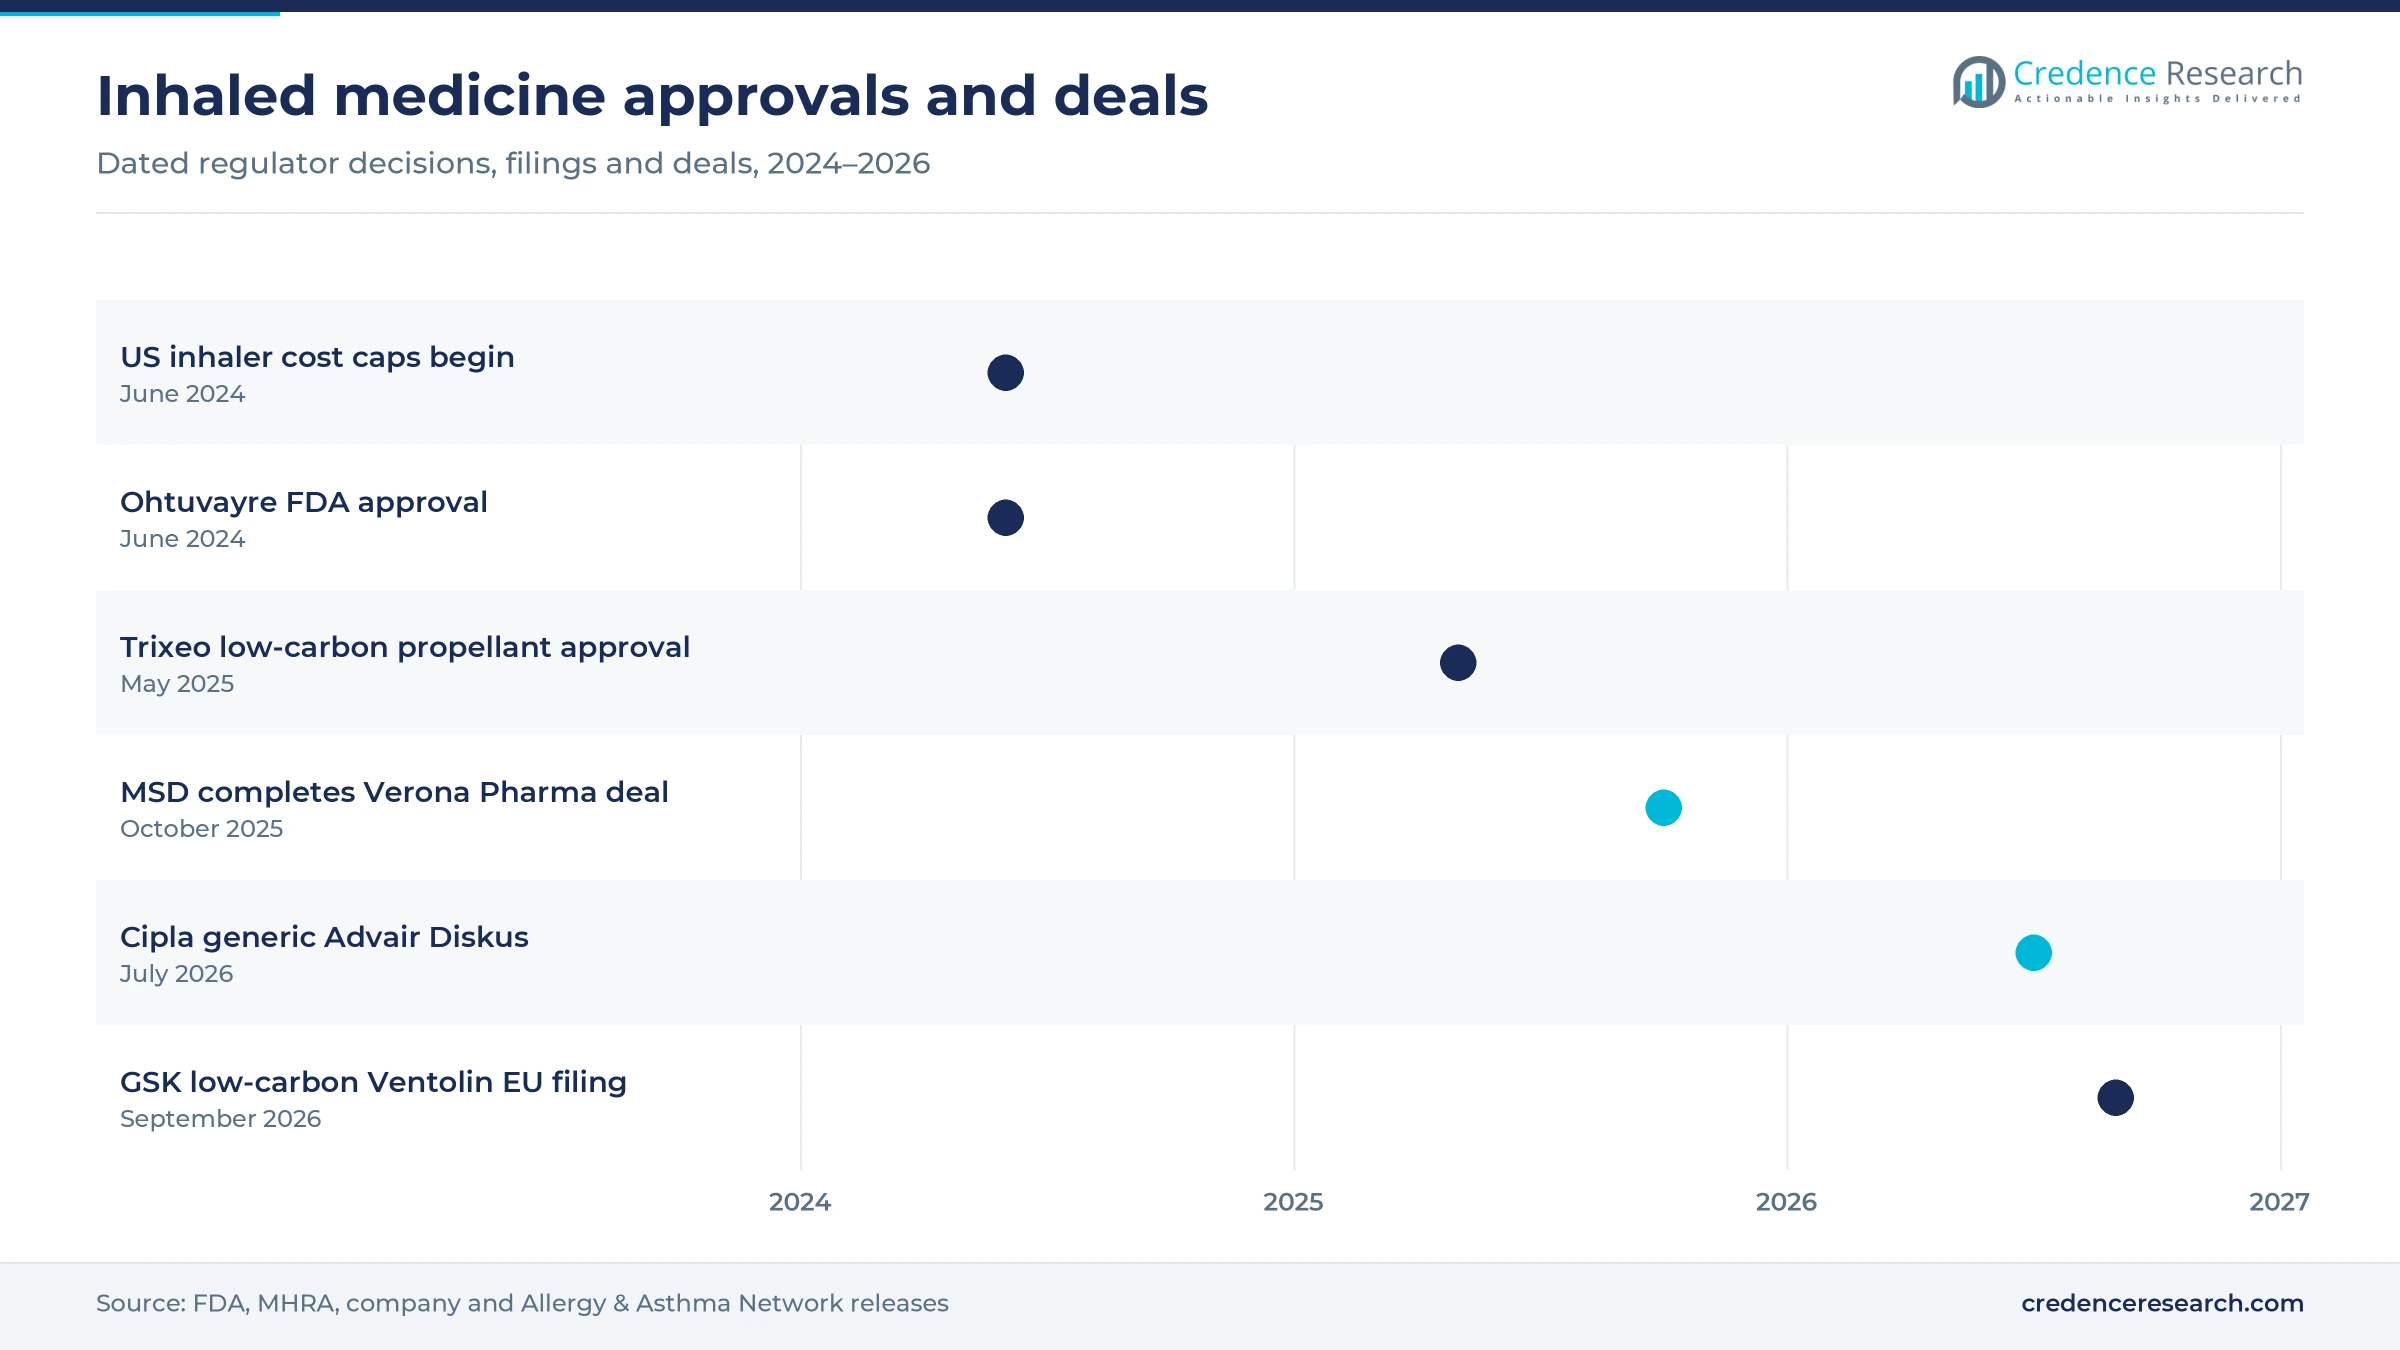
New mechanisms widen COPD treatment options, because many patients stay symptomatic on existing bronchodilators and corticosteroids. In June 2024, the FDA approved Verona Pharma Ohtuvayre, an inhaled dual phosphodiesterase 3 and 4 inhibitor for COPD maintenance in adults, delivered through a standard jet nebulizer. In October 2025, MSD completed its acquisition of Verona Pharma, which brought the medicine into a larger commercial organization. As a result, premium add-on therapies now raise spending per treated patient in the United States.
Why do out-of-pocket caps support adherence and volume?
Out-of-pocket caps support adherence and volume, because high copays often lead patients to skip maintenance inhalers. Boehringer Ingelheim and AstraZeneca introduced caps on monthly out-of-pocket costs at USD 35 for eligible U.S. patients from June 1, 2024. GSK committed to a similar USD 35 cap no later than Jan. 1, 2025. In turn, more patients can stay on controller therapy, which supports prescription volume for branded inhalers despite lower net prices.
Greener propellants and new mechanisms reshape treatment
How is the shift to low-carbon propellants reshaping portfolios?
The shift to low-carbon propellants is reshaping inhaler portfolios, because older hydrofluoroalkane propellants carry high global warming potential. In May 2025, AstraZeneca announced U.K. approval of Trixeo Aerosphere with HFO-1234ze(E), a propellant with 99.9% lower global warming potential than those in current pressurized inhalers. The company said the medicine had been prescribed to more than five million patients globally. As a result, rivals are moving reliever and maintenance inhalers to new propellants.
Why are reliever inhalers rising on the climate agenda?
Reliever inhalers are rising on the climate agenda, because salbutamol aerosols account for a large share of inhaler use worldwide. In September 2026, GSK filed an EU regulatory submission for a lower-carbon Ventolin metered dose inhaler using the propellant HFA-152a. Phase III data showed the new version was therapeutically equivalent to the current HFA-134a formulation, with a comparable safety profile in the study population. In turn, health systems in Europe can switch patients without changing the active medicine.
Can generic combination inhalers open new access in the U.S.?
Generic manufacturers have a clear opening in combination inhalers, because complex device and formulation rules have long limited competition. In July 2026, Cipla announced FDA approval of its generic version of Advair Diskus, fluticasone propionate and salmeterol inhalation powder, in all three strengths. Generic entry usually lowers prices for patients, pharmacies and payers over time. As a result, generic makers with device expertise can win share in high-volume maintenance products.
Where can connected devices add value for inhaled therapy?
Connected devices give manufacturers room to add value, because poor technique and missed doses reduce the benefit of inhaled medicines. Smart inhalers record each dose, check timing and send reminders through phone apps to patients and their care teams. Hospitals also use nebulizers for patients who cannot use handheld inhalers during exacerbations. In turn, companies that pair medicines with adherence tools can support payer contracts based on outcomes.
Generic pressure, device skills and access gaps slow value
Why does generic and price pressure limit value growth?
Generic and price pressure limits value growth, because major combination inhalers face new generic competition and voluntary patient cost caps. Copay caps of USD 35 a month lower patient payments, and manufacturers often absorb part of that cost. Generic Advair Diskus versions also reduce prices for one of the largest maintenance products. As a result, branded companies must launch new mechanisms or improved devices to defend their positions. In July 2026, Cipla announced its generic Advair Diskus approval, which shows how quickly generic competition is reaching complex powder inhalers.
How does poor inhaler technique reduce treatment benefit?
Poor inhaler technique reduces treatment benefit, because patients must coordinate breathing with device actuation to deliver medicine to the lungs. Many patients, especially children and older adults, use devices incorrectly without regular training. This problem lowers symptom control and can lead to more exacerbations, emergency visits and hospital stays for patients with COPD. In turn, clinicians and pharmacists need time for device teaching, which health systems often do not fund.
Why do diagnosis gaps slow uptake in low-income countries?
Diagnosis gaps slow uptake in low-income countries, because spirometry is often unavailable outside large hospitals. The World Health Organization notes that COPD diagnosis may be missed where spirometry is unavailable in low- and middle-income countries. Undiagnosed patients rarely receive maintenance inhalers and often rely on oral medicines or emergency care. In those countries, tobacco smoking accounts for 30% to 40% of COPD cases, while indoor air pollution from biomass fuel adds further risk. As a result, a large treatment gap remains despite high disease burden.
How does the propellant transition raise development costs?
The propellant transition raises development costs, because each reformulated inhaler needs new clinical and regulatory data. Companies must run equivalence studies, validate new manufacturing lines and file in each major market separately. Smaller generic makers may struggle to fund these programs across many products. In September 2026, GSK announced its EU filing for a lower-carbon Ventolin, which shows the scale of data required for even a well-known reliever. In turn, the transition may favor large companies and delay some low-cost versions in certain markets.
North America leads as Asia Pacific gains pace
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 10.98 | 38.0% | 5.76% |
| Europe | 8.09 | 28.0% | 5.56% |
| Asia Pacific | 6.94 | 24.0% | 7.36% |
| Latin America | 1.73 | 6.0% | 6.66% |
| Middle East & Africa | 1.16 | 4.0% | 6.76% |
Why does North America hold the largest regional share?
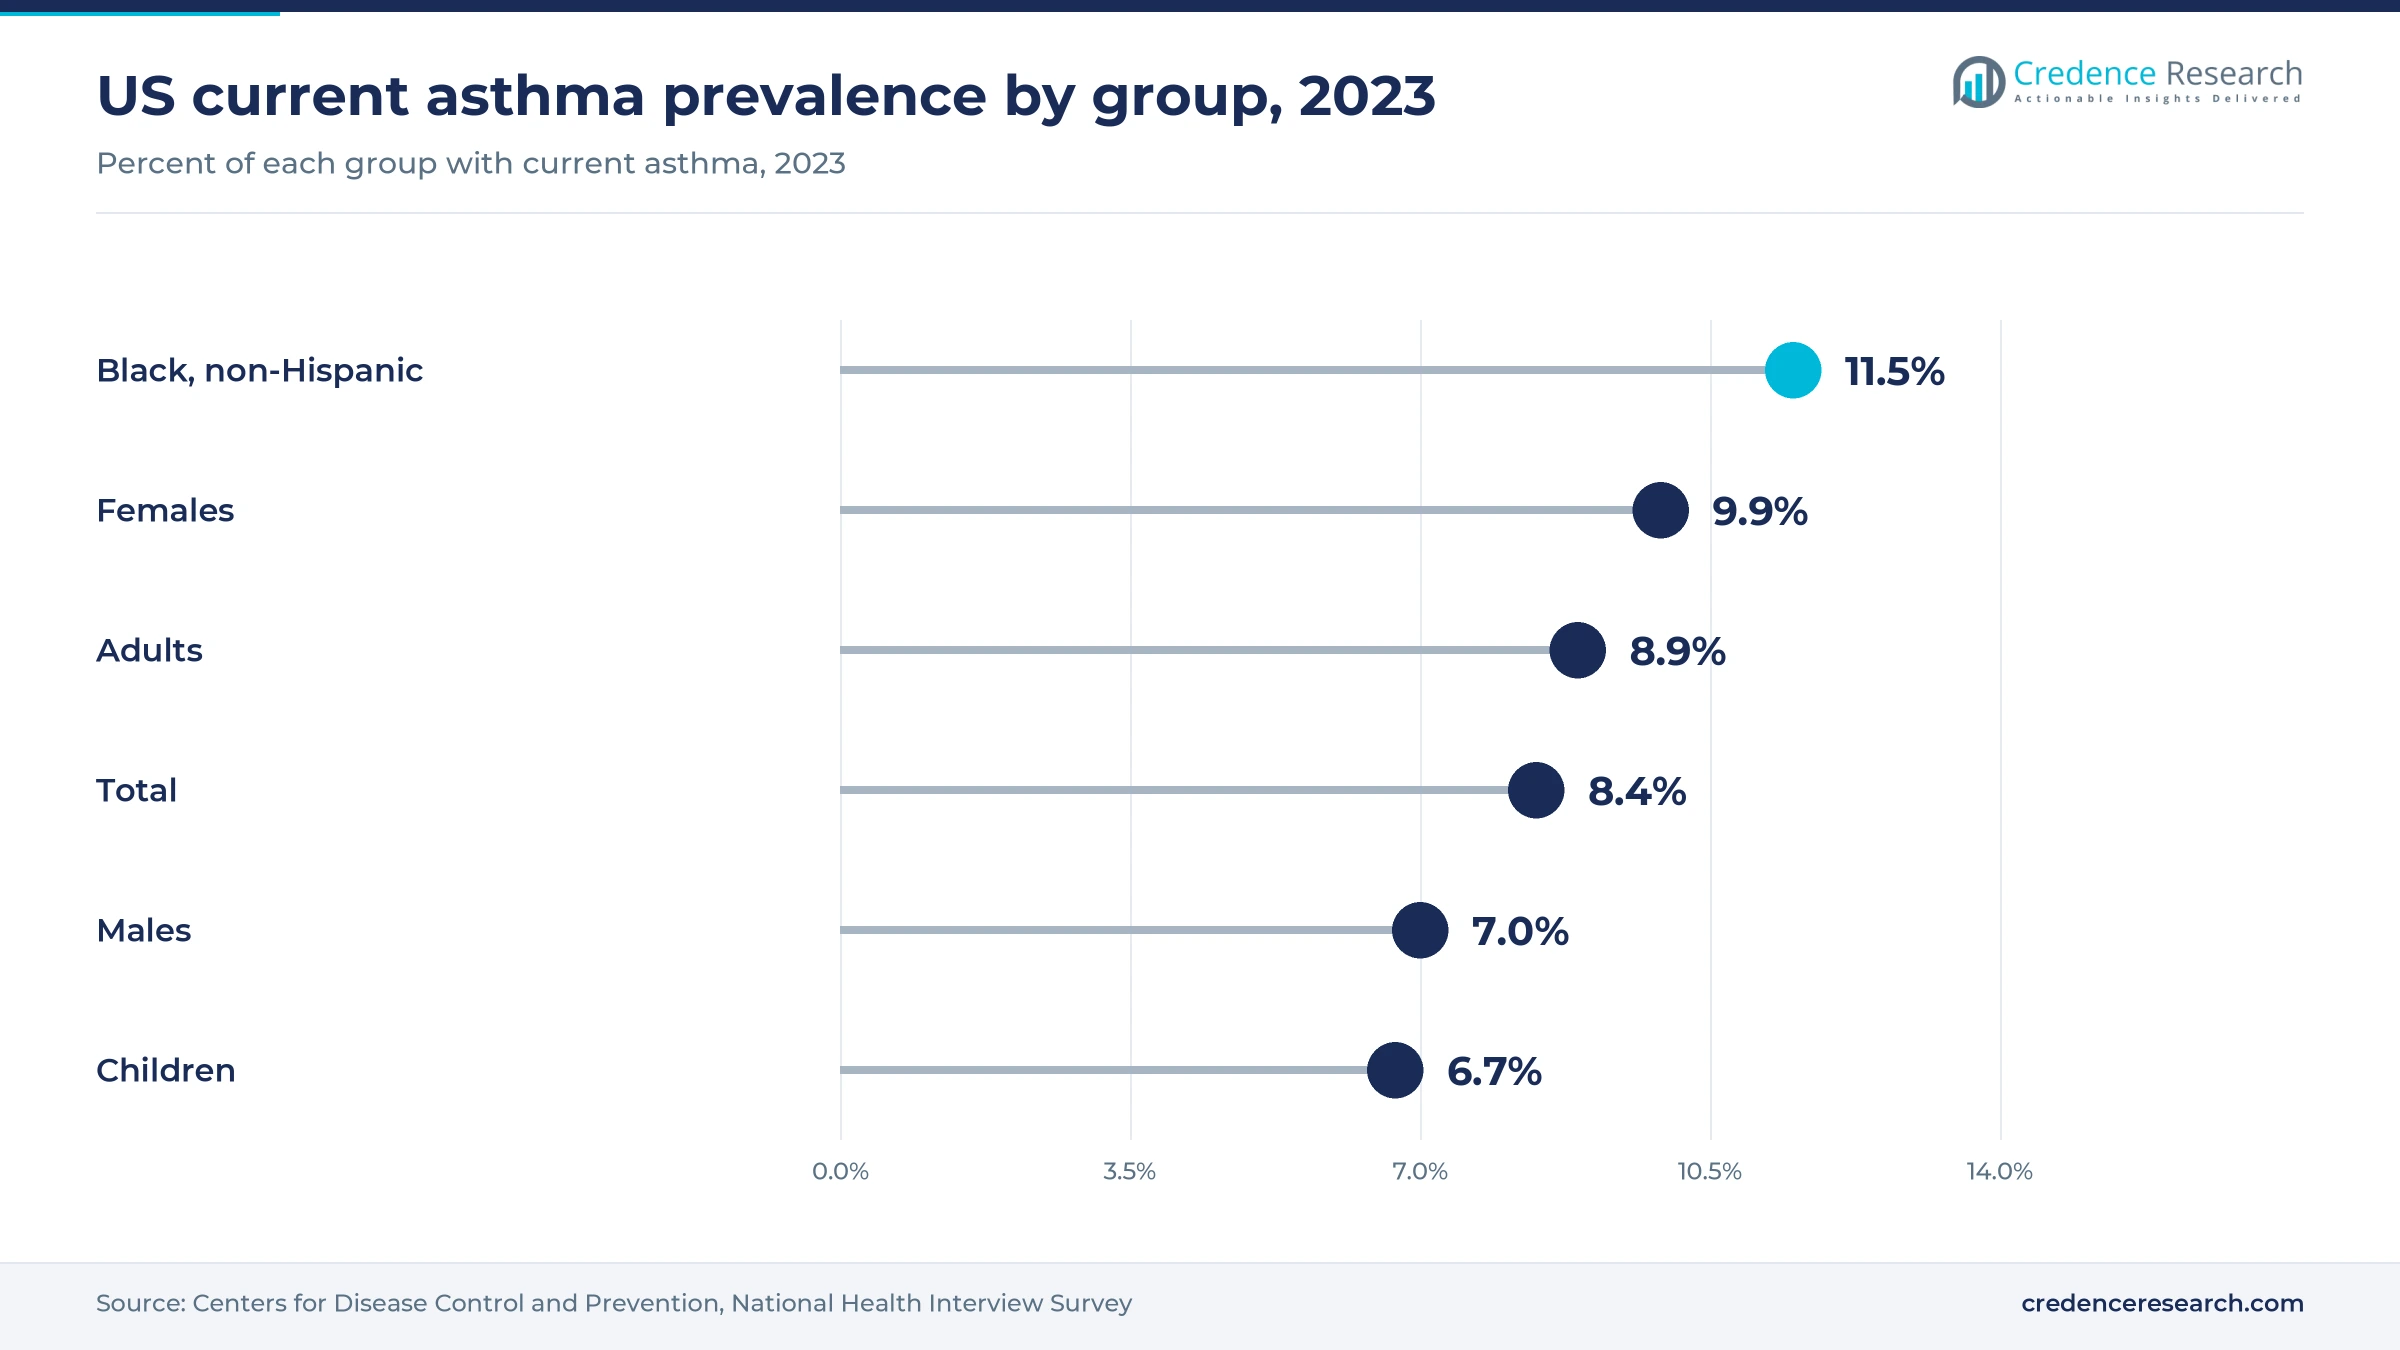
North America held a 38.0% share of 2025 value and grows at 5.76% a year through 2035. The United States drives this position, because branded triple and dual combination inhalers carry high list prices. The Centers for Disease Control and Prevention counts 27.8 million people with current asthma in 2023, or 8.4% of the population. New COPD medicines such as Ohtuvayre launched first in this market. However, out-of-pocket caps and generic entry are lowering net prices.
How fast is Asia Pacific adding treated patients?
Asia Pacific held a 24.0% share of 2025 value and is the fastest-growing region at 7.36% a year. China and India carry large COPD populations linked to smoking, air pollution and biomass fuel use. Wider spirometry testing and public coverage add new patients each year. Local makers such as Cipla Ltd supply affordable generic inhalers, which expands access in price-sensitive markets across the region.
What shapes demand across Europe?
Europe held a 28.0% share of 2025 value and grows at 5.56% a year, the slowest pace of the five regions. Germany, the United Kingdom, France and Italy account for most spending through national formularies. Climate targets push health systems toward dry powder and low-carbon aerosol inhalers. In May 2025, AstraZeneca announced the U.K. approval of Trixeo Aerosphere with a next-generation propellant. However, price controls keep value growth below the global average.
Where is Latin America adding demand?
Latin America held a 6.0% share of 2025 value and grows at 6.66% a year through 2035. Brazil and Mexico lead regional spending, while public programs supply basic relievers and corticosteroids to many patients.
What limits growth in the Middle East and Africa?
The Middle East and Africa held a 4.0% share of 2025 value and grows at 6.76% a year through 2035. Gulf states fund branded inhalers, while much of Africa relies on low-cost relievers and limited spirometry.
Approvals, filings and deals in inhaled care since 2024
| Development | Status and market relevance |
|---|---|
| In June 2024, the FDA approved Verona Pharma Ohtuvayre, an inhaled dual phosphodiesterase 3 and 4 inhibitor for COPD maintenance in adults. | Approved; nebulized maintenance treatment for adults with COPD |
| In May 2025, U.K. regulators approved AstraZeneca Trixeo Aerosphere with the HFO-1234ze(E) propellant. | Approved; first inhaled respiratory medicine with a near-zero global warming potential propellant |
| In October 2025, MSD completed its acquisition of Verona Pharma. | Completed; adds Ohtuvayre to a large respiratory portfolio |
| In July 2026, Cipla received FDA approval for a generic version of Advair Diskus in all three strengths. | Approved; adds generic competition in fluticasone and salmeterol powder inhalers |
| In September 2026, GSK filed an EU regulatory submission for a lower-carbon Ventolin inhaler using HFA-152a. | Under review; supported by positive phase III equivalence data |
Propellant change and device design lead innovation
- Low global warming potential propellants such as HFO-1234ze(E) and HFA-152a replace older gases, which cuts the climate impact of aerosol inhalers.
- Triple combination inhalers deliver a corticosteroid and two bronchodilators in one device, which simplifies treatment for COPD patients.
- Dry powder inhaler design uses the patient breath to release medicine, which avoids propellants and coordination problems.
- Nebulized novel mechanisms such as dual phosphodiesterase inhibitors add anti-inflammatory and bronchodilator effects for symptomatic COPD patients.
- Connected dose counters record inhaler use and technique, which helps clinicians identify poor adherence before exacerbations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Respiratory leaders and generic makers compete on access
Competition is led by large respiratory originators and by generic manufacturers with complex inhaler expertise. GSK, AstraZeneca plc and Boehringer Ingelheim International GmbH hold leading positions in maintenance inhalers, and each has acted on patient cost caps or propellant change since 2024. Novartis AG, Sanofi SA and Pfizer Inc participate through respiratory portfolios, partnerships and specific inhaled products. Teva Pharmaceutical Industries Ltd, Cipla Ltd and Hikma Pharmaceuticals PLC compete in generic and branded-generic inhalers, where device equivalence and manufacturing scale matter most. Mundipharma International Limited serves respiratory patients in selected international markets. As a result, competition increasingly centers on low-carbon device platforms, new mechanisms and affordable access for chronic patients.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| GSK | Originator | Ventolin relievers and lower-carbon HFA-152a program |
| AstraZeneca plc | Originator | Breztri and Trixeo Aerosphere triple inhalers with next-generation propellant |
| Boehringer Ingelheim International GmbH | Originator | Respiratory inhalers with USD 35 U.S. out-of-pocket cap |
| Novartis AG | Originator | Respiratory portfolio including inhaled products |
| Teva Pharmaceutical Industries Ltd | Generic and branded | Generic and branded respiratory inhalers |
| Cipla Ltd | Generic | Generic Advair Diskus and affordable inhalers in emerging markets |
| Hikma Pharmaceuticals PLC | Generic | Generic respiratory products |
| Pfizer Inc | Originator | Selected respiratory and inhaled products |
| Sanofi SA | Originator | Respiratory portfolio and partnerships |
| Mundipharma International Limited | Specialty | Respiratory products in selected international markets |
Propellant transition sets the pace of change to 2035
Credence Research's view is that the propellant transition and new mechanisms will set the pace of change through 2035, while disease burden keeps volumes rising. The overall market grows at 6.20% a year, supported by wider COPD diagnosis in Asia Pacific and premium add-on therapies in high-income markets. Generic combination inhalers and cost caps restrain price growth in the United States. Companies that pair low-carbon devices, affordable access and new mechanisms will win the most patients.
How Credence Research sized inhaled medicine spending
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, which builds spending by drug class, type, indication, distribution channel and region. Regional and segment splits are Credence Research estimates informed by World Health Organization and Centers for Disease Control and Prevention statistics, regulator decisions and company press releases. No primary interviews or surveys were used in preparing this edition of the report.
Inhaled medicine spending outlook to 2035
By 2035, the inhalation drugs market is projected to reach USD 52.73 billion, with growth led by combination maintenance inhalers, new mechanisms and wider treatment in Asia Pacific. Bronchodilators will remain the largest drug class, while dry powder and low-carbon aerosol products gain share. North America keeps the highest spending per patient, although generic entry and cost caps limit price growth. Online pharmacies will take a larger share of monthly refills for chronic patients. As a result, advantage will depend on device platforms, access and climate-friendly reformulation.
Frequently Asked Questions
How big is the global inhalation drugs market?
Which drug class leads the inhalation drugs market?
Which region leads inhaled medicine spending?
Which product type grows fastest?
How many people have COPD and asthma?
Why are inhaler propellants changing?
Who are the leading inhalation drug companies?
What restrains growth in inhalation drugs?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Class
- 1.2.1 Bronchodilators
- 1.2.2 Corticosteroids
- 1.2.3 Others
- 1.3 By Type
- 1.3.1 Aerosol
- 1.3.2 Inhalation Spray
- 1.3.3 Dry Powder Formulation
- 1.4 By Indication
- 1.4.1 Respiratory Diseases
- 1.4.2 Non-Respiratory Diseases
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 28.90 billion → 2035: USD 52.73 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Inhalation Drugs Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Inhalation Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Inhalation Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Inhalation Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Inhalation Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Inhalation Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Inhalation Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Inhalation Drugs Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 28.90 billion → 2035: USD 52.73 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Inhalation Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Class - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bronchodilators
- 12.3.7.2 Corticosteroids
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Aerosol
- 12.4.7.2 Inhalation Spray
- 12.4.7.3 Dry Powder Formulation
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Indication - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Respiratory Diseases
- 12.5.7.2 Non-Respiratory Diseases
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Inhalation Drugs Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Inhalation Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Inhalation Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Hikma Pharmaceuticals PLC
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 GSK
- 17.4 AstraZeneca plc
- 17.5 Boehringer Ingelheim International GmbH
- 17.6 Novartis AG
- 17.7 Teva Pharmaceutical Industries Ltd
- 17.8 Cipla Ltd
- 17.9 Pfizer Inc
- 17.10 Sanofi SA
- 17.11 Mundipharma International Limited
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

