
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Inhalers Market Size 2024 | USD 19,661.62 Million |
| Smart Inhalers Market, CAGR | 19.25% |
| Smart Inhalers Market Size 2032 | USD 80,120.35 Million |
Market Overview:
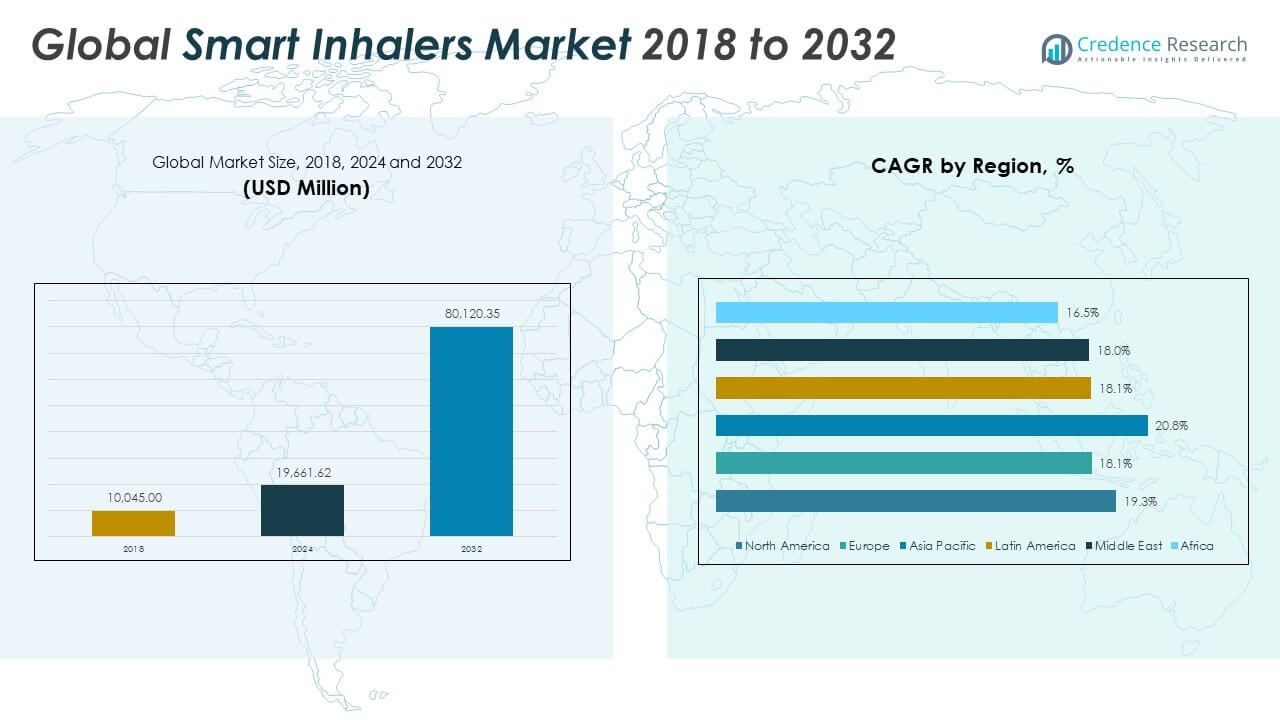
The Global Smart Inhalers Market size was valued at USD 10,045.00 million in 2018 to USD 19,661.62 million in 2024 and is anticipated to reach USD 80,120.35 million by 2032, at a CAGR of 19.25% during the forecast period.
The primary growth drivers of the Global Smart Inhalers Market include the global increase in chronic respiratory conditions, coupled with the healthcare sector’s shift toward preventive and remote care models. Asthma and COPD remain among the leading causes of morbidity, prompting a need for tools that enable better disease control. Smart inhalers offer features such as dose tracking, reminders, and data synchronization with clinical platforms, improving both patient engagement and treatment outcomes. A Cleveland Clinic study demonstrated a 35% reduction in COPD-related hospitalizations when patients used smart inhalers. Supportive regulatory frameworks and growing investments in telemedicine and remote monitoring technologies are accelerating adoption. Pharmaceutical companies and medtech innovators are actively enhancing inhaler platforms with embedded digital features to capture real-time data and support evidence-based interventions.
Regionally, North America leads the Global Smart Inhalers Market, accounting for the largest revenue share due to high healthcare spending, early adoption of connected devices, and a significant burden of respiratory diseases. The United States, in particular, benefits from robust digital infrastructure and favorable reimbursement policies that encourage the use of smart inhaler solutions. Europe follows closely, driven by government-backed chronic disease management programs, widespread digital health initiatives, and increasing awareness about adherence tools. The Asia-Pacific region is expected to exhibit the fastest growth, supported by rising urbanization, increasing air pollution, expanding healthcare access, and strong investment in medical technology across China, India, and Japan. Latin America, the Middle East, and Africa are witnessing gradual market development, helped by expanding pharmaceutical supply chains and growing emphasis on chronic disease detection and management. This regional diversity underscores the market’s global relevance and future scalability.
Market Insights:
- The Global Smart Inhalers Market grew from USD 10,045.00 million in 2018 to USD 19,661.62 million in 2024 and is projected to reach USD 80,120.35 million by 2032, registering a CAGR of 19.25%.
- Increasing prevalence of asthma and COPD, affecting over 300 million people globally, is driving demand for smart inhalers to support better disease management.
- Smart inhalers offer real-time data synchronization, dose tracking, and connectivity with mobile apps, enabling remote monitoring and personalized treatment.
- Studies show that smart inhalers can improve adherence by up to 59% and significantly reduce hospital visits by providing reminders and usage alerts.
- Regulatory approvals and reimbursement policies in North America and Europe are boosting adoption of connected inhaler platforms across healthcare systems.
- High costs and limited affordability in low- and middle-income countries remain major obstacles to widespread market adoption of smart inhaler devices.
- Data privacy concerns and lack of seamless integration with electronic health records present challenges to the full-scale implementation of smart inhalers.
Market Drivers:
Growing Global Burden of Asthma and Chronic Obstructive Pulmonary Disease (COPD):
The increasing prevalence of respiratory disorders, particularly asthma and COPD, is a primary driver of demand in the Global Smart Inhalers Market. Over 300 million people suffer from asthma globally, with COPD ranking as one of the leading causes of death. This escalating disease burden is creating pressure on healthcare systems to adopt more effective, scalable, and proactive treatment approaches. Smart inhalers offer advantages such as consistent dose tracking, early symptom detection, and reduced hospitalization rates. The Global Smart Inhalers Market is responding with solutions that align with long-term disease management goals. As more patients are diagnosed with chronic respiratory conditions, healthcare providers are seeking digital solutions that improve adherence and clinical outcomes.
- For instance, Propeller Health’s digital platform has been used in over 100,000 patients globally, with clinical studies showing a 79% reduction in asthma-related emergency visits among users of its smart inhaler system.
Increased Adoption of Digital Health and Remote Monitoring Technologies:
The rise of telehealth and mobile health solutions has accelerated the integration of connected devices into chronic disease management. Patients and providers are embracing technologies that enable real-time data sharing, medication tracking, and virtual consultations. Smart inhalers support these capabilities by syncing usage data with mobile applications and clinician dashboards. It enhances treatment precision, encourages adherence, and allows physicians to make data-driven adjustments to therapy plans. The Global Smart Inhalers Market benefits from growing investments in digital infrastructure and supportive policies that promote remote patient monitoring. As health systems seek to reduce in-person visits and optimize care delivery, connected inhalers are becoming essential tools.
- For instance, Teva Pharmaceuticals’ Digihaler family, approved by the FDA, features built-in sensors that automatically record inhaler use and transmit data to a mobile app, with over 50,000 devices distributed in the United States by 2024.
Focus on Improving Patient Adherence and Clinical Outcomes:
Medication non-adherence remains a significant challenge in respiratory care, leading to uncontrolled symptoms, emergency visits, and increased healthcare costs. Smart inhalers address this issue by providing reminders, usage alerts, and behavioral insights that help patients stay on track with their prescribed therapies. Clinical studies have shown that smart inhalers improve adherence by up to 59% and reduce hospital admissions. It strengthens the case for broader deployment across health systems aiming to enhance patient engagement and lower overall treatment costs. The Global Smart Inhalers Market is driven by the growing need to support patients with personalized and interactive tools that reinforce daily compliance. Healthcare payers and providers increasingly recognize the value of adherence-focused digital devices.
Supportive Regulatory and Reimbursement Environment for Connected Devices:
Governments and regulatory bodies are actively encouraging the use of smart medical devices, including inhalers, to improve chronic disease management. Regulatory agencies have approved several digital inhaler platforms, creating a clearer pathway for market entry. At the same time, payers in markets such as the U.S. and Europe are beginning to reimburse digital therapeutics and remote monitoring technologies. It strengthens the commercial viability of smart inhalers and accelerates their adoption across public and private health systems. The Global Smart Inhalers Market is expanding in part because of policy-level support that recognizes the clinical and economic benefits of connected devices. These developments are aligning reimbursement structures with long-term value-based care goals.
Market Trends:
Integration of Artificial Intelligence for Predictive and Personalized Respiratory Care:
Artificial intelligence (AI) is reshaping how smart inhalers collect, process, and analyze patient data. Developers are embedding machine learning algorithms to detect early symptom patterns, predict exacerbations, and recommend individualized interventions. AI-enabled platforms can correlate inhaler use with environmental data, such as air quality or pollen levels, offering more contextually aware insights. It strengthens the value of smart inhalers as proactive health management tools rather than passive tracking devices. The Global Smart Inhalers Market is embracing this shift toward intelligent, predictive capabilities that enhance clinical decision-making. Providers are more inclined to adopt systems that offer actionable insights instead of raw adherence data.
- For instance, Adherium’s Hailie® platform uses AI algorithms to analyze inhaler usage and environmental triggers, supporting over 200,000 monitored patient-days and demonstrating a 59% improvement in medication adherence in clinical trials.
Partnerships Between Pharma Companies and Digital Health Startups:
Strategic collaborations are increasing between pharmaceutical manufacturers and health tech startups to co-develop connected respiratory devices. Drug-device combination products are being launched through partnerships that combine established therapies with novel digital capabilities. These alliances help accelerate product development, regulatory navigation, and market entry. The Global Smart Inhalers Market reflects this trend through high-profile partnerships focused on smart drug delivery systems and integrated digital platforms. Such collaborations allow pharmaceutical companies to differentiate their portfolios while gaining access to data-driven healthcare solutions. Digital startups benefit from the pharma sector’s manufacturing scale, clinical networks, and commercial channels.
- For instance, Propeller Health partnered with AstraZeneca to integrate its digital platform with the Symbicort inhaler, receiving FDA clearance in 2020. Clinical studies show the Propeller platform supports 90% of inhaled COPD and asthma medications on the U.S. market, and the partnership aims to improve medication adherence and reduce hospitalizations.
Expansion of Cloud-Enabled Platforms and Data Interoperability:
Smart inhalers are increasingly being designed to integrate with broader digital health ecosystems via cloud-based infrastructure. Real-time inhaler usage data can now be stored, analyzed, and shared securely across multiple stakeholders, including clinicians, caregivers, and researchers. The Global Smart Inhalers Market is adopting interoperable solutions that align with electronic health records (EHRs) and remote patient monitoring systems. This connectivity supports more coordinated care, timely interventions, and comprehensive patient management. The move toward cloud architecture enables scalability and cross-platform compatibility across mobile devices and healthcare systems. Cloud integration is no longer a feature but a core expectation in product design.
Growing Emphasis on Pediatric and Geriatric Use Cases:
Manufacturers are tailoring smart inhaler solutions to meet the specific needs of pediatric and elderly populations. These patient groups often face greater challenges with manual device use, medication adherence, and understanding treatment regimens. The Global Smart Inhalers Market is responding with user-friendly designs, voice-enabled interfaces, and simplified data visualizations suited for non-technical users. Devices are also incorporating caregiver access features, allowing remote supervision and support. Pediatric applications are gaining traction in school-based asthma programs, while geriatric use is expanding in home-based care models. This trend reflects a shift toward inclusive, accessible respiratory care across diverse age groups.
Market Challenges Analysis:
High Cost of Smart Inhaler Devices Limits Widespread Adoption:
The relatively high cost of smart inhalers compared to conventional inhalers remains a significant barrier, particularly in low- and middle-income markets. These devices require embedded electronics, connectivity modules, and software integration, which increase production and retail costs. Many healthcare systems still operate under tight budget constraints and may hesitate to approve reimbursement for digitally enhanced devices. The Global Smart Inhalers Market faces challenges in demonstrating cost-effectiveness at scale, especially in public health programs. Patients without insurance coverage or access to value-based care models may not afford these advanced therapies. Manufacturers must address pricing concerns through scalable production, value-based pricing models, or broader payer engagement.
Data Privacy Concerns and Technical Integration Issues Slow Implementation:
Smart inhalers generate sensitive health data that must comply with stringent regulatory standards such as HIPAA and GDPR. Concerns around data storage, cybersecurity, and patient consent create hesitation among providers and patients. Interoperability with existing electronic health records (EHRs) and telehealth systems also poses technical hurdles. The Global Smart Inhalers Market must overcome fragmented digital ecosystems that lack standardization in data exchange. Poor integration can disrupt workflow efficiency and reduce clinician willingness to adopt connected inhaler platforms. Developers need to ensure secure, seamless data flow across systems to maximize clinical utility and maintain trust in digital respiratory solutions.
Market Opportunities:
Expansion into Emerging Markets with Growing Respiratory Disease Burden:
Emerging economies present strong opportunities for market penetration as asthma and COPD rates rise due to urbanization, pollution, and smoking prevalence. Countries in Asia-Pacific, Latin America, and the Middle East are investing in healthcare digitization and expanding chronic disease programs. The Global Smart Inhalers Market can leverage these developments by introducing cost-effective, mobile-compatible solutions tailored to local infrastructure. Partnerships with public health agencies and local distributors can accelerate adoption and training efforts. Governments are showing interest in preventive care models that reduce long-term hospitalization costs. Device manufacturers that offer scalable platforms will gain early traction in underserved markets.
Integration with Broader Digital Health Ecosystems and Value-Based Care Models:
The shift toward value-based care models opens the door for smart inhalers to demonstrate measurable improvements in clinical outcomes and cost savings. Health systems are actively seeking technologies that reduce emergency visits and optimize chronic disease management. The Global Smart Inhalers Market can expand by aligning products with remote monitoring platforms, electronic health records, and digital therapeutic programs. Seamless integration enables real-time care adjustments and strengthens payer-provider collaboration. As reimbursement policies evolve to support digital tools, connected inhalers can play a key role in long-term respiratory health strategies. This creates sustained demand for intelligent, interoperable device ecosystems.
Market Segmentation Analysis:
By Type
The market is categorized into Dry Powdered Inhalers (DPIs) and Metered Dose Inhalers (MDIs). DPIs hold a significant share due to ease of administration and breath-actuated mechanisms, which improve usability and adherence. MDIs remain widely used, supported by decades of clinical acceptance and compatibility with smart sensor add-ons.
- For instance, Novartis’ Breezhaler (Enerzair Breezhaler) is a once-daily DPI approved for asthma maintenance and offers an optional digital companion for dose confirmation and adherence tracking.
By Indication
Asthma dominates this segment owing to its high global prevalence and need for consistent medication adherence. COPD follows, driven by the growing elderly population and chronic disease burden. The "others" category includes less common respiratory conditions that contribute modestly to market demand.
- For instance, the Ellipta inhaler by GSK has demonstrated consistent dose delivery over a 30-day in-use period, supporting both asthma and COPD management with once-daily therapies.
By End-use
Hospitals lead the market due to advanced infrastructure and higher deployment of connected health tools. Homecare settings are gaining momentum as patients and caregivers adopt remote monitoring devices for convenience and continuity. The “others” segment includes specialty clinics and ambulatory centers with steady but smaller adoption rates.
By Distribution Channel
Hospital pharmacies account for the largest revenue share, supported by centralized purchasing systems and inpatient care requirements. Retail pharmacies contribute significantly by providing over-the-counter and prescription smart inhalers to walk-in customers. Online pharmacies are expanding rapidly, driven by digital health trends and consumer preference for doorstep delivery.
Segmentation:
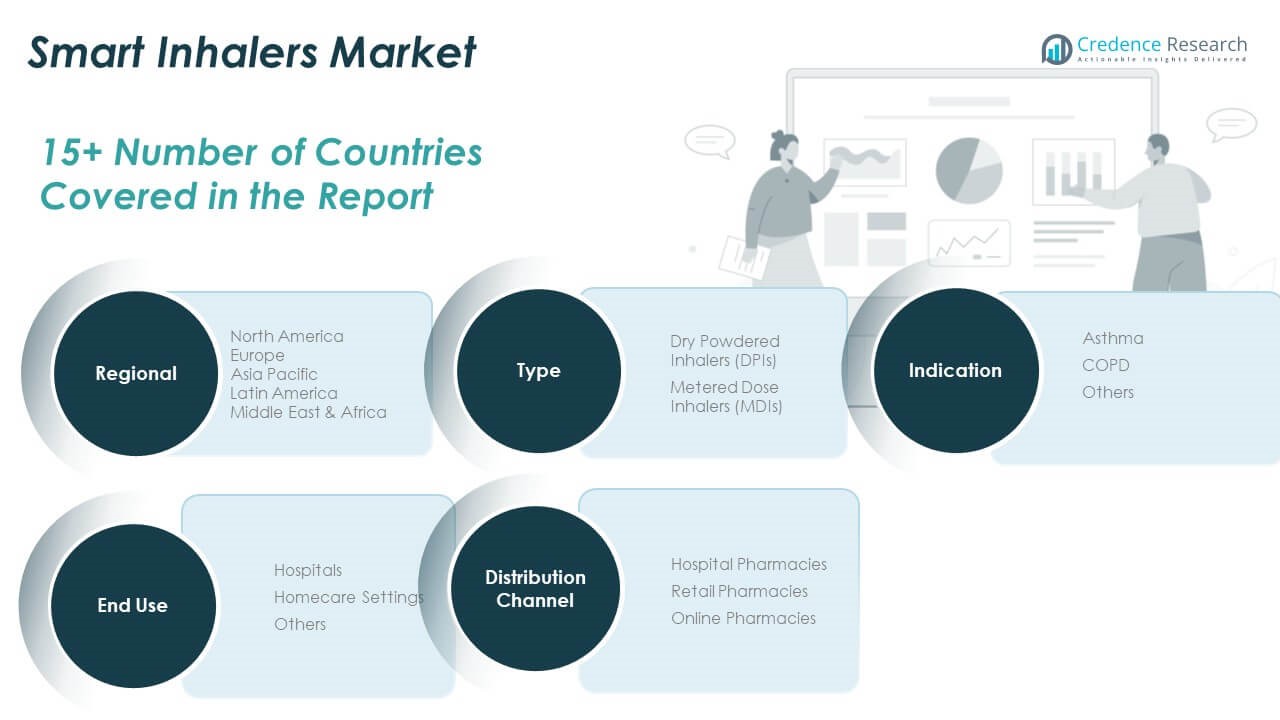
By Type
- Dry Powdered Inhalers (DPIs)
- Metered Dose Inhalers (MDIs)
By Indication
- Asthma
- COPD
- Others
By End-use
- Hospitals
- Homecare Settings
- Others
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Regional Analysis:
North America
The North America Smart Inhalers Market size was valued at USD 4,530.30 million in 2018 to USD 8,780.76 million in 2024 and is anticipated to reach USD 35,741.83 million by 2032, at a CAGR of 19.3% during the forecast period. North America holds the largest share of the Global Smart Inhalers Market. High healthcare spending, early adoption of connected medical devices, and a significant asthma and COPD burden are driving demand. The U.S. leads in smart inhaler deployment, supported by favorable reimbursement policies and regulatory clarity. Strong collaboration between pharmaceutical and digital health companies is advancing innovation. It benefits from widespread use of mobile health platforms and increasing focus on adherence solutions. The region remains a key hub for product development and commercialization.
Europe
The Europe Smart Inhalers Market size was valued at USD 2,054.20 million in 2018 to USD 3,819.71 million in 2024 and is anticipated to reach USD 14,441.91 million by 2032, at a CAGR of 18.2% during the forecast period. Europe is a major contributor to the Global Smart Inhalers Market, driven by public healthcare models and chronic disease management programs. Countries like Germany, the UK, and France have integrated smart inhalers into national digital health strategies. Market growth is supported by regulatory alignment and clinical emphasis on long-term monitoring. It benefits from patient-centric care models that encourage adherence to therapy. The region also shows strong activity in digital therapeutics partnerships and R&D funding.
Asia Pacific
The Asia Pacific Smart Inhalers Market size was valued at USD 2,360.58 million in 2018 to USD 4,833.73 million in 2024 and is anticipated to reach USD 21,816.84 million by 2032, at a CAGR of 20.8% during the forecast period. Asia Pacific is the fastest-growing region in the Global Smart Inhalers Market. Rising respiratory disorders due to urbanization and pollution are accelerating product demand. Countries like China, India, and Japan are adopting digital health solutions through government initiatives and private investments. It shows increasing penetration of remote monitoring and smart drug delivery systems. Expanding healthcare access and mobile infrastructure support broad market potential. Local manufacturing partnerships are further improving product availability.
Latin America
The Latin America Smart Inhalers Market size was valued at USD 580.60 million in 2018 to USD 1,124.45 million in 2024 and is anticipated to reach USD 4,219.94 million by 2032, at a CAGR of 18.1% during the forecast period. Latin America is an emerging market for smart inhalers with growing awareness of chronic respiratory care. Brazil and Mexico are leading in adoption due to healthcare reforms and expanding urban populations. Retail pharmacies and mobile platforms are increasing access to connected devices. It is gradually integrating digital tools into chronic disease management frameworks. Infrastructure and affordability barriers still exist, but pilot programs and partnerships are improving reach. The region shows steady growth potential with targeted investments.
Middle East
The Middle East Smart Inhalers Market size was valued at USD 436.96 million in 2018 to USD 807.96 million in 2024 and is anticipated to reach USD 3,012.97 million by 2032, at a CAGR of 18.0% during the forecast period. The Middle East is witnessing a steady rise in smart inhaler adoption, particularly in GCC countries. Healthcare modernization and government-backed digital health initiatives are fueling growth. Telemedicine integration and increased awareness of respiratory conditions support demand. It is benefiting from hospital infrastructure upgrades and clinician training. Variations in regulatory frameworks and pricing strategies influence country-specific uptake. Investment in innovation hubs and connected care ecosystems is strengthening regional capabilities.
Africa
The Africa Smart Inhalers Market size was valued at USD 82.37 million in 2018 to USD 295.00 million in 2024 and is anticipated to reach USD 886.87 million by 2032, at a CAGR of 13.9% during the forecast period. Africa holds a small but growing share in the Global Smart Inhalers Market. South Africa leads in regional adoption due to stronger private healthcare presence. Awareness of asthma and COPD treatment is improving, but access to smart devices remains limited. It is supported by international aid programs and localized initiatives to improve respiratory care. High device cost and low digital penetration hinder widespread usage. Progress depends on infrastructure investments and broader healthcare policy reforms.
Key Player Analysis:
- Presspart Verwaltungs GmbH.
- Personal Air Quality Systems Pvt Ltd
- COHERO Health Inc. (AptarGroup, Inc.)
- Cognita Labs
- Adherium
- Amiko Digital Health Limited
- Teva Pharmaceuticals Industries Ltd.
- Propeller Health (ResMed)
- Novartis AG
- Pneuma Respiratory Inc.
- 3M
- AireHealth, Inc.
- FindAir Sp. z o.o.
Competitive Analysis:
The Global Smart Inhalers Market is moderately concentrated, with a mix of established pharmaceutical companies and emerging digital health firms competing for market share. Key players include Teva Pharmaceuticals, AstraZeneca, GlaxoSmithKline, Propeller Health (ResMed), Adherium, and AptarGroup. These companies focus on integrating sensors, mobile connectivity, and analytics into inhaler platforms to enhance treatment adherence and real-time monitoring. It is characterized by strategic partnerships between pharma and tech firms, accelerating product development and regulatory approvals. Competitors differentiate through device usability, app functionality, and compatibility with broader digital health systems. Investment in AI integration, cloud-based platforms, and user-friendly designs is intensifying. Market participants continue to seek global expansion through regional collaborations, distribution networks, and clinical validation. The competitive environment favors companies that offer clinically proven, scalable solutions aligned with value-based care and remote patient management trends.
Recent Developments:
- In September 2024, Presspart Verwaltungs GmbH (H&T Presspart) announced a major investment in its metered-dose inhaler dose counter manufacturing capacity at the Marsberg, Germany facility. The company added a new production line for dose counters aimed at supporting rising demand for pMDIs with integrated sensors.
- In October 2024, H&T Presspart entered a strategic partnership with invoX Pharma to manufacture the device sub-assembly for the commercial launch of the Softhaler®, a complex soft mist inhalation (SMI) device. H&T Presspart now supports large-scale production of the component in their cleanroom facility in Tarragona, Spain .
Market Concentration & Characteristics:
The Global Smart Inhalers Market shows moderate concentration, with a few leading pharmaceutical and digital health companies controlling a significant portion of market share through proprietary technologies and strong distribution networks. It is characterized by a combination of drug-device integration, app-based platforms, and real-time monitoring features that support chronic respiratory care. The market favors players with robust R&D capabilities, regulatory expertise, and the ability to deliver scalable, interoperable solutions. Adoption depends on clinical validation, user-friendly interfaces, and compatibility with digital health systems. Strategic collaborations between pharma firms and health tech startups are shaping product innovation and accelerating market entry. It continues to evolve with increasing focus on personalized care, remote monitoring, and digital therapeutic integration.
Report Coverage:
The research report offers an in-depth analysis based on type, indication, end-use, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising global prevalence of asthma and COPD will sustain long-term demand for smart inhaler solutions.
- Integration of AI and predictive analytics will enhance personalized treatment and early intervention.
- Wider adoption of remote patient monitoring will drive smart inhaler use in home-based care models.
- Expansion into emerging markets will open new growth avenues through scalable, mobile-first solutions.
- Cloud connectivity and EHR integration will become standard features across leading product platforms.
- Pediatric and geriatric-focused designs will increase device accessibility and broaden user adoption.
- Reimbursement policy reforms will support commercial viability in public and private healthcare systems.
- Strategic alliances between pharma and tech firms will accelerate innovation and global reach.
- Demand for digital therapeutics will grow, positioning smart inhalers as central tools in hybrid care models.
- Regulatory approval of advanced drug-device combinations will strengthen market competitiveness and credibility.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Asthma and COPD
The increasing global burden of chronic respiratory diseases, particularly asthma and COPD, is driving demand for smart inhalers that support better disease management and adherence, especially as these conditions affect over 300 million people worldwide.
Adoption of Digital Health and Remote Monitoring
Healthcare systems are rapidly integrating telemedicine and remote monitoring technologies, with smart inhalers enabling real-time data sharing, dose tracking, and virtual consultations, thus improving treatment precision and patient engagement.
Supportive Regulatory and Reimbursement Policies
Favorable regulatory frameworks and evolving reimbursement policies in regions like North America and Europe are accelerating the adoption of smart inhalers by making them more accessible and commercially viable within public and private healthcare systems.
Focus on Improving Medication Adherence
Smart inhalers address the critical issue of medication non-adherence by providing reminders, usage alerts, and behavioral insights, which have been shown to improve adherence rates by up to 59% and reduce hospital admissions.
Technological Advancements and AI Integration
The integration of artificial intelligence and cloud connectivity into smart inhaler platforms enables predictive analytics, personalized interventions, and seamless interoperability with electronic health records, enhancing clinical outcomes and supporting value-based care models.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Smart Inhalers Market?
What factors are driving the growth of the Global Smart Inhalers Market?
What are the key segments within the Global Smart Inhalers Market?
What are some challenges faced by the Global Smart Inhalers Market?
Who are the major players in the Global Smart Inhalers Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Dry Powdered Inhalers (DPIs)
- 1.2.2 Metered Dose Inhalers (MDIs)
- 1.3 By End-use
- 1.3.1 Hospitals
- 1.3.2 Homecare Settings
- 1.3.3 Others
- 1.4 By Indication
- 1.4.1 Asthma
- 1.4.2 COPD
- 1.4.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 19,661.62 million → 2032: USD 80,120.35 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Smart Inhalers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Smart Inhalers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Smart Inhalers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Smart Inhalers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Smart Inhalers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Smart Inhalers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Smart Inhalers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Smart Inhalers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 19,661.62 million → 2032: USD 80,120.35 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Smart Inhalers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Dry Powdered Inhalers (DPIs)
- 12.3.7.2 Metered Dose Inhalers (MDIs)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Homecare Settings
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Indication - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Asthma
- 12.5.7.2 COPD
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Smart Inhalers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Smart Inhalers Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Smart Inhalers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Smart Inhalers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Teva Pharmaceuticals Industries Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Propeller Health (ResMed)
- 18.4 Adherium
- 18.5 Novartis AG
- 18.6 GlaxoSmithKline plc
- 18.7 AstraZeneca plc
- 18.8 COHERO Health Inc. (AptarGroup, Inc.)
- 18.9 Presspart Verwaltungs GmbH
- 18.10 Amiko Digital Health Limited
- 18.11 Cognita Labs
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

