
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Kidney Dialysis Equipment Market Size 2024 | USD 21,415 Million |
| Kidney Dialysis Equipment Market, CAGR | 5.5% |
| Kidney Dialysis Equipment Market Size 2032 | USD 32,864.54 Million |
Market Overview:
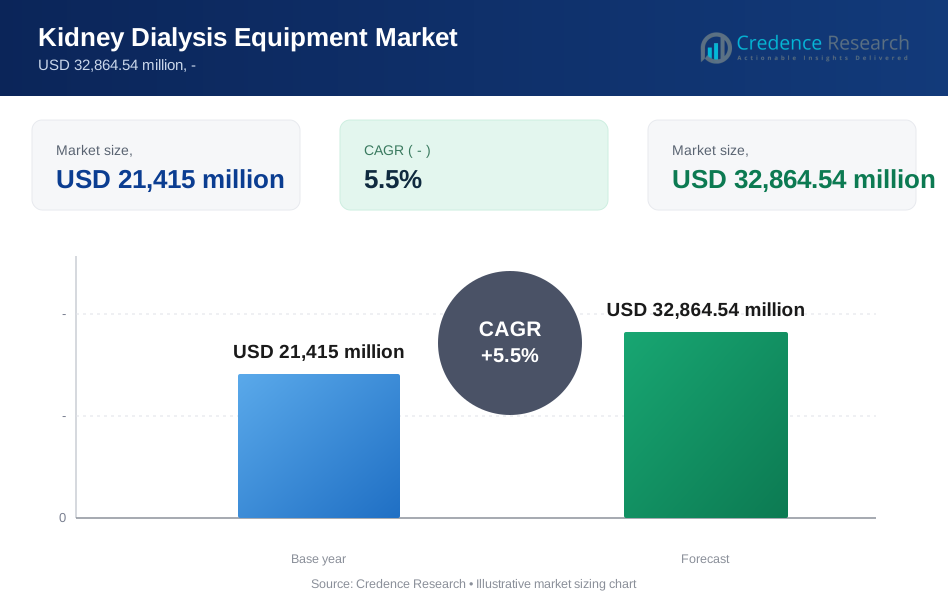
The Kidney Dialysis Equipment Market is experiencing robust growth, driven by the increasing prevalence of kidney diseases and advancements in dialysis technologies. As of 2024, the global Kidney Dialysis Equipment Market is valued at USD 21,415 million and is projected to grow at a compound annual growth rate (CAGR) of 5.5% over the forecast period, reaching approximately USD 32,864.54 million by 2032. This growth underscores the rising demand for effective treatment options for patients with chronic kidney failure and the continuous innovation in dialysis equipment.
Several key factors are propelling the market's expansion. The increasing incidence of diabetes and hypertension, which are major risk factors for kidney disease, is significantly driving demand for dialysis services. Additionally, advancements in dialysis technologies, including the development of portable and home-based dialysis machines, are making treatment more accessible and convenient for patients. The emphasis on improving patient quality of life and outcomes is further pushing healthcare providers to adopt state-of-the-art dialysis equipment.
Regionally, North America dominates the Kidney Dialysis Equipment Market, primarily due to a high prevalence of kidney disorders and a well-established healthcare infrastructure. The presence of major market players and continuous technological advancements also contribute to this region's leadership. Europe follows closely, with similar trends observed, including a strong focus on improving healthcare services and patient outcomes. The Asia-Pacific region is anticipated to exhibit significant growth during the forecast period, driven by the increasing healthcare expenditure, rising awareness about kidney health, and government initiatives aimed at improving dialysis access. Emerging economies like India and China present substantial growth opportunities due to their large patient populations and increasing investments in healthcare infrastructure.
Market Drivers:
Growing Prevalence of Kidney Diseases:
The rising incidence of chronic kidney diseases (CKD) globally is a major driver of the kidney dialysis equipment market. According to the World Health Organization (WHO), CKD is estimated to affect approximately 13% of the global population, and this percentage is projected to rise due to factors such as increasing diabetes and hypertension rates. The World Bank reports that the burden of kidney disease is particularly pronounced in low- and middle-income countries, where access to treatment remains limited. This escalating prevalence necessitates the development and provision of advanced dialysis solutions to cater to the growing patient population, thereby propelling market growth.
Technological Advancements in Dialysis Equipment:
Technological innovation plays a crucial role in shaping the kidney dialysis equipment market. The introduction of sophisticated dialysis systems enhances patient outcomes and improves the efficiency of treatment. For instance, in February 2024, Fresenius Medical Care (FME) received FDA 510(k) clearance for its 5008X Hemodialysis System. This system represents a significant leap forward in establishing a new standard of care for dialysis therapy, emphasizing the importance of regulatory approval in facilitating market entry for advanced technologies. According to research by the International Monetary Fund (IMF), investment in healthcare technology is projected to increase by approximately 5% annually, highlighting the economic incentive for companies to innovate in this field.
Rising Demand for Home Dialysis Solutions:
The shift toward home-based dialysis is another significant driver influencing the market landscape. With the increasing number of patients opting for home dialysis due to its convenience and enhanced quality of life, the demand for portable and user-friendly dialysis equipment has surged. The WHO has highlighted that home dialysis can significantly reduce healthcare costs and improve patient satisfaction, making it a preferred choice among patients and healthcare providers alike. Research indicates that the home dialysis segment is expected to grow at a rate of 8% annually over the next five years. For instance, Fresenius Medical Care reported a 15% increase in home dialysis patients in 2023, with their NxStage home hemodialysis system being used by over 25,000 patients worldwide. Companies are responding to this trend by developing products that are not only effective but also easier for patients to use in a home setting, further driving market expansion.
Supportive Government Initiatives and Policies:
Government initiatives and healthcare policies are vital in promoting the kidney dialysis equipment market. Various health authorities, including the Centers for Medicare & Medicaid Services (CMS) in the U.S., have implemented policies that encourage the use of dialysis equipment and support reimbursement for these services. Such measures create a conducive environment for market growth by ensuring that both patients and providers have access to necessary equipment. The World Bank has noted that investments in healthcare infrastructure in developing regions, particularly in Africa and Asia, are expected to rise, with a focus on chronic disease management, including kidney diseases. For instance, European Kidney Health Alliance (EKHA) successfully lobbied for the inclusion of kidney disease management in the EU4Health programme, securing €5.1 billion in funding for 2021-2027. This investment is projected to increase by approximately 7% over the next five years, reflecting the commitment of governments to improve healthcare access and quality. the kidney dialysis equipment market is being driven by a combination of factors including the increasing prevalence of kidney diseases, advancements in technology, rising demand for home dialysis solutions, and supportive government initiatives. As companies continue to innovate and respond to these market dynamics, the industry is poised for significant growth in the coming years.
Market Trends:
Increasing Focus on Personalized Medicine:
The trend toward personalized medicine is gaining traction within the kidney dialysis equipment market. As healthcare becomes more tailored to individual patient needs, manufacturers are investing in developing equipment that can be customized for specific renal conditions. According to research by the World Health Organization (WHO), personalized approaches to treatment can significantly enhance patient outcomes and satisfaction. In line with this, companies are exploring ways to integrate artificial intelligence and machine learning into their dialysis systems, enabling real-time monitoring and adjustment of treatment protocols based on individual patient data. This shift not only improves the effectiveness of dialysis but also aligns with global healthcare trends emphasizing personalized care, which is anticipated to increase patient compliance and overall success rates.
Expanding Access to Innovative Dialysis Solutions:
Another prominent trend is the concerted effort to expand access to innovative dialysis solutions, particularly in underserved regions. The World Bank has noted that equitable access to healthcare technologies is critical for managing chronic diseases like kidney failure, especially in developing countries. To address this gap, governments and health organizations are increasingly partnering with private companies to provide affordable dialysis equipment and training for healthcare providers. For instance, in August 2023, Quanta Dialysis Technologies secured USFDA clearance to expand the indications for its Quanta Dialysis System. This approval enables the system to be utilized for dialysis treatment in patients suffering from acute kidney issues, thereby increasing its accessibility. Such initiatives underscore a growing commitment to ensuring that all patients, regardless of their geographic location, have access to high-quality dialysis care, promoting better health outcomes across diverse populations. These trends highlight the dynamic nature of the kidney dialysis equipment market, driven by innovations in personalized care and efforts to enhance accessibility. As the market evolves, stakeholders are poised to play a crucial role in shaping the future of dialysis treatment worldwide.
Market Challenge Analysis:
Regulatory Compliance and Reimbursement Issues:
One of the primary challenges facing the Kidney Dialysis Equipment Market is navigating the complex landscape of regulatory compliance and reimbursement policies. The healthcare industry is heavily regulated, with varying standards set by authorities across different regions. Companies must ensure that their products meet stringent safety and efficacy criteria before receiving approval for market entry. This process can be time-consuming and costly, often delaying the launch of new technologies. Additionally, manufacturers must stay updated with evolving regulations, which can differ significantly between countries, further complicating their operational strategies.
Reimbursement policies also present significant challenges. While the demand for dialysis treatment is high, the reimbursement rates set by government and private payers can vary, impacting the profitability of dialysis providers. Healthcare facilities often face pressure to manage costs while delivering quality care, which can lead to hesitance in adopting new, potentially more expensive technologies. This situation necessitates a robust business case to justify investments in advanced equipment, creating a barrier for both manufacturers and healthcare providers aiming to innovate and improve patient care.
Market Competition and Price Sensitivity:
Another major challenge in the Kidney Dialysis Equipment Market is intense competition and price sensitivity. Numerous established players and new entrants vie for market share, leading to a crowded landscape where differentiation becomes crucial. Companies must constantly innovate and enhance their product offerings to stand out, which often requires significant investment in research and development. As a result, the financial burden on manufacturers can be substantial, especially for smaller firms that may lack the resources to compete effectively with larger corporations.
Moreover, price sensitivity among healthcare providers complicates the market dynamics. Many dialysis facilities operate on tight budgets, and their purchasing decisions are heavily influenced by cost considerations. This price pressure can lead to a race to the bottom, forcing manufacturers to lower prices, which may impact their profit margins. To navigate this challenge, companies must focus on demonstrating the long-term value and improved patient outcomes associated with their products, ensuring that they communicate the benefits of investing in higher-quality dialysis equipment while remaining competitive in pricing.
Market Segmentation Analysis:
By Type The Kidney Dialysis Equipment Market is segmented into hemodialysis and peritoneal dialysis. Hemodialysis equipment includes machines and related components that filter blood through an external device, while peritoneal dialysis involves using the patient's abdominal lining to filter waste and excess fluid. The hemodialysis segment holds a larger market share due to its widespread use in clinical settings and hospitals, driven by the growing number of patients requiring renal replacement therapy.
By Technology The market is categorized by technology into conventional dialysis and automated dialysis. Conventional dialysis refers to traditional methods that require manual setup and operation, whereas automated dialysis includes advanced systems that offer greater efficiency and convenience, such as home dialysis machines. The automated dialysis segment is gaining traction as it enhances patient independence and quality of life, contributing to its increasing market share.
By End-User The end-user segmentation of the Kidney Dialysis Equipment Market includes hospitals, dialysis centers, and home care settings. Hospitals and dialysis centers are the primary users due to their capacity to provide comprehensive renal care. However, the home care segment is expected to grow significantly, fueled by the rising preference for home-based treatments among patients seeking more flexible and comfortable care options. This shift reflects a broader trend towards patient-centric healthcare solutions.
Segmentation:
Based on Product Type:
- Hemodialysis Equipment
- Peritoneal Dialysis Equipment
Based on Technology:
- Conventional Dialysis
- Automated Dialysis
Based on End-User:
- Hospitals
- Dialysis Centers
- Home Care Settings
Based on Region:
- North America
- United States
- Canada
- Europe
- Germany
- United Kingdom
- France
- Italy
- Asia-Pacific
- China
- India
- Japan
- Australia
- Latin America
- Brazil
- Mexico
- Middle East and Africa
- South Africa
- UAE
Regional Analysis:
North America (40% Market Share)
North America dominates the Kidney Dialysis Equipment Market, holding approximately 40% of the global market share. This leadership position can be attributed to several factors, including the high prevalence of chronic kidney diseases, particularly in the United States, where diabetes and hypertension are significant risk factors. The region boasts advanced healthcare infrastructure, allowing for the integration of the latest technologies in dialysis equipment. Additionally, the presence of major players such as Fresenius Medical Care and Baxter International enhances innovation and competitive dynamics, fostering an environment conducive to technological advancements.
Moreover, strong reimbursement policies and government support for renal care significantly contribute to market growth in North America. The Centers for Medicare & Medicaid Services (CMS) provides favorable reimbursement rates for dialysis treatments, encouraging healthcare providers to adopt newer and more efficient technologies. This regulatory environment facilitates access to care and drives investment in high-quality dialysis equipment. Furthermore, the increasing trend toward home dialysis options is reshaping the landscape, as patients seek greater flexibility and autonomy in their treatment options.
Europe (30% Market Share)
Europe holds a substantial share of the Kidney Dialysis Equipment Market, accounting for approximately 30%. The region is characterized by stringent healthcare regulations and a strong emphasis on patient safety and quality of care. Countries such as Germany, the United Kingdom, and France are leading the way in adopting advanced dialysis technologies. The aging population in Europe, coupled with a rising incidence of kidney-related disorders, propels the demand for dialysis services and equipment.
European healthcare systems are increasingly focusing on improving operational efficiency, which creates opportunities for innovative dialysis solutions. Initiatives aimed at enhancing patient outcomes and reducing hospitalization rates are driving healthcare providers to invest in modern dialysis technologies. Moreover, the European Union’s regulatory framework encourages manufacturers to ensure compliance with high standards, fostering a competitive market environment. This regulatory rigor ultimately benefits patients through the availability of safer and more effective dialysis options.
Asia-Pacific (25% Market Share)
The Asia-Pacific region is rapidly emerging as a high-growth market in the Kidney Dialysis Equipment sector, with a market share of approximately 25%. Factors contributing to this growth include rising healthcare expenditures, improving healthcare infrastructure, and an increasing awareness of chronic kidney diseases among the population. Countries like China and India are witnessing a surge in the prevalence of diabetes and hypertension, leading to a higher demand for dialysis services. Government initiatives aimed at expanding access to healthcare and improving renal care are also driving growth in this region. For instance, both China and India are investing significantly in healthcare infrastructure, which includes the establishment of more dialysis centers. Additionally, the rising middle-class population is increasing the demand for quality healthcare services, including dialysis treatment. The shift towards home dialysis solutions is gaining traction as patients and caregivers seek more convenient and flexible treatment options.
Despite the promising growth prospects, the Asia-Pacific region faces challenges such as price sensitivity and varying levels of healthcare access across countries. To navigate these challenges, manufacturers must focus on cost-effective solutions while ensuring quality and reliability. The region presents vast opportunities for market players who can adapt to the unique needs of diverse populations and leverage advancements in technology to enhance patient care.
Key Player Analysis:
- Resenius Medical Care AG & Co. KGaA
- Baxter International Inc.
- Davita Inc.
- B. Braun Melsungen AG
- Asahi Kasei Corporation
- Nipro Corporation
- Cantel Medical Corporation
- Nikkiso Co., Ltd.
- Medical Care AG & Co. KGaA
- Diaverum Deutschland GmbH
- Medtronic PLC
- Toray Medical Co., Ltd.
- Allmed Medical Corp.
- Bain Medical Equipment
- JMS Co. Ltd.
- HEMOCLEAN CO., LTD.
Competitive Analysis:
The Kidney Dialysis Equipment Market is characterized by intense competition among several key players, each striving to enhance their market share through innovation and strategic positioning. Major companies like Fresenius Medical Care, Baxter International, and Nipro Medical Corporation dominate the landscape, leveraging their extensive product portfolios and established distribution networks. Fresenius, in particular, is recognized for its comprehensive range of dialysis products and services, allowing it to maintain a significant market presence. Baxter International is also notable for its focus on innovative dialysis solutions, particularly in home dialysis systems, which aligns with the growing patient preference for at-home treatments. Emerging players in the market are challenging the status quo by introducing cost-effective solutions and utilizing advanced technologies, such as artificial intelligence and remote monitoring capabilities, to enhance patient outcomes. Companies like Quanta Dialysis Technologies are gaining traction by offering portable and automated dialysis systems that cater to the increasing demand for flexible treatment options. Additionally, strategic partnerships and collaborations among manufacturers and healthcare providers are becoming more common, aimed at improving access to dialysis services and fostering innovation. Pricing strategies are a critical factor in this competitive environment, as healthcare providers often face budget constraints. Companies must balance quality with affordability to remain competitive. As the market evolves, firms are also focusing on sustainability and environmentally friendly practices, which are increasingly important to consumers and regulatory bodies alike. Overall, the competitive landscape in the Kidney Dialysis Equipment Market is dynamic, driven by technological advancements, changing patient preferences, and regulatory requirements, compelling companies to continuously innovate and adapt to maintain their competitive edge.
Recent Developments:
- In February 2024, Fresenius Medical Care (FME), a leading global provider of products and services for individuals with renal diseases, received FDA 510(k) clearance for its 5008X Hemodialysis System. This clearance represents a significant advancement in establishing a new standard of care for dialysis therapy for kidney disease patients in the U.S.
- In March 2022, Nipro Medical Corporation, a medical equipment manufacturer, launched the SURDIAL DX Hemodialysis System in the United States, broadening its portfolio of renal, vascular, and medical-surgical products.
- In August 2023, Quanta Dialysis Technologies secured USFDA clearance to expand the indications for its Quanta Dialysis System. This approval allows the system to be used for dialysis treatment in patients suffering from acute kidney issues.
Market Concentration & Characteristics:
The Kidney Dialysis Equipment Market exhibits moderate to high concentration, with several key players holding significant market shares while also facing competition from emerging companies. Major manufacturers such as Fresenius Medical Care, Baxter International, and Nipro Medical Corporation dominate the landscape, collectively accounting for a substantial portion of the market. These established firms benefit from extensive distribution networks, established brand reputations, and strong financial resources, allowing them to invest heavily in research and development. This enables them to introduce innovative products and technologies, such as automated and home dialysis systems, which cater to evolving patient needs. The market is characterized by rapid technological advancements, particularly in automation and telehealth integration, which enhance the efficiency and convenience of dialysis treatments. Additionally, there is a growing trend towards patient-centric solutions, with a focus on improving patient outcomes and quality of life. Companies are increasingly adopting strategies that emphasize collaboration with healthcare providers to ensure that their products meet clinical needs effectively. Despite the presence of dominant players, the market also sees a rise in smaller firms that focus on niche segments or offer cost-effective alternatives, fostering a competitive environment that drives innovation. Price sensitivity among healthcare providers further influences market dynamics, as budget constraints push manufacturers to balance quality with affordability. As regulatory requirements evolve, companies must remain agile and responsive to maintain compliance while pursuing growth opportunities. Overall, the Kidney Dialysis Equipment Market is marked by a blend of established leadership and emerging competition, driving continuous improvement and adaptation within the industry.
Report Coverage:
This report provides a comprehensive analysis of the Kidney Dialysis Equipment Market, examining key trends, drivers, challenges, and competitive dynamics from 2024 to 2032. It covers various segments, including product types such as hemodialysis and peritoneal dialysis equipment, as well as technological advancements in conventional and automated dialysis systems. The report also delves into market dynamics across different end-users, including hospitals, dialysis centers, and home care settings. A regional analysis highlights the market's landscape in North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa, focusing on each region's unique growth drivers and challenges. Additionally, the report offers insights into the market concentration and characteristics, outlining the competitive environment dominated by major players like Fresenius Medical Care and Baxter International, alongside emerging firms innovating in niche areas. It also discusses regulatory compliance, reimbursement issues, and price sensitivity as critical factors shaping market dynamics. Overall, this report serves as a valuable resource for stakeholders, including investors, healthcare providers, and manufacturers, seeking to understand the evolving Kidney Dialysis Equipment Market landscape and identify growth opportunities in the coming years.
Future Outlook:
- The Kidney Dialysis Equipment Market is expected to grow significantly, driven by the rising prevalence of chronic kidney diseases worldwide.
- Advancements in technology, including automated and portable dialysis systems, will enhance patient convenience and treatment effectiveness.
- Increased focus on home dialysis options will create new opportunities for manufacturers and improve patient autonomy.
- Regulatory frameworks are likely to evolve, promoting innovation while ensuring patient safety and quality care.
- Strategic partnerships between manufacturers and healthcare providers will become more common to enhance service delivery.
- The demand for telehealth solutions will rise, enabling remote patient monitoring and management.
- Emerging markets in Asia-Pacific will see rapid growth due to improving healthcare infrastructure and rising awareness of kidney health.
- Sustainability and environmentally friendly practices will become increasingly important in product development and manufacturing.
- Price sensitivity will continue to influence purchasing decisions, prompting manufacturers to offer cost-effective solutions without compromising quality.
- Overall, the market will witness dynamic changes, driven by technological innovation and shifting patient needs over the next decade.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current value of the global Kidney Dialysis Equipment Market?
How much is the market expected to grow by 2032?
What are the main factors driving the market's growth?
Which region leads the Kidney Dialysis Equipment Market?
Which region is expected to show significant growth in the coming years?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Kidney Dialysis Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Kidney Dialysis Equipment Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 21,415 million → forecast year: USD 32,864.54 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Kidney Dialysis Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Kidney Dialysis Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Kidney Dialysis Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Kidney Dialysis Equipment Market Drivers
- 3.3 Kidney Dialysis Equipment Market Restraints & Challenges
- 3.4 Kidney Dialysis Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Kidney Dialysis Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Kidney Dialysis Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Kidney Dialysis Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Kidney Dialysis Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Kidney Dialysis Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Kidney Dialysis Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Kidney Dialysis Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Kidney Dialysis Equipment Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Kidney Dialysis Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Kidney Dialysis Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Kidney Dialysis Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Kidney Dialysis Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Kidney Dialysis Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Kidney Dialysis Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Kidney Dialysis Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Kidney Dialysis Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Kidney Dialysis Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Kidney Dialysis Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Kidney Dialysis Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
