
Chronic Kidney Disease Market Overview:
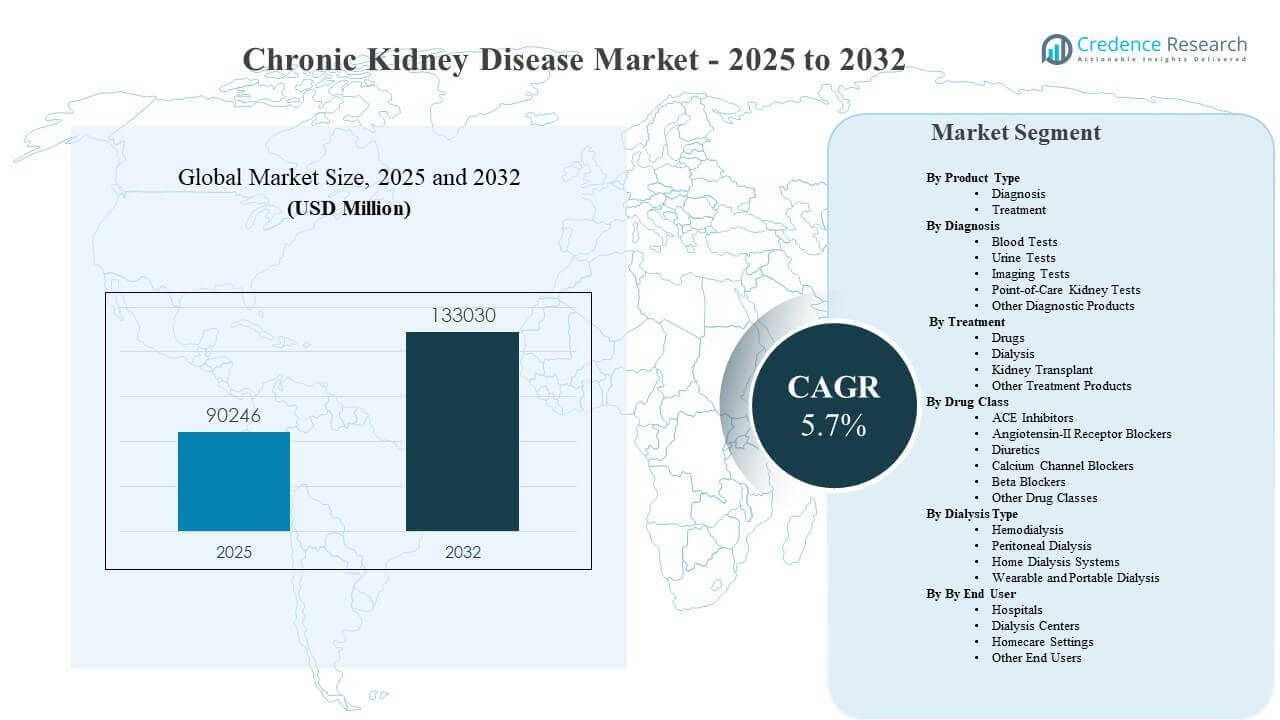
The global Chronic Kidney Disease Market size was estimated at USD 90,246 million in 2025 and is expected to reach USD 133,030 million by 2032, growing at a CAGR of 5.7% from 2025 to 2032. Demand is being driven by the sustained rise in diabetes and hypertension burdens, which expands the diagnosed and treated CKD population across early-stage management and late-stage renal replacement therapy. Growing emphasis on earlier detection and progression-slowing therapies is also strengthening utilization across care pathways, supported by continued investment in dialysis networks and specialist renal care capacity.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Chronic Kidney Disease Market Size 2025 | USD 90,246 million |
| Chronic Kidney Disease Market, CAGR | 5.7% |
| Chronic Kidney Disease Market Size 2032 | USD 133,030 million |
Key Market Trends & Insights
- The Chronic Kidney Disease Market is projected to expand at 5.7% CAGR (2025–2032), supported by rising diagnosed prevalence and longer treatment duration per patient.
- Treatment accounted for the largest share of 72.3% in 2025, reflecting the recurring nature of pharmacotherapy, dialysis services, and advanced renal care utilization.
- Hospitals held 40.2% share in 2025, indicating their central role in diagnosis, complication management, and referral-driven advanced care initiation.
- North America contributed 39.4% of revenue in 2025, supported by high care intensity, mature reimbursement, and strong renal therapy adoption.
- Asia Pacific captured 23.9% share in 2025, reflecting the region’s expanding CKD patient base and improving access to diagnostics and renal care services.
Segment Analysis
Chronic Kidney Disease Market structure spans two core revenue pools-diagnosis and treatment-because patients move from screening and staging to long-duration management and, for advanced disease, renal replacement therapy. Market behavior is shaped by repeated monitoring needs, comorbidity overlap with cardiovascular and metabolic disease, and progressive escalation in treatment intensity. As a result, product demand stretches from routine blood and urine testing to multi-class drug therapy and dialysis delivery systems.
The market is also differentiated by where care is delivered and how intensively patients are managed. Hospitals remain pivotal due to complex case handling, specialist nephrology access, and integrated management of complications. Dialysis centers expand capacity to absorb rising end-stage demand, while homecare settings gain relevance where training, monitoring, and equipment availability support decentralized care. This creates a multi-channel growth pathway across clinical, outpatient, and home-based CKD management.
By Product Type Insights
Treatment accounted for the largest share of 72.3% in 2025. Treatment leads because CKD management typically requires long-term therapy and frequent follow-up to slow progression and manage complications. Advanced disease increases recurring spend through dialysis procedures, consumables, and service delivery intensity. Treatment demand is also reinforced by multi-class regimens that address blood pressure control, anemia, and mineral-bone disorders, expanding therapy duration and complexity. Care pathway escalation over time sustains a structurally larger treatment revenue base than diagnosis.
By Diagnosis Insights
Diagnosis demand is supported by the need for early detection, routine staging, and repeat monitoring as kidney function changes over time. Blood tests remain foundational for assessing kidney function and tracking decline, while urine tests are widely used to identify protein-related risk and progression. Imaging plays a complementary role for structural assessment and complications, especially in advanced or unclear cases. Point-of-care kidney tests are gaining attention where faster triage and broader access can improve screening reach in outpatient and community settings.
By Treatment Insights
Treatment demand is anchored in the fact that CKD is chronic, progressive, and closely linked to comorbid conditions that require continuous management. Drugs are central in early-to-mid stages to slow progression and address complications such as hypertension and anemia. Dialysis becomes a major treatment pathway for late-stage disease because it is procedure-intensive and highly recurring. Kidney transplant remains clinically definitive for eligible patients, but volume is constrained by donor availability and system capacity. Other treatment products contribute through supportive renal care needs.
By Drug Class Insights
Drug class utilization is shaped by progression stage and complication profile, which creates demand across both foundational and specialized therapies. Blood pressure control and protein-related risk management support persistent use of established antihypertensive classes. Complication-focused therapies such as anemia management agents and mineral-bone disorder drugs become more prominent as disease advances. Newer kidney-protective mechanisms strengthen therapy intensification and combination approaches, expanding the clinical rationale for earlier initiation and longer persistence. This broadens the commercial opportunity across nephrology and cardio-renal care pathways.
By Dialysis Type Insights
Dialysis modality adoption is influenced by infrastructure availability, patient suitability, and clinical workflow preferences. Hemodialysis remains widely utilized due to established center-based networks and operational standardization. Peritoneal dialysis supports home-based care where training and supply continuity are strong. Home dialysis systems are gaining momentum in markets pushing for patient convenience and lower travel burden, supported by monitoring and support models. Wearable and portable dialysis remains an innovation-driven opportunity aimed at mobility and quality-of-life improvement.
By End User Insights
Hospitals accounted for the largest share of 40.2% in 2025. Hospitals lead because they manage complex CKD cases, acute complications, and multidisciplinary care needs tied to comorbid cardiovascular and metabolic disease. They also act as referral hubs for late-stage treatment initiation, including dialysis planning and transplant evaluation. Hospitals benefit from integrated diagnostics, specialist staffing, and inpatient/outpatient continuity. Dialysis centers remain essential for scaling procedure capacity and specialized service delivery as advanced disease volumes rise.
Chronic Kidney Disease Market Drivers
Rising CKD risk burden from diabetes and hypertension
Chronic Kidney Disease Market growth is driven by the expansion of diabetes and hypertension populations, which are primary contributors to kidney damage and progression risk. These conditions increase demand for routine screening, repeat monitoring, and sustained medical management across early-stage CKD. As risk pools expand, healthcare systems face higher volumes requiring nephrology referral, complication management, and long-term therapy adherence. This increases utilization across diagnostics, drug therapy, and advanced renal care pathways over multi-year treatment timelines.
- For instance, Novo Nordisk reported that its FLOW trial of semaglutide 1.0 mg enrolled 3,533 people with type 2 diabetes and CKD, and demonstrated a 24% reduction in the combined risk of kidney disease progression, major adverse cardiovascular events, and death versus placebo, underscoring how expanding diabetic CKD populations are translating into measurable demand for long-duration renal management strategies.
Longer duration of therapy and progressive escalation of care
Chronic Kidney Disease Market demand strengthens because CKD is chronic and often requires ongoing intervention rather than one-time treatment. Patients typically move from risk evaluation to sustained management, then escalate to more intensive therapy when kidney function declines. This progression increases recurring utilization of medications, monitoring tests, specialist visits, and procedure-based care. Advanced-stage patients create higher service intensity, particularly in dialysis and complication management. This care escalation supports a structurally large and recurring treatment-driven revenue base.
Expanding dialysis capacity and renal care delivery networks
Chronic Kidney Disease Market expansion is supported by continued investment in dialysis facilities, staffing, and standardized clinical workflows that increase treatment capacity. Dialysis centers improve throughput, care consistency, and patient management across high-volume populations requiring recurring procedures. Integrated service models and better referral coordination support smoother transitions from hospital nephrology care to outpatient dialysis delivery. As end-stage disease volumes rise, capacity buildout becomes a direct enabler of market growth. Service-based revenue streams also deepen recurring demand for equipment and consumables.
- For instance, Fresenius Medical Care reported that as of December 31, 2024, it treated 299,352 patients in 3,675 dialysis clinics worldwide, demonstrating how large-scale network expansion and standardized renal care delivery infrastructure directly support recurring dialysis volumes.
Growing emphasis on earlier detection and routine monitoring
Chronic Kidney Disease Market growth is strengthened by rising awareness of early-stage disease and the need to identify progression risk sooner. Earlier detection increases utilization of blood and urine testing, repeat monitoring, and follow-up assessments that convert at-risk patients into managed CKD pathways. Routine monitoring also supports therapy optimization and more consistent clinical decision-making, improving adherence and persistence. Point-of-care approaches can widen access in outpatient settings, supporting screening reach and frequency. This expands both diagnosis-related volumes and downstream treatment demand.
Chronic Kidney Disease Market Challenges
Chronic Kidney Disease Market growth is constrained by underdiagnosis and delayed presentation, which limits timely initiation of therapy and reduces the conversion of at-risk populations into treated cohorts. Many patients are identified after kidney damage has progressed, increasing complication burden and making care pathways more complex. This also drives variability in referral patterns, patient adherence, and continuity of care across geographies. Inconsistent screening uptake and fragmented care coordination can weaken long-term treatment optimization and outcomes.
- For instance, Carna Health reported in its Cameroon CKD pilot that it exceeded 550 screened participants within three days, with 19% showing both significant proteinuria and eGFR results suggestive of CKD stages 3 to 5, while over 50% had eGFR findings requiring further follow-up, illustrating how targeted screening technologies can uncover a sizable previously unrecognized patient pool but also highlight the scale of delayed detection.
Chronic Kidney Disease Market expansion is also challenged by uneven access to specialist care and renal replacement therapy infrastructure, particularly outside mature healthcare systems. Dialysis and transplant pathways require sustained capacity, trained staff, and reliable supply chains, which can be difficult to scale uniformly. Cost pressure affects payer decisions, therapy access, and modality availability, especially for procedure-intensive care. These constraints can slow adoption of advanced solutions and limit the pace of market development in emerging regions.
Chronic Kidney Disease Market Trends and Opportunities
Chronic Kidney Disease Market trends include the shift toward integrated cardio-renal management, where care teams aim to address kidney decline alongside cardiovascular risk and metabolic drivers. This supports broader adoption of multi-class therapy strategies and more frequent monitoring to optimize treatment response. Care coordination models that improve referral timing and follow-up can increase sustained therapy utilization and reduce drop-off across the disease journey. These changes create opportunity for solutions that streamline workflows and improve longitudinal patient management.
- For instance, AstraZeneca’s dapagliflozin demonstrated a clear cardio-renal benefit in the Phase III DAPA-CKD trial, where the primary composite endpoint occurred in 9.2% of treated patients versus 14.5% with placebo over a median 2.4 years, corresponding to a hazard ratio of 0.61 and a number needed to treat of 19, reinforcing the move toward integrated therapy strategies in CKD management.
Chronic Kidney Disease Market opportunities also include the expansion of decentralized care, including home-based modalities and support services that improve patient convenience and reduce travel burden. Homecare settings can expand addressable access where training, monitoring, and supply continuity are strong. Innovation in dialysis devices and support services can improve quality-of-life and widen eligibility for at-home treatment pathways. Digital tools that enable monitoring, adherence support, and care navigation can further strengthen utilization consistency across chronic management.
Regional Insights
North America
North America held 39.4% share in 2025, supported by high treatment intensity, mature reimbursement frameworks, and dense dialysis and specialist networks. The region’s care delivery model supports early testing, sustained pharmacotherapy, and strong procedure capacity for advanced disease. Hospitals and dialysis centers remain central to care coordination, supported by established referral pathways. Continued focus on progression slowing and complication management reinforces treatment-led revenue. These factors collectively sustain regional leadership across diagnosis and treatment categories.
Europe
Europe held 26.8% share in 2025, supported by structured health systems, broad access to nephrology services, and strong clinical guideline adherence. Demand is anchored in steady monitoring and long-duration management, with emphasis on standardized care pathways. Cost control and formulary management shape therapy mix and adoption timing across markets. Hospitals play a key role in specialist access and complication handling, while outpatient networks support longitudinal follow-up. These dynamics maintain Europe as a major revenue contributor.
Asia Pacific
Asia Pacific held 23.9% share in 2025, reflecting a large and expanding CKD patient base coupled with improving access to diagnostics and renal care services. Growth is supported by urbanization, aging demographics, and rising metabolic risk factors that increase CKD incidence and progression. Market development varies by country due to differences in reimbursement coverage and infrastructure capacity. Expansion of dialysis networks and stronger screening initiatives support rising utilization over time. These trends position the region for sustained growth and increasing share.
Latin America
Latin America held 5.4% share in 2025, with demand shaped by expanding chronic disease burden and improving renal care access in larger markets. Infrastructure variability influences diagnosis rates, treatment continuity, and modality availability. Hospitals remain key for advanced disease management, with outpatient and dialysis capacity gradually expanding. Reimbursement constraints and affordability can limit therapy intensity in some settings. Despite constraints, growth potential remains meaningful as screening and treatment access improve.
Middle East & Africa
Middle East & Africa held 4.5% share in 2025, reflecting uneven renal care capacity across countries. Some markets have advanced hospital and dialysis infrastructure, while others face access limitations that constrain diagnosis and treatment continuity. Demand growth is supported by rising metabolic disease prevalence and gradual investments in renal services. Capacity expansion and care pathway strengthening can lift utilization over time. The region’s opportunity is linked to improving access, affordability, and continuity of care.
Competitive Landscape
The Chronic Kidney Disease Market is characterized by competition across two major arenas: differentiated therapeutics for progression slowing and complication control, and scaled renal replacement therapy delivery through dialysis equipment and service networks. Companies compete on clinical outcomes, tolerability profiles, therapy positioning across CKD stages, and the ability to support longitudinal patient management. Dialysis-focused players differentiate through installed base, service footprint, device reliability, and operational efficiency, while drug developers differentiate through evidence strength and care pathway integration.
AstraZeneca’s approach is anchored in strengthening cardio-renal disease management strategies with therapies positioned to slow progression and reduce complications across chronic disease populations. The company’s competitive focus typically emphasizes clinical evidence generation, guideline alignment, and integration into specialist and primary care workflows. Market influence depends on therapy adoption across high-risk CKD cohorts and persistence over long treatment durations. Execution is supported by strong commercial reach and the ability to engage both nephrology and broader chronic disease stakeholders.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- AstraZeneca
- Bayer AG
- Boehringer Ingelheim
- Eli Lilly and Company
- Otsuka Holdings Co., Ltd.
- CSL Vifor
- Akebia Therapeutics, Inc.
- Ardelyx, Inc.
- FibroGen, Inc.
- Pfizer Inc.
- Novartis AG
- Sanofi
- Fresenius Medical Care
- DaVita Inc.
- Baxter International Inc.
- Nipro Corporation
- B. Braun Melsungen AG
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In September 2025, Arch Biopartners announced the acquisition of a pre-clinical platform for chronic kidney disease, adding assets targeting interleukin-32 (IL-32) and expanding its kidney therapeutics pipeline into next-generation CKD drug development.
- In January 2025, Novo Nordisk announced that the U.S. FDA approved Ozempic (semaglutide) to reduce the risk of worsening kidney disease, kidney failure, and cardiovascular death in adults with type 2 diabetes and chronic kidney disease, marking an important product-related expansion in the CKD space.
- In August 2024, Versant Ventures and Novartis launched Borealis Biosciences through a partnership focused on developing next-generation RNA medicines for kidney diseases, supported by more than $150 million in combined Series A financing and strategic research collaboration funding.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 90,246 million |
| Revenue forecast in 2032 | USD 133,030 million |
| Growth rate (CAGR) | 5.7% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026–2032 |
| Quantitative units | USD million |
| Segments covered | By Product Type, By Diagnosis, By Treatment, By Drug Class, By Dialysis Type, By End User |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | AstraZeneca; Bayer AG; Boehringer Ingelheim; Eli Lilly and Company; Otsuka Holdings Co., Ltd.; CSL Vifor; Akebia Therapeutics, Inc.; Ardelyx, Inc.; FibroGen, Inc.; Pfizer Inc.; Novartis AG; Sanofi; Fresenius Medical Care; DaVita Inc.; Baxter International Inc.; Nipro Corporation; B. Braun Melsungen AG |
| No. of Pages | 328 |
By Segmentation
By Product Type
- Diagnosis
- Treatment
By Diagnosis
- Blood Tests
- Urine Tests
- Imaging Tests
- Point-of-Care Kidney Tests
- Other Diagnostic Products
By Treatment
- Drugs
- Dialysis
- Kidney Transplant
- Other Treatment Products
By Drug Class
- ACE Inhibitors
- Angiotensin-II Receptor Blockers
- Diuretics
- Calcium Channel Blockers
- Beta Blockers
- Erythropoiesis-Stimulating Agents
- Phosphate Binders
- SGLT2 Inhibitors
- Mineralocorticoid Receptor Antagonists
- HIF-PH Inhibitors
- Other Drug Classes
By Dialysis Type
- Hemodialysis
- Peritoneal Dialysis
- Home Dialysis Systems
- Wearable and Portable Dialysis
By End User
- Hospitals
- Dialysis Centers
- Homecare Settings
- Specialty Clinics
- Ambulatory Surgery Centers
- Other End Users
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and forecast for the Chronic Kidney Disease Market?
What is the CAGR of the Chronic Kidney Disease Market?
Which segment holds the largest share in 2025?
What factors are driving market growth?
Who are the leading companies in the Chronic Kidney Disease Market?
Which region leads the market in 2025?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 90,246 million → 2032: USD 133,030 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Chronic Kidney Disease Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Chronic Kidney Disease Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Chronic Kidney Disease Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Chronic Kidney Disease Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Chronic Kidney Disease Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Chronic Kidney Disease Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Chronic Kidney Disease Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Chronic Kidney Disease Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 90,246 million → 2032: USD 133,030 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Chronic Kidney Disease Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Chronic Kidney Disease Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Chronic Kidney Disease Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Chronic Kidney Disease Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

