
Cashless shopping and new logistics zones lift volumes
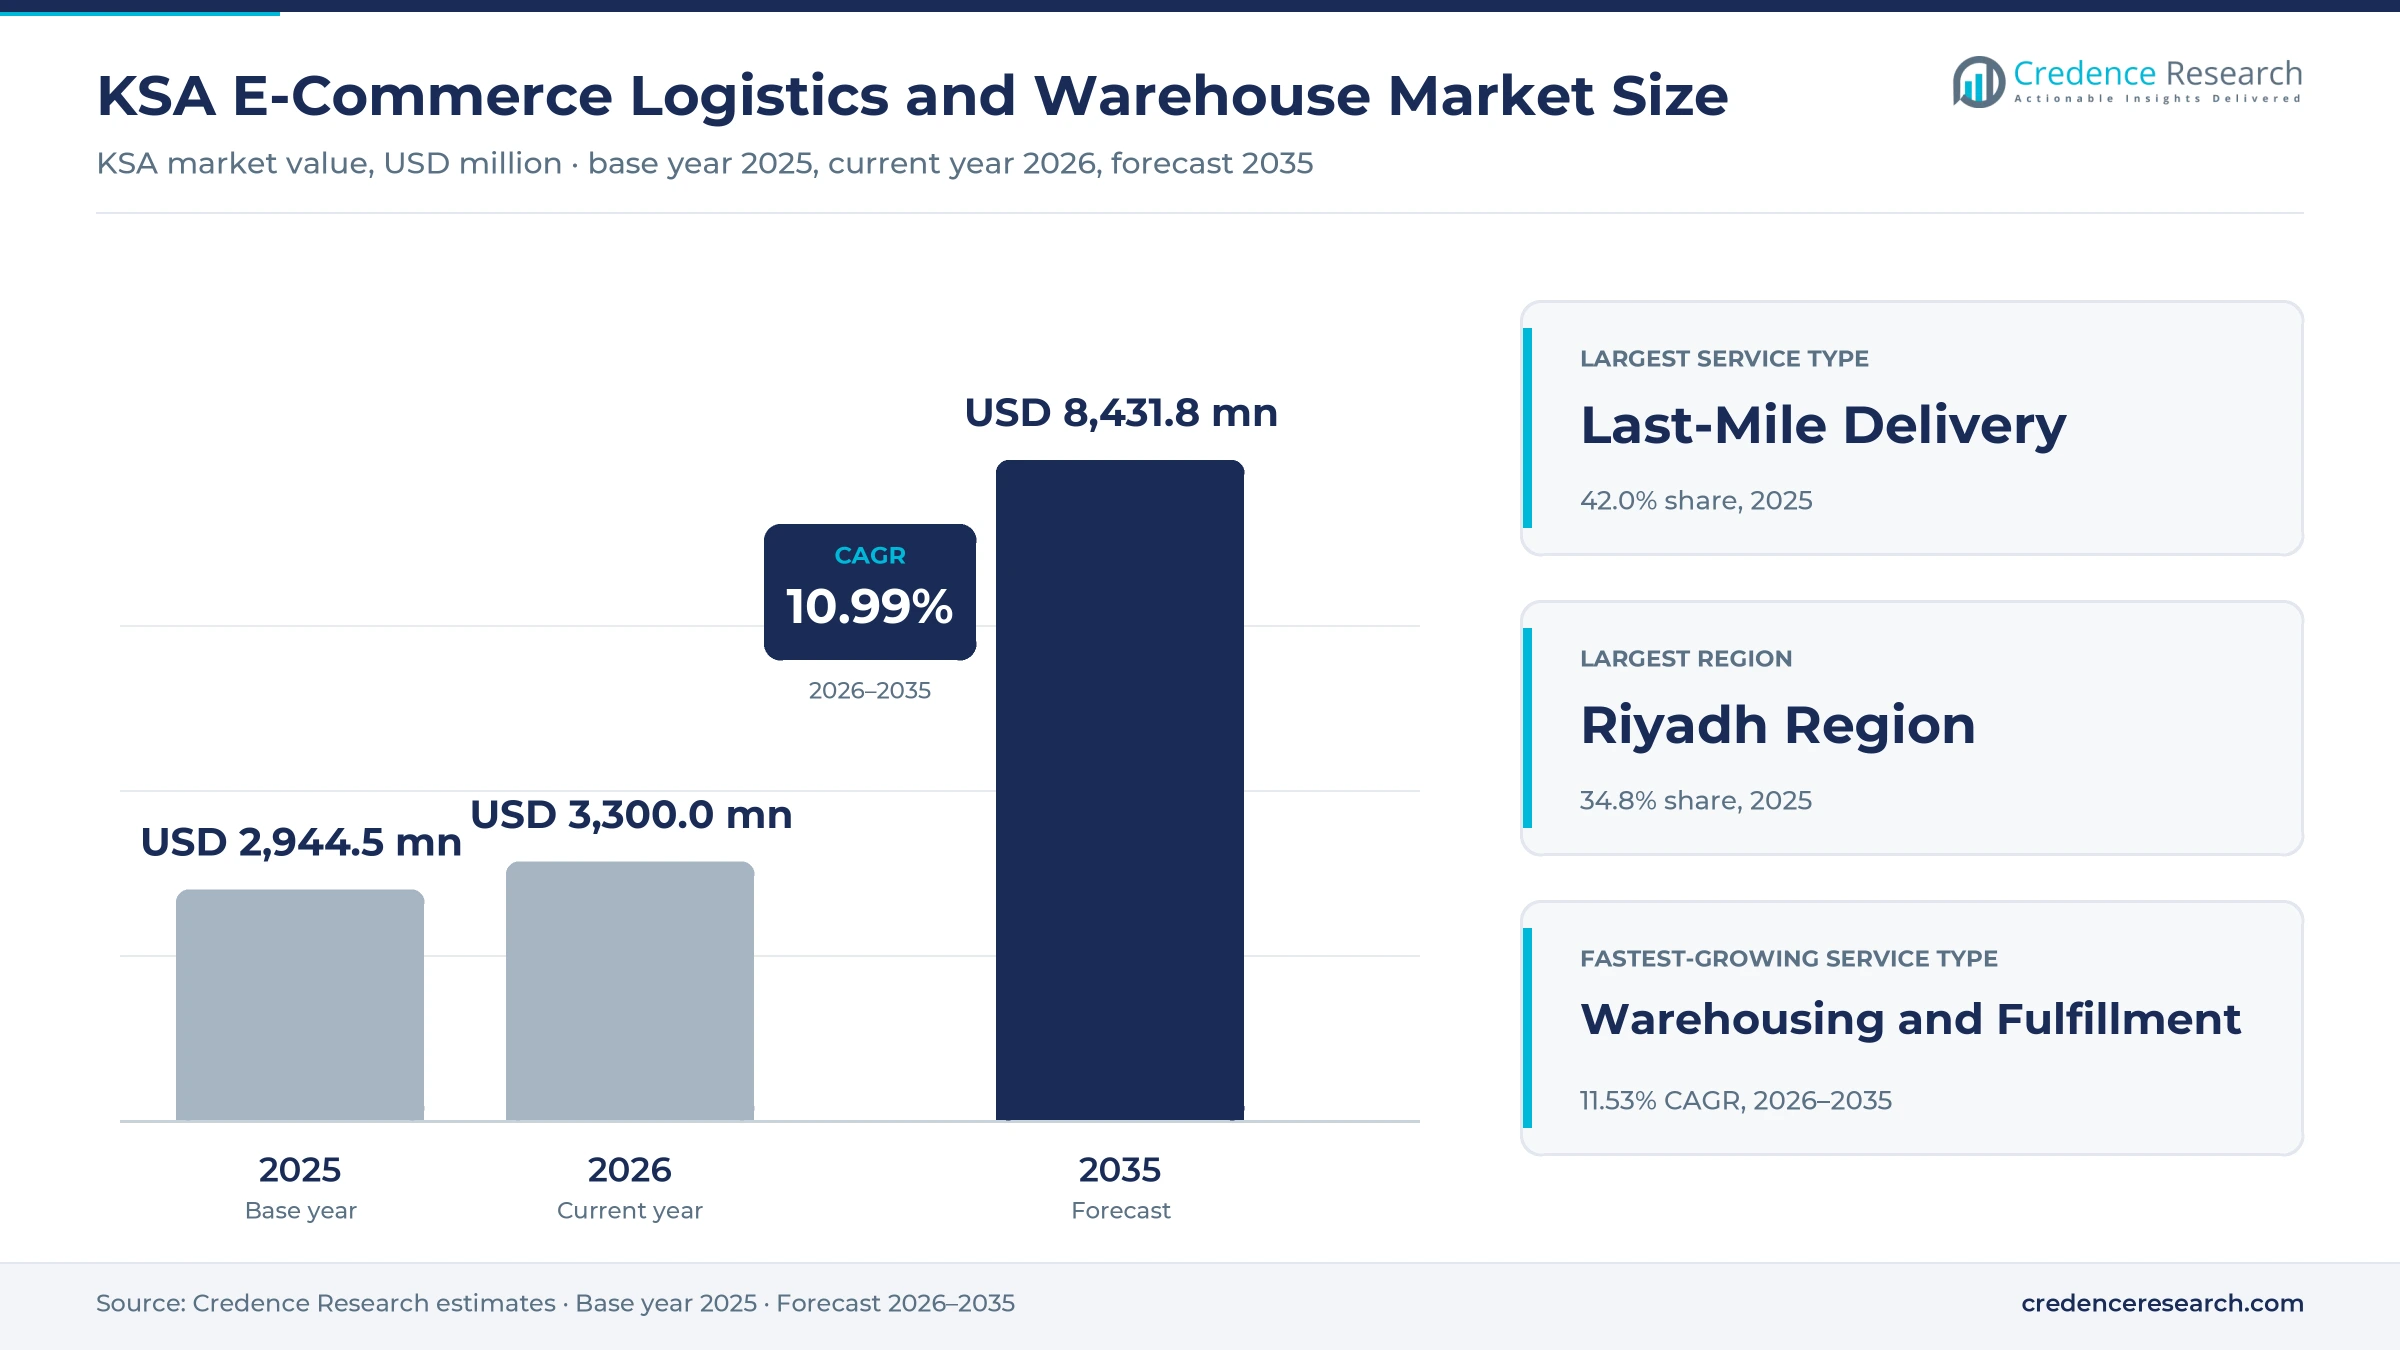
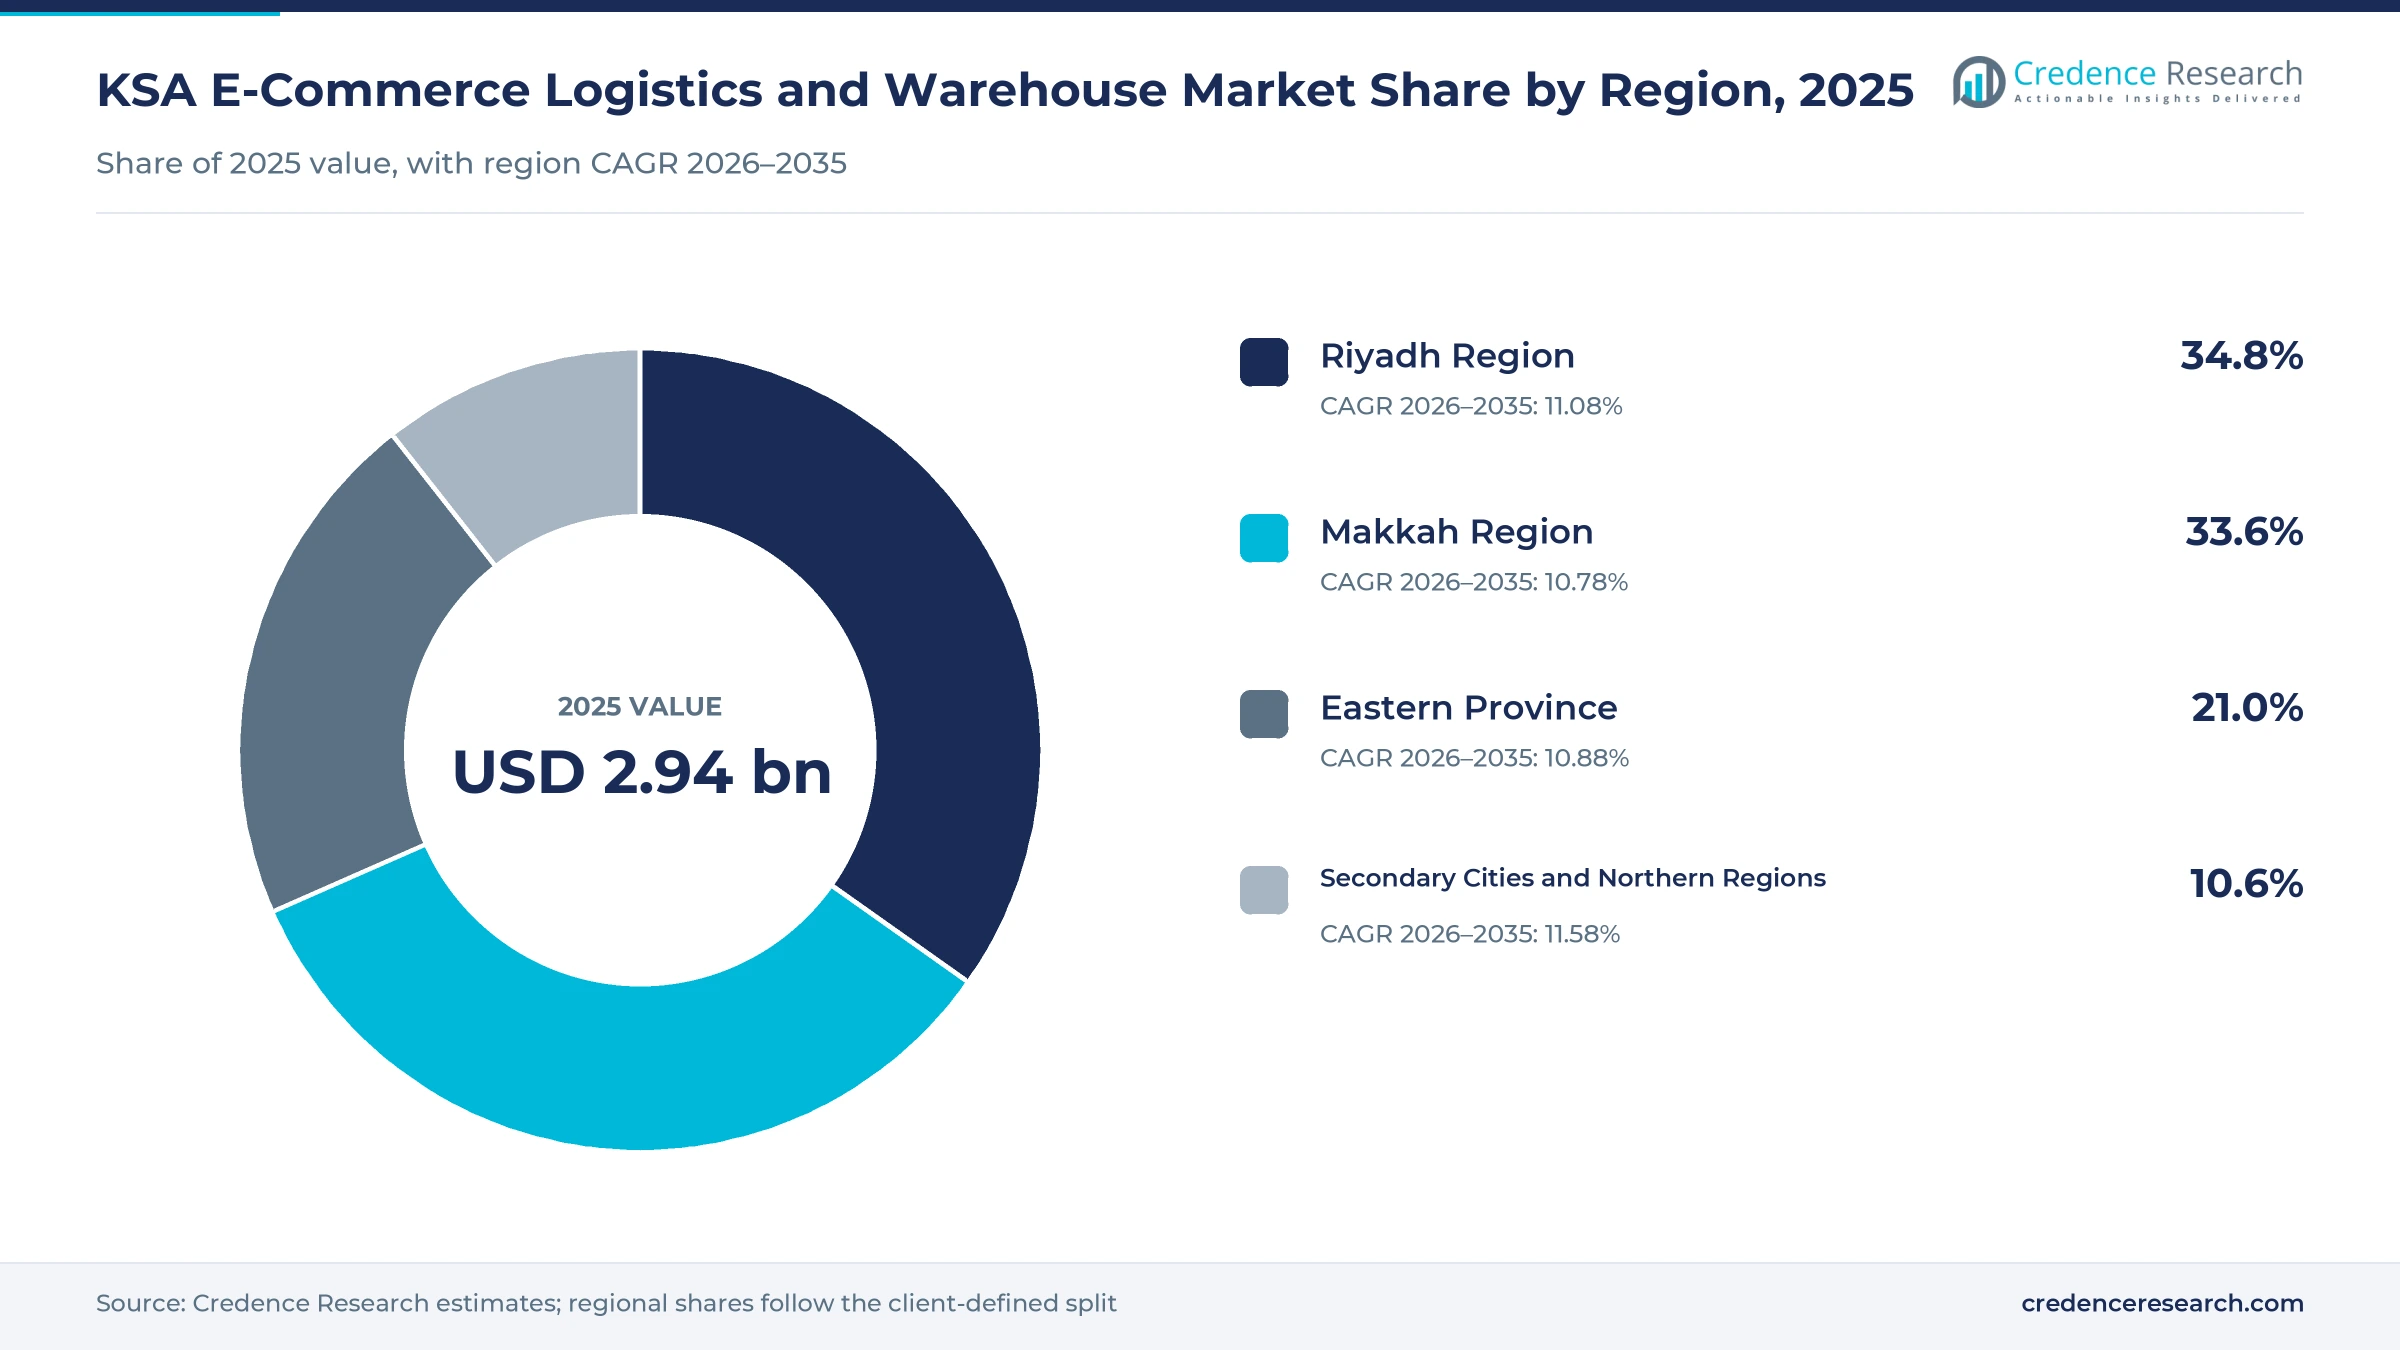
The KSA e-commerce logistics and warehouse market was valued at USD 2.94 billion in 2025 and is projected to increase from USD 3.30 billion in 2026 to USD 8.43 billion by 2035, registering a CAGR of 10.99% during 2026–2035. Demand comes from online marketplaces, omnichannel retailers and digital-native brands that need storage, order picking, parcel delivery and returns handling for shoppers who now pay mostly by card and wallet. Riyadh Region held the largest regional share, 34.8% in 2025, because the capital has the most online sellers, the most delivery orders and new bonded warehouse capacity near its main airport. Secondary Cities and Northern Regions is the fastest-growing region at 11.58% a year, as parcel networks extend coverage beyond the three main urban regions. In turn, electronic payments reached 79% of retail payments in 2024, which removes much of the cost and risk of cash on delivery.
Which online order logistics services does the estimate cover?
The estimate measures the value of logistics and warehouse services sold to online sellers in Saudi Arabia. It counts last-mile parcel delivery, warehousing and order fulfillment, cross-border parcel logistics and returns and value-added services such as labeling, kitting and cash collection.
The estimate excludes food delivery from restaurants, bulk freight for traditional retail, and the purchase of warehouse buildings or vehicles. The value chain runs from sellers and marketplaces through fulfillment centers, sorting hubs and courier fleets to shoppers in every region of the Kingdom.
KSA E-Commerce Logistics and Warehouse Market Insights
- The KSA e-commerce logistics and warehouse market was valued at USD 2.94 billion in 2025 and is projected to reach USD 8.43 billion by 2035, registering a CAGR of 10.99% during 2026–2035.
- Riyadh Region held a 34.8% share of 2025 value, because the capital leads online seller registrations and delivery orders.
- Last-mile delivery led with a 42.0% share of 2025 value, because every online order ends with a doorstep or locker handoff.
- DHL Supply Chain signed a 26-year land lease on Nov. 24, 2025, for about 53,000 sqm of warehouse space in a Riyadh logistics zone.
- Delivery orders topped 124 million in the fourth quarter of 2025, up 60% year on year, according to transport regulator data.
Last-mile delivery leads while fulfillment grows fastest
Why does last-mile delivery hold the largest share?
Based on service type, the market is categorized into last-mile delivery, warehousing and fulfillment, cross-border logistics and returns and value-added services. Last-Mile Delivery led with a 42.0% share of 2025 value, because every online order needs a courier handoff at a home, office or locker. Warehousing and Fulfillment grows fastest at 11.53% a year, as sellers move stock into multi-user warehouses near airports and cities.
How do marketplaces and brands split logistics spending?
Based on customer type, the market is categorized into online marketplaces, omnichannel retailers, digital-native brands and social commerce sellers. Online Marketplaces led with a 46.0% share of 2025 value, because large platforms carry the widest product ranges and highest order counts. Social Commerce Sellers grow fastest at 12.11% a year, as small sellers on messaging and social apps outsource storage and delivery.
Which product categories generate the most parcels?
Based on end-use industry, the market is categorized into fashion and apparel, consumer electronics, beauty and personal care, and grocery and specialty food. Fashion and Apparel led with a 30.0% share of 2025 value, because clothing orders are frequent and carry high return rates. Grocery and Specialty Food grows fastest at 11.55% a year, as shoppers buy household staples online for scheduled delivery.
Why does third-party fulfillment lead business models?
Based on business model, the market is categorized into third-party fulfillment, dedicated contract logistics, asset-light delivery orchestration and integrated marketplace logistics. Third-Party Fulfillment led with a 33.0% share of 2025 value, because many sellers prefer shared warehouses to their own sites. Asset-Light Delivery Orchestration grows fastest at 11.69% a year, as software platforms route orders across several courier fleets.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Service Type | Last-Mile Delivery | 42.0% | Warehousing and Fulfillment | 11.53% |
| By Customer Type | Online Marketplaces | 46.0% | Social Commerce Sellers | 12.11% |
| By End-Use Industry | Fashion and Apparel | 30.0% | Grocery and Specialty Food | 11.55% |
| By Business Model | Third-Party Fulfillment | 33.0% | Asset-Light Delivery Orchestration | 11.69% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Payments, logistics zones and parcel networks drive demand
How do cashless payments and online selling lift parcel demand?
Cashless payments and online selling lift parcel demand, because shoppers who pay by card or wallet order more often and refuse fewer deliveries. Electronic payments accounted for 79% of retail payments in 2024, up from 70% in 2023, according to the Saudi Central Bank. Electronic non-cash transactions rose to 12.6 billion in 2024 from 10.8 billion a year earlier. Internet use reached 100% of the population in 2024, according to the World Bank, which keeps almost every household within reach of online stores. As a result, online marketplaces hold 46.0% of 2025 value, while e-commerce registrations rose 9% to 43,854 in the fourth quarter of 2025.
Why does logistics zone build-out expand fulfillment capacity?
Logistics zone build-out expands fulfillment capacity, because sellers need modern warehouses close to airports, ports and cities. Nearly 30 logistics zones were under development nationwide in November 2025, against a target of 59, the transport minister said, as reported by Argaam. Eleven zones developed with private investment already operate at Jeddah Islamic Port. DHL Supply Chain plans about 53,000 sqm of multi-user warehouse space in Riyadh, with construction from early 2026, according to DHL Group. In turn, warehousing and fulfillment grows at 11.53% a year, the fastest service rate, as sellers shift stock from small storerooms into shared, bonded and automated sites.
How does parcel network modernization raise delivery capacity?
Parcel network modernization raises delivery capacity, because automated hubs and app-based tracking let couriers handle more parcels with fewer errors. Licensed companies delivered more than 48 million postal parcels in the fourth quarter of 2024 and more than 50 million in the second quarter of 2025, a record at the time. Aramex runs an automated courier facility at King Khalid International Airport that can handle up to 100,000 shipments a day. Saudi Post said in October 2024 that it planned to launch the region's largest super sorting center. As a result, last-mile delivery holds 42.0% of 2025 value, supported by automated sorting equipment in main hubs.
Why does rapid order growth keep courier fleets busy?
Rapid order growth keeps courier fleets busy, because shoppers now buy fashion, electronics and groceries online throughout the year. Delivery orders reached 79.6 million in the first quarter of 2025, up 22% on the year, and more than 101 million in the second quarter. Orders then topped 124 million in the fourth quarter of 2025, up 60% year on year, according to transport regulator data reported by Mubasher. Urban residents made up 84.6% of the population in 2025, which keeps delivery density high. In turn, grocery and specialty food grows at 11.55% a year, the fastest category rate, as households move weekly staples to scheduled online delivery.
Wider regional reach, service rules and bonded hubs
How is the rise of orders outside the big three regions reshaping networks?
The rise of orders outside the three largest regions is reshaping courier networks, because carriers must serve smaller cities with fewer parcels per route. Madinah took 4.65% of delivery orders in the second quarter of 2025, Aseer 3.56%, Qassim 2.89% and Tabuk 1.77%. Madinah also held 1,875 e-commerce registrations and Qassim 1,377 in the fourth quarter of 2025. These cities need regional sorting points, partner pickup counters and scheduled linehaul trucks from the main hubs. As a result, carriers that already serve Riyadh and Jeddah are adding feeder routes and local delivery partners, and they link those routes to regional road haulage corridors.
Why is the shift to published service rankings changing couriers?
The shift to published service rankings is changing courier behavior, because the transport regulator names companies by complaints per 100,000 parcels. In the fourth quarter of 2024, J&T Express and NAQEL Express tied for the fewest complaints at one per 100,000 parcels, iMile Delivery recorded two and DHL three. Aramex recorded nine complaints per 100,000 parcels in the same ranking. Companies must resolve complaints within seven days before customers can escalate them to the regulator. In turn, sellers choose carriers on service scores as well as price, which favors networks with strong tracking, driver training and clear customer communication at every delivery stage.
Can bonded multi-user warehouses open cross-border fulfillment?
Bonded multi-user warehouses can open cross-border fulfillment, because foreign brands can store stock close to Saudi shoppers before customs clearance. The Riyadh logistics zone chosen by DHL sits about 8 km from King Khalid International Airport and links to it by a bonded corridor. The 78,000 sqm plot carries a 26-year lease, and completion is expected in the second quarter of 2027. The project forms part of a EUR 500 million Middle East investment plan through 2030. As a result, operators that combine bonded storage with micro-fulfillment sites in cities can serve both local and international sellers that want delivery within one or two days.
Is there room for asset-light platforms to serve small sellers?
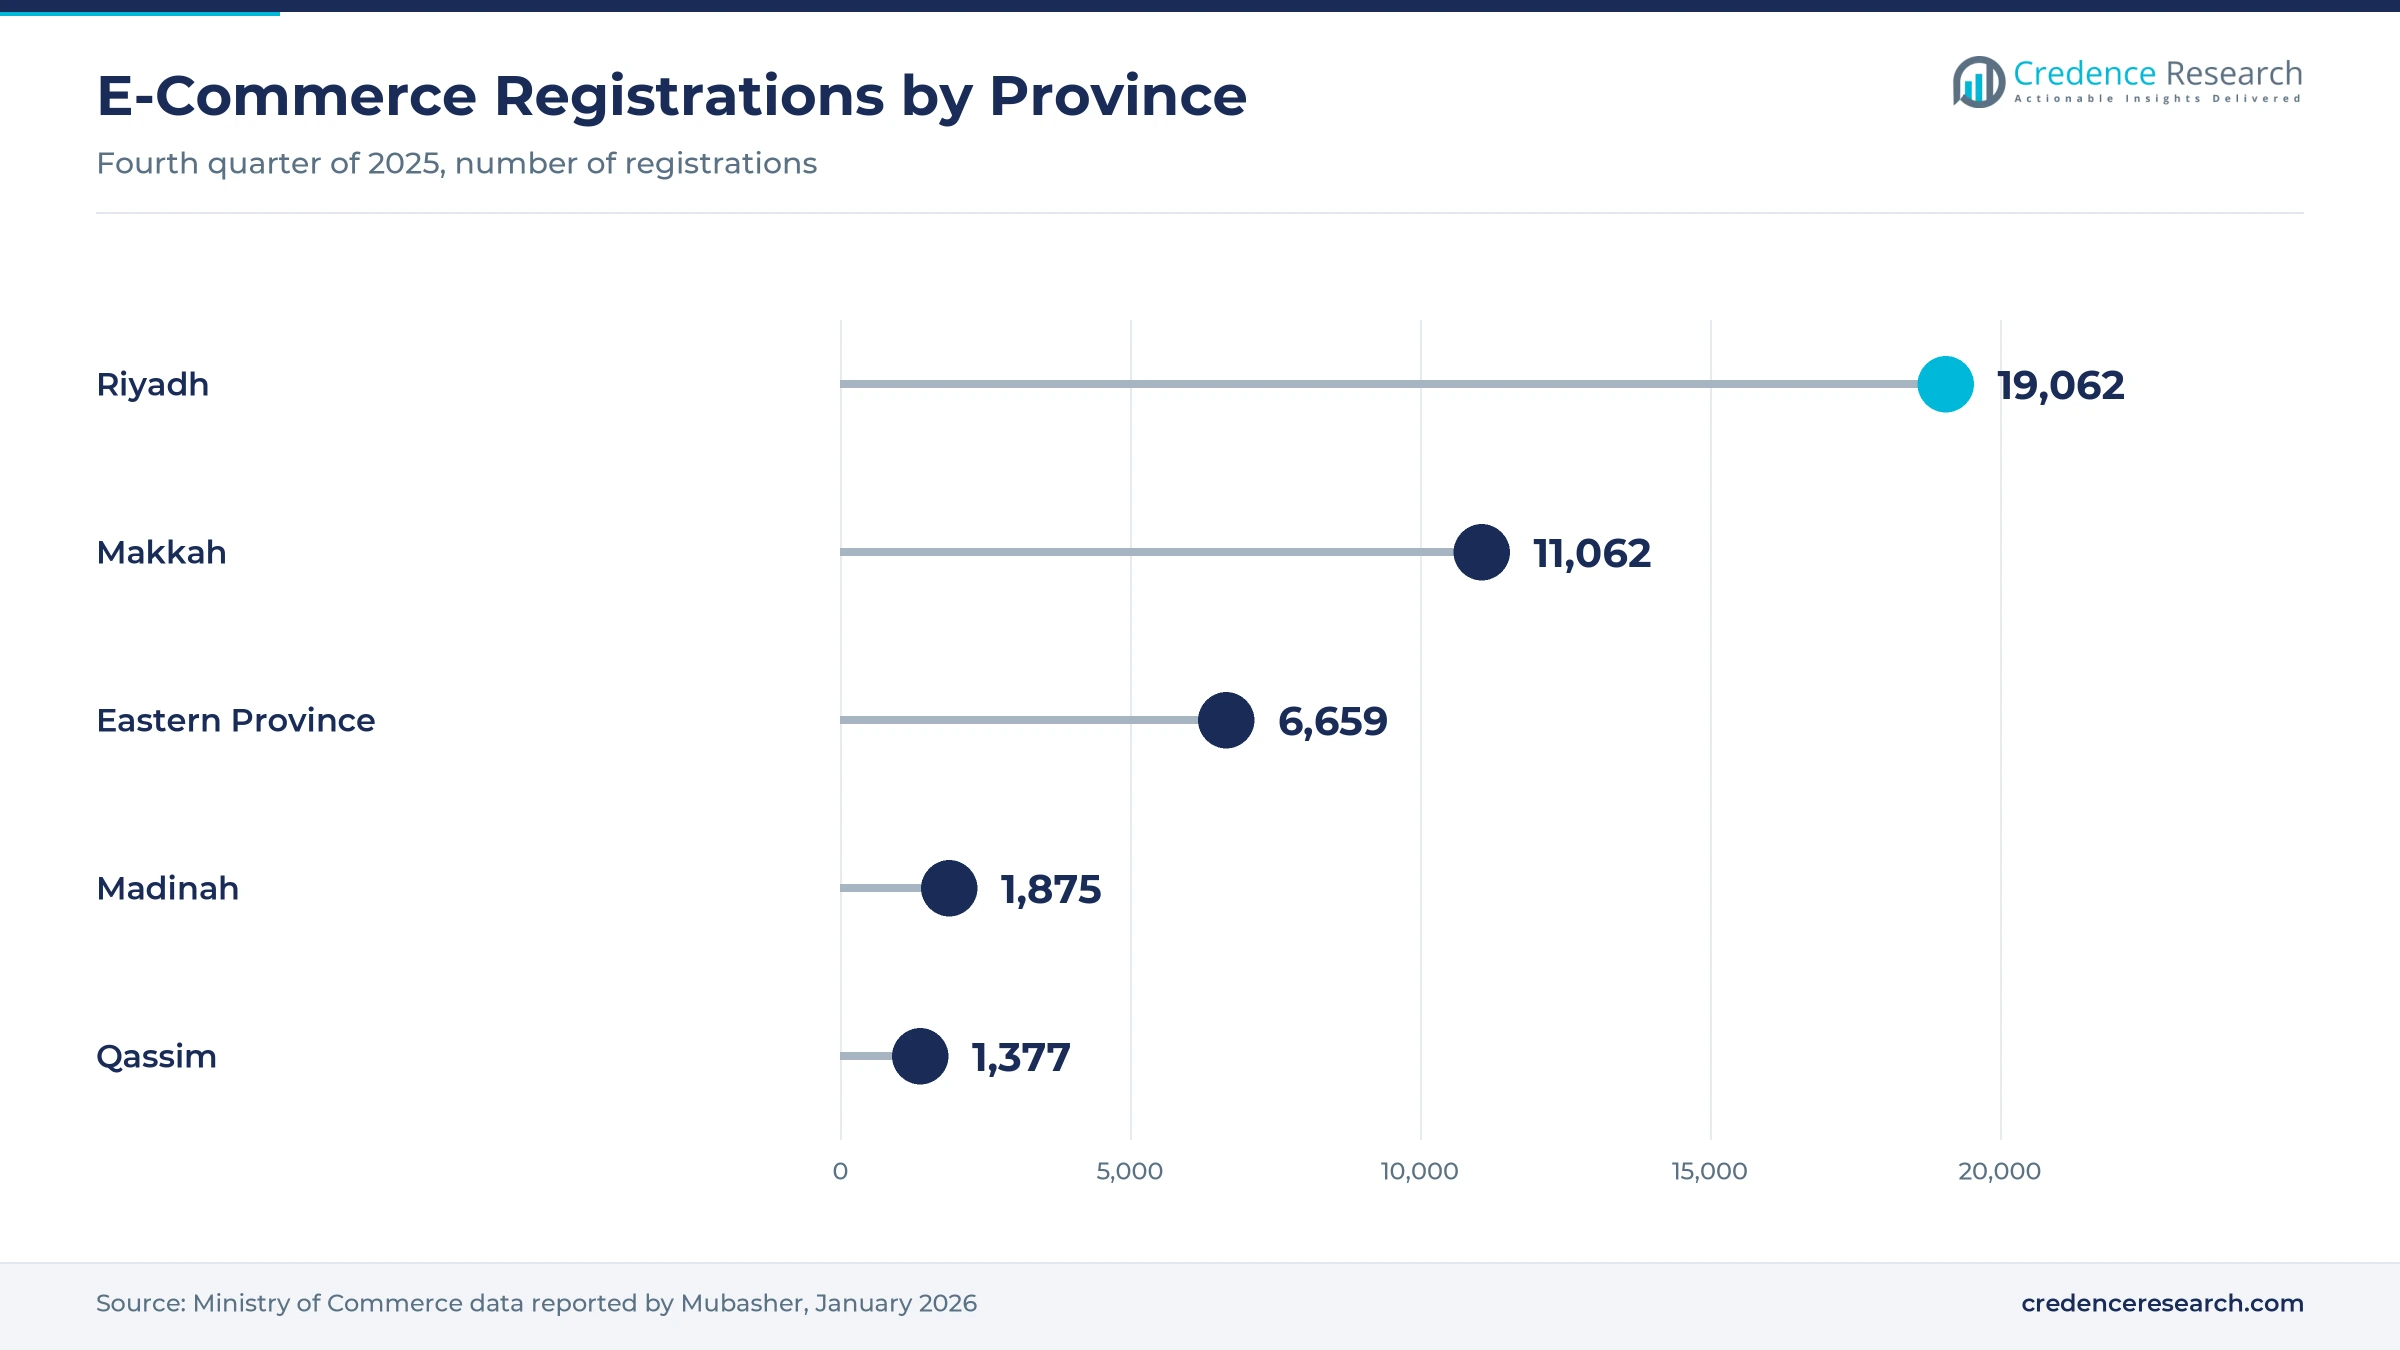
Asset-light platforms have room to serve small sellers, because many new online businesses lack the volume to sign contracts with several couriers. E-commerce registrations rose to 43,854 in the fourth quarter of 2025 from 40,041 a year earlier, which adds thousands of potential shippers. Riyadh Province alone held 19,062 of those registrations and Makkah Province 11,062. Investors are also backing larger networks, as ADQ completed its acquisition of a 63.16% stake in Aramex on July 22, 2025. In turn, asset-light delivery orchestration grows at 11.69% a year, the fastest business model rate, as platforms pool orders from many small sellers.
Delivery costs, peaks, returns and heat test operators
How do last-mile costs limit courier margins?
Last-mile costs limit courier margins, because each parcel needs a driver, a vehicle and often more than one delivery attempt. Low-density neighborhoods and gated compounds raise the time spent per stop. As a result, couriers struggle to cover costs on low-value orders. Operators respond with parcel lockers, pickup counters, route planning software and delivery fees that rise for remote addresses, which together lift the number of parcels each driver completes per shift.
Why do seasonal peaks strain warehouses and fleets?
Seasonal peaks strain warehouses and fleets, because Ramadan, Eid and year-end sales events concentrate orders into a few weeks. Sellers then need extra pickers, drivers and vehicles at short notice. In turn, delivery times slip and complaint rates rise during the busiest periods. Operators respond with temporary staff pools, earlier stock positioning in regional hubs and capacity agreements with partner fleets, which spread peak volumes across more vehicles and sites.
How do returns raise handling costs for sellers?
Returns raise handling costs for sellers, because fashion and electronics shoppers often send items back after trying them. Each return needs collection, inspection, repackaging and restocking before the item can be sold again. As a result, sellers lose a large part of their margin on high-return categories such as fashion. Logistics providers respond with drop-off points, faster refund checks and refurbishment services that turn returns into sellable stock within days.
Why does summer heat complicate grocery and beauty deliveries?
Summer heat complicates grocery and beauty deliveries, because high temperatures can damage food, cosmetics and some electronics in transit. Couriers need insulated packaging or chilled vehicles for these items. In turn, the cost per delivery rises sharply for temperature-sensitive orders during the summer months. Operators respond with chilled micro-hubs, shorter delivery windows and scheduled evening slots that limit exposure to peak daytime heat for food and cosmetics.
Riyadh leads as secondary cities post the fastest growth
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Riyadh Region | 1.02 | 34.8% | 11.08% |
| Makkah Region | 0.99 | 33.6% | 10.78% |
| Eastern Province | 0.62 | 21.0% | 10.88% |
| Secondary Cities and Northern Regions | 0.31 | 10.6% | 11.58% |
Why does the Riyadh region lead online order logistics?
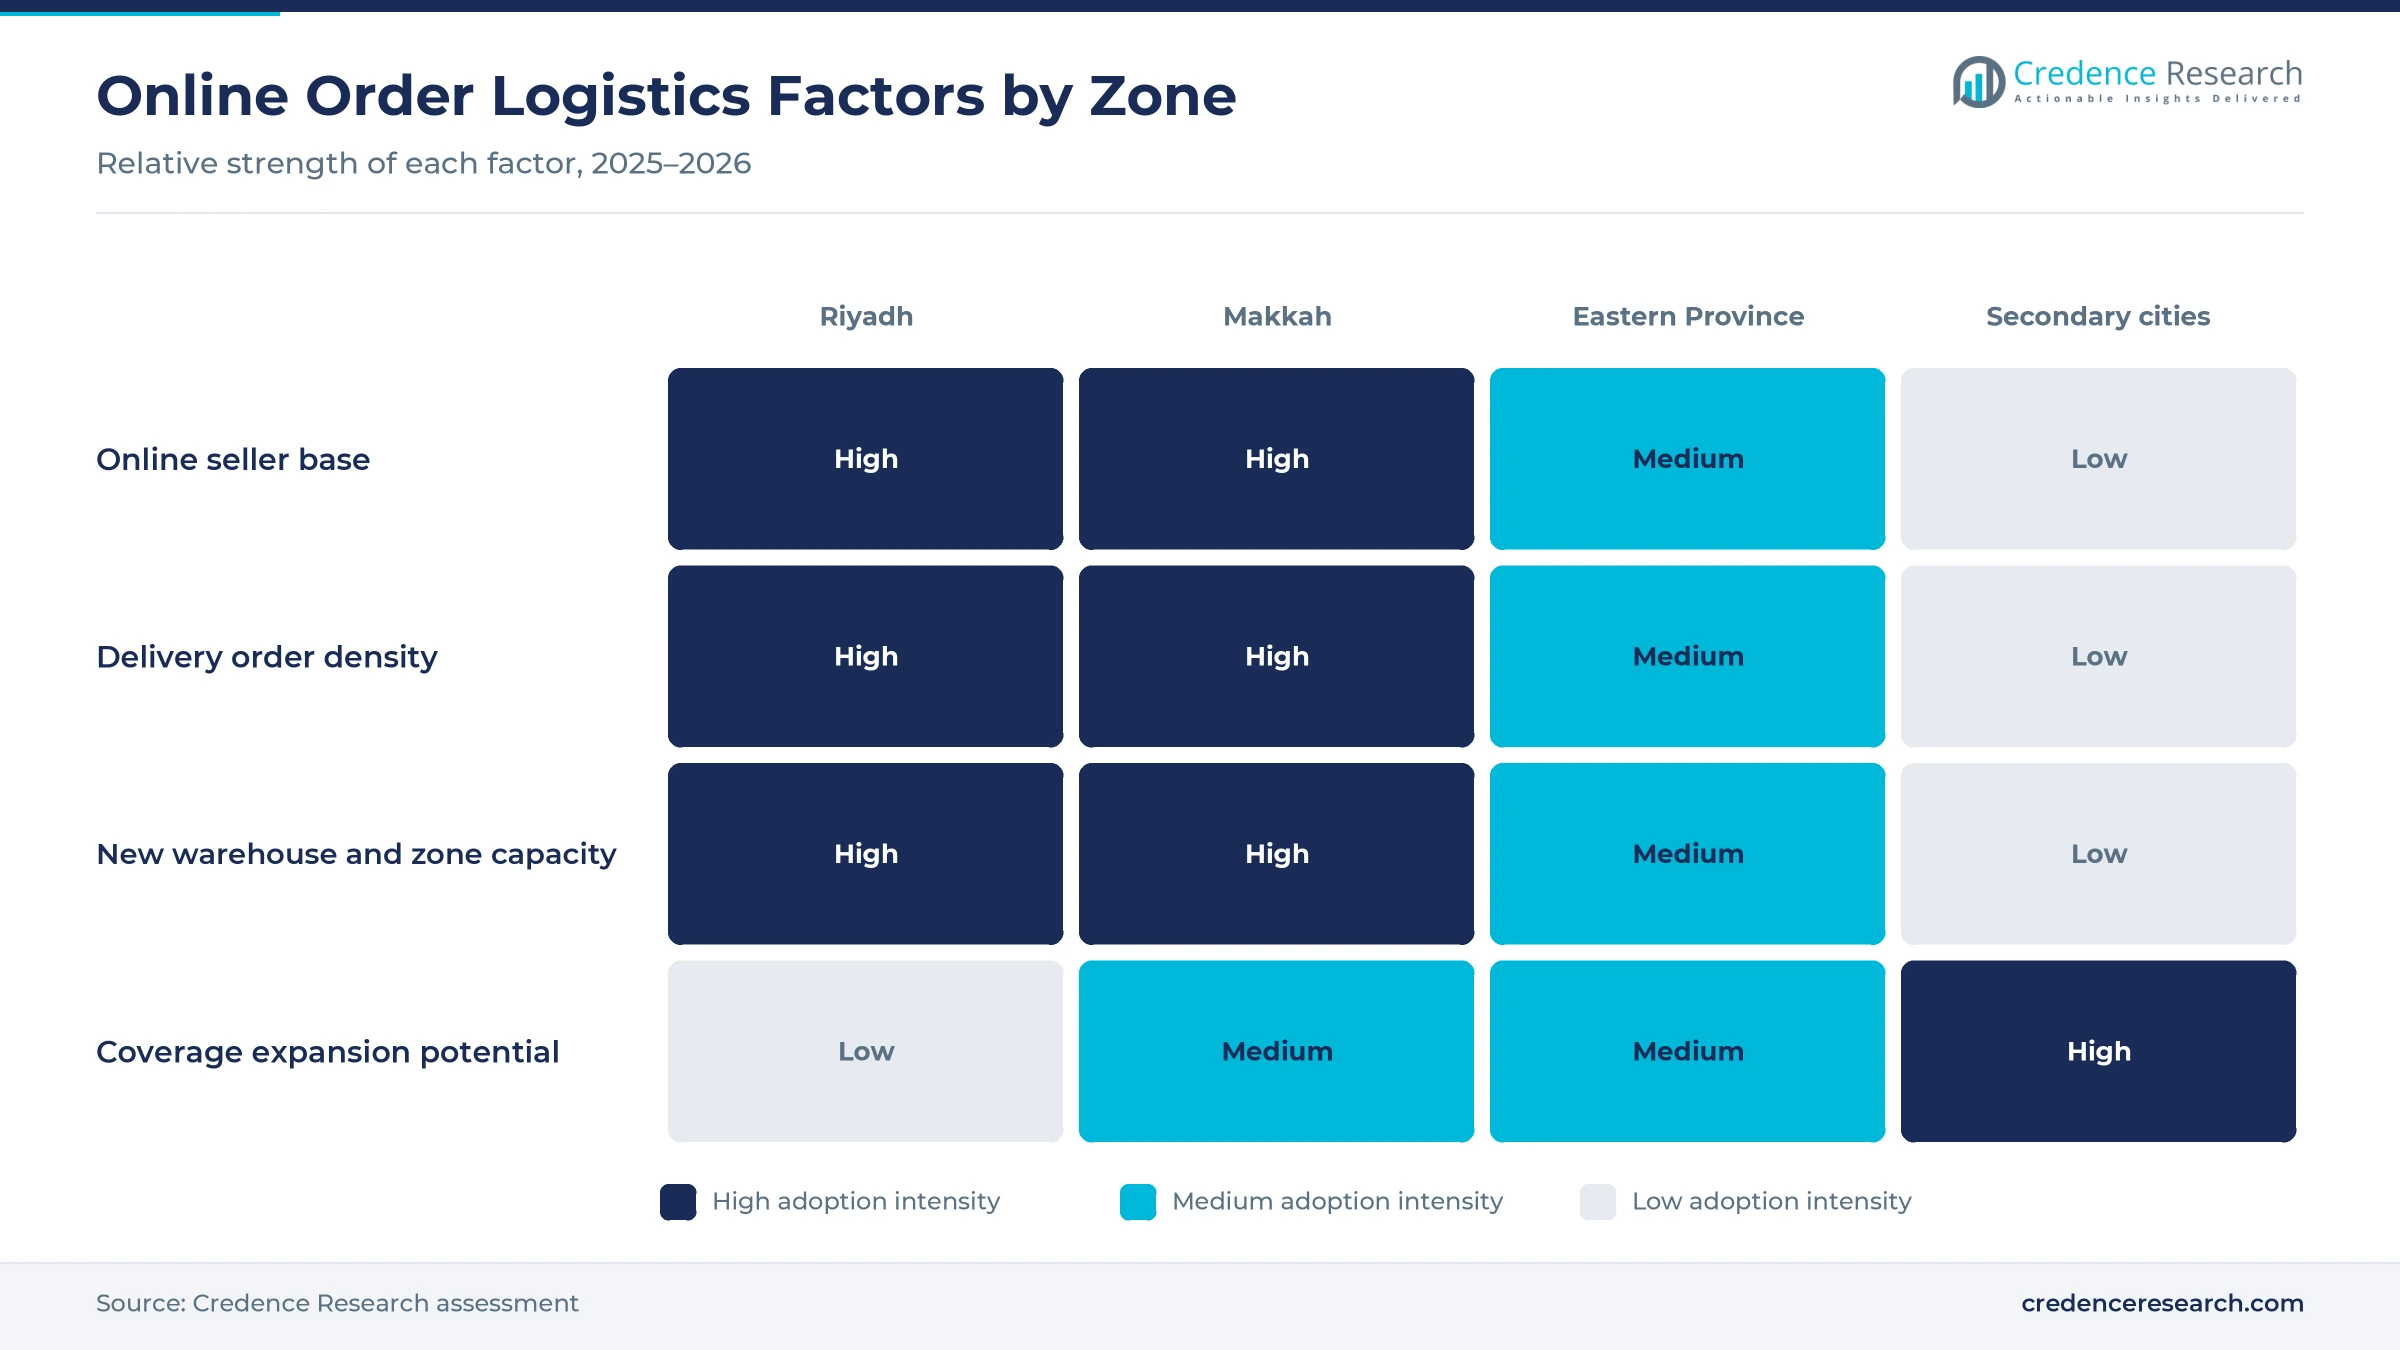
Riyadh Region held a 34.8% share of 2025 value and grows at 11.08% a year, because the capital generated 44.45% of delivery orders in the fourth quarter of 2025. Riyadh Province also held 19,062 of the 43,854 e-commerce registrations recorded in that quarter. DHL Supply Chain plans about 53,000 sqm of multi-user warehouse space near King Khalid International Airport. As a result, the capital remains the main base for national fulfillment centers.
How does the Makkah region support parcel volumes?
Makkah Region held a 33.6% share of 2025 value and grows at 10.78% a year, because Jeddah combines a large population, the main Red Sea port and seasonal pilgrim demand. The region generated 22.17% of delivery orders in the fourth quarter of 2025 and held 11,062 e-commerce registrations. Agility inaugurated a logistics complex in Jeddah in November 2025, which adds warehouse space for western shoppers.
What drives demand in the Eastern province?
Eastern Province held a 21.0% share of 2025 value and grows at 10.88% a year, because Dammam, Khobar and Jubail have high incomes and large expatriate communities. The province generated 15.90% of delivery orders in the fourth quarter of 2025 and held 6,659 e-commerce registrations. As a result, fashion and electronics orders flow steadily into the region from Riyadh hubs and from Gulf neighbors.
How do secondary cities push growth beyond the main hubs?
Secondary Cities and Northern Regions held a 10.6% share of 2025 value and grow fastest at 11.58% a year, because couriers are extending coverage to Madinah, Aseer, Qassim, Tabuk, Hail and Jazan. Madinah took 4.65% of delivery orders in the second quarter of 2025 and Aseer 3.56%. As a result, regional sorting points and partner pickup counters are spreading.
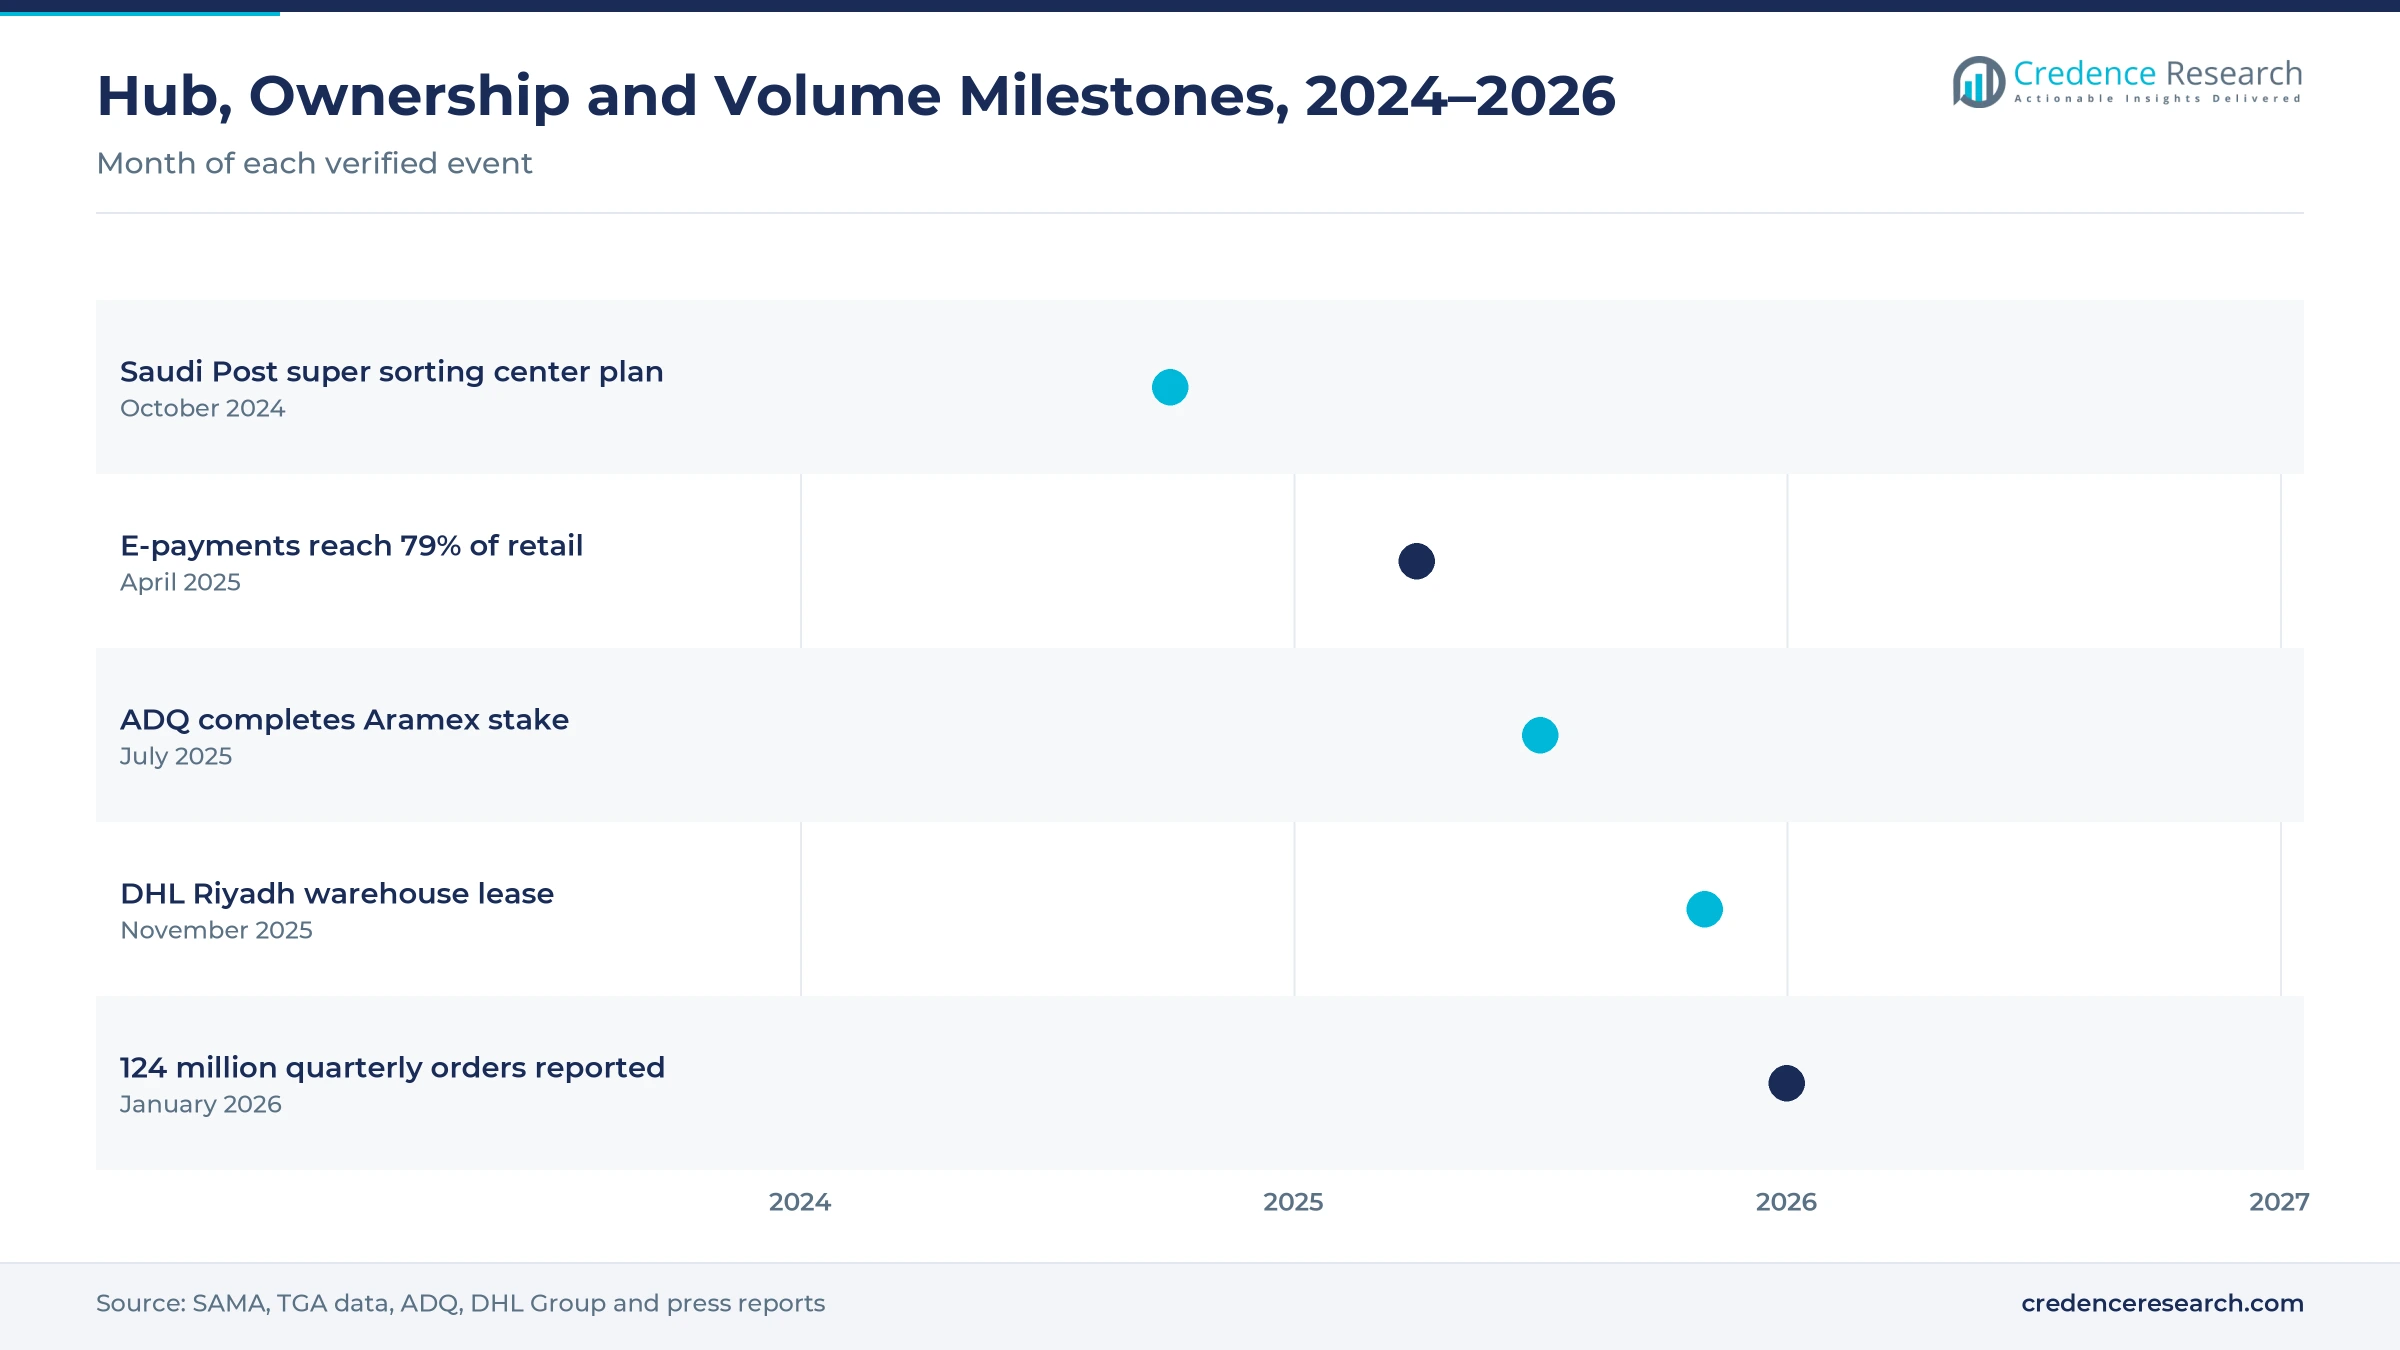
Hubs, acquisitions and record parcel volumes, 2024–2026
| Development | Status and market relevance |
|---|---|
| In October 2024, Saudi Post said it planned to launch the region's largest super sorting center. | Signals higher national sorting capacity |
| In April 2025, the Saudi Central Bank reported that electronic payments reached 79% of retail payments in 2024. | Reduces cash on delivery handling for couriers |
| In July 2025, ADQ completed its acquisition of a 63.16% stake in Aramex. | Brings new ownership to a major regional courier |
| In November 2025, DHL Supply Chain signed a 26-year lease for about 53,000 sqm of warehouse space in a Riyadh logistics zone. | Adds bonded multi-user fulfillment capacity |
| In January 2026, transport regulator data showed more than 124 million delivery orders in the fourth quarter of 2025, up 60%. | Confirms rapid growth in parcel demand |
Automated sorting, tracking and address data advance
- Automated sorting and warehouse systems move parcels through hubs with scanners and conveyors, which lets couriers handle tens of thousands of shipments a day with fewer errors and faster cut-off times for same-day dispatch.
- Live tracking and digital proof of delivery give sellers and shoppers real-time status updates, which cuts failed deliveries and supports the regulator's complaint rankings by giving carriers clear records of each handoff.
- Address data and route planning software match national address codes with traffic data, which helps courier and parcel services plan dense multi-stop routes in large cities and reduce failed first attempts.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Postal, express and fulfillment groups compete for sellers
Competition is split between the national postal group, regional express carriers, global integrators and newer parcel networks. Saudi Post said in October 2024 that it planned the region's largest super sorting center. NAQEL Express and J&T Express tied for the fewest complaints, one per 100,000 parcels, in the fourth quarter of 2024 ranking, while iMile Delivery recorded two. Aramex runs an automated airport facility in Riyadh that can handle up to 100,000 shipments a day, and ADQ took a 63.16% stake in the group in July 2025. DHL Supply Chain signed a lease in November 2025 for a large multi-user warehouse in Riyadh. Rivals compete on coverage, delivery speed, service scores, fulfillment capacity and price. Because sellers now compare published complaint rankings, service quality has become a key advantage.
Which couriers and fulfillment providers lead in Saudi Arabia?
| Company | Type | Role in the market |
|---|---|---|
| Saudi Post and Logistics (SPL) | National postal and parcel group | Planned the region's largest super sorting center in 2024 |
| NAQEL Express | Domestic express carrier | One complaint per 100,000 parcels in the fourth quarter of 2024 |
| J&T Express | Parcel delivery network | One complaint per 100,000 parcels in the fourth quarter of 2024 |
| Aramex | Regional express and logistics group | Automated Riyadh airport facility handling up to 100,000 shipments a day |
| DHL Supply Chain | Contract logistics provider | Signed a 26-year Riyadh warehouse lease in November 2025 |
| iMile Delivery | Parcel delivery network | Two complaints per 100,000 parcels in the fourth quarter of 2024 |
Credence Research view on Saudi online order logistics
Credence Research's view is that Saudi online order logistics will keep growing quickly because cashless payments, new logistics zones and wider courier coverage all lower the cost of buying online. Last-mile delivery remains the largest value pool, while warehousing and fulfillment add the fastest service growth. Published complaint rankings from the transport regulator reward reliable carriers with more seller contracts. Providers that combine bonded storage, automated sorting and strong regional reach should gain share fastest across the KSA e-commerce logistics and warehouse base over the next decade.
How the national online order logistics estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines central bank payment data, transport regulator delivery and parcel statistics, commerce ministry registration counts, World Bank population and internet data, and company announcements. Segment splits and zone growth rates are Credence Research estimates, while zone shares follow the client-defined split. Sources used are official statistics, government releases and company announcements, and no interviews or surveys were used.
Fulfillment and asset-light delivery lead growth to 2035
Online order logistics value is expected to reach USD 8.43 billion by 2035, a 10.99% CAGR during 2026–2035, as Saudi shoppers buy more goods online and sellers move stock into shared warehouses. Growth should come from fulfillment services, asset-light delivery platforms and secondary cities. New logistics zones and bonded corridors would support cross-border fulfillment, while rising delivery costs would pressure low-value orders. Providers with automated hubs, wide coverage and strong service scores are expected to gain the most as KSA e-commerce logistics and warehouse demand spreads nationwide.
Frequently Asked Questions
How big is the KSA e-commerce logistics and warehouse market?
Which service type leads Saudi online order logistics value?
Which region leads the Saudi market?
How many delivery orders were recorded in late 2025?
How widely do Saudi shoppers pay electronically?
Which business model is growing fastest?
Who are the leading companies in the Saudi market?
What are the main challenges for logistics providers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Type
- 1.2.1 Last-Mile Delivery
- 1.2.2 Warehousing and Fulfillment
- 1.2.3 Cross-Border Logistics
- 1.2.4 Returns and Value-Added Services
- 1.3 By Customer Type
- 1.3.1 Online Marketplaces
- 1.3.2 Omnichannel Retailers
- 1.3.3 Digital-Native Brands
- 1.3.4 Social Commerce Sellers
- 1.4 By End-Use Industry
- 1.4.1 Fashion and Apparel
- 1.4.2 Consumer Electronics
- 1.4.3 Beauty and Personal Care
- 1.4.4 Grocery and Specialty Food
- 1.5 By Business Model
- 1.5.1 Third-Party Fulfillment
- 1.5.2 Dedicated Contract Logistics
- 1.5.3 Asset-Light Delivery Orchestration
- 1.5.4 Integrated Marketplace Logistics
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 2.94 billion → 2035: USD 8.43 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 KSA E-Commerce Logistics and Warehouse Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 KSA E-Commerce Logistics and Warehouse Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 KSA E-Commerce Logistics and Warehouse Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 KSA E-Commerce Logistics and Warehouse Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 KSA E-Commerce Logistics and Warehouse Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 KSA E-Commerce Logistics and Warehouse Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 KSA E-Commerce Logistics and Warehouse Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 KSA E-Commerce Logistics and Warehouse Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 2.94 billion → 2035: USD 8.43 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 KSA E-Commerce Logistics and Warehouse Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Last-Mile Delivery
- 12.3.7.2 Warehousing and Fulfillment
- 12.3.7.3 Cross-Border Logistics
- 12.3.7.4 Returns and Value-Added Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Customer Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Online Marketplaces
- 12.4.7.2 Omnichannel Retailers
- 12.4.7.3 Digital-Native Brands
- 12.4.7.4 Social Commerce Sellers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fashion and Apparel
- 12.5.7.2 Consumer Electronics
- 12.5.7.3 Beauty and Personal Care
- 12.5.7.4 Grocery and Specialty Food
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Business Model - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Third-Party Fulfillment
- 12.6.7.2 Dedicated Contract Logistics
- 12.6.7.3 Asset-Light Delivery Orchestration
- 12.6.7.4 Integrated Marketplace Logistics
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 KSA E-Commerce Logistics and Warehouse End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 KSA E-Commerce Logistics and Warehouse Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 KSA E-Commerce Logistics and Warehouse Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 KSA E-Commerce Logistics and Warehouse Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Saudi Post and Logistics (SPL)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SMSA Express
- 18.4 NAQEL Express
- 18.5 Aramex
- 18.6 DHL Supply Chain
- 18.7 FedEx Express
- 18.8 UPS
- 18.9 AJEX Logistics Services
- 18.10 iMile Delivery
- 18.11 J&T Express
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

