
Market Overview:
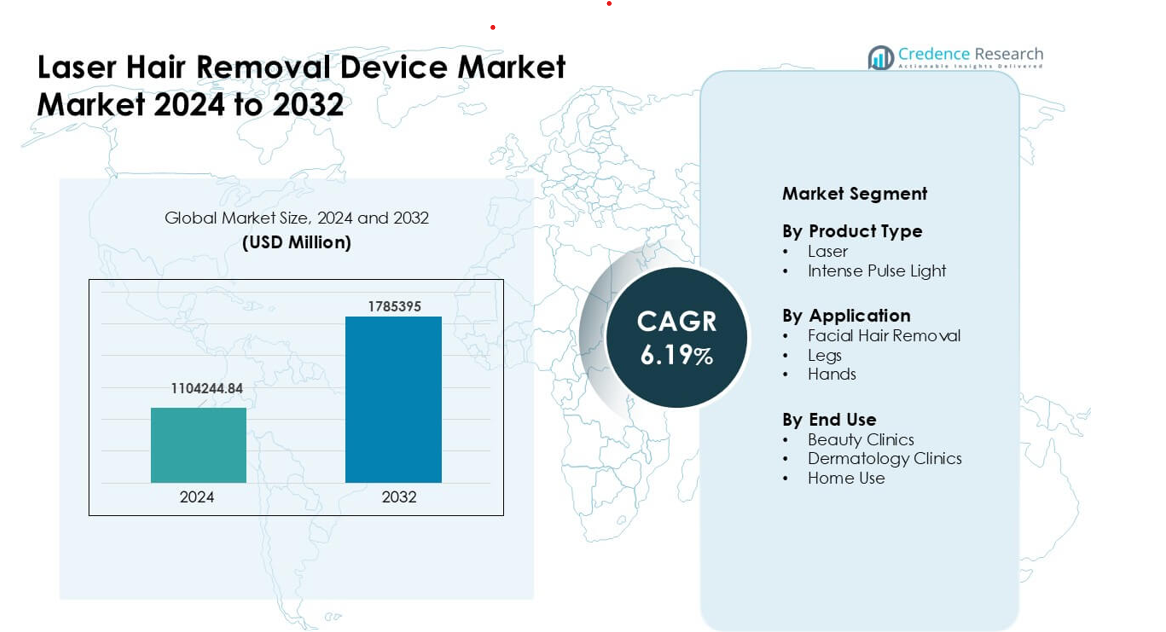
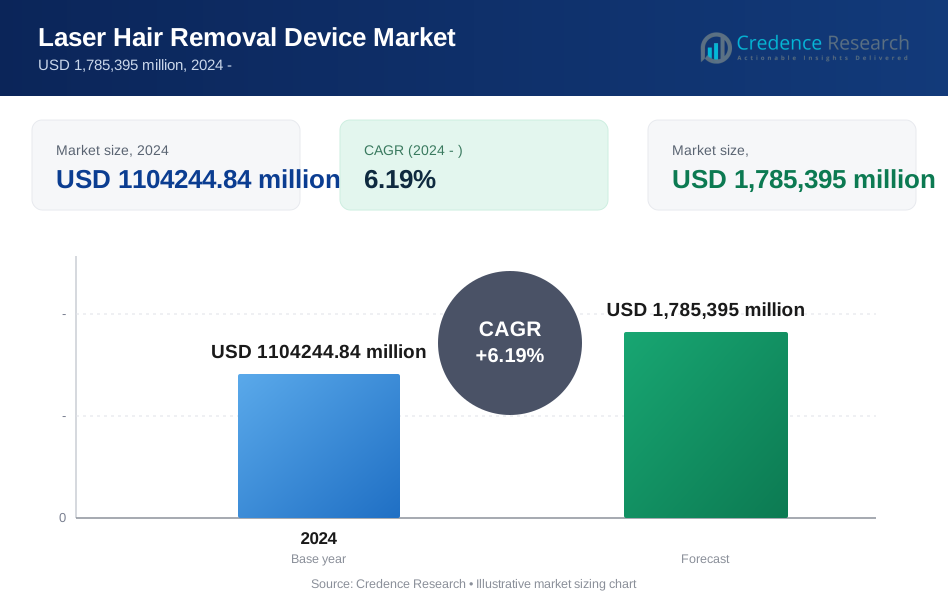
Laser Hair Removal Device Market was valued at USD 1104244.84 million in 2024 and is anticipated to reach USD 1785395 million by 2032, growing at a CAGR of 6.19% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Laser Hair Removal Device Market Size 2024 | USD 1104244.84 million |
| Laser Hair Removal Device Market, CAGR | 6.19% |
| Laser Hair Removal Device Market Size 2032 | USD 1785395 million |
Top players in the Laser Hair Removal Device Market include Viora, Cutera, Alma Lasers, Cynosure, Sciton, Syneron Medical, Lutronic, Solta Medical, Lumenis, and Venus Concept Canada Corp. These companies compete through advanced diode, alexandrite, and Nd:YAG platforms that offer higher precision, stronger safety, and faster treatment cycles. Many providers also expand global training, service networks, and device upgrades to meet rising demand across clinics and home-use segments. North America emerged as the leading region in 2024 with a 36% share, supported by strong aesthetic procedure adoption, high spending on premium technologies, and a dense clinic network.
Market Insights:
- The Laser Hair Removal Device Market reached a significant value at USD 1104244.84 million in 2024 and is projected to grow steadily by 2032 at a strong CAGR of 6.19%, supported by rising demand for long-term grooming solutions.
- Growing preference for non-invasive hair reduction drives adoption, with laser systems leading the product segment at about 62% share due to higher precision and consistent results.
- Smart, multi-skin-tone devices and compact home-use platforms shape key trends, improving accessibility and expanding consumer reach across younger groups.
- Market competition remains strong as players like Viora, Cutera, Alma Lasers, and Cynosure invest in advanced cooling, safety features, and training programs to sustain clinic and retail adoption.
- North America led the market with a 36% share, followed by Europe at 29% and Asia-Pacific at 24%, driven by dense clinic networks and expanding home-use device penetration across major economies
Market Segmentation Analysis:
By Product Type
Laser systems led the product type segment in 2024 with about 62% share. Laser devices gained strong demand due to higher precision, deeper follicle targeting, and better results on both light and dark skin tones. Many clinics adopted diode and Nd:YAG platforms because these systems reduced treatment time and improved comfort. Intense Pulse Light expanded in budget and home-use categories but lacked the consistency offered by laser units. Wider adoption of professional-grade laser technology and rising focus on long-term hair reduction supported the dominant position of laser devices.
- For instance, Lumenis’s LightSheer QUATTRO a diode‑laser work‑station features a large 22 × 35 mm spot‑size handpiece, enabling rapid treatment of larger areas and reducing session duration compared to older devices.
By Application
Facial hair removal dominated the application segment in 2024 with nearly 48% share. Users preferred facial treatments due to higher visibility concerns, quick results, and strong demand among women and men seeking grooming solutions. Clinics promoted targeted laser protocols that reduced regrowth and improved skin clarity, driving strong uptake. Legs and hands also grew as full-body grooming trends increased across younger groups. Higher spending on personal care and rising awareness of non-invasive aesthetic solutions helped facial hair removal maintain its leading position.
- For instance, a leading global device maker, Cynosure, offers laser hair‑removal platforms that dermatology clinics deploy for whole‑body sessions enabling a typical under‑arm or leg treatment in as little as 10–30 minutes depending on the area, thus making it practical for clients seeking full‑body grooming beyond just the face.
By End Use
Beauty clinics held the dominant end-use share in 2024 with around 52%. These centers attracted clients due to trained technicians, advanced laser platforms, and flexible treatment packages. Dermatology clinics grew as demand rose for medically supervised procedures, especially for sensitive skin and complex cases. Home-use devices gained traction in compact and low-energy formats but remained secondary due to limited power and slower results. Strong interest in professional-grade safety and better long-term outcomes kept beauty clinics ahead in most markets.
Key Growth Drivers:
Growing Demand for Long-Term Hair Reduction Solutions
Global users now seek long-term grooming methods that reduce repetitive shaving or waxing. Laser hair removal devices meet this need by offering durable results, shorter treatment cycles, and fewer skin issues. Beauty centers promote diode and Nd:YAG systems for consistent outcomes across many skin types, which builds confidence among new users. Rising awareness through social media, influencer reviews, and clinic marketing also speeds adoption. Men’s grooming demand adds new volume, especially for facial, chest, and back hair removal. As consumers look for non-invasive and time-saving options, long-term reduction becomes a strong growth engine for advanced devices.
- For instance, clinics deploying Lumenis’ diode‑laser system LightSheer DUET have benefited from its large spot‑size handpiece (22 × 35 mm) that enables rapid treatment of large body areas like back or legs in as little as ~15 minutes per session significantly cutting down on repetitive visits.
Advancements in Laser Technology and Treatment Precision
Laser engineering now provides improved cooling, stable energy delivery, and higher pulse accuracy. These upgrades help clinics achieve better results with less discomfort and lower risk of burns. New-generation diode and alexandrite systems also suit a wider range of tones, which expands the user base. Many brands integrate AI-assisted settings, skin sensors, and automated calibration to refine treatment precision. Mobile platforms and compact systems further support flexible use. As performance improves, clinics deliver faster sessions and higher throughput, raising revenue potential. This steady shift toward smarter and safer technology drives broader acceptance in both professional and home settings.
- For instance, the multi-wavelength platform Soprano ICE from Alma Lasers combining 755 nm (Alexandrite), 810 nm (diode), and 1064 nm (Nd:YAG) wavelengths uses continuous contact‑cooling (ICE™) and in-motion delivery at up to 10 Hz repetition rate, making treatments safer and practically painless even on tanned or darker skin tones, and enabling clinically proven hair reduction across all skin types.
Expansion of Beauty Clinics and At-Home Aesthetic Devices
Urban centers now host many advanced beauty clinics offering affordable treatment packages, EMI plans, and quick procedures. These clinics use premium laser units that attract a wide mix of clients seeking quality services. Meanwhile, at-home devices grow due to rising comfort with DIY grooming and interest in cost-effective solutions. Compact IPL and low-energy diode units appeal to first-time buyers who want privacy and convenience. Strong retail expansion, online sales channels, and influencer promotions boost visibility. Combined growth across professional and home segments increases overall device penetration and supports steady market expansion.
Key Trends & Opportunities:
Rising Popularity of Multi-Skin-Tone and Multi-Area Devices
Manufacturers now design systems that adjust to different skin tones and hair densities using automatic detection tools. These devices offer stronger versatility, which suits clinics handling diverse customer groups. Broader compatibility across facial, leg, and underarm areas also improves utility. Home-use devices reflect the same trend, with preset modes for beginners. This shift ensures safer outcomes and reduces dependency on manual settings. As inclusive grooming solutions gain attention, the trend supports larger buyer segments and improves product adoption across global markets.
- For instance, the Philips Lumea 9000 Series BRI958/00 uses a SmartSkin sensor to automatically detect skin tone and adjust light intensity accordingly this makes it usable across a wide range of skin tones and reduces risk of over‑treatment. The device comes with four different attachments (for face, underarms, bikini, and legs), making it practical for full‑body grooming beyond just one area.
Growing Integration of Smart Features and Digital Interfaces
Laser hair removal technology now includes mobile apps, treatment tracking tools, and guided safety prompts. These features help users follow correct routines, schedule follow-ups, and track skin response. Clinics benefit from digital dashboards that manage patient history and optimize device calibration. Smart connectivity improves user experience and reduces errors, especially for home devices. This digital enhancement builds trust among new users and encourages repeat sessions. As smart aesthetics grow, device value increases and supports stronger competitive differentiation.
- For instance, many modern home‑use IPL and laser devices (like those from leading brands) bundle a companion app that guides users step‑by‑step: it may prompt you to run a patch test, choose appropriate intensity based on skin tone/hair type, remind you of upcoming sessions, and log each session’s results (hair regrowth, skin sensitivity, etc.). This digital interface lowers the barrier for first‑time users and reduces human error in settings, making hair‑removal safer and more user‑friendly particularly for non‑professional consumers.
Key Challenges:
High Initial Device Cost and Limited Access in Developing Regions
Professional laser units require large capital investments, which challenges small clinics in emerging markets. Maintenance fees, part replacements, and training costs add pressure. Home-use devices remain cheaper but still exceed mass-market affordability in many regions. Limited financing options and weak clinic density restrict availability, especially in rural zones. These barriers slow adoption and reduce overall penetration rates. Without lower-cost models or better financing support, many users remain dependent on temporary grooming options, affecting long-term market expansion.
Safety Concerns and Need for Skilled Technicians
Laser treatments require knowledge of skin response, energy levels, and contraindications. Inadequate training can lead to burns, pigmentation changes, or ineffective results. Many regions lack strict regulatory standards, which increases operator risk. Users also hesitate to adopt home devices due to fear of improper use or skin sensitivity. Clinics must invest in certification and training programs to minimize complications. As safety expectations rise, brands must deliver clearer guidance, better sensors, and automated controls. Failure to address safety challenges may limit trust and slow adoption across both professional and home segments.
Regional Analysis:
North America
North America led the Laser Hair Removal Device Market in 2024 with about 36% share. Strong demand came from high spending on aesthetic treatments, early adoption of professional laser platforms, and a dense network of beauty and dermatology clinics. Users preferred diode and alexandrite systems due to proven precision and faster results. Home-use devices also gained traction through large e-commerce channels. Rising interest among men and younger consumers supported steady treatment volume. Continuous technology upgrades and clear regulatory pathways helped North America maintain its leadership across both professional and personal-use segments.
Europe
Europe held nearly 29% share in 2024, supported by strong acceptance of medical-grade aesthetics and wide access to certified dermatology clinics. Consumers favored safe, high-performance laser systems aligned with strict EU safety standards. Demand increased across Germany, the U.K., France, and Italy due to rising interest in long-term grooming and wellness. Expansion of med-spa chains and broader training programs strengthened service quality. Home-use IPL units also saw steady growth through pharmacy and online retail channels. Europe’s focus on regulated technology, skilled operators, and premium treatments helped the region retain a strong position.
Asia-Pacific
Asia-Pacific accounted for around 24% share in 2024 and showed the fastest growth due to rising disposable income, urban lifestyle shifts, and expanding beauty clinic networks. Countries such as China, Japan, South Korea, and India led demand for diode and Nd:YAG systems suited to diverse skin tones. Social-media influence and wider acceptance of non-invasive grooming boosted adoption among younger buyers. Home-use devices expanded rapidly through online platforms. Lower treatment costs and increasing clinic availability improved accessibility, allowing Asia-Pacific to emerge as a high-potential market with strong future expansion prospects.
Latin America
Latin America captured about 7% share in 2024, driven by growing interest in aesthetic procedures across Brazil, Mexico, and Argentina. Beauty clinics expanded their offerings using mid-range diode and IPL systems that balanced performance and affordability. Rising influence of beauty culture and social media pushed higher demand among women and men seeking long-term grooming. Economic fluctuations limited premium device penetration, but installment plans and competitive clinic pricing supported steady uptake. Home-use devices gradually gained visibility through online retail. These factors helped Latin America develop as a developing yet promising market.
Middle East & Africa
The Middle East & Africa region held around 4% share in 2024, supported by strong cosmetic procedure demand in the UAE, Saudi Arabia, and South Africa. Clinics invested in advanced diode and Nd:YAG platforms capable of treating darker skin tones with higher safety. High-income urban centers drove most adoption, while rural areas saw limited penetration due to cost barriers. Medical tourism further boosted demand in select countries offering premium treatments. Home-use devices posted gradual growth. Despite smaller share, rising beauty awareness and expanding clinic networks position MEA as an emerging opportunity zone.
Market Segmentations:
By Product Type
- Laser
- Intense Pulse Light
By Application
- Facial Hair Removal
- Legs
- Hands
By End Use
- Beauty Clinics
- Dermatology Clinics
- Home Use
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape:
The competitive landscape of the Laser Hair Removal Device Market features strong participation from leading companies such as Viora, Cutera, Alma Lasers, Cynosure, Sciton, Syneron Medical, Lutronic, Solta Medical, Lumenis, and Venus Concept Canada Corp. These manufacturers compete through advanced diode, alexandrite, and Nd:YAG systems designed for higher precision, faster sessions, and safer outcomes across multiple skin tones. Many brands focus on integrated cooling, AI-assisted settings, and ergonomic designs that improve user comfort and treatment efficiency. Companies also expand after-sales support, technician training, and global distribution to strengthen clinic adoption. In the home-use segment, compact IPL and low-energy diode devices widen reach through retail and e-commerce platforms. Continuous R&D investment, regulatory approvals, and strategic partnerships help players maintain strong market visibility and respond to rising demand for non-invasive grooming solutions.
Key Player Analysis:
- Viora
- Cutera
- Alma Lasers
- Cynosure, Inc.
- Sciton, Inc.
- Syneron Medical Ltd.
- Lutronic
- Solta Medical, Inc.
- Lumenis
- Venus Concept Canada Corp.
Recent Developments:
- In April 2025, Lumenis unveiled an enhanced SPLENDOR X laser hair removal solution at the ASLMS conference, adding new preset parameters for hair removal and vascular work plus digital capabilities for better uptime and data services in the US and Canada.
- In October 2024, Research and Markets’ Laser Hair Removal Devices Global Strategic Business Report profiled Solta Medical as one of a small group of focus players in the global laser hair removal devices market, underlining its continued role in professional energy-based hair removal systems.
- In April 2024, Cutera announced the North America launch of the redesigned xeo+ platform (updated handpieces, faster treatment times and usability improvements for multi-application devices including hair removal).
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market
Future Outlook:
- Demand for long-term hair reduction will rise as grooming habits shift toward non-invasive solutions.
- Advanced diode and alexandrite systems will gain wider use for higher precision and safer outcomes.
- Home-use devices will expand due to stronger e-commerce presence and improving device safety.
- AI-enabled treatment settings will improve accuracy and reduce operator errors in clinics.
- Multi-skin-tone compatibility will broaden adoption across diverse global populations.
- Beauty clinics will invest more in premium platforms to increase treatment speed and improve revenue.
- Dermatology clinics will adopt upgraded systems for sensitive-skin treatments and medical-grade procedures.
- Hybrid devices with cooling and smart sensors will enhance comfort and reduce complications.
- Emerging regions will see faster adoption due to rising awareness and competitive clinic pricing.
- Strong competition among leading brands will drive continuous innovation and product refinement.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Laser Hair Removal Device Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is Laser Hair Removal Device Market projected to grow between 2024 and 2032?
Which Laser Hair Removal Device Market segment held the largest share in 2024?
What are the primary factors fueling the growth of Laser Hair Removal Device Market?
Who are the leading companies in Laser Hair Removal Device Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1104244.84 million → 2032: USD 1,785,395 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Laser Hair Removal Device Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Laser Hair Removal Device Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Laser Hair Removal Device Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Laser Hair Removal Device Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Laser Hair Removal Device Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Laser Hair Removal Device Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Laser Hair Removal Device Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Laser Hair Removal Device Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1104244.84 million → 2032: USD 1,785,395 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Laser Hair Removal Device Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Laser Hair Removal Device Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Laser Hair Removal Device Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Laser Hair Removal Device Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

