
Market Overview:
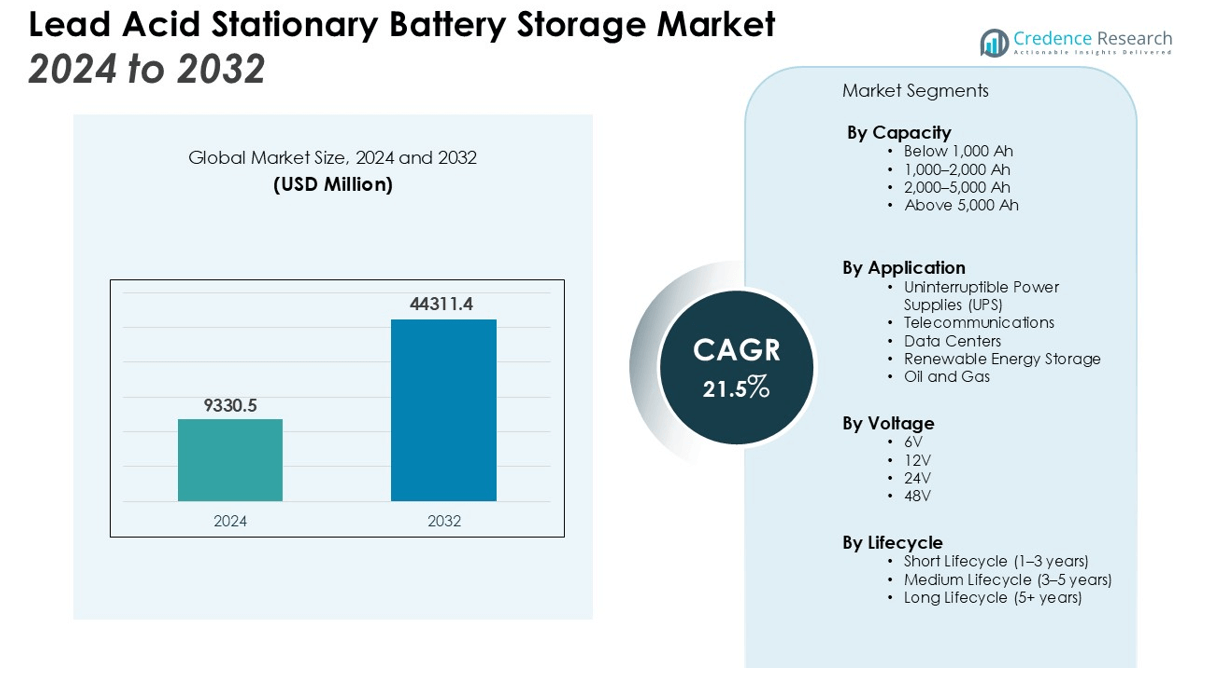
The Lead Acid Stationary Battery Storage Market size was valued at USD 9330.5 million in 2024 and is anticipated to reach USD 44311.4 million by 2032, at a CAGR of 21.5% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Lead Acid Stationary Battery Storage Market Size 2024 | USD 9330.5 million |
| Lead Acid Stationary Battery Storage Market, CAGR | 21.5% |
| Lead Acid Stationary Battery Storage Market Size 2032 | USD 44311.4 million |
Key drivers of this market include the rising adoption of renewable energy sources, which necessitate efficient storage systems to manage intermittent power generation. Lead acid batteries, particularly Valve-Regulated Lead-Acid (VRLA) types, offer a balance between cost and performance, making them suitable for applications such as uninterruptible power supplies (UPS), telecommunications, and data centers. Additionally, advancements in battery technology and recycling processes are enhancing the appeal of lead acid batteries in stationary applications. The cost-effectiveness and recyclability of lead acid batteries further contribute to their widespread adoption across various industries.
Regionally, North America held a significant market share in 2023, driven by industrial demand and supportive energy policies. Europe follows closely, with strong government incentives promoting energy storage systems. The Asia-Pacific region, particularly countries like China and India, is experiencing rapid growth due to industrialization, urbanization, and increasing energy storage requirements. This regional diversification underscores the global shift towards sustainable and resilient energy infrastructures. Furthermore, the ongoing investments in grid modernization and renewable energy projects globally are set to further propel the demand for stationary battery storage solutions.
Market Insights:
- The Lead Acid Stationary Battery Storage Market was valued at USD 9330.5 million in 2024 and is projected to reach USD 44311.4 million by 2032, growing at a CAGR of 21.5% during the forecast period.
- The rising adoption of renewable energy sources is driving the demand for efficient energy storage systems. Lead acid batteries, particularly Valve-Regulated Lead-Acid (VRLA) types, offer a balance of cost and performance, making them ideal for uninterruptible power supplies (UPS), telecommunications, and data centers.
- Governments worldwide are implementing policies and incentives to promote energy storage systems, further driving the adoption of lead acid stationary batteries, especially in regions with ambitious renewable energy targets.
- Lead acid stationary batteries are known for their cost-effectiveness and established technology. Their affordability and widespread availability make them a preferred choice for many industries, supported by a mature recycling infrastructure that enhances their economic viability.
- North America led the market in 2023, capturing 38% of the share, driven by industrial demand and energy policies that promote grid resilience and backup power solutions.
- Europe followed closely with 33% of the market share, with countries like Germany and Italy at the forefront of battery energy storage capacity, fueled by strong renewable energy integration and regulatory incentives.
- The Asia-Pacific region holds a 23% share, propelled by rapid industrialization, urbanization, and growing energy storage needs in countries like China and India, driving the demand for cost-effective energy storage solutions.
Market Drivers:
Integration of Renewable Energy Sources
The global transition to renewable energy sources, such as solar and wind, necessitates efficient energy storage solutions to manage their intermittent nature. Lead acid stationary battery storage systems offer a cost-effective and reliable means to store excess energy generated during peak production periods. This capability ensures a stable power supply during periods of low generation, facilitating the integration of renewable energy into the grid and supporting sustainability goals.
- For instance, Tesla advanced the integration of clean energy by deploying 31.4 GWh of battery storage worldwide in 2024, a figure that more than doubled its deployments from the previous year.
Demand for Uninterrupted Power Supply
Industries and critical infrastructure sectors require a consistent and reliable power supply to maintain operations. Lead acid stationary batteries provide an effective solution for uninterruptible power supply (UPS) systems, ensuring continuous power during outages. Their ability to deliver high surge currents makes them suitable for applications in telecommunications, data centers, and healthcare facilities, where power reliability is paramount.
Cost-Effectiveness and Established Technology
Lead acid batteries are among the most cost-effective energy storage solutions available, offering a balance between performance and affordability. Their well-established technology and widespread availability make them a preferred choice for many applications. The mature recycling infrastructure for lead acid batteries also contributes to their economic viability, supporting a circular economy and reducing environmental impact.
- For instance, thanks to a robust, coast-to-coast lead battery infrastructure in the U.S., the industry successfully keeps approximately 160 million used batteries out of landfills every year.
Government Incentives and Policy Support
Governments worldwide are implementing policies and providing incentives to promote the adoption of energy storage systems. These initiatives aim to enhance energy security, reduce carbon emissions, and support the transition to cleaner energy sources. Such policy support is driving the adoption of lead acid stationary battery storage systems, particularly in regions with ambitious renewable energy targets and grid modernization plans.
Market Trends:
Shift Towards Hybrid and Modular Energy Storage Systems
The stationary battery storage market is witnessing a significant shift towards hybrid and modular energy storage systems. These systems combine different battery technologies, such as lead-acid and lithium-ion, to optimize performance and cost-effectiveness. Hybrid systems offer enhanced flexibility, allowing users to tailor energy storage solutions to their specific needs. Modular designs facilitate scalability, enabling easy expansion as energy demands grow. This trend is driven by the increasing need for efficient and adaptable energy storage solutions across various sectors, including residential, commercial, and industrial applications.
- For instance, the Tesla Megapack, a large-scale modular battery system, has a storage capacity of up to 3.9 megawatt-hours (MWh) per unit.
Advancements in Battery Recycling and Sustainability Initiatives
Advancements in battery recycling technologies are playing a crucial role in enhancing the sustainability of lead acid stationary battery storage systems. Companies are investing in closed-loop recycling processes, recovering lead and other materials from used batteries to produce new ones. This not only reduces the environmental impact but also lowers the demand for raw materials. Additionally, sustainability initiatives are gaining momentum, with manufacturers focusing on improving battery lifespan and reducing energy consumption during production. These efforts contribute to the overall growth and acceptance of lead acid stationary battery storage systems as environmentally responsible energy solutions.
- For instance, San-Lan has developed recycling equipment technology that allows for the recovery of 998 kilograms of lead for every 1,000 kilograms of battery lead that is processed.
Market Challenges Analysis:
Environmental and Health Concerns
Lead acid stationary battery storage systems face significant environmental and health challenges due to the toxic nature of lead and sulfuric acid. Improper disposal and recycling of these batteries can lead to soil and water contamination, posing risks to human health and ecosystems. Additionally, the production and recycling processes can release harmful pollutants, contributing to air and water pollution. These issues have led to stricter regulations and increased scrutiny from environmental agencies, potentially increasing operational costs and affecting market growth.
Competition from Advanced Battery Technologies
The lead acid stationary battery storage market is experiencing intensified competition from advanced battery technologies, particularly lithium-ion batteries. Lithium-ion batteries offer higher energy density, longer cycle life, and reduced maintenance requirements compared to lead acid batteries. As a result, industries and consumers are increasingly opting for lithium-ion solutions, especially in applications where space, weight, and performance are critical. This shift poses a challenge for lead acid batteries to maintain their market share and necessitates innovation and adaptation within the industry.
Market Opportunities:
Expansion into Emerging Markets
The lead acid stationary battery storage market presents significant opportunities in emerging economies experiencing rapid industrialization and urbanization. Regions such as Asia, Africa, and South America are witnessing increased energy consumption due to growing middle classes and expanding industrial sectors. For instance, countries like India and Brazil are implementing aggressive renewable energy integration plans, which include substantial investments in solar and wind capacities. Governments in these regions are supporting the adoption of energy storage technologies through various incentives such as tax breaks, subsidies, and favorable regulations. This combination of increasing energy demand, favorable government policies, and the critical need for grid modernization positions lead acid stationary battery storage systems as a viable solution to meet these challenges.
Integration with Renewable Energy Sources
The global transition towards renewable energy sources, such as solar and wind, necessitates efficient energy storage solutions to manage their intermittent nature. Lead acid stationary batteries offer a cost-effective and reliable means to store excess energy generated during peak production periods. This capability ensures a stable power supply during periods of low generation, facilitating the integration of renewable energy into the grid. The growing adoption of renewable energy sources is driving the demand for stationary lead acid battery storage systems, particularly in applications like uninterruptible power supplies (UPS), telecommunications, and data centers. Additionally, advancements in battery technology and recycling processes are enhancing the appeal of lead acid batteries in stationary applications, further supporting their role in sustainable energy infrastructures.
Market Segmentation Analysis:
By Capacity
The market is segmented into four capacity ranges: Below 1,000 Ah, 1,000–2,000 Ah, 2,000–5,000 Ah, and Above 5,000 Ah. The 1,000–2,000 Ah segment holds the largest market share, driven by its widespread adoption in uninterruptible power supplies (UPS) and telecommunications. The Below 1,000 Ah segment is projected to witness the highest growth rate, fueled by increasing demand for small-scale energy storage solutions in residential and commercial sectors. The 2,000–5,000 Ah segment is significant in large-scale applications such as grid balancing and renewable energy integration. The Above 5,000 Ah segment is gaining traction due to the growing need for high-capacity energy storage solutions in industrial and utility applications.
- For instance, Aoke Epower Co., Ltd. manufactures the AK-EH04 solar storage system, which features LFP battery technology and has a nominal capacity of 300 Ah.
By Application
Key applications include UPS systems, telecommunications, data centers, renewable energy storage, and oil and gas sectors. The UPS segment is expected to dominate, driven by the need for reliable backup power in critical infrastructure. Telecommunications and data centers also represent substantial portions of the market, requiring uninterrupted power supply to maintain operations. Renewable energy storage is an emerging application, facilitating the integration of solar and wind energy into the grid. The oil and gas sector utilizes stationary lead acid batteries for backup power in remote locations and offshore platforms.
- For instance, Huawei’s FusionPower UPS5000-H series for data centers can achieve a power capacity of 1 megawatt in a single rack, a design that supports high-density deployments.
By Voltage
Voltage options in the market include 6V, 12V, 24V, and 48V. The 12V segment is anticipated to hold the largest market share, owing to its versatility and widespread use in various applications, including UPS systems, automotive batteries, and renewable energy storage. The 6V segment is expected to grow steadily, driven by its adoption in small-scale applications such as emergency lighting and portable devices. The 24V and 48V segments are projected to expand, particularly in industrial and commercial applications requiring higher power capacities.
Segmentations:
By Capacity- Below 1,000 Ah
- 1,000–2,000 Ah
- 2,000–5,000 Ah
- Above 5,000 Ah
- Uninterruptible Power Supplies (UPS)
- Telecommunications
- Data Centers
- Renewable Energy Storage
- Oil and Gas
- 6V
- 12V
- 24V
- 48V
- Short Lifecycle (1–3 years)
- Medium Lifecycle (3–5 years)
- Long Lifecycle (5+ years)
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America held a significant share of 38% in the stationary lead acid battery storage market, driven by a strong industrial base and rising demand for reliable backup power. The United States, in particular, is projected to surpass substantial market value, fueled by applications in data centers, telecommunications, and utilities. The region's established infrastructure and emphasis on energy resilience contribute to its market dominance. With increasing demand for grid stabilization and power backup solutions, North America remains a key player in the market.
Europe
Europe accounted for 33% of the market share, with countries like Germany and Italy leading in battery energy storage capacity. Germany has seen strong installations of home storage systems in recent years. The region's commitment to renewable energy integration and stringent environmental regulations support the adoption of lead acid stationary battery storage systems for grid stabilization and backup power. As a major player in the renewable energy sector, Europe is well-positioned for continued growth in battery storage solutions.
Asia-Pacific
The Asia-Pacific region captured a market share of 23%, driven by rapid industrialization and growing energy demand in countries like China and India. These nations are focusing on expanding renewable energy capacity and improving grid infrastructure, creating a significant opportunity for lead acid battery storage solutions. The region’s emphasis on cost-effective and scalable energy storage systems is expected to drive its market share further, especially in emerging economies where energy demand is rapidly increasing.
Key Player Analysis:
- Exide Technologies
- Crown Battery Manufacturing Co.
- S. Battery Manufacturing Co.
- GNB Industrial Power
- Yuasa Battery Co. Ltd.
- Fiamm S.p.A.
- Trojan Battery Co.
- HBL Power Systems
- Enersys
- East Penn Manufacturing Co.
- Leoch Battery Group Co. Ltd.
- Johnson Controls Inc.
Competitive Analysis:
The Lead Acid Stationary Battery Storage Market is competitive, with key players like Exide Technologies, Crown Battery Manufacturing Co., HOPPECKE Batterien, and East Penn Manufacturing Co. dominating the landscape. Exide Technologies is notable for its broad range of products and strong R&D focus, continuously improving battery efficiency and performance. Crown Battery, known for long-lasting, durable batteries, and HOPPECKE, offering comprehensive industrial solutions, also hold significant positions in the market. East Penn's extensive product portfolio and global presence further enhance its competitive edge. These companies differentiate themselves through technological advancements, high-quality products, and robust customer service. The rising demand for energy storage solutions, particularly driven by renewable energy integration and backup power needs, intensifies competition. Players are focusing on expanding their offerings, improving performance, and tapping into new markets to maintain their market leadership.
Recent Developments:
- In July 2025, Exide Technologies launched its new EZ800 Dual EFB battery, designed for marine and leisure applications.
- In July 2025, GS Yuasa launched its next-generation SWL+ series of Valve Regulated Lead Acid (VRLA) batteries for uninterruptible power supply (UPS) and other standby power applications.
- In March 2025, East Penn Manufacturing Co. launched its new Deka Ready Power product family, which includes both Lithium and Gel battery technologies, at the ProMat 2025 trade show.
Market Concentration & Characteristics:
The Lead Acid Stationary Battery Storage Market is moderately concentrated, with several key players holding substantial market shares. Leading companies, including Exide Technologies, Crown Battery, HOPPECKE, and East Penn Manufacturing, dominate the market by offering a wide range of reliable and cost-effective solutions for various applications. These companies leverage strong research and development capabilities to improve battery performance, efficiency, and lifespan. The market is characterized by high competition, as manufacturers focus on product innovation, technological advancements, and expanding their global presence. Despite this, there remains room for regional players to enter and establish a presence by offering tailored solutions and capitalizing on specific industry needs. The market’s characteristics include a steady demand for energy storage solutions driven by the adoption of renewable energy, growing industrial applications, and the increasing need for backup power systems in critical sectors.
Report Coverage:
The research report offers an in-depth analysis based on Capacity, Application, Voltage, Lifecycle and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Lead Acid Stationary Battery Storage Market will continue to benefit from the increasing adoption of renewable energy sources, requiring reliable energy storage solutions for grid integration.
- Technological advancements in battery design and recycling processes will enhance the efficiency and sustainability of lead acid batteries.
- The demand for uninterruptible power supply (UPS) systems, particularly in critical industries like telecommunications, data centers, and healthcare, will drive further growth.
- Government policies and incentives supporting renewable energy adoption and energy storage systems will provide a favorable environment for market expansion.
- The rise in industrialization and urbanization, especially in developing economies, will increase the need for energy storage solutions in commercial and residential sectors.
- Competition from advanced battery technologies, such as lithium-ion, will encourage continuous improvements in lead acid battery performance.
- Regional diversification will lead to increased market opportunities, especially in emerging markets like Asia-Pacific and Latin America.
- The growing focus on energy security and the need for reliable backup power will continue to drive demand in various applications, including oil and gas and large-scale energy storage.
- Manufacturers will invest more in expanding their product portfolios and entering new markets to maintain a competitive edge.
- The shift towards more sustainable and environmentally friendly solutions will drive innovation in lead acid battery recycling and lifespan improvements.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Integration of Renewable Energy Sources
The increasing adoption of solar and wind power requires efficient storage solutions to manage intermittent generation. Lead acid stationary batteries provide a cost-effective and reliable means to store excess energy, supporting grid stability and renewable integration.
Demand for Uninterruptible Power Supply (UPS)
Critical infrastructure sectors such as data centers, telecommunications, and healthcare require reliable backup power. Lead acid batteries are widely used in UPS systems due to their ability to deliver high surge currents and ensure continuous operations during outages.
Cost-Effectiveness and Established Technology
Lead acid batteries offer a favorable balance between performance and affordability, making them attractive for a wide range of stationary applications. Their mature technology and robust recycling infrastructure further enhance their economic viability and environmental appeal.
Government Incentives and Policy Support
Global policies and incentives aimed at promoting energy storage and renewable integration are accelerating the adoption of lead acid stationary battery systems, especially in regions with ambitious clean energy targets and grid modernization initiatives.
Advancements in Battery Recycling and Sustainability
Improvements in recycling technologies and closed-loop processes are reducing the environmental impact of lead acid batteries. Enhanced sustainability and resource recovery are making these batteries more attractive for stationary storage applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Lead Acid Stationary Battery Storage, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Lead Acid Stationary Battery Storage market projected to grow between 2024 and 2032?
Which Lead Acid Stationary Battery Storage market segment held the largest share in 2024?
Who are the leading companies in the Lead Acid Stationary Battery Storage market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Voltage
- 1.2.1 6V
- 1.2.2 12V
- 1.2.3 24V
- 1.2.4 48V
- 1.3 By Capacity
- 1.3.1 Below 1,000 Ah
- 1.3.2 1,000–2,000 Ah
- 1.3.3 2,000–5,000 Ah
- 1.3.4 Above 5,000 Ah
- 1.4 By Lifecycle
- 1.4.1 Short Lifecycle (1–3 years)
- 1.4.2 Medium Lifecycle (3–5 years)
- 1.4.3 Long Lifecycle (5+ years)
- 1.5 By Application
- 1.5.1 Uninterruptible Power Supplies (UPS)
- 1.5.2 Telecommunications
- 1.5.3 Data Centers
- 1.5.4 Renewable Energy Storage
- 1.5.5 Oil and Gas
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9330.5 million → 2032: USD 44311.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Lead Acid Stationary Battery Storage Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Lead Acid Stationary Battery Storage Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Lead Acid Stationary Battery Storage Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Lead Acid Stationary Battery Storage Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Lead Acid Stationary Battery Storage Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Lead Acid Stationary Battery Storage Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Lead Acid Stationary Battery Storage Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Lead Acid Stationary Battery Storage Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9330.5 million → 2032: USD 44311.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Lead Acid Stationary Battery Storage Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Voltage - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 6V
- 12.3.7.2 12V
- 12.3.7.3 24V
- 12.3.7.4 48V
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Capacity - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Below 1,000 Ah
- 12.4.7.2 1,000–2,000 Ah
- 12.4.7.3 2,000–5,000 Ah
- 12.4.7.4 Above 5,000 Ah
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Lifecycle - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Short Lifecycle (1–3 years)
- 12.5.7.2 Medium Lifecycle (3–5 years)
- 12.5.7.3 Long Lifecycle (5+ years)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Uninterruptible Power Supplies (UPS)
- 12.6.7.2 Telecommunications
- 12.6.7.3 Data Centers
- 12.6.7.4 Renewable Energy Storage
- 12.6.7.5 Oil and Gas
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Lead Acid Stationary Battery Storage End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Lead Acid Stationary Battery Storage Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Lead Acid Stationary Battery Storage Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Lead Acid Stationary Battery Storage Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Exide Technologies
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Crown Battery Manufacturing Co.
- 18.4 HOPPECKE Batterien
- 18.5 East Penn Manufacturing Co.
- 18.6 Enersys
- 18.7 Leoch Battery Group Co. Ltd.
- 18.8 GS Yuasa
- 18.9 Fiamm S.p.A.
- 18.10 Trojan Battery Co.
- 18.11 Johnson Controls Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

