
Market Overview
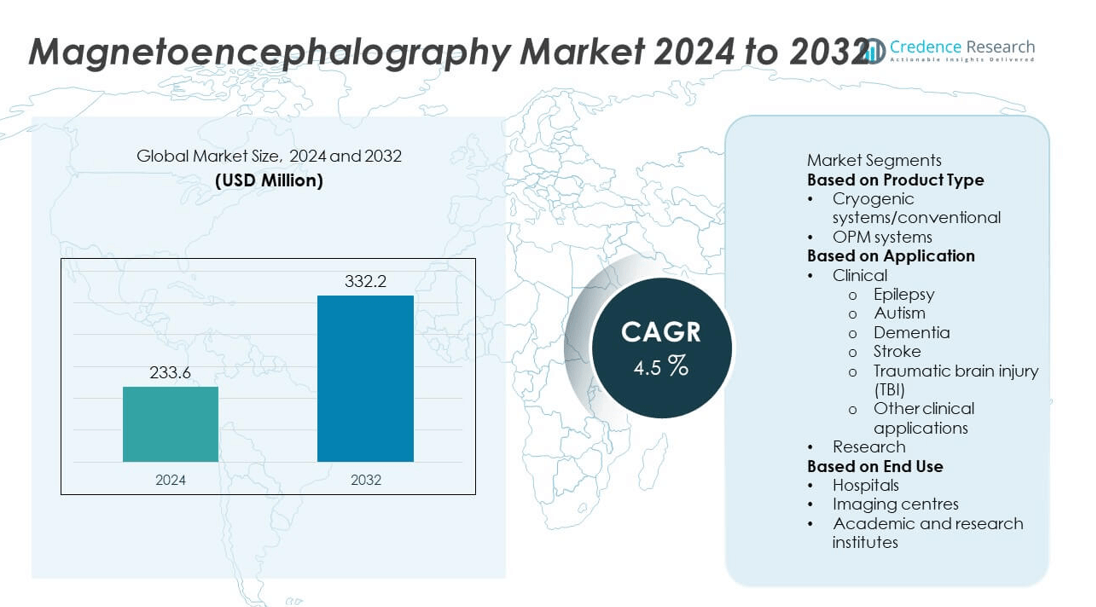
The Magnetoencephalography Market size was valued at USD 233.6 million in 2024 and is anticipated to reach USD 332.2 million by 2032, growing at a steady CAGR of 4.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Magnetoencephalography Market Size 2024 | USD 233.6 million |
| Magnetoencephalography Market, CAGR | 4.5% |
| Magnetoencephalography Market Size 2032 | USD 332.2 million |
The Magnetoencephalography Market grows steadily with rising demand for advanced neuroimaging to address neurological disorders such as epilepsy, Alzheimer’s, and Parkinson’s disease. It benefits from increasing adoption in presurgical planning, early diagnosis, and functional brain mapping, where high temporal resolution is critical.
The Magnetoencephalography Market demonstrates strong geographical presence across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. North America leads adoption due to advanced healthcare infrastructure, early use of MEG in epilepsy and brain mapping, and strong investment in neuroscience research. Europe follows with significant contributions from Germany, the United Kingdom, and France, where government funding and academic collaborations drive innovation in clinical and research applications. Asia-Pacific shows rapid growth supported by increasing healthcare modernization in Japan, China, and India, alongside growing demand for non-invasive neuroimaging solutions. Latin America and the Middle East & Africa are gradually expanding adoption through partnerships and medical infrastructure development. Key players shaping the Magnetoencephalography Market include Ricoh USA, MEGIN, Compumedics, and Cerca Magnetics, each focusing on advanced MEG systems, technological integration, and expanding global reach to support both clinical diagnostics and cutting-edge neuroscience research.
Market Insights
- The Magnetoencephalography Market was valued at USD 233.6 million in 2024 and is projected to reach USD 332.2 million by 2032, growing at a CAGR of 4.5% during the forecast period.
- Rising demand for accurate neuroimaging drives growth, with MEG widely used in epilepsy presurgical planning, Alzheimer’s detection, and brain connectivity research.
- Key market trends include integration with artificial intelligence for advanced data analysis, development of portable and wearable MEG systems, and expanding use in psychiatric and cognitive neuroscience studies.
- Competitive analysis highlights major players such as Ricoh USA, MEGIN, Compumedics, and Cerca Magnetics, which focus on sensor innovation, system upgrades, and global expansion strategies to strengthen market presence.
- Market restraints include high equipment costs, complex infrastructure requirements, and shortage of skilled professionals trained in MEG data interpretation and system operation.
- Regional analysis shows North America leading adoption due to advanced healthcare infrastructure, Europe emphasizing research collaborations and early diagnosis, Asia-Pacific gaining momentum through healthcare modernization, while Latin America and the Middle East & Africa expand gradually with emerging opportunities.
- The market continues to evolve through collaborative projects between hospitals, research institutes, and industry players, positioning MEG as a critical tool in precision medicine, neuroscience research, and long-term development of non-invasive brain imaging technologies.
Market Drivers
Rising Prevalence of Neurological Disorders and Epilepsy Cases
The Magnetoencephalography Market grows with increasing cases of epilepsy, Alzheimer’s disease, and other neurological disorders requiring advanced diagnostic tools. MEG enables precise localization of abnormal brain activity, making it indispensable in presurgical evaluation for epilepsy. It supports clinicians in identifying treatment pathways and improving patient outcomes. Hospitals and specialized neurology centers adopt it to meet the growing demand for accurate brain mapping solutions. The rising burden of neurological diseases globally continues to strengthen the adoption of MEG technology. This driver highlights the role of MEG as a vital clinical tool in modern healthcare systems.
- For instance, the Norman Fixel Institute at the University of Florida Health logged over 100 clinical MEG cases within its first year of operations, underlining strong clinical adoption and the value clinicians place on MEG in improving patient outcomes
Advancements in Non-Invasive Neuroimaging Technologies
The Magnetoencephalography Market benefits from advancements in non-invasive imaging methods that provide high temporal and spatial resolution. MEG offers real-time monitoring of brain activity without exposure to radiation, making it safer compared to other imaging modalities. It allows researchers to explore complex brain functions such as memory, language, and sensory processing. Development of advanced sensors and superconducting technologies enhances system sensitivity and reliability. The growing demand for patient-friendly and non-invasive diagnostics fuels investments in MEG systems. This technological progress reinforces its relevance in both clinical and research environments.
- For instance, Cerca Magnetics and the University of Nottingham installed a new OPM-MEG system in June 2025, enabling high-resolution recordings from more than 50 optically pumped magnetometers in a wearable format.
Expanding Applications in Neuroscience Research and Cognitive Studies
The Magnetoencephalography Market gains momentum from its expanding role in neuroscience research and cognitive studies. Universities and research institutions rely on MEG to analyze brain connectivity, developmental disorders, and psychiatric conditions. It supports projects focused on brain-computer interfaces and neural activity modeling. Researchers value its ability to capture millisecond-level neural responses that are critical for studying cognition and perception. Collaborative initiatives between healthcare providers and academic centers accelerate the adoption of MEG for advanced research. This driver emphasizes MEG’s importance in pushing the boundaries of neuroscience discovery.
Government Support and Growing Healthcare Infrastructure
The Magnetoencephalography Market benefits from government funding and investments in advanced healthcare infrastructure. Public and private initiatives provide financial assistance to medical facilities for acquiring high-cost MEG systems. National healthcare programs promote research and clinical usage of MEG for neurological care. It also aligns with policies supporting early detection and treatment of brain disorders. Emerging economies expand their healthcare budgets, creating opportunities for MEG adoption in developing regions. This support framework ensures stronger accessibility and wider clinical utilization of MEG systems worldwide.
Market Trends
Adoption of MEG in Personalized Medicine and Precision Diagnostics
The Magnetoencephalography Market reflects a growing trend toward personalized medicine, where advanced imaging tools provide patient-specific insights. MEG systems deliver precise brain activity data that help tailor surgical and therapeutic decisions. It supports individualized treatment planning in epilepsy, psychiatric disorders, and neurodegenerative diseases. Hospitals and research institutes increasingly integrate MEG with genetic and molecular studies to develop precision diagnostics. This convergence strengthens the clinical value of MEG in improving healthcare outcomes. Personalized medicine continues to elevate MEG’s role in advanced neurodiagnostics.
- For instance, MEGIN's TRIUX neo is a leading fourth-generation magnetoencephalography (MEG) system used in hospitals and research centers worldwide, including installations at institutions like the University of Nebraska Medical Center (UNMC) and the University of Cambridge's MRC Cognition and Brain Sciences Unit
Integration with Artificial Intelligence and Machine Learning
The Magnetoencephalography Market evolves with the integration of artificial intelligence and machine learning tools. AI-driven algorithms enhance the accuracy of brain activity interpretation and reduce diagnostic errors. It allows clinicians to process complex MEG datasets more efficiently, accelerating clinical decision-making. Research centers use AI models to study connectivity patterns in neurological and psychiatric disorders. The combination of MEG and AI improves predictive analysis in early disease detection. This trend enhances MEG’s utility in both clinical and research domains.
- For instance, researchers at the University of Nottingham, working with Cerca Magnetics, developed an AI-supported OPM-MEG system capable of processing real-time brain data from over 50 sensors, achieving classification accuracy above 90% in epilepsy case studies, showcasing the power of AI integration in MEG analysis.
Development of Portable and Wearable MEG Systems
The Magnetoencephalography Market shows progress with the development of portable and wearable MEG devices. Traditional MEG systems require large, shielded rooms and high operational costs, limiting accessibility. It is now being adapted into compact models using optically pumped magnetometers and advanced sensors. These systems enable broader use in outpatient settings and research studies outside traditional labs. Universities and hospitals invest in wearable MEG devices for child-friendly and mobility-focused applications. This innovation expands MEG’s reach to new clinical and research environments.
Increasing Collaborations Between Academic and Clinical Institutions
The Magnetoencephalography Market advances with growing collaborations between academic institutions, research centers, and hospitals. Partnerships accelerate the validation of MEG applications in epilepsy surgery, cognitive neuroscience, and psychiatric research. It allows sharing of data, technical expertise, and clinical outcomes that enhance system development. Governments and funding agencies support joint initiatives to promote MEG adoption in healthcare and research. These collaborations help bridge the gap between laboratory discoveries and clinical practice. The trend strengthens MEG’s role as a bridge between science and patient care.
Market Challenges Analysis
High Equipment Costs and Limited Accessibility
The Magnetoencephalography Market faces significant challenges due to the high cost of MEG systems and the infrastructure required for installation. These devices demand specialized shielded rooms and advanced superconducting sensors, which increase overall expenses for hospitals and research centers. It restricts adoption mainly to large academic and specialized medical institutions with sufficient budgets. Smaller healthcare facilities struggle to justify the financial burden of acquiring and maintaining such systems. Limited reimbursement frameworks for MEG procedures further reduce affordability for patients. This challenge continues to slow widespread adoption in both developed and emerging markets.
Shortage of Skilled Professionals and Technical Complexity
The Magnetoencephalography Market also encounters barriers due to the shortage of skilled professionals capable of operating and interpreting MEG data. It requires advanced training in neuroimaging, signal processing, and clinical neurology to ensure accurate analysis. Many regions lack academic programs or training facilities to develop such expertise. The technical complexity of system calibration and maintenance further adds to operational hurdles. Hospitals may hesitate to invest in MEG when faced with limited human resources to support its usage. This shortage of expertise creates a gap between technological advancement and effective clinical application.
Market Opportunities
Expansion in Clinical Applications and Early Diagnosis
The Magnetoencephalography Market holds strong opportunities through its expanding role in clinical applications beyond epilepsy. MEG provides early insights into neurodegenerative conditions such as Alzheimer’s and Parkinson’s disease, where early detection can significantly improve treatment strategies. It also supports psychiatric research by mapping neural activity linked to depression, autism, and schizophrenia. Hospitals and specialized centers can integrate MEG to improve diagnostic accuracy and tailor therapies to patient-specific needs. Growing demand for precision medicine creates favorable conditions for wider use. This opportunity positions MEG as an essential tool in modern neurological care.
Technological Innovation and Emerging Market Adoption
The Magnetoencephalography Market benefits from opportunities linked to technological advancements and adoption in emerging regions. Compact, wearable MEG systems powered by optically pumped magnetometers are lowering infrastructure requirements and opening pathways for broader accessibility. It creates new possibilities for outpatient and child-focused applications that were difficult with conventional large-scale devices. Emerging economies investing in healthcare modernization present untapped markets for MEG system suppliers. Partnerships between global manufacturers and regional institutions can accelerate penetration in Asia-Pacific, Latin America, and the Middle East. These developments establish strong opportunities for MEG to expand its footprint in both research and clinical environments.
Market Segmentation Analysis:
By Product Type
The Magnetoencephalography Market divides into systems, software, and services. Systems account for the largest share, as they form the core of clinical and research applications, offering real-time brain activity mapping. High costs and technical complexity make them most accessible to large hospitals, research centers, and academic institutions. It also includes superconducting quantum interference device (SQUID)-based systems and emerging optically pumped magnetometer (OPM)-based devices that reduce infrastructure needs. Software contributes significantly by enabling advanced data processing, visualization, and integration with artificial intelligence platforms. Services, including installation, maintenance, and training, continue to grow as users demand expert support for operational efficiency and accuracy.
- For instance, Compumedics’ Orion LifeSpan system, accepted at Tianjin Normal University, supports both adult and pediatric helmets and integrates with CURRY software, allowing dual-optimized recordings from more than 300 channels.
By Application
The Magnetoencephalography Market demonstrates strong demand in epilepsy diagnosis and presurgical planning, where MEG plays a critical role in localizing abnormal neural activity. It is also widely applied in brain mapping for tumor resections, functional connectivity studies, and cognitive neuroscience research. Psychiatric applications are gaining momentum, as MEG helps investigate complex conditions such as depression, autism spectrum disorder, and schizophrenia. Research into brain-computer interfaces and neurodegenerative diseases further broadens its scope. Increasing integration with multimodal imaging, such as MRI and PET, enhances MEG’s precision and clinical value. These expanding applications highlight MEG’s versatility across healthcare and academic domains.
- For instance, the University of Nottingham’s OPM-MEG, developed with Cerca Magnetics, has been used in more than 20 autism-related studies, capturing data from over 150 children in naturalistic environments.
By End Use
The Magnetoencephalography Market serves hospitals, diagnostic centers, research institutes, and academic facilities. Hospitals represent the largest end-use segment, where MEG assists in complex neurological diagnostics and surgical planning. Diagnostic centers adopt MEG for specialized services, particularly in regions with rising epilepsy and neurodegenerative disease cases. Research institutes focus on expanding neuroscience knowledge, using MEG for cognitive studies and brain connectivity projects. Academic facilities integrate MEG into education and advanced research programs, often through collaborations with clinical centers. It continues to gain traction in specialized neurological clinics as healthcare systems prioritize non-invasive and high-precision technologies. This wide end-user base ensures consistent demand and positions MEG as an indispensable tool in both clinical and scientific environments.
Segments:
Based on Product Type
- Cryogenic systems/conventional
- OPM systems
Based on Application
- Clinical
- Epilepsy
- Autism
- Dementia
- Stroke
- Traumatic brain injury (TBI)
- Other clinical applications
- Research
Based on End Use
- Hospitals
- Imaging centres
- Academic and research institutes
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds around 38% of the global Magnetoencephalography Market, driven by strong adoption of advanced neuroimaging technologies and high prevalence of neurological disorders. The United States leads the region with significant investment in clinical applications of MEG, particularly in epilepsy surgery planning and functional brain mapping. It benefits from established healthcare infrastructure, skilled professionals, and favorable reimbursement systems that encourage adoption in hospitals and specialized centers. Canada also contributes, with universities and research facilities integrating MEG for neuroscience projects and clinical research. Increasing government and private funding in brain health research strengthens North America’s dominance. The concentration of major manufacturers and partnerships with academic institutions further reinforce the region’s leadership in the MEG market.
Europe
Europe accounts for approximately 30% of the global Magnetoencephalography Market, supported by strong research activity and widespread clinical use of MEG. Germany, the United Kingdom, and France lead adoption, with hospitals and research centers utilizing MEG in epilepsy treatment and neuroscience studies. It benefits from government-backed funding for brain research and cross-border collaborations under European Union programs. Academic institutions and clinical networks establish partnerships to integrate MEG into multimodal imaging studies with MRI and PET. Demand is reinforced by Europe’s focus on precision medicine and early diagnosis of neurodegenerative conditions. Strong emphasis on non-invasive technologies and advanced medical infrastructure ensures continued growth for MEG across the region.
Asia-Pacific
Asia-Pacific represents about 22% of the global Magnetoencephalography Market, with rapid growth supported by expanding healthcare infrastructure and government investment in medical technologies. Japan leads adoption with advanced research institutes and hospitals utilizing MEG for clinical and neuroscience studies. China follows with growing installations in top hospitals, supported by rising demand for epilepsy diagnostics and neurodevelopmental research. India shows potential with its increasing investment in neurology and academic collaborations. South Korea and Australia also contribute, focusing on cognitive studies and precision healthcare. It benefits from the rising prevalence of neurological disorders and government-backed initiatives to promote early detection. Asia-Pacific is expected to expand rapidly as local healthcare systems adopt advanced imaging solutions.
Latin America
Latin America holds around 6% of the global Magnetoencephalography Market, with gradual adoption in Brazil, Mexico, and Argentina. Hospitals and universities in these countries integrate MEG for specialized epilepsy diagnostics and neuroscience research. It gains momentum from increasing healthcare investments and partnerships with global manufacturers to expand access to advanced technologies. Despite challenges such as high equipment costs and limited skilled professionals, growing awareness of non-invasive brain mapping strengthens demand. Latin American governments are prioritizing healthcare modernization, creating opportunities for future MEG adoption. The region remains an emerging market with significant long-term potential for growth.
Middle East and Africa
The Middle East and Africa account for about 4% of the global Magnetoencephalography Market, reflecting gradual adoption with strong potential for expansion. The United Arab Emirates and Saudi Arabia lead in MEG adoption, supported by investments in healthcare infrastructure and neurological research. South Africa contributes with advanced medical facilities and research programs targeting brain disorders. It benefits from increasing government support for advanced diagnostic solutions and collaboration with global institutions. Limited access to skilled professionals and high costs remain barriers, but growing focus on neurological health opens opportunities. The region is expected to gain traction as more countries invest in modern healthcare systems and brain health initiatives.
Key Player Analysis
- Ricoh USA
- MEGIN
- FieldLine
- Compumedics
- CTF MEF
- Cerca Magnetics
- Elekta
- Yokogawa Electric Corporation
- Croton Healthcare
- Tristan Technologies
Competitive Analysis
The competitive landscape of the Magnetoencephalography Market is shaped by a small group of specialized companies focusing on innovation, technological advancement, and strategic collaborations. Leading players include Ricoh USA, MEGIN, Compumedics, Cerca Magnetics, CTF MEF, FieldLine, Elekta, Yokogawa Electric Corporation, Croton Healthcare, and Tristan Technologies. These companies compete by offering high-resolution MEG systems designed for clinical and research applications, with emphasis on epilepsy diagnostics, cognitive neuroscience, and psychiatric studies. Ricoh USA leverages its expertise in advanced imaging to expand MEG’s role in hospitals, while MEGIN continues to pioneer SQUID-based technologies widely used in neurology centers. Compumedics strengthens its position with integration of multimodal imaging platforms and global distribution networks, and Cerca Magnetics focuses on developing portable, wearable MEG systems using optically pumped magnetometers to increase accessibility. FieldLine and Tristan Technologies invest in compact sensor technologies, while Elekta and Yokogawa support long-term research collaborations across universities and clinical institutes. Companies adopt strategies such as partnerships with healthcare institutions, investments in AI-driven software for data interpretation, and regional expansion into Asia-Pacific and emerging economies. Innovation in sensor design, service offerings, and sustainable system deployment ensures these players remain competitive, reinforcing MEG’s role in advancing precision diagnostics and brain research.
Recent Developments
- In June 2025, CTF MEG enabled real-time magnetoencephalography (MEG) analysis for brain–computer interface applications, leveraging its 151- and 275-channel systems in live data streaming scenarios.
- In May 2025, Compumedics achieved a world-first by delivering both adult- and child-optimized MEG recordings from a single system, the Orion LifeSpan MEG, installed at Tianjin Normal University. It features dual-helmet capability integrated with CURRY analytics software.
- In November 2024, Compumedics secured acceptance of its Orion LifeSpan MEG system at Tianjin Normal University, marking the final stage of its largest contract to date.
- In October 2024, MEGIN celebrated installation milestones and launched its new MEG Maps™ platform, with the TRIUX neo scanner completing its 100th MEG scan at the University of Florida Health’s Fixel Institute.
Market Concentration & Characteristics
The Magnetoencephalography Market demonstrates a moderately concentrated structure with a limited number of specialized companies leading global supply. Key players such as MEGIN, Compumedics, Cerca Magnetics, Ricoh USA, and CTF MEG hold significant positions by offering advanced systems tailored for both clinical and research needs. It reflects characteristics of a niche market where demand is driven primarily by neurological applications, epilepsy surgery planning, and cognitive neuroscience studies. The market is defined by high technological barriers, with systems requiring superconducting sensors, optically pumped magnetometers, and specialized shielding facilities. It also shows reliance on collaborations between hospitals, universities, and research institutes to expand usage and validate clinical outcomes. Smaller companies compete by focusing on sensor miniaturization and portable MEG solutions that lower infrastructure requirements and increase accessibility. The Magnetoencephalography Market continues to be shaped by technological innovation, regulatory compliance, and the growing importance of precision neuroimaging in both advanced healthcare and neuroscience research.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Development of compact, wearable MEG systems using optically pumped magnetometers will broaden clinical and research access.
- Integration with artificial intelligence and machine learning will accelerate data interpretation and improve diagnostic accuracy.
- Greater adoption in personalized medicine and early detection of neurodegenerative conditions will elevate MEG’s clinical relevance.
- Expansion into psychiatric and cognitive neuroscience, including studies on autism and schizophrenia, will deepen MEG utilization.
- Collaboration between neurological centers, research institutions, and healthcare providers will continue to advance validation and clinical integration.
- Ongoing improvements in sensor density and noise reduction will enhance spatial resolution and capture of complex brain signals.
- Integration with other neuroimaging modalities, such as MRI and PET, will strengthen multimodal brain mapping capabilities.
- Use of MEG for neurofeedback training and brain–computer interface research will open therapeutic and interactive technology pathways.
- Rising funding for neuroscience research and infrastructure in developing regions will gradually expand global access to MEG systems.
- Growth in data-driven biomarker development using combined MEG and MRI pipelines will improve early diagnosis in Alzheimer’s and cognitive disorders.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Neurological Disorders and Epilepsy Cases
Increasing cases of epilepsy, Alzheimer’s, and other neurological disorders are driving demand for advanced diagnostic tools like MEG, which enables precise localization of abnormal brain activity and supports presurgical evaluation and improved patient outcomes.
Advancements in Non-Invasive Neuroimaging Technologies
Technological progress in non-invasive imaging, such as the development of high-sensitivity sensors and optically pumped magnetometers, is making MEG safer and more effective, enhancing its adoption for real-time brain monitoring without radiation exposure.
Expanding Applications in Neuroscience Research and Cognitive Studies
MEG’s ability to capture millisecond-level neural responses is fueling its use in cognitive neuroscience, psychiatric research, and brain-computer interface projects, broadening its relevance beyond traditional clinical diagnostics.
Government Support and Growing Healthcare Infrastructure
Government funding and investments in healthcare modernization, especially in emerging economies, are enabling more hospitals and research centers to acquire MEG systems, increasing accessibility and clinical utilization worldwide.
Integration with Artificial Intelligence and Machine Learning
The adoption of AI and machine learning in MEG data analysis is improving diagnostic accuracy, enabling faster and more precise interpretation of complex brain activity, and supporting early detection of neurological conditions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Magnetoencephalography, and what is its projected size in 2032?
Which Magnetoencephalography market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Magnetoencephalography market?
Who are the leading companies in the Magnetoencephalography market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Hospitals
- 1.2.2 Imaging centres
- 1.2.3 Academic and research institutes
- 1.3 By Application
- 1.3.1 Epilepsy
- 1.3.2 Autism
- 1.3.3 Dementia
- 1.3.4 Stroke
- 1.3.5 Traumatic brain injury (TBI)
- 1.3.6 Other clinical applications
- 1.3.7 Research
- 1.4 By Product Type
- 1.4.1 Cryogenic systems/conventional
- 1.4.2 OPM systems
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 233.6 million → 2032: USD 332.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Magnetoencephalography Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Magnetoencephalography Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Magnetoencephalography Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Magnetoencephalography Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Magnetoencephalography Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Magnetoencephalography Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Magnetoencephalography Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Magnetoencephalography Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 233.6 million → 2032: USD 332.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Magnetoencephalography Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Imaging centres
- 12.3.7.3 Academic and research institutes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Epilepsy
- 12.4.7.2 Autism
- 12.4.7.3 Dementia
- 12.4.7.4 Stroke
- 12.4.7.5 Traumatic brain injury (TBI)
- 12.4.7.6 Other clinical applications
- 12.4.7.7 Research
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cryogenic systems/conventional
- 12.5.7.2 OPM systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Magnetoencephalography End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Magnetoencephalography Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Magnetoencephalography Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Magnetoencephalography Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Ricoh USA
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 MEGIN
- 18.4 Compumedics
- 18.5 Cerca Magnetics
- 18.6 CTF MEG
- 18.7 FieldLine
- 18.8 Elekta
- 18.9 Yokogawa Electric Corporation
- 18.10 Croton Healthcare
- 18.11 Tristan Technologies
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

