
Photographic Services Market Overview:
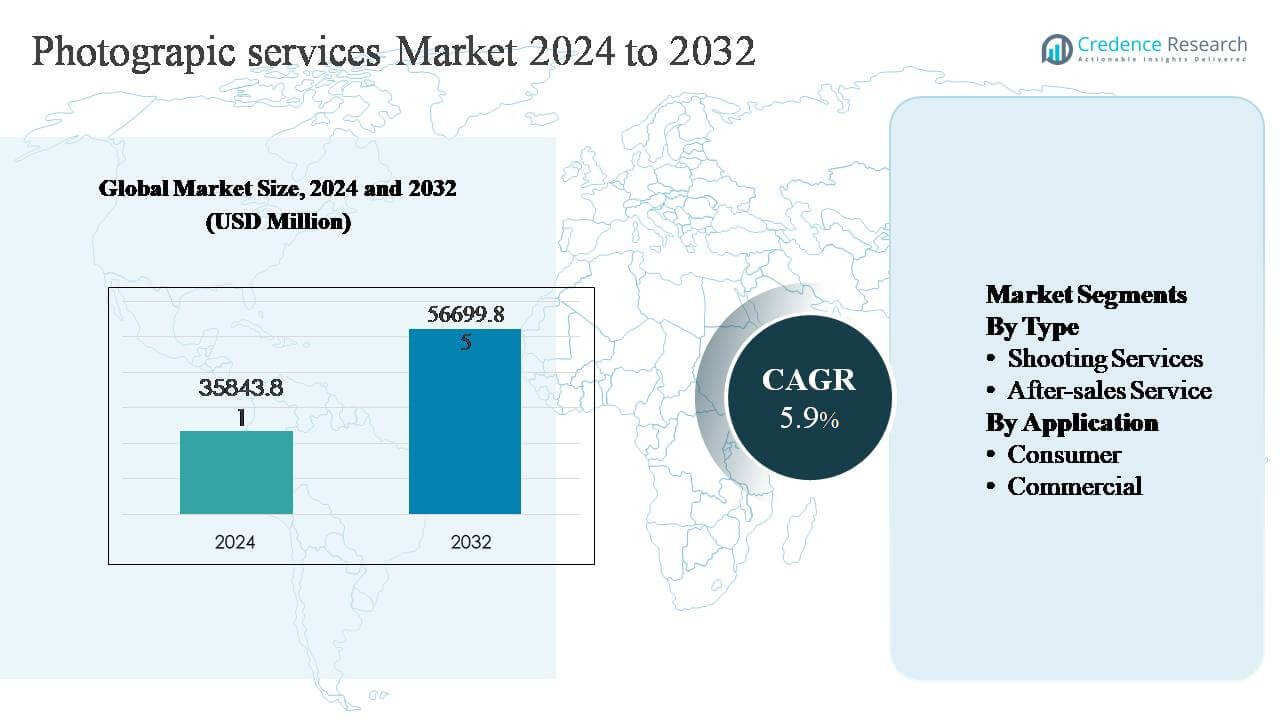
The global photographic services market was valued at USD 35,843.81 million in 2024 and is projected to reach USD 56,699.85 million by 2032, expanding at a CAGR of 5.9% during the forecast period (2025-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Photographic Services Market Size 2024 | USD 35,843.81 million |
| Photographic Services Market, CAGR | 5.9% |
| Photographic Services Market Size 2032 | USD 56,699.85 million |
Photographic Services Market Insights
- The photographic services market was valued at USD 35,843.81 million in 2024 and is projected to reach USD 56,699.85 million by 2032, expanding at a CAGR of 5.9% during the forecast period.
- Market growth is driven by rising demand for professional visual content across digital marketing, social media, e-commerce, and personal events, with shooting services dominating the type segment due to their direct revenue contribution from weddings, events, advertising, and product photography.
- Key trends include increasing personalization of photography services, adoption of advanced editing and digital delivery tools, and growing demand for lifestyle and brand-centric visuals, while the consumer application segment holds the largest share supported by recurring personal and social photography needs.
- The competitive landscape is moderately fragmented, with franchise-based operators, specialized studios, and freelancers competing on service quality, customization, pricing, and digital turnaround, creating sustained pricing pressure across mature markets.
- Regionally, North America leads with ~34% market share, followed by Asia-Pacific (~30%), Europe (~27%), Latin America (~5%), and Middle East & Africa (~4%), reflecting differences in digital adoption, consumer spending, and commercial branding intensity.
Photographic Services Market Segmentation Analysis:
By Type:
By type, Shooting Services represent the dominant sub-segment in the photographic services market, accounting for the majority market share due to their central role in value creation. This segment benefits from sustained demand across events, portraits, weddings, advertising campaigns, fashion shoots, and digital content production for social media and e-commerce platforms. Growth is driven by rising consumer preference for professional-quality visuals, increased brand spending on visual marketing, and the proliferation of influencer- and content-driven digital ecosystems. While After-sales Service including photo editing, retouching, restoration, and archiving continues to expand, it remains complementary, supporting repeat business and long-term client engagement rather than primary revenue generation.
- For instance, Getty Images operates a global network of contracted photographers and videographers whose on-ground shooting activities have contributed to a licensed content library exceeding 500 million still images and video assets, reflecting the scale and operational depth of professional shooting services required to continuously refresh commercial visual inventories.
By Application:
By application, the Consumer segment holds the dominant market share, supported by consistent demand for personal photography services such as weddings, family portraits, lifestyle shoots, and social media content creation. Rising disposable incomes, urbanization, and the cultural emphasis on visual storytelling across personal milestones are key growth drivers. The Commercial segment, encompassing advertising, corporate branding, real estate, media, and product photography, is growing steadily as businesses prioritize high-impact visual assets to strengthen digital presence and brand differentiation. However, the broader and recurring nature of consumer demand continues to position the consumer segment as the leading revenue contributor.
- For instance, "Airbnb’s professional photography program, which utilizes a global network of freelance photographers, has provided professional imagery for thousands of listings worldwide.
Key Growth Drivers
Expansion of Digital Content Consumption
The rapid expansion of digital platforms is a primary growth driver for the photographic services market. Businesses and individuals increasingly rely on high-quality visual content to enhance online engagement across websites, social media, e-commerce platforms, and digital advertising channels. Brands are allocating higher budgets to professional photography to improve conversion rates, brand recall, and storytelling effectiveness. The growth of influencer marketing, short-form video platforms, and visual-first social networks further amplifies demand for professional shooting services. Additionally, small and medium enterprises are adopting professional photography to compete in crowded digital marketplaces, reinforcing steady demand across both consumer and commercial applications.
- For instance, Instagram reported that over 200 million business accounts actively use its platform, with professional-grade imagery and creator collaborations forming the backbone of branded content strategies, directly supporting recurring demand for commercial and lifestyle photography services.
Rising Demand for Event and Lifestyle Photography
The sustained popularity of personal and corporate events continues to drive the photographic services market. Weddings, anniversaries, cultural celebrations, corporate events, exhibitions, and conferences require professional photography to document experiences and create lasting visual assets. Urbanization, rising disposable incomes, and evolving lifestyle aspirations support higher spending on premium photography packages. Consumers increasingly prefer customized, themed, and experience-driven photography services, encouraging service providers to expand creative offerings. Corporate clients also rely on professional photographers for internal branding, employer branding, and event documentation, strengthening recurring demand across multiple industry verticals.
- For instance, WedMeGood, a leading wedding services platform in India, lists over 80,000 active vendors, including approximately 7,000+ verified wedding photographers. The platform supports discovery for a significant portion of India's multi-million annual wedding market serving over 2 million couples to date with typical multi-day wedding photography packages delivering between 800 to 1,200 edited images.
Growth of E-commerce and Visual Branding
The expansion of global e-commerce is a significant catalyst for photographic services. Online retailers depend on high-resolution product images, lifestyle visuals, and creative shoots to influence purchasing decisions and reduce product return rates. Professional photography enhances product presentation, builds consumer trust, and supports omnichannel retail strategies. As brands expand digital storefronts and adopt direct-to-consumer models, the need for consistent visual standards increases. This trend drives demand for specialized shooting services, including product, fashion, food, and real estate photography, reinforcing the market’s long-term growth trajectory.
Key Trends & Opportunities
Integration of Advanced Imaging and Editing Technologies
Technological advancements present strong growth opportunities for photographic service providers. The integration of AI-powered editing, automated retouching, cloud-based workflows, and advanced post-production tools improves efficiency and turnaround times. These technologies enable photographers to scale operations, deliver consistent quality, and offer value-added services such as rapid edits and customized outputs. Virtual shoots, remote collaboration, and digital asset management platforms further expand service capabilities. Providers adopting advanced tools can differentiate offerings, attract commercial clients, and improve profitability through streamlined operations.
- For instance, Adobe’s Firefly generative AI is integrated across Photoshop and Lightroom workflows, supporting batch edits on thousands of images in a single project and enabling features such as content-aware fill and automated masking that significantly reduce manual retouching time for professional studios.
Rising Demand for Personalized and Niche Photography Services
Personalization is emerging as a key trend in the photographic services market. Consumers increasingly seek tailored photography experiences aligned with personal branding, lifestyle preferences, and social media aesthetics. Niche segments such as maternity, pet, travel, fitness, and creator-focused photography are gaining traction. On the commercial side, demand is growing for industry-specific visuals tailored to hospitality, healthcare, real estate, and education sectors. This trend creates opportunities for specialized service providers to command premium pricing and build strong client loyalty through differentiated offerings.
- For instance, Shoott, a U.S.-based on-demand photography platform, operates with a curated network of professional photographers accepting only the top 2–5% of applicants across more than 60 cities (covering over 600 locations). The platform supports 30-minute mini-sessions that typically deliver 40+ lightly edited images per client gallery.
Key Challenges
Intense Competition and Pricing Pressure
The photographic services market faces significant competitive pressure due to low entry barriers and a growing number of freelance photographers and small studios. The availability of affordable high-quality cameras and editing software enables new entrants, intensifying price competition. This environment limits pricing power, particularly in consumer segments, and compresses profit margins. Clients increasingly compare services based on cost rather than expertise, making differentiation challenging. Established players must continuously invest in branding, service quality, and client relationships to maintain market position.
Rapid Technological Change and Skill Requirements
Rapid advancements in imaging technology present an ongoing challenge for service providers. Continuous upgrades in camera equipment, editing software, and digital workflows require sustained capital investment. Additionally, photographers must regularly update technical and creative skills to meet evolving client expectations. Failure to adapt can result in service obsolescence and loss of competitiveness. Smaller providers may struggle to keep pace with technological change, affecting service consistency and scalability, particularly in commercial and high-volume project environments.
Regional Analysis
North America
North America leads the photographic services market with an estimated 34% share, supported by strong consumer spending, advanced digital marketing adoption, and a mature commercial photography ecosystem. High demand stems from weddings, lifestyle shoots, advertising, real estate, and e-commerce product imagery. Brands in retail, media, and entertainment prioritize professional visuals to enhance digital engagement and conversion performance. The region’s well-established network of studios and freelancers, premium pricing structures, and early adoption of advanced imaging and post-production technologies further reinforce market leadership and sustain consistent service demand across consumer and commercial applications.
Europe
Europe accounts for approximately 27% of the global photographic services market, driven by a strong creative culture and sustained demand across weddings, tourism, fashion, architecture, and corporate branding. Western European countries such as the UK, Germany, France, and Italy contribute significantly through advertising, media, and design-driven industries. The region benefits from high demand for artistic and documentary photography tied to cultural events and heritage tourism. Increasing digitalization among small businesses and expanding online retail platforms continue to strengthen demand for professional photography services across both consumer and commercial segments.
Asia-Pacific
Asia-Pacific holds nearly 30% market share and represents the fastest-growing region in photographic services. Growth is driven by rising disposable incomes, rapid urbanization, and expanding digital economies across China, India, Japan, and Southeast Asia. Strong demand arises from weddings, social media content creation, influencer marketing, and e-commerce product photography. A large population base and increasing aspiration for premium lifestyle services support high service volumes. Competitive pricing, expanding small business branding needs, and the rapid adoption of digital platforms position Asia-Pacific as a critical growth engine for the global market.
Latin America
Latin America represents around 5% of the photographic services market, with demand concentrated in Brazil, Mexico, Argentina, and Chile. Growth is supported by urbanization, rising social media usage, and increasing demand for professional event and lifestyle photography. Small and medium enterprises are gradually investing in professional visuals to enhance digital presence and brand differentiation. Weddings, cultural events, and local advertising remain key demand drivers. While pricing sensitivity and fragmented service structures persist, improving economic stability and expanding e-commerce activity are contributing to steady market development across the region.
Middle East & Africa
The Middle East & Africa region accounts for approximately 4% of the global photographic services market, supported by luxury events, tourism promotion, and commercial branding activities. In the Middle East, demand is driven by weddings, hospitality, real estate marketing, and large-scale corporate events, particularly in GCC countries. Africa’s growth is linked to urban expansion, media development, and increasing digital engagement among businesses. Although market maturity varies significantly across countries, rising investment in visual communication and branding continues to support gradual adoption of professional photography services.
Photographic Services Market Segmentations:
By Type
- Shooting Services
- After-sales Service
By Application
- Consumer
- Commercial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the photographic services market is moderately fragmented, with a diverse mix of specialized studios, franchise-based networks, and independent professionals competing across consumer and commercial segments. Established players differentiate through service specialization, geographic coverage, brand recognition, and the ability to deliver consistent quality at scale. Franchise operators leverage standardized processes and localized market presence, while boutique studios compete on creativity, personalization, and premium experiences. Commercial service providers focus on long-term contracts with corporate, media, retail, and real estate clients, emphasizing reliability and turnaround speed. Competition increasingly centers on digital capabilities, including advanced post-production, cloud-based delivery, and integrated content services. Pricing pressure remains high due to low entry barriers, prompting leading companies to invest in brand building, customer experience, and value-added services to sustain margins and client loyalty.
Key Player Analysis
- Carma Media Productions
- Cherry Hill Programs Inc.
- Bella Baby Photography
- DE Photo (Franchising) Ltd.
- BSTRO
Recent Developments
- In April 2025, the Newborn photography services launched at St. Peter's Hospital and Samaritan Hospital's Burdett Birth Center. New parents can enjoy a complimentary newborn photography service, thanks to Bella Baby Photography. The service captures those magical first hours of a newborn's life, offering parents a chance to preserve these precious moments.
- In April 2025, Bella Baby Photography, Japan Airlines announced the launch of SKYPIX, Japan's first unmanned aerial drone photography service with AI-powered automated video editing to create attractive sightseeing spots. It aims to create a sustainable tourist destination, bringing spectacular scenery within reach.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for professional photographic services will continue to rise as digital platforms prioritize high-quality visual content for engagement and conversion.
- Consumer photography, particularly weddings, lifestyle, and personal branding, will remain a primary revenue contributor due to recurring and experience-driven demand.
- Commercial photography will expand steadily as businesses increase investment in brand identity, product presentation, and digital marketing assets.
- Advanced editing tools, automation, and cloud-based workflows will improve service efficiency and reduce turnaround times.
- Personalization and niche-focused photography services will gain importance as clients seek differentiated visual storytelling.
- Integration of photography with video and multimedia content offerings will strengthen service portfolios and client retention.
- Franchise and network-based models will expand to improve geographic reach and service standardization.
- Competition will intensify, encouraging providers to focus on quality, branding, and customer experience rather than price alone.
- Emerging markets will contribute incremental growth as urbanization and digital adoption increase.
- Long-term growth will be supported by sustained reliance on visual communication across consumer and commercial applications.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Photographic services, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Photographic services market projected to grow between 2024 and 2032?
Which Photographic services segment held the largest share in 2024?
What are the primary factors fueling the growth of Photographic services?
Who are the leading companies in the Photographic services market?
Which region commanded the largest share of the Photographic services market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 35,843.81 million → 2032: USD 56,699.85 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Photographic Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Photographic Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Photographic Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Photographic Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Photographic Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Photographic Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Photographic Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Photographic Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 35,843.81 million → 2032: USD 56,699.85 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Photographic Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Photographic Services Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Photographic Services Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Photographic Services Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

