
Market Overview:
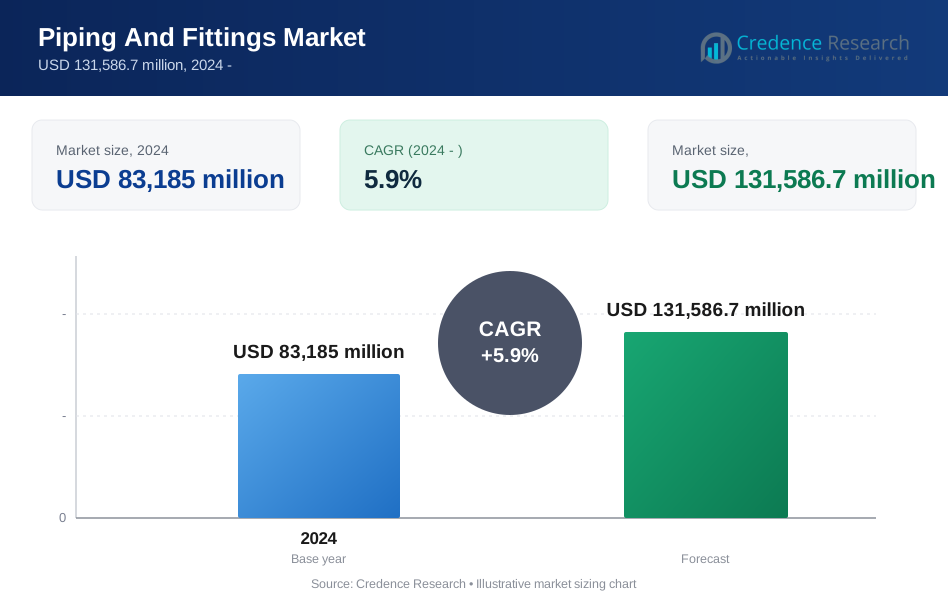
The Piping and fittings market is projected to grow from USD 83,185 million in 2024 to USD 131,586.7 million by 2032. This expansion reflects a compound annual growth rate of 5.9% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Piping And Fittings Market Size 2024 | USD 83,185 million |
| Piping And Fittings Market, CAGR | 5.9% |
| Piping And Fittings Market Size 2032 | USD 131,586.7 million |
Infrastructure investment drives steady demand across residential, commercial, and industrial projects. Urban expansion increases the need for reliable water supply and wastewater systems. Energy projects require durable piping for oil, gas, and power transport. Industrial plants adopt advanced fittings to improve safety and flow control. Regulations push replacement of aging pipelines with corrosion-resistant materials. Manufacturing growth raises demand for customized piping solutions. Prefabrication improves installation speed and reduces labor costs. Sustainability goals encourage recyclable and long-life materials. These factors sustain consistent market momentum.
Asia Pacific leads the market due to rapid urbanization and industrial expansion. China and India invest heavily in water, energy, and transport infrastructure. Southeast Asia emerges as a key growth zone from new construction activity. North America shows stable demand driven by pipeline replacement and shale energy projects. Europe focuses on renovation and strict environmental standards. The Middle East benefits from oil, gas, and desalination projects. Africa and Latin America emerge gradually, supported by infrastructure development and urban growth.

Market Insights:
- The market stood at USD 83,185 million in 2024 and is set to reach USD 131,586.7 million by 2032, expanding at a CAGR of 5.9%, driven by construction, energy, and water infrastructure demand.
- Asia Pacific leads with about 42% share due to rapid urbanization, China–India infrastructure spending, and large industrial bases, while North America holds nearly 25% from pipeline replacement and energy projects, and Europe accounts for around 22% supported by renovation activity and strict safety norms.
- The Middle East & Africa is the fastest-growing region with close to 5% share, supported by oil and gas projects, desalination plants, and government-led infrastructure programs.
- By type, steel pipes hold the largest share at roughly 45% due to high strength needs in energy and industrial uses, followed by plastic/PVC pipes at about 35% from residential and water applications.
- By end use, industrial applications account for nearly 40% share, while residential and commercial together represent around 60%, supported by housing growth and commercial construction.
Market Drivers:
Expansion Of Urban Infrastructure And Utility Networks Across Developing Regions
The Piping and fittings market benefits from steady urban infrastructure expansion across developing economies. Governments invest in water supply, sewage, and drainage systems. Smart city programs raise demand for durable piping networks. Housing projects require standardized fittings for fast deployment. Public infrastructure budgets support long-term procurement cycles. Industrial corridors depend on reliable fluid transport systems. Pipeline replacement programs address leak risks and safety gaps. These factors sustain consistent volume demand across regions.
- For instance, Saint-Gobain supplied ductile iron pipelines for large municipal water projects, with its PAM brand supporting networks exceeding 200,000 km globally, reducing leakage and improving pressure reliability.
Rising Industrial Output And Process Automation Requirements
Industrial growth supports demand for high-performance piping solutions. Manufacturing plants require controlled fluid transfer for safety and efficiency. Chemical and petrochemical facilities rely on corrosion-resistant fittings. Food and beverage plants demand hygienic piping standards. Power generation facilities require pressure-rated piping systems. Automated plants prefer precision-engineered fittings for reliability. Industrial safety norms reinforce quality compliance. This environment supports steady equipment upgrades.
- For instance, Georg Fischer reports that its corrosion-resistant plastic piping systems operate safely in chemical plants at temperatures up to 120°C and pressures above 16 bar, supporting automated process lines worldwide.
Growth Of Energy And Resource Development Projects Worldwide
Energy sector expansion supports large-scale pipeline deployment. Oil and gas projects require extensive transmission networks. Refining and processing units depend on specialized fittings. Thermal and nuclear plants use high-grade piping systems. Renewable energy projects need fluid handling infrastructure. Offshore projects demand materials with high stress tolerance. Energy security policies drive investment momentum. These projects strengthen long-term market demand.
Regulatory Focus On Safety And System Reliability Standards
Regulators enforce strict pipeline safety standards across industries. Compliance requirements drive replacement of outdated systems. Municipal authorities mandate leak-proof distribution networks. Fire protection systems require certified piping solutions. Building codes specify approved materials and fittings. Inspection regimes increase lifecycle management needs. Operators adopt higher-grade components to reduce risk. Regulatory pressure sustains structured demand growth.
Market Trends:
Shift Toward Advanced Materials With Extended Service Life
Manufacturers adopt composite and alloy-based piping solutions. End users prefer materials with longer operational life. Corrosion resistance gains priority across harsh environments. Lightweight materials simplify transport and installation. Thermal stability improves system reliability. Cost predictability supports lifecycle planning. The Piping and fittings market aligns with material innovation strategies. This shift reshapes product portfolios.
- For instance, Aliaxis Group develops multilayer plastic pipe systems designed for service lifetimes beyond 50 years, widely used in potable water and gas distribution networks across Europe and Asia.
Increasing Adoption Of Prefabricated And Modular Piping Systems
Construction firms prefer prefabricated piping assemblies. Modular systems reduce onsite installation time. Labor efficiency improves project execution speed. Quality control improves under factory conditions. Large projects favor standardized modules. Waste reduction supports sustainability goals. Project timelines benefit from predictable installation cycles. This trend gains acceptance across sectors.
- For instance, JM Eagle manufactures large-diameter prefabricated PVC and HDPE pipe systems, with production facilities capable of supplying pipes exceeding 60 inches in diameter for rapid municipal installation projects.
Digital Design And Simulation Integration In Pipeline Planning
Engineers use digital tools for pipeline layout planning. Simulation improves flow efficiency and pressure control. Error reduction supports cost management. Digital twins enable predictive maintenance planning. Project owners gain better asset visibility. Design optimization reduces material waste. Smart planning improves long-term performance. Technology use shapes procurement decisions.
Rising Demand For Customized And Application-Specific Solutions
End users request tailored piping configurations. Industrial plants require application-specific fittings. Customization supports complex layouts and constraints. Manufacturers invest in flexible production systems. Shorter lead times improve client satisfaction. Specialized designs enhance operational efficiency. Niche applications gain supplier focus. Custom solutions strengthen supplier differentiation.
Market Challenges Analysis:
Volatility In Raw Material Prices And Supply Chain Constraints
Raw material price swings affect production costs. Metal and polymer inputs face global supply risks. Manufacturers manage margin pressure during price instability. Procurement planning becomes more complex. Logistics disruptions delay project timelines. Inventory management requires careful balance. Smaller suppliers face cost absorption limits. These factors challenge pricing stability.
Complex Installation Requirements And Skilled Labor Dependence
Advanced piping systems require skilled installation teams. Labor shortages affect project execution speed. Training costs add operational burden. Improper installation risks system failure. Quality assurance demands strict supervision. Remote projects face workforce access limits. Contractors manage higher coordination complexity. These issues impact deployment efficiency.
Market Opportunities:
Infrastructure Modernization And Aging Pipeline Replacement Programs
Governments plan large-scale pipeline replacement initiatives. Aging water networks require urgent upgrades. Urban centers prioritize leak reduction programs. Industrial operators replace outdated systems for safety. Modern materials improve system lifespan. Funding support accelerates execution pace. The Piping and fittings market gains from renewal demand. Long-term contracts improve revenue visibility.
Expansion Across Emerging Economies And New Industrial Zones
Emerging economies invest in basic infrastructure. Industrial parks drive localized piping demand. Export-oriented manufacturing expands facility construction. Energy access programs require distribution networks. Urban migration fuels housing development. Policy support attracts private investment. Local manufacturing boosts regional supply chains. These markets present strong growth potential.
Market Segmentation Analysis:
By Type / Material
Steel pipes hold a strong position due to high strength and pressure tolerance. Energy, water transmission, and industrial facilities prefer steel for durability. Plastic and PVC pipes gain demand from low weight and corrosion resistance. Residential and irrigation systems favor these materials for easy installation. Aluminium pipes serve applications that require light structure and moderate strength. Transport and HVAC systems adopt aluminium for efficiency. Copper pipes maintain steady demand in plumbing and HVAC due to thermal performance. Glass and brass pipes support niche chemical and specialty uses. The Piping and fittings market reflects diverse material adoption based on performance needs.
- For instance, Mueller Industries produces millions of pounds of copper tubing annually, supporting plumbing and HVAC systems that operate efficiently at high thermal loads and strict safety standards.
By Application / End-Use
Residential applications drive demand for water supply and drainage systems. Housing growth increases usage of plastic and copper piping. Commercial buildings require reliable piping for plumbing and fire safety. Offices, malls, and hospitals prefer standardized and certified fittings. Industrial applications dominate volume consumption across oil, gas, chemicals, and power sectors. These facilities require high-pressure and corrosion-resistant systems. Steel and alloy pipes support complex industrial processes. End-use diversity ensures balanced demand across construction and industrial sectors.
- For instance, Georg Fischer supplies stainless steel and plastic piping to pharmaceutical and food plants, where hygienic systems meet international standards such as FDA and EHEDG for clean processing lines.
Segmentation:
By Type / Material- Steel Pipe
- Plastic / PVC Pipe
- Aluminium Pipe
- Copper Pipe
- Others (Glass Pipe, Brass)
- Residential
- Commercial
- Industrial
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia Pacific Dominates Through Infrastructure Expansion And Industrial Growth
Asia Pacific holds the largest share of the global market, accounting for nearly 42% of total demand. The Piping and fittings market in this region benefits from rapid urban development and industrial expansion. China leads due to large-scale water, energy, and construction projects. India follows with strong demand from housing, sanitation, and industrial corridors. Southeast Asian countries support growth through manufacturing investments. Public infrastructure spending sustains long-term consumption. Cost-effective production also strengthens regional supply capacity.
North America And Europe Maintain Strong Replacement And Compliance Demand
North America represents around 25% of the global share, driven by replacement of aging infrastructure. The Piping and fittings market in the region relies on municipal upgrades and energy projects. The United States leads with strong demand from oil, gas, and water utilities. Europe accounts for nearly 22% of global demand due to strict safety and environmental regulations. Germany, France, and the United Kingdom invest in renovation projects. Industrial modernization supports steady consumption. Quality standards influence material and product choices.
Latin America And Middle East & Africa Show Emerging Growth Potential
Latin America holds close to 6% of the global market share, supported by urban housing and energy projects. The Piping and fittings market in the region gains traction from Brazil and Mexico. Infrastructure gaps create replacement and expansion demand. The Middle East & Africa account for about 5% of global share. Oil, gas, and desalination projects drive consumption in GCC countries. Africa shows gradual growth through urban water projects. Government-led infrastructure plans support long-term expansion.
Key Player Analysis:
- Saint-Gobain
- Aliaxis Group
- Georg Fischer
- Mueller Industries
- JM Eagle
Competitive Analysis:
The Piping and fittings market features strong competition among global and regional manufacturers. Large players focus on product range depth and material quality. Scale advantages support pricing control and supply reliability. Companies invest in advanced manufacturing to improve consistency. Regional firms compete through localized distribution networks. Product certification supports access to regulated sectors. Strategic sourcing helps manage input cost pressure. Brand reputation influences contractor and utility preferences. The market shows moderate consolidation with active portfolio expansion.
Recent Developments:
- Georg Fischer successfully closed the acquisition of VAG-Group on October 1, 2025, finalizing a transaction announced on May 9, 2025. VAG-Group, headquartered in Mannheim, Germany, is a renowned manufacturer of water utility valve solutions with approximately 1,000 employees operating production and sales offices across 46 countries. The company generated annual sales of approximately €200 million (approximately CHF 190 million) and was owned by Aurelius Alpha Invest New GmbH, a private equity firm. The transaction value was approximately CHF 200 million. The acquisition strengthens Georg Fischer's Infrastructure Flow Solutions division by adding metal valve technologies that complement existing pipe and fittings portfolios, enabling comprehensive end-to-end solutions for aging water infrastructure renovation and new infrastructure development.
- Mueller Industries announced and completed the acquisition of Elkhart Products Corporation on August 2, 2024, with the formal announcement released on August 6, 2024. Elkhart Products, headquartered in Indiana with additional manufacturing in Fayetteville, Arkansas, is a U.S. manufacturer of copper solder fittings. Mueller acquired the business for approximately $38.2 million in cash (net of cash acquired and working capital adjustments). The acquisition directly supported Mueller's recovery strategy following the March 2023 tornado that substantially impacted its copper fittings manufacturing plant in Covington, Tennessee. Elkhart Products' complementary manufacturing capabilities and geographic footprint provided Mueller with redundant production capacity and accelerated the recovery of its copper fittings business segment.
- In June 2024, Saint-Gobain completed its acquisition of The Bailey Group of Companies, a leading Canadian manufacturer of metal building solutions for light construction. The transaction, announced on April 3, 2024, was valued at C$880 million (approximately €600 million) and closed on June 2, 2024. Bailey operates 12 manufacturing facilities across Canada with approximately 690 employees and generated C$532 million in revenues in 2023. This represented Saint-Gobain's third major acquisition in Canada within three years, following Kaycan (2022) and Building Products of Canada (2023), strengthening the company's position in sustainable light construction.
- Additionally, Saint-Gobain completed the acquisition of Fosroc, a leading global construction chemicals manufacturer, announced on June 27, 2024, with closure finalized on February 9, 2025. The transaction value was approximately $1.025 billion in cash, making it one of Saint-Gobain's most significant investments in construction chemicals. Fosroc, headquartered in Dubai with a legacy as a UK firm, generated approximately $487 million in annual sales with strong geographic presence in India, the Middle East, and Asia-Pacific regions. Following this acquisition and previous construction chemicals acquisitions including Chryso, GCP, and Cemix (formerly OVNIVER), Saint-Gobain's combined construction chemicals portfolio reached €6.5 billion in annual sales across 76 countries.
Report Coverage:
The research report offers an in-depth analysis based on material type, application, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Infrastructure upgrades will sustain long-term demand.
- Urban housing growth will support residential installations.
- Industrial expansion will raise high-pressure pipe usage.
- Material innovation will improve durability and lifecycle value.
- Prefabrication adoption will improve project efficiency.
- Sustainability focus will favor recyclable materials.
- Regional manufacturing will reduce logistics risks.
- Energy projects will drive large-diameter pipe demand.
- Digital design tools will influence procurement decisions.
- Strategic partnerships will shape competitive positioning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Piping and fittings market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Piping and fittings market projected to grow between 2025 and 2032?
Which Piping and fittings market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Piping and fittings market?
Who are the leading companies in the Piping and fittings market?
Which region commanded the largest share of the Piping and fittings market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 83,185 million → 2032: USD 131,586.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Piping And Fittings Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Piping And Fittings Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Piping And Fittings Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Piping And Fittings Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Piping And Fittings Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Piping And Fittings Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Piping And Fittings Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Piping And Fittings Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 83,185 million → 2032: USD 131,586.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Piping And Fittings Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Piping And Fittings Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Piping And Fittings Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Piping And Fittings Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

