
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
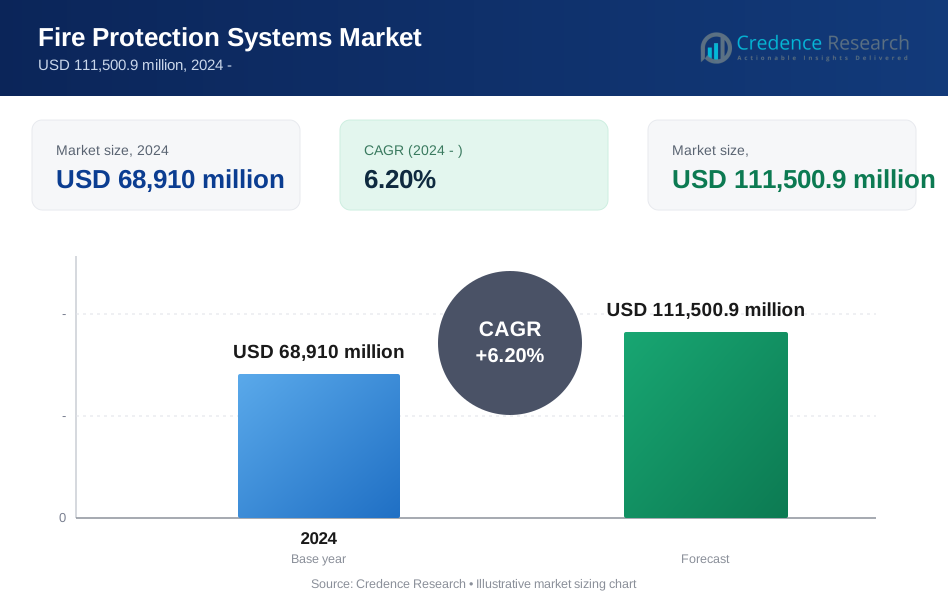
| fire protection systems market Size 2024 | USD 68,910 million |
| fire protection systems market, CAGR | 6.2% |
| fire protection systems market Size 2032 | USD 111,500.9 million |
Market Overview:
The global fire protection systems market is expected to grow from USD 68,910 million in 2024 to approximately USD 111,500.9 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.2%. Fire protection systems include detection, suppression, and containment solutions designed to prevent, monitor, and control fire outbreaks in commercial, industrial, and residential settings. Rising concerns for property and life safety and strict regulatory standards worldwide drive demand across construction, oil and gas, manufacturing, and other sectors where fire hazards are prevalent. Technological advancements, such as the integration of IoT and AI in detection systems, are also elevating market growth, as smart systems offer enhanced response accuracy and faster intervention.
Key market drivers include stringent fire safety regulations and building codes enforced by government bodies like the National Fire Protection Association (NFPA) and Occupational Safety and Health Administration (OSHA) in the United States and similar organizations in Europe and Asia-Pacific. Growing urbanization and infrastructure investments are further increasing demand, especially in emerging economies where construction projects require comprehensive fire safety systems. Additionally, the increasing awareness and adoption of smart fire detection and suppression technologies enhance fire protection’s appeal for commercial and industrial applications.
Regionally, North America holds a dominant market share due to strong regulatory frameworks and advanced infrastructure investments in the U.S. and Canada. Europe also represents a significant share, with countries like Germany, the U.K., and France implementing strict fire safety standards across industries. The Asia-Pacific region is projected to witness the fastest growth, driven by rising construction activities, urbanization, and industrialization, particularly in China, India, and Southeast Asia. With increasing government initiatives focusing on fire safety, the global fire protection systems market is set for steady expansion as industries prioritize safety, compliance, and advanced protection solutions.
Market Drivers:
Stringent Government Regulations and Standards:
Regulatory bodies worldwide enforce strict fire safety standards across sectors, driving the adoption of comprehensive fire protection systems. In the United States, the National Fire Protection Association (NFPA) and Occupational Safety and Health Administration (OSHA) require robust fire protection measures in workplaces and public buildings. For instance, European countries follow stringent fire safety codes, like the BS 5839 standard in the U.K., which mandates fire detection and alarm systems in commercial properties. These regulations increase demand for reliable fire protection solutions to ensure compliance and minimize risks in various industries.
Rising Construction and Infrastructure Investments:
Rapid urbanization and significant infrastructure projects, especially in emerging economies, have heightened the need for effective fire protection systems. Governments in regions like Asia-Pacific are heavily investing in urban infrastructure and commercial construction. For instance, India’s Smart Cities Mission and infrastructure expansion projects in China prioritize fire safety measures to protect valuable assets and reduce the risk of fire-related incidents. Such initiatives drive demand for advanced fire detection and suppression systems in residential, commercial, and industrial spaces.
Growing Awareness and Technological Advancements:
The integration of smart technologies like IoT and AI has transformed fire protection systems, enabling rapid, accurate response mechanisms that reduce fire hazards. Companies such as Honeywell and Siemens have developed smart detection systems that utilize sensors, data analytics, and automation to detect fire risks early and trigger immediate actions. This trend aligns with the increased adoption of connected systems in smart buildings, where real-time alerts and remote monitoring enhance safety and operational efficiency, especially in high-risk environments like manufacturing and oil & gas.
Rising Emphasis on Property and Life Safety:
Increasing awareness of fire hazards and their impact on property and life safety further fuels demand for fire protection systems. Studies by the World Health Organization (WHO) emphasize the importance of fire prevention in reducing injury and property loss, leading to greater adoption of safety measures across public buildings, schools, and healthcare facilities. In commercial sectors, companies invest in advanced fire protection to secure assets and maintain business continuity, with heightened demand in areas like data centers, where fire incidents can cause significant data and operational losses.
Market Trends:
Integration of IoT and Smart Technologies:
The fire protection systems market increasingly incorporates Internet of Things (IoT) and smart technologies to enhance fire detection and response. IoT-enabled systems offer real-time monitoring, early warning alerts, and remote accessibility, allowing facility managers to respond quickly to potential fire hazards. For instance, Honeywell has developed connected fire alarms that integrate with building management systems to streamline fire detection and alert systems. The use of AI algorithms in these systems further improves detection accuracy, minimizing false alarms and ensuring a timely response.
Expansion of Wireless Fire Protection Systems:
Wireless fire protection systems are gaining traction, particularly in large facilities or structures where wired systems are less practical. Wireless systems simplify installation, reduce costs, and provide flexibility in expanding or relocating fire safety components. This trend is prevalent in sectors like healthcare and hospitality, where building layouts often require adaptable safety solutions. Siemens and other companies are developing advanced wireless detection and alarm systems that comply with stringent safety regulations, making them ideal for retrofitting existing structures without extensive renovations.
Increased Focus on Sustainable and Eco-Friendly Solutions:
Sustainability is becoming a priority in fire protection as companies focus on reducing the environmental impact of suppression agents. Traditional fire suppression systems often use chemicals with high global warming potential, while newer systems employ eco-friendly agents like water mist or clean agents, which are less harmful to the environment. For example, Johnson Controls has introduced fire suppression solutions using environmentally friendly agents that minimize greenhouse gas emissions while meeting regulatory standards. This trend aligns with global sustainability efforts and helps organizations meet their environmental compliance goals.
Growing Demand for Customized Fire Safety Solutions:
As businesses in various sectors have unique fire protection needs, the demand for tailored fire safety solutions is rising. Companies are increasingly seeking customized systems that address specific risks in their industries, from data centers to oil refineries. For instance, FM Global, a large property insurance provider, works closely with clients to design and implement fire protection systems based on industry-specific requirements and facility layouts. This trend reflects a shift toward precision-engineered solutions that meet the distinct needs of high-risk sectors, helping minimize property damage and operational disruptions in the event of a fire.
Market Challenges Analysis:
High Installation and Maintenance Costs:
Fire protection systems can be costly to install and maintain, posing a significant barrier, especially for small and medium-sized enterprises (SMEs). The initial investment in fire detection and suppression systems, along with regular testing, inspection, and maintenance, demands considerable financial commitment. This can be challenging for budget-constrained facilities and industries, slowing the adoption of comprehensive fire protection systems. In particular, advanced systems integrated with IoT or smart technology are costlier, which restricts their implementation in older facilities where retrofitting costs are prohibitive.
Complex Regulatory Compliance:
Fire protection systems must comply with strict local and international regulations, which vary by region and industry. For example, in the United States, the National Fire Protection Association (NFPA) and Occupational Safety and Health Administration (OSHA) mandate specific standards for system design, installation, and inspection, often requiring facilities to update systems to remain compliant. Similarly, the European Union’s Construction Products Regulation (CPR) sets stringent fire safety requirements, which can lead to additional costs and complexity for manufacturers and installers. Adhering to these diverse regulations can be burdensome, particularly in industries where compliance costs are high.
Technological Complexity and Skilled Workforce Requirements:
The increasing integration of IoT, AI, and data analytics into fire protection systems brings complexity that requires a skilled workforce for proper installation, monitoring, and maintenance. However, there is a shortage of professionals trained in these advanced technologies, creating a challenge for companies aiming to implement and manage these systems. According to the U.S. Bureau of Labor Statistics (BLS), the demand for skilled technicians in building and fire protection systems is growing, but the talent gap remains an industry-wide issue.
Environmental Concerns and Disposal Issues:
Traditional fire suppression agents, such as halons, are known for their environmental impact, particularly on the ozone layer. While newer, eco-friendly agents are available, they come at a higher cost. Additionally, Environmental Protection Agency (EPA) regulations impose strict guidelines on the disposal of outdated and harmful agents, requiring companies to invest in compliant disposal methods. These environmental restrictions complicate system upgrades, especially for companies using older suppression technologies.
Market Segmentation Analysis:
By Type, the market includes fire detection systems, suppression systems, alarm systems, and fire response systems. Detection systems, which include smoke detectors, heat detectors, and flame detectors, dominate the market due to their essential role in early fire identification. Suppression systems, such as sprinklers and extinguishing agents, are increasingly used across sectors requiring immediate fire control, with clean agents preferred in data centers and sensitive equipment areas.
By Technology, the market is categorized into active and passive fire protection. Active protection involves systems that detect and control fires, such as sprinklers and fire alarms, and are critical in facilities with high human occupancy or asset value. Passive fire protection, which includes fire-resistant walls, doors, and coatings, is widely used in building construction to contain fire spread, especially in commercial and industrial settings.
By End User, the market serves commercial, industrial, and residential sectors. The commercial segment, which includes offices, retail centers, and educational institutions, holds a significant share due to strict regulatory compliance requirements. The industrial sector also represents a considerable portion, as facilities such as oil and gas refineries, manufacturing plants, and warehouses need robust fire protection due to heightened fire risks. Residential applications are growing as awareness of home fire safety rises, spurred by government safety campaigns and incentives for fire protection system installations. This segmentation highlights the varied demand and adaptability of fire protection systems across diverse environments and safety needs.
Segmentations:
By Product Type
- Fire Detection
- Smoke Detector
- Heat Detector
- Flame Detector
- Gas Detector
- Fire Suppression
- Gaseous
- Chemical
- Water
- Foam
- Fire Sprinkler System
- Water Pipe Fire Sprinkler
- Dry Pipe Fire Sprinkler
- Pre-action Sprinkler System
- Deluge Sprinkler System
- Alarm and Notification Systems
- Fire Response
By Service
- Installations & Replacements
- System Inspections & Maintenance
- Fire Alarm & Fire Sprinkler Monitoring
- Fire Extinguisher Training
- Others (Engineering Services, etc.)
By End-User
- Residential
- Commercial
- Office Buildings and Educational Institutes
- Retail
- Hotels and Hospitality
- Shopping Malls
- Others (Theaters, etc.)
- Industrial
- Energy and Power
- Manufacturing
- Oil and Gas Plant
- Automotive
- Others (Transportation, etc.)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America North America holds the largest share of the global fire protection systems market, accounting for approximately 35% of total revenue. This dominance is driven by stringent safety regulations enforced by bodies such as the National Fire Protection Association (NFPA) and the Occupational Safety and Health Administration (OSHA) in the United States. High levels of construction activity, particularly in commercial buildings, also boost the demand for fire protection systems in the region. The United States leads North America’s market, with significant investment in IoT-enabled smart fire detection and suppression technologies. Canada follows, focusing on strict fire codes that drive the adoption of advanced fire protection systems in commercial and industrial sectors. North America’s market growth reflects a combination of regulatory compliance, high public safety awareness, and advanced technological infrastructure.
Europe Europe represents around 25% of the global fire protection systems market, with a strong focus on sustainable and eco-friendly solutions. Regulatory standards, like the European Union’s Construction Products Regulation (CPR), mandate high fire safety standards in residential and commercial buildings. Countries such as Germany, France, and the United Kingdom lead the region, with extensive use of fire protection systems in public buildings, industrial facilities, and transport infrastructure. The demand for wireless and eco-friendly fire suppression solutions, such as water mist and clean agents, is also increasing in Europe as sustainability concerns grow. Additionally, ongoing upgrades to fire safety systems in older buildings further support market expansion.
Asia-Pacific The Asia-Pacific region is anticipated to experience the fastest growth in the fire protection systems market, projected to capture approximately 20% of global demand by 2032. Rapid industrialization, urbanization, and infrastructure development, particularly in China, Japan, and India, drive this growth. The Chinese government’s investments in smart cities and infrastructure projects prioritize fire safety measures, boosting the demand for comprehensive fire protection systems. In Japan, a high focus on earthquake-resistant and fire-safe buildings propels the adoption of robust fire protection solutions. India is witnessing rising adoption of fire safety systems in commercial sectors, spurred by increasing awareness and regulatory emphasis on safety.
Latin America and Middle East & Africa Latin America and the Middle East & Africa (MEA) together account for around 10% of the global fire protection systems market. In Latin America, Brazil and Mexico are major contributors, driven by regulatory measures and safety awareness in urban areas. MEA countries, particularly the UAE and Saudi Arabia, show strong demand for advanced fire protection systems due to extensive construction projects and high safety standards in commercial developments. Although these regions have smaller market shares compared to North America and Europe, growing awareness and the expansion of urban infrastructure present opportunities for growth, particularly in the commercial and industrial sectors.
Key Player Analysis:
- Honeywell International Inc.
- Johnson Controls International plc
- RTX Corporation
- Siemens AG
- Robert Bosch GmbH
- Eaton Corporation plc
- Halma plc
- HOCHIKI Corporation
- Gentex Corporation
- Amerex Corporation
Competitive Analysis:
The fire protection systems market is highly competitive, with key players like Honeywell International Inc., Johnson Controls International plc, and Siemens AG leading due to their broad portfolios and advanced technology capabilities. These companies leverage strong R&D investments to integrate IoT, AI, and sustainable solutions, aligning with the market’s shift towards smart fire detection and eco-friendly suppression systems. Mid-sized companies such as Halma plc and HOCHIKI Corporation also contribute by specializing in innovative fire safety solutions tailored to specific industries, including commercial and residential sectors. In addition, as stringent fire safety regulations drive demand, companies across the board are enhancing their offerings with real-time monitoring and wireless system options to meet compliance standards in various regions. The competitive landscape reflects a balance between established global leaders focusing on cutting-edge technology and regional players offering specialized and adaptable fire protection solutions.
Recent Developments:
- Johnson Controls launched the new Simplex Foundation series of fire alarm control units in August 2023. This series is designed for industrial and commercial applications, focusing on reliability and cost-efficiency, featuring advanced detection capabilities suitable for diverse environments.
- In April 2024, Honeywell International Inc. introduced the Fire Lite alarm system aimed at residential, commercial, and industrial sectors. This system supports cloud-based monitoring, remote operations, and enhanced compliance features, catering especially to small and medium-sized enterprises with streamlined safety needs.
- Carrier’s subsidiary, Edwards, released the Optica duct smoke detector in June 2024, engineered for HVAC systems in commercial and industrial buildings. This advanced detector improves early smoke detection and helps mitigate potential fire hazards in large-scale facilities.
- In February 2023, Halma Plc acquired Thermocable Ltd, a UK-based fire protection and detection company, for approximately $24.3 million. This acquisition aimed to expand Halma’s product portfolio and improve its sales growth by leveraging Thermocable’s expertise in fire detection technologies.
Market Concentration & Characteristics:
The fire protection systems market is moderately concentrated, with major players like Honeywell International Inc., Johnson Controls International plc, and Siemens AG leading due to their extensive product portfolios, global reach, and robust R&D investments. These companies dominate the market by offering technologically advanced fire detection, suppression, and alarm systems, often integrated with IoT and smart-building technologies. Mid-sized firms such as Halma plc and HOCHIKI Corporation focus on specialized fire safety solutions tailored for industries like healthcare, industrial manufacturing, and hospitality, contributing to a diverse market landscape. With stringent regulatory requirements and rising safety awareness, companies across all segments prioritize compliance and innovation. The competitive landscape is shaped by advancements in wireless and eco-friendly systems, as companies work to align with environmental standards and evolving building safety codes.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Service, End-User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The fire protection systems market is expected to expand as urbanization and infrastructure development continue to rise.
- Demand for IoT-enabled fire detection systems is anticipated to grow, driven by advancements in smart technologies that provide real-time monitoring and remote access capabilities.
- Government regulations on fire safety in North America and Europe are projected to intensify, pushing businesses to adopt compliant and high-performance fire protection solutions.
- The commercial sector, including offices, retail, and healthcare, is expected to remain a dominant end-user segment.
- The adoption of wireless fire protection systems will likely increase, especially in retrofitting projects, where they provide flexibility and reduce installation costs.
- Increasing environmental awareness is forecasted to drive demand for eco-friendly fire suppression agents.
- Technological advancements in AI and machine learning are set to improve fire detection accuracy, minimizing false alarms and enhancing emergency response times.
- Retrofitting and updating fire protection systems in older buildings will continue to offer growth opportunities in mature markets, especially in Europe and North America.
- Collaborative efforts between fire protection companies and construction firms are anticipated to streamline fire safety integration in new buildings, making fire systems a standard component of smart infrastructure.
- Partnerships between manufacturers and property insurance companies will likely emerge, as insurers encourage investment in advanced fire safety measures to reduce risk and potential losses.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Government Regulations and Standards
Global enforcement of strict fire safety codes by organizations such as NFPA, OSHA, and the EU’s CPR compels businesses and property owners to install and maintain advanced fire protection systems, ensuring compliance and minimizing fire-related risks.
Rising Construction and Infrastructure Investments
Rapid urbanization and large-scale infrastructure projects, especially in emerging economies, are increasing the need for comprehensive fire protection systems in new commercial, industrial, and residential developments.
Technological Advancements and Smart Integration
The adoption of IoT, AI, and wireless technologies in fire protection systems enables real-time monitoring, early detection, and remote management, making fire safety solutions more effective and appealing for modern smart buildings.
Growing Awareness of Property and Life Safety
Heightened awareness of the devastating impact of fires on lives and assets, supported by public safety campaigns and insurance incentives, is driving the adoption of fire protection systems across sectors.
Demand for Sustainable and Eco-Friendly Solutions
Environmental regulations and corporate sustainability goals are pushing the market toward eco-friendly fire suppression agents and systems, encouraging innovation and adoption of green technologies in fire protection.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Fire Protection Systems Market?
What factors are driving the growth of the Fire Protection Systems Market?
What are some challenges faced by the Fire Protection Systems Market?
Who are the major players in the Fire Protection Systems Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service
- 1.2.1 Installations & Replacements
- 1.2.2 System Inspections & Maintenance
- 1.2.3 Fire Alarm & Fire Sprinkler Monitoring
- 1.2.4 Fire Extinguisher Training
- 1.2.5 Others (Engineering Services, etc.)
- 1.3 By End-User
- 1.3.1 Residential
- 1.3.2 Commercial (Office Buildings, Retail, Hospitality, Shopping Malls, Others)
- 1.3.3 Industrial (Energy and Power, Manufacturing, Oil and Gas, Automotive, Others)
- 1.4 By Product Type
- 1.4.1 Fire Detection (Smoke Detector, Heat Detector, Flame Detector, Gas Detector)
- 1.4.2 Fire Suppression (Gaseous, Chemical, Water, Foam)
- 1.4.3 Fire Sprinkler System (Water Pipe, Dry Pipe, Pre-action, Deluge)
- 1.4.4 Alarm and Notification Systems
- 1.4.5 Fire Response
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 68,910 million → 2032: USD 111,500.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fire Protection Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fire Protection Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Fire Protection Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Fire Protection Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fire Protection Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fire Protection Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fire Protection Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fire Protection Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 68,910 million → 2032: USD 111,500.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fire Protection Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Installations & Replacements
- 12.3.7.2 System Inspections & Maintenance
- 12.3.7.3 Fire Alarm & Fire Sprinkler Monitoring
- 12.3.7.4 Fire Extinguisher Training
- 12.3.7.5 Others (Engineering Services, etc.)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial (Office Buildings, Retail, Hospitality, Shopping Malls, Others)
- 12.4.7.3 Industrial (Energy and Power, Manufacturing, Oil and Gas, Automotive, Others)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fire Detection (Smoke Detector, Heat Detector, Flame Detector, Gas Detector)
- 12.5.7.2 Fire Suppression (Gaseous, Chemical, Water, Foam)
- 12.5.7.3 Fire Sprinkler System (Water Pipe, Dry Pipe, Pre-action, Deluge)
- 12.5.7.4 Alarm and Notification Systems
- 12.5.7.5 Fire Response
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fire Protection Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Fire Protection Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Fire Protection Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Fire Protection Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Honeywell International Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Johnson Controls International plc
- 18.4 Siemens AG
- 18.5 Robert Bosch GmbH
- 18.6 Eaton Corporation plc
- 18.7 Halma plc
- 18.8 HOCHIKI Corporation
- 18.9 Gentex Corporation
- 18.10 Amerex Corporation
- 18.11 RTX Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

