
Plumbing Fixtures Market Overview:
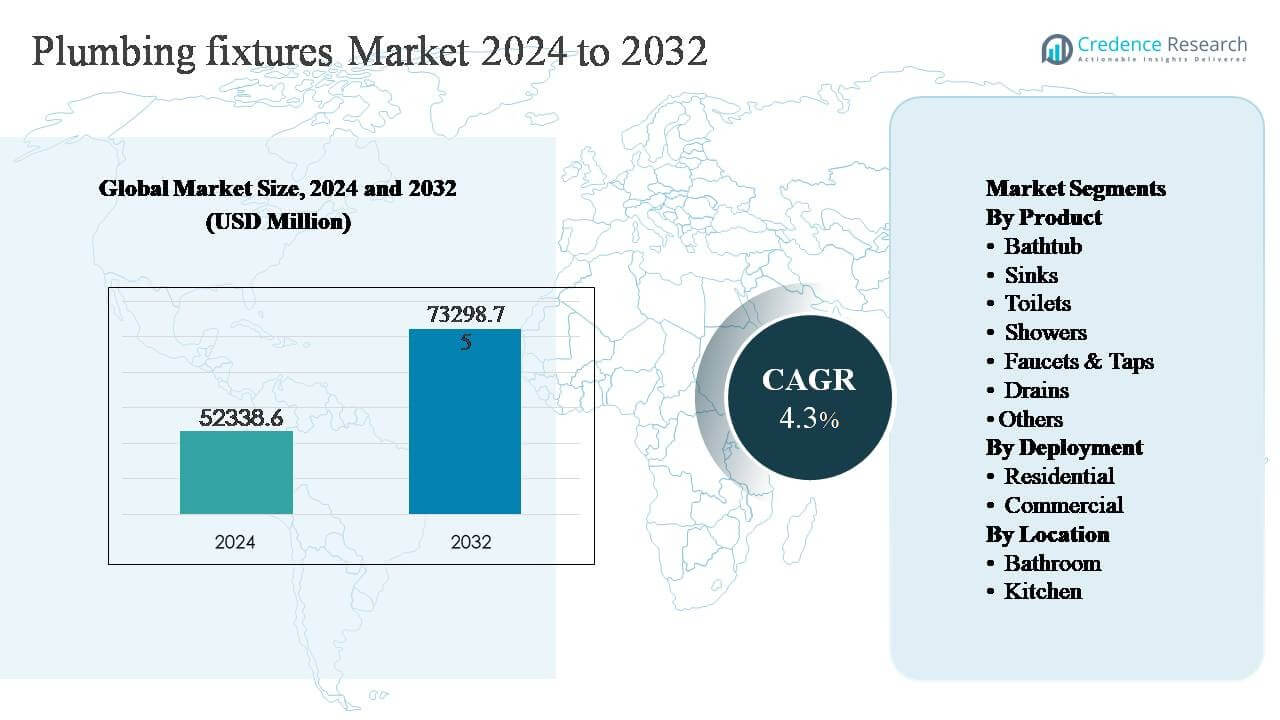
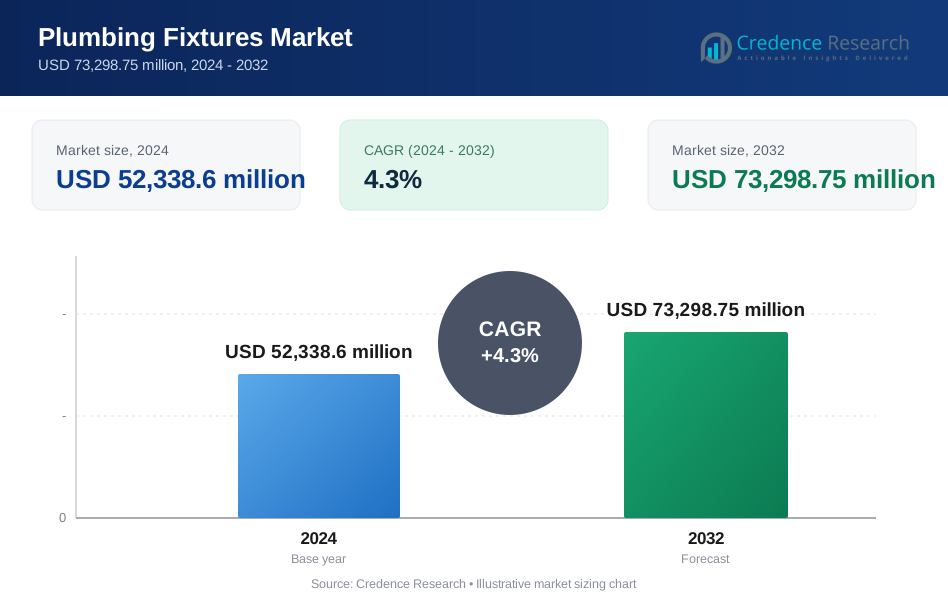
The global plumbing fixtures market was valued at USD 52,338.6 million in 2024 and is projected to reach USD 73,298.75 million by 2032, expanding at a compound annual growth rate (CAGR) of 4.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Plumbing Fixtures Market Size 2024 | USD 52,338.6 million |
| Plumbing Fixtures Market, CAGR | 4.3% |
| Plumbing Fixtures Market, Size 2032 | USD 73,298.75 million |
Plumbing Fixtures Market Insights
- Market growth is driven by rising urbanization, housing development, and renovation projects, along with increasing adoption of water-efficient fixtures such as dual-flush toilets, low-flow faucets, and pressure-regulated showers to comply with water conservation regulations.
- Key trends include growing demand for smart and touchless fixtures, premium and design-oriented products, and integrated bathroom and kitchen solutions, while toilets remain the dominant product segment with nearly 30% share, and residential deployment accounts for about 60-65% of demand.
- The competitive landscape is moderately fragmented, with global players focusing on innovation, sustainability, and brand differentiation, while regional manufacturers compete on pricing and localized product offerings in cost-sensitive markets.
- Regionally, Asia Pacific leads with around 35% market share, followed by North America at ~29% and Europe at ~25%, with bathrooms contributing nearly 70% of total fixture demand due to higher fixture density and frequent renovations.
Plumbing Fixtures Market Segmentation Analysis:
By Product:
By product, toilets represent the dominant sub-segment in the plumbing fixtures market, accounting for an estimated 28-32% of total revenue share. Their leadership is driven by universal necessity across residential and commercial buildings, frequent replacement cycles, and strong regulatory push for water-efficient designs such as dual-flush and low-flow toilets. Faucets & taps follow closely, supported by rising adoption of sensor-based and touchless models in commercial spaces. Sinks and showers maintain steady demand from housing and hospitality projects, while bathtubs remain niche, primarily driven by premium residential renovations and luxury hotel developments.
- For instance, TOTO’s latest generation of ultra-high-efficiency toilets, including models under its Drake II 1G and Neorest series, are certified to operate at 3.0–3.8 liters per flush (0.8–1.0 GPF), compared with legacy 13-liter systems, while integrating gravity-fed Tornado Flush (or Dynamax Tornado Flush) mechanisms delivering 1,000 g MaP waste removal performance.
By Deployment:
By deployment, the residential segment dominates, contributing approximately 60-65% of overall market share. This dominance is driven by continuous housing construction, urbanization, and strong renovation activity, particularly in bathrooms and kitchens. Homeowners increasingly invest in modern, aesthetically appealing, and water-saving fixtures to enhance comfort and property value. Government housing schemes and rising disposable incomes further support residential demand. Meanwhile, the commercial segment covering hotels, offices, healthcare facilities, and educational institutions shows steady growth, supported by infrastructure expansion, hygiene standards, and demand for durableBY-driven and sensor-enabled fixtures.
- For instance, LIXIL’s INAX residential toilet and faucet ranges integrate water-saving technologies certified to operate at 0-4.5 liters per flush for toilets and 5-6 liters per minute for faucets, supported by ceramic cartridge valves tested for over 200,000 operating cycles, aligning with durability requirements in high-use households.
By Location:
By location, the bathroom segment holds the leading position, accounting for nearly 70% of total plumbing fixtures demand. Bathrooms require a higher concentration of fixtures, including toilets, showers, faucets, sinks, and bathtubs, making them the primary revenue contributor. Growth is driven by rising bathroom upgrades, luxury housing trends, and increased focus on hygiene and water efficiency. The kitchen segment, while smaller, is expanding steadily due to demand for advanced faucets, pull-down sprays, and integrated sink systems, supported by modular kitchen adoption and residential remodeling trends.
Key Growth Drivers
Expansion of Residential and Commercial Construction Activities
Rising global construction activity remains a primary driver of the plumbing fixtures market. Rapid urbanization, population growth, and government-backed housing initiatives are accelerating new residential developments, particularly in emerging economies. In parallel, steady investments in commercial infrastructure including hotels, offices, healthcare facilities, and educational institutions are generating sustained demand for durable and high-performance plumbing fixtures. Replacement demand from aging buildings further strengthens market growth, as outdated fixtures are upgraded to meet modern efficiency, safety, and design standards. Renovation and remodeling activities, especially in urban households, contribute significantly as consumers seek enhanced aesthetics, comfort, and functionality. Together, new construction and refurbishment cycles ensure a consistent and long-term demand base for plumbing fixtures across multiple end-use sectors.
- For instance, Kohler’s commercial sanitary solutions, tailored for high-traffic hospitality and healthcare environments, utilize Pressure Lite® pressure-assisted flushing systems that achieve 1,000g MaP waste removal the highest industry rating while its commercial manual flush valves feature self-cleaning piston technology and brass components designed for long-term reliability in demanding settings.
Rising Focus on Water Conservation and Efficiency Regulations
Increasing water scarcity and growing environmental awareness are driving the adoption of water-efficient plumbing fixtures. Governments and regulatory bodies worldwide are enforcing stringent standards related to water usage, compelling builders and consumers to shift toward low-flow faucets, dual-flush toilets, and pressure-optimized showers. These regulations not only encourage sustainable consumption but also reduce utility costs for end users, strengthening adoption rates. Commercial facilities, in particular, are prioritizing water-saving fixtures to comply with building codes and sustainability certifications. As water efficiency becomes a critical purchasing criterion, manufacturers continue to innovate in flow-control technologies, reinforcing water conservation as a key growth catalyst for the plumbing fixtures market.
- For instance, Grohe’s EcoJoy faucet technology integrates flow limiters calibrated at 0 liters per minute, supported by ceramic cartridges endurance-tested for over 500,000 handle operations.
Increasing Demand for Hygiene, Comfort, and Modern Living Standards
Changing consumer lifestyles and heightened awareness of hygiene are significantly influencing demand for advanced plumbing fixtures. Post-pandemic emphasis on sanitation has accelerated adoption of touchless faucets, sensor-enabled taps, and easy-to-clean fixture designs, especially in commercial and public spaces. In residential settings, consumers increasingly view bathrooms and kitchens as comfort-driven lifestyle spaces rather than purely functional areas. This shift fuels demand for premium fixtures offering enhanced usability, ergonomic designs, and aesthetic appeal. Rising disposable incomes and exposure to global interior design trends further encourage consumers to invest in upgraded plumbing solutions, supporting steady market expansion.
Key Trends & Opportunities
Growth of Smart and Sensor-Based Plumbing Fixtures
Smart plumbing fixtures represent a major trend and opportunity within the market. Touchless faucets, automated flushing systems, and digitally controlled showers are gaining traction due to their hygiene benefits, water-saving capabilities, and user convenience. These solutions are particularly attractive in commercial environments such as airports, malls, hospitals, and offices, where high usage frequency necessitates durability and efficiency. In residential applications, smart fixtures appeal to tech-savvy consumers seeking connected home solutions. Integration with smart home ecosystems and building management systems creates opportunities for manufacturers to differentiate offerings and capture premium market segments.
- For instance, Sloan Valve Company electronic flushometers used in large public facilities integrate infrared sensors. These systems typically have a user-friendly 3-second flush delay (for water closets; 1 second for urinals) to prevent false flushing, not a sub-0.3-second activation response.
Rising Demand for Premium and Aesthetically Designed Fixtures
Design-driven consumption is emerging as a key opportunity, especially in urban residential and hospitality projects. Consumers increasingly prefer fixtures that combine functionality with contemporary aesthetics, such as minimalist faucets, matte finishes, and customized bathroom fittings. Luxury housing developments and high-end hotels are driving demand for premium bathtubs, designer faucets, and integrated shower systems. This trend allows manufacturers to expand margins through value-added products while catering to evolving consumer preferences focused on personalization and interior design coherence.
- For instance, Hansgrohe’s AXOR design faucets are manufactured with PVD-coated surfaces measured at >1,000 Vickers hardness, providing significantly higher scratch resistance than conventional chrome finishes, while internal ceramic cartridges are tested for 500,000+ actuation cycles to ensure durability alongside premium appearance.
Growth Potential in Emerging Economies and Infrastructure Development
Emerging markets present strong growth opportunities due to rapid urban development, improving living standards, and large-scale infrastructure investments. Government initiatives supporting affordable housing, sanitation improvement, and smart city development are expanding the addressable market for plumbing fixtures. As penetration of modern plumbing solutions increases in these regions, demand for reliable, cost-effective, and regulation-compliant fixtures is expected to rise steadily, offering long-term expansion potential for market participants.
Key Challenges
Volatility in Raw Material Prices and Manufacturing Costs
Fluctuating prices of key raw materials such as metals, ceramics, and polymers pose a significant challenge for plumbing fixture manufacturers. Cost volatility directly impacts production expenses, pricing strategies, and profit margins, particularly for manufacturers operating at scale. In highly competitive markets, passing increased costs to consumers is often difficult, leading to margin pressure. Additionally, energy costs and transportation expenses further compound operational challenges, especially for companies with global supply chains. Managing cost efficiency while maintaining product quality remains a critical concern across the industry.
Intense Market Competition and Price Sensitivity
The plumbing fixtures market is highly competitive, with numerous global and regional players offering similar product portfolios. Price sensitivity among consumers, particularly in emerging markets, intensifies competition and limits pricing flexibility. Low-cost local manufacturers often challenge established brands by offering affordable alternatives, making brand differentiation increasingly important. Maintaining market share requires continuous innovation, marketing investment, and distribution expansion, which can strain operational resources. This competitive pressure creates challenges for both new entrants and established players seeking sustainable growth.
Regional Analysis
North America
North America accounts for approximately 28-30% of the global plumbing fixtures market, supported by strong renovation activity and strict water-efficiency regulations. The region benefits from a mature construction sector, high replacement demand, and widespread adoption of smart and water-saving fixtures. Residential remodeling, particularly bathroom and kitchen upgrades, remains a key growth driver, while commercial demand is reinforced by healthcare, hospitality, and office infrastructure investments. The presence of established manufacturers and high consumer awareness regarding hygiene, sustainability, and premium design further strengthen market stability and steady growth across the United States and Canada.
Europe
Europe represents nearly 24-26% of the global market share, driven by stringent environmental regulations and strong emphasis on sustainable building practices. Water conservation directives and green building certifications accelerate adoption of low-flow toilets, faucets, and advanced shower systems. Western Europe leads demand through renovation of aging housing stock and premium bathroom installations, while Eastern Europe contributes through expanding residential construction. High consumer preference for design-centric and durable fixtures supports demand for premium products. Government-backed energy- and water-efficiency initiatives continue to position Europe as a technology-driven and regulation-led regional market.
Asia Pacific
Asia Pacific holds the largest share at approximately 34-36%, making it the dominant regional market for plumbing fixtures. Rapid urbanization, population growth, and large-scale residential construction projects in China, India, and Southeast Asia are key growth drivers. Rising disposable incomes and improving living standards fuel demand for modern bathroom and kitchen fixtures. Government investments in sanitation, affordable housing, and urban infrastructure further support market expansion. While cost-effective products dominate volumes, premium and smart fixtures are gaining traction in urban centers, reinforcing Asia Pacific’s leadership in both volume and growth potential.
Latin America
Latin America accounts for around 6-7% of the global plumbing fixtures market, supported by gradual recovery in construction activity and steady urban development. Residential housing projects and refurbishment of existing buildings drive demand, particularly in Brazil, Mexico, and Chile. Growing awareness of water efficiency and improved access to modern sanitation are encouraging adoption of standardized plumbing fixtures. However, price sensitivity remains high, favoring mid-range and economical products. Commercial demand from hospitality and retail infrastructure contributes moderately, positioning the region for stable, incremental growth rather than rapid expansion.
Middle East & Africa
The Middle East & Africa region contributes approximately 5-6% of the global market share, driven primarily by commercial and infrastructure-led demand. Large-scale construction projects, including hotels, airports, healthcare facilities, and smart city developments, support strong demand for durable and high-capacity plumbing fixtures. In the Middle East, luxury real estate and hospitality investments boost premium fixture adoption, while Africa’s growth is supported by improving sanitation infrastructure and urban housing initiatives. Despite challenges related to cost sensitivity and uneven development, long-term infrastructure spending sustains regional market potential.
Plumbing Fixtures Market Segmentations:
By Product
- Bathtub
- Sinks
- Toilets
- Showers
- Faucets & Taps
- Drains
- Others
By Deployment
- Residential
- Commercial
By Location
- Bathroom
- Kitchen
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the plumbing fixtures market is characterized by the presence of established global manufacturers alongside numerous regional and local players, creating a moderately fragmented and highly competitive environment. Leading companies compete through broad product portfolios covering toilets, faucets, showers, sinks, and bathtubs, while emphasizing water efficiency, durability, and design innovation. Strategic priorities include continuous product launches, integration of smart and sensor-based technologies, and expansion of premium and customized offerings. Companies also strengthen their market position through mergers, acquisitions, and partnerships to enhance geographic reach and distribution networks. Brand reputation, compliance with water conservation regulations, and after-sales service play a critical role in competitive differentiation. Meanwhile, regional players focus on cost-competitive solutions and localized designs to address price-sensitive markets, intensifying competition across both developed and emerging regions.
Key Player Analysis
- TOTO Group
- ROCA Group
- Masco Corporation
- LIXIL International Pte Ltd.
- Jaquar Group
- Hindware Homes
Recent Developments
- In March 2025, Roca showcased its latest bathroom collections and technologies including new sustainable sanitaryware and design-centric bathroom systems at one of the world’s largest sanitary and HVAC trade shows, emphasizing Mediterranean design and resource-efficient manufacturing practices.
- In February 24, 2025, TOTO unveiled a lineup of next-generation smart, sustainable, and luxury bathroom innovations at KBIS 2025 (Kitchen & Bath Industry Show) including advanced digital control fixtures and high-efficiency systems designed for modern residential and commercial bathrooms.
Report Coverage
The research report offers an in-depth analysis based on Product, Deployment, Location and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to benefit from steady residential construction and renovation activities across both developed and emerging economies.
- Demand for water-efficient plumbing fixtures will increase as governments strengthen water conservation regulations and sustainability standards.
- Smart and sensor-based fixtures will see wider adoption, particularly in commercial buildings and high-end residential projects.
- Bathroom applications will remain the primary demand center due to higher fixture density and frequent upgrade cycles.
- Residential deployment will continue to dominate, supported by urbanization and rising home improvement spending.
- Premium and design-focused fixtures will gain traction as consumers prioritize aesthetics and comfort in living spaces.
- Emerging economies will play a critical role in volume growth driven by housing, sanitation, and infrastructure development.
- Manufacturers will increasingly focus on product innovation, durability, and ease of installation to differentiate offerings.
- Strategic partnerships and acquisitions will shape competition by expanding geographic reach and product portfolios.
- Digital sales channels and omnichannel distribution will grow in importance for both residential and commercial buyers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for plumbing fixtures, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the plumbing fixtures market projected to grow between 2024 and 2032?
Which plumbing fixtures segment held the largest share in 2024?
What are the primary factors fueling the growth of the plumbing fixtures market?
Who are the leading companies in the plumbing fixtures market?
Which region commanded the largest share of the plumbing fixtures market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 52,338.6 million → 2032: USD 73,298.75 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Plumbing Fixtures Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Plumbing Fixtures Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Plumbing Fixtures Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Plumbing Fixtures Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Plumbing Fixtures Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Plumbing Fixtures Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Plumbing Fixtures Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Plumbing Fixtures Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 52,338.6 million → 2032: USD 73,298.75 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Plumbing Fixtures Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Plumbing Fixtures Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Plumbing Fixtures Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Plumbing Fixtures Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

