
Market Overview
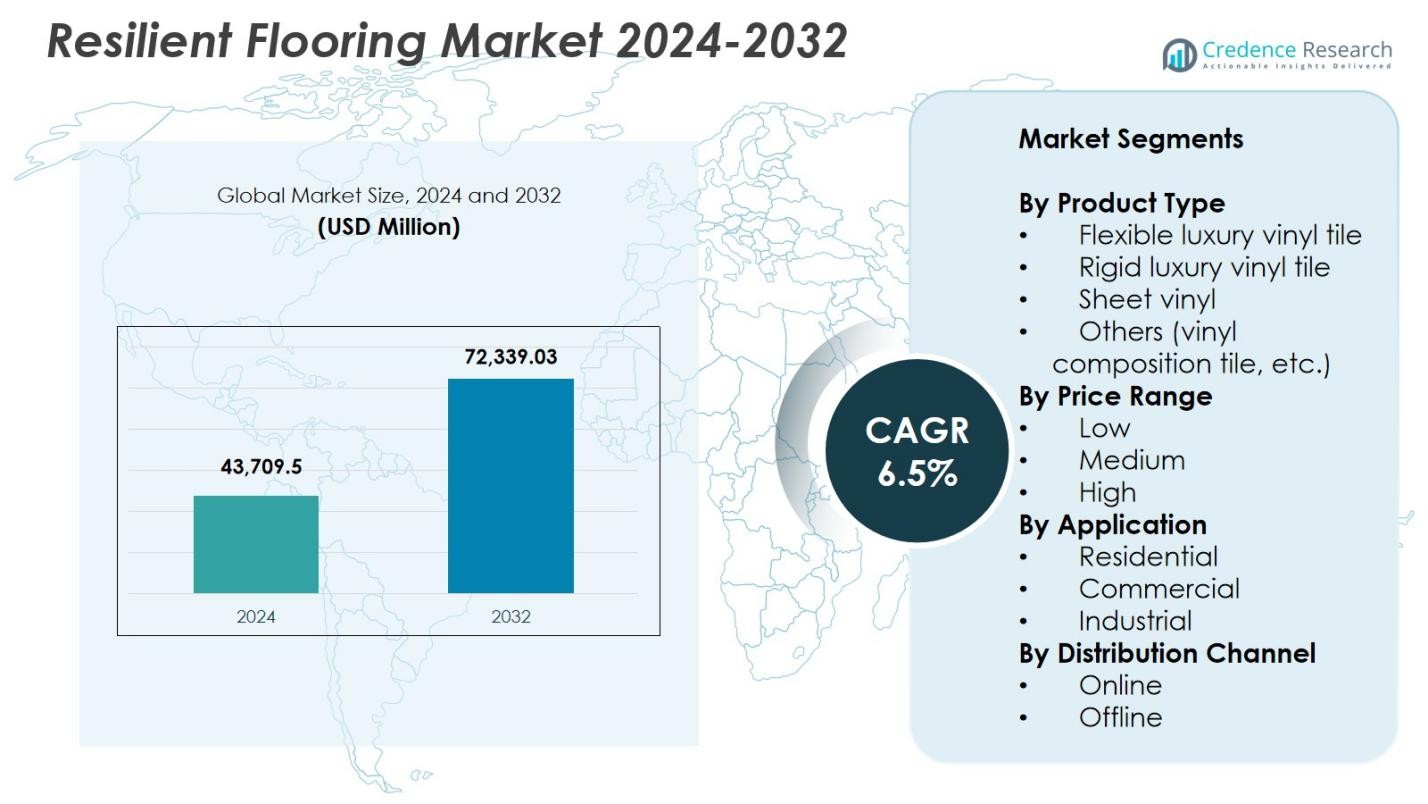
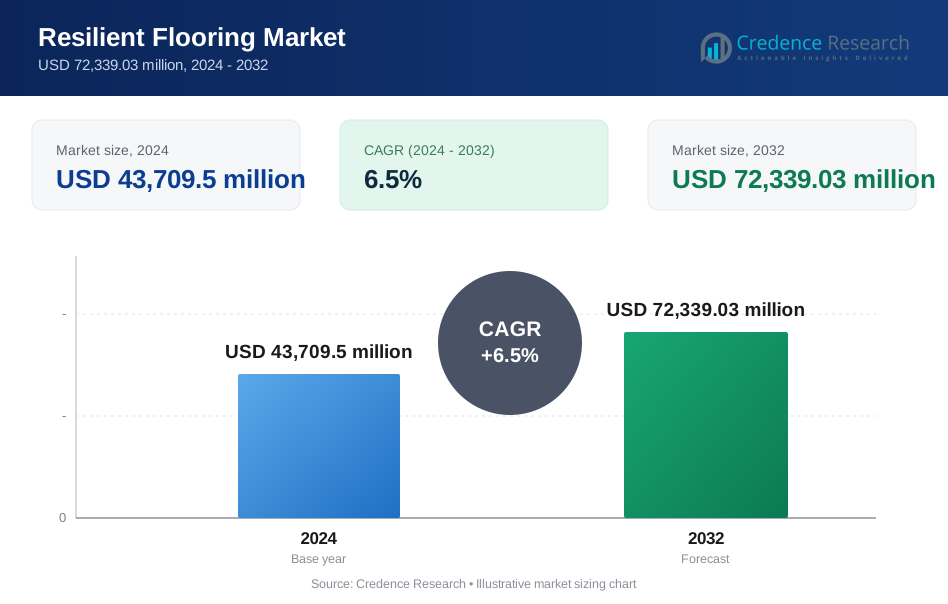
Resilient Flooring Market size was valued at USD 43,709.5 million in 2024 and is anticipated to reach USD 72,339.03 million by 2032, at a CAGR of 6.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Resilient Flooring Market Size 2024 | USD 43,709.5 Million |
| Resilient Flooring Market, CAGR | 6.5% |
| Resilient Flooring Market Size 2032 | USD 72,339.03 Million |
Resilient Flooring Market features leading players such as Gerflor, Beaulieu, COREtec, Karndean, Interface, Armstrong Flooring, LG Hausys, Forbo, Amtico, and Congoleum, all driving growth through advanced product innovation and expansion of luxury vinyl tile, sheet vinyl, and rigid-core flooring portfolios. These companies focus on design versatility, durability enhancements, and sustainable material development to meet rising demand across residential, commercial, and institutional environments. Regionally, Asia Pacific dominated the market with 34.8% share in 2024, supported by rapid urbanization, large-scale construction, and strong adoption of cost-effective flooring solutions. North America and Europe follow, driven by renovation trends and preference for high-performance, low-maintenance flooring materials.
Market Insights
- The Resilient Flooring Market was valued at USD 43,709.5 million in 2024 and is projected to grow at a CAGR of 6.5% through 2032.
- Rising renovation and remodeling activities across residential and commercial sectors drive demand, with the flexible LVT segment holding 41.8% share due to its durability, design versatility, and ease of installation.
- Key trends include accelerating adoption of sustainable, low-VOC flooring solutions and advanced digital printing technologies that enhance customization and aesthetic realism.
- Leading players such as Gerflor, Beaulieu, COREtec, Karndean, Interface, Armstrong Flooring, LG Hausys, Forbo, Amtico, and Congoleum expand product portfolios and strengthen manufacturing capabilities to meet evolving market demands.
- Asia Pacific led with 34.8% share in 2024, followed by North America at 32.4% and Europe at 27.1%, while the commercial application segment dominated with 48.5% share driven by high-traffic facility requirements.
 Market Segmentation Analysis:
By Product Type:
The Resilient Flooring Market is led by the flexible luxury vinyl tile (LVT) segment, which accounted for 41.8% share in 2024, driven by its superior design versatility, ease of installation, and strong performance in moisture-prone environments. Flexible LVT continues gaining traction in both residential and commercial renovations due to its comfort underfoot, wide aesthetic range, and cost efficiency. Rigid LVT follows with strong adoption in high-traffic areas for its dimensional stability, while sheet vinyl and other formats such as VCT remain relevant in budget-sensitive applications requiring durable and low-maintenance surfaces.
- For instance, Armstrong's StrataMax Pro vinyl sheet handles heavy traffic and high-moisture areas, while its Standard Excelon VCT uses 85% limestone in 12x12-inch tiles for economical commercial use in schools and retail.
By Price Range:
The medium price range segment dominated the Resilient Flooring Market with 46.3% share in 2024, supported by its balanced value proposition of enhanced durability, wider design options, and suitability for both residential and commercial spaces. This segment attracts consumers seeking premium performance without the high cost of luxury variants. The high-price range continues expanding due to rising demand for upscale interior finishes and advanced waterproofing technologies, while the low-price range remains preferred for large-scale projects prioritizing affordability over long-term performance benefits.
- For instance, Welspun Flooring's MultiStile™ vinyl tiles feature ScrapeGuard™ technology with UV coating for scratch protection and easy stick-on installation, ideal for residential upgrades in high-traffic areas.
By Application: The commercial segment led the Resilient Flooring Market with 48.5% share in 2024, driven by extensive use in retail spaces, offices, healthcare facilities, and education buildings seeking durable, easy-to-clean, and aesthetically adaptable flooring solutions. Commercial users prefer resilient flooring for its long lifecycle, stain resistance, and ability to withstand heavy foot traffic. Residential applications continue to grow with increasing home renovation activities and preference for waterproof surfaces, whereas the industrial segment gains traction in light-industrial spaces requiring slip-resistant and impact-resistant flooring materials.
Key Growth Drivers
Rising Renovation and Remodeling Activities
Growing global investment in residential and commercial renovation significantly drives the Resilient Flooring Market. Consumers increasingly prefer durable, moisture-resistant, and visually appealing flooring options like LVT for modernizing interiors. The surge in home improvement spending, expansion of commercial real estate, and upgrades in hospitality and retail spaces reinforce demand. Resilient flooring’s ease of installation, lower lifecycle cost, and compatibility with underfloor heating systems further accelerate adoption. Developers also favor resilient flooring for its ability to replicate natural materials while offering superior performance under heavy foot traffic.
- For instance, Havasu Regional Medical Center renewed its worn resilient flooring using Bona's Commercial System, completing the project in 18 hours instead of over 72 hours required for full replacement, while saving $20,000 plus labor costs.
Technological Advancements Enhancing Performance
Innovations in surface coatings, rigid core technology, embossing techniques, and digital printing are strengthening product performance and design diversity across the market. Advanced protective layers now deliver improved scratch resistance, waterproofing, and stain protection, making resilient flooring suitable for a broader array of applications. Manufacturers are investing in sustainable production technologies and recyclable materials, aligning with global green building standards. These advancements enhance product lifespan and aesthetic realism, attracting both commercial and residential buyers seeking long-lasting, high-performance flooring solutions.
- For instance, Engineered Floors' PureGrain Direct Digital Print DLVT uses digital emboss technology on a high-density SPC core, achieving high-resolution designs with five times greater color clarity and perfectly registered textures for realistic wood visuals.
Growing Adoption in Commercial and Institutional Facilities
The rapid expansion of retail, healthcare, education, and hospitality sectors fuels strong adoption of resilient flooring due to its durability, hygiene benefits, and ease of maintenance. Commercial spaces require materials that withstand heavy foot traffic while maintaining consistent visual quality, making LVT, sheet vinyl, and rigid core products preferred choices. The rise of modern office layouts, increased construction of clinics, and demand for slip-resistant flooring in public facilities further boost market growth. Additionally, resilient flooring supports faster installation, reducing operational downtime for high-traffic environments.
Key Trends & Opportunities
Shift Toward Sustainable and Low-Emission Flooring Solutions
Sustainability is emerging as a defining trend as manufacturers introduce low-VOC, phthalate-free, and recyclable resilient flooring products. Green building certifications such as LEED and BREEAM are strengthening the demand for environmentally responsible materials across commercial and residential projects. Bio-based backing materials, energy-efficient manufacturing, and closed-loop recycling programs present lucrative opportunities for innovation. With consumers and businesses prioritizing eco-friendly interiors, brands offering transparent environmental declarations and circular flooring models gain a competitive edge in the evolving market landscape.
- For instance, Tarkett has pioneered ultra-low VOC flooring since 2011, with emissions 10 to 100 times below stringent global standards and verified by Eurofins at Gold and Platinum levels for indoor air quality.
Expansion of Digital Printing and Customizable Designs
Advanced digital printing technologies are enabling highly realistic textures, enhanced color accuracy, and personalized flooring designs, unlocking substantial opportunities across hospitality, retail, and premium residential interiors. Custom patterns that mimic wood, stone, and ceramic with precision are driving preference for LVT and sheet vinyl. This shift allows architects and designers greater creative flexibility, supporting unique branding and thematic interior concepts. As personalization becomes a key purchasing factor, manufacturers offering agile design capabilities and faster production turnaround are expected to capture growing market demand.
- For instance, Mannington Commercial's Northern Wonder LVT collection leverages digital printing for very long pattern repeats and stretched-out colors that are exceptionally difficult to achieve with traditional rotogravure methods.
Key Challenges
Volatility in Raw Material Prices
Fluctuating prices of PVC, plasticizers, stabilizers, and other petrochemical-derived inputs create significant cost uncertainty for manufacturers in the Resilient Flooring Market. Any rise in crude oil prices impacts material procurement, production costs, and profit margins. Manufacturers often struggle to balance cost pressures without compromising quality or affordability for consumers. Additionally, supply chain disruptions and tightening environmental regulations on chemical components can further intensify volatility, making long-term pricing strategies and inventory planning increasingly challenging for market players.
Environmental Concerns and Recycling Limitations
Despite progress in sustainable product development, resilient flooring faces challenges related to end-of-life recycling and waste management. Many multilayer flooring structures are difficult to recycle due to mixed material compositions, limiting circularity and raising environmental concerns. Regulations targeting plastic waste reduction and strict emission standards add compliance burdens for manufacturers. Consumers and institutional buyers are increasingly scrutinizing environmental footprints, pushing companies to innovate with recyclable materials and cleaner manufacturing processes. However, scaling such technologies remains complex and cost-intensive for the industry.
Regional Analysis
North America
North America held a 32.4% share of the Resilient Flooring Market in 2024, driven by strong demand across residential renovations, commercial offices, retail spaces, and institutional buildings. The region benefits from high adoption of luxury vinyl tile due to its durability, moisture resistance, and design flexibility. Growth is further supported by rising home improvement spending, expanding multifamily housing construction, and increasing preference for low-maintenance flooring solutions. Manufacturers continue to invest in technologically advanced and eco-friendly product lines that align with sustainability standards, strengthening resilient flooring penetration across the United States and Canada.
Europe
Europe accounted for 27.1% share of the Resilient Flooring Market in 2024, supported by stringent environmental regulations and strong demand from commercial and industrial facilities. The region’s emphasis on sustainable building materials and low-VOC flooring fuels adoption of advanced vinyl formats and recyclable resilient flooring solutions. Rising refurbishment activities in residential and hospitality sectors further enhance market expansion. Countries such as Germany, the United Kingdom, and France lead consumption due to high investments in modern infrastructure and energy-efficient interiors, while southern Europe experiences growing uptake driven by increased construction and tourism-related facility upgrades.
Asia Pacific
Asia Pacific dominated the global Resilient Flooring Market with 34.8% share in 2024, propelled by rapid urbanization, expanding residential construction, and large-scale commercial development. Strong economic growth in China, India, and Southeast Asia continues to accelerate demand for cost-effective, durable, and stylish flooring materials. The region increasingly adopts luxury vinyl tile and sheet vinyl for modern housing, retail chains, and educational facilities. Rising disposable incomes, government housing initiatives, and growing investments in smart cities further strengthen market momentum. Additionally, the presence of major manufacturing hubs ensures competitive pricing and widespread product availability across the region.
Latin America
Latin America captured 3.4% share of the Resilient Flooring Market in 2024, with demand largely influenced by infrastructure modernization and increasing adoption of vinyl flooring in commercial and residential projects. Brazil and Mexico dominate consumption due to urban development and rising preference for economical, moisture-resistant flooring options. Growth is supported by expanding retail, hospitality, and healthcare construction activities. The shift toward low-maintenance interior materials and the availability of imported LVT and sheet vinyl products also contribute to market expansion. However, economic fluctuations and limited local manufacturing capacity present challenges to broader market penetration.
Middle East & Africa
The Middle East & Africa region accounted for 2.3% share in 2024, driven by rising construction of commercial complexes, hospitality properties, and premium residential communities. Countries such as the UAE, Saudi Arabia, and South Africa are key consumers, driven by investments in modern infrastructure and interior upgrades. The region increasingly adopts resilient flooring for its durability, heat resistance, and suitability for high-traffic environments. Growing tourism and retail expansion further support demand. However, market growth is moderated by price sensitivity and dependency on imports, although the long-term outlook remains positive with ongoing urban development initiatives.
Market Segmentations:
By Product Type
- Flexible luxury vinyl tile
- Rigid luxury vinyl tile
- Sheet vinyl
- Others (vinyl composition tile, etc.)
By Price Range
- Low
- Medium
- High
By Application
- Residential
- Commercial
- Industrial
By Distribution Channel
- Online
- Offline
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape of the Resilient Flooring Market features leading players such as Gerflor, Beaulieu, COREtec, Karndean, Interface, Armstrong Flooring, LG Hausys, Forbo, Amtico, and Congoleum, all driving innovation through product diversification, advanced technologies, and sustainability-focused strategies. These companies prioritize expanding their luxury vinyl tile, sheet vinyl, and rigid-core flooring portfolios to meet growing demand across residential, commercial, and institutional sectors. Many manufacturers invest heavily in digital printing, embossing techniques, and eco-friendly materials to enhance product realism and performance. Strategic initiatives such as mergers, capacity expansions, and distribution partnerships strengthen their global market presence. Additionally, ongoing R&D efforts focus on improving recyclability, strengthening wear layers, and developing low-VOC products aligned with green building standards. As consumer preferences shift toward durable, design-flexible, and cost-efficient flooring solutions, key players continue to enhance brand visibility, optimize supply chains, and expand offerings tailored to evolving end-user requirements.
Key Player Analysis
- Gerflor
- Beaulieu
- COREtec
- Karndean
- Interface
- Armstrong Flooring
- LG Hausys
- Forbo
- Amtico
- Congoleum
Recent Developments
- In November 2025, Beaulieu International Group (via its subsidiary New Congol LLC) acquired the assets of Congoleum Flooring, significantly expanding its U.S. presence and resilient flooring portfolio.
- In 2025, Gerflor Group completed the acquisition of Matter Surfaces, a U.S.-based provider of entrance systems and architectural surface products, broadening Gerflor’s commercial flooring and surface offerings.
- In December 2023, Karndean Designflooring acquired Go Resilient (Canada), strengthening its North American footprint and distribution capabilities.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Price Range, Application, Distribution Channel Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth driven by rising renovation and remodeling activities across residential and commercial sectors.
- Luxury vinyl tile demand will continue strengthening as consumers shift toward durable, waterproof, and design-rich flooring solutions.
- Technological advancements in rigid-core construction and digital printing will enhance product performance and aesthetic realism.
- Sustainability initiatives will accelerate adoption of low-VOC, recyclable, and bio-based resilient flooring materials.
- Commercial spaces will increasingly prefer resilient flooring for high-traffic durability and low maintenance benefits.
- Manufacturers will expand investments in eco-friendly production processes and circular recycling programs.
- Emerging economies will drive significant demand due to rapid urbanization and expanding construction activities.
- Customizable designs and advanced embossing will support premiumization trends across hospitality and retail environments.
- Distribution networks will strengthen through strategic partnerships and omnichannel retail expansion.
- Innovation in acoustic performance, impact resistance, and underfoot comfort will enhance long-term market adoption.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Resilient Flooring Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Resilient Flooring Market projected to grow between 2024 and 2032?
Which Resilient Flooring Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Resilient Flooring Market?
Who are the leading companies in the Resilient Flooring Market?
Which region commanded the largest share of the Resilient Flooring Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 43,709.5 million → 2032: USD 72,339.03 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Resilient Flooring Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Resilient Flooring Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Resilient Flooring Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Resilient Flooring Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Resilient Flooring Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Resilient Flooring Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Resilient Flooring Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Resilient Flooring Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 43,709.5 million → 2032: USD 72,339.03 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Resilient Flooring Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Resilient Flooring Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Resilient Flooring Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Resilient Flooring Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

