
United States Home Improvement Market Overview:
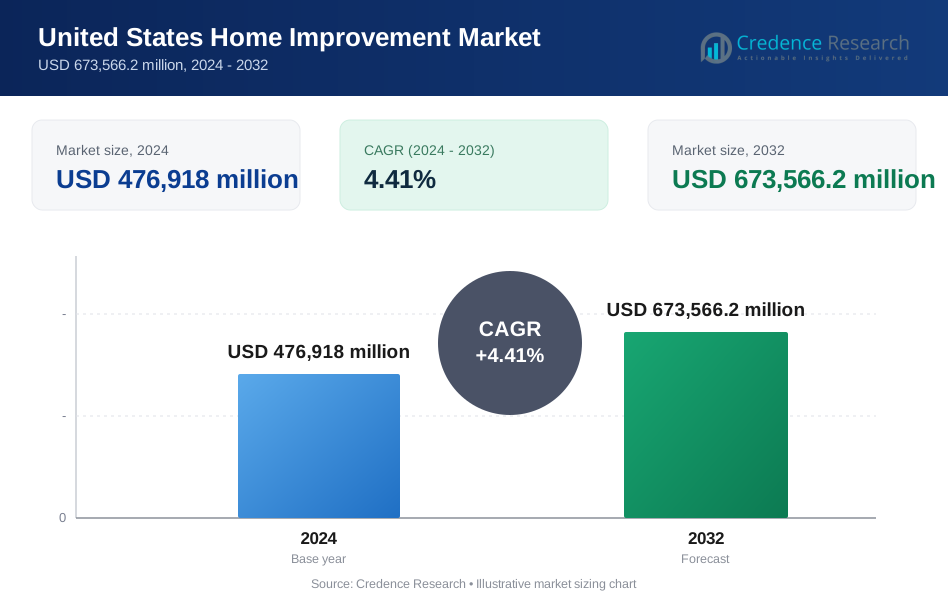
The United States Home Improvement Market size was valued at USD 476,918 million in 2024 and is anticipated to reach USD 673,566.2 million by 2032, expanding at a CAGR of 4.41% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| United States Home Improvement Market Size 2024 | USD 476,918million |
| United States Home Improvement Market, CAGR | 4.41% |
| United States Home Improvement Market Size 2032 | USD 673,566.2 million |
United States Home Improvement Market Insights
- The United States Home Improvement Market growth is driven by aging housing stock, rising home equity access, and higher spending on remodeling, repairs, and energy-efficiency upgrades across residential properties.
- The United States Home Improvement Market shows strong shifts toward DIFM, where DIFM held 64.8% share in 2024 versus DIY at 35.2%, supported by demand for professional workmanship and complex renovation needs.
- The United States Home Improvement Market remains led by major retailers, manufacturers, and service providers, with strong emphasis on omnichannel retailing, contractor networks, smart-home upgrades, and sustainable product portfolios.
- The United States Home Improvement Market is regionally led by the South with 34.6% share in 2024, followed by the Midwest at 23.4%, Northeast at 21.8%, and West at 20.2%, reflecting housing activity, renovation intensity, and premium upgrade demand.

United States Home Improvement Market Segmentation Analysis:
By Project:
In the United States Home Improvement Market, the DIFM (Do-It-For-Me) segment dominated the By Project category, accounting for 64.8% market share in 2024, while DIY held 35.2%. DIFM leadership is driven by rising project complexity, growing preference for professional workmanship, and increased spending on large-scale renovations such as roofing, electrical upgrades, and plumbing. Aging housing stock and strict building codes further encourage homeowners to rely on licensed contractors. Higher disposable income among middle- and high-income households and financing options offered by service providers continue to reinforce DIFM demand across residential projects.
- For instance, DNM Plumbing & Heating executed full bathroom renovations, reconfiguring layouts with new fixtures, vanities, and pipes while overhauling systems for water efficiency in older residences.
By End Use:
Within the By End Use segment of the United States Home Improvement Market, Kitchen improvement & additions emerged as the dominant sub-segment, holding a 29.6% market share in 2024, followed by bath improvement & additions at 23.4%. Kitchen dominance is supported by high renovation frequency, premium appliance upgrades, cabinetry replacements, and strong homeowner focus on property value enhancement. Open-layout remodeling trends, energy-efficient fixtures, and smart kitchen integrations further stimulate demand. Rising home resale activity and lifestyle-driven renovation spending continue to position kitchen improvements as the primary revenue contributor within end-use applications.
- For instance, Samsung's Bespoke AI Family Hub refrigerator, showcased at CES 2025, uses AI Vision Inside sensors to detect 37 fresh ingredients and 50 processed foods, enabling inventory tracking via its display or app for seamless smart kitchen integration.
Key Growth Drivers
Aging Housing Stock and Rising Renovation Demand
The United States Home Improvement Market continues to expand due to the aging residential housing stock, with a large proportion of homes requiring structural upgrades, system replacements, and aesthetic renovations. Older properties demand frequent improvements in roofing, plumbing, electrical systems, insulation, and exterior materials to meet safety standards and energy-efficiency requirements. Homeowners increasingly prioritize renovation over relocation, driving consistent investment in both essential repairs and value-enhancing upgrades. This trend sustains long-term demand across interior, exterior, and system-focused home improvement projects nationwide.
- For instance, Lowe's promotes attic insulation upgrades using products like InsulSafe SP blown-in fiberglass, which fills hard-to-reach areas to achieve R-38 standards at least 12 inches thick for enhanced thermal performance in pre-1990 homes needing energy efficiency improvements.
Growth in Home Equity and Consumer Spending Power
Rising home equity levels and steady disposable income growth significantly support the United States Home Improvement Market. Higher property valuations allow homeowners to access financing through home equity loans and credit lines, enabling larger renovation budgets. Consumers increasingly invest in premium remodeling projects such as kitchen upgrades, bathroom expansions, and exterior enhancements. This financial flexibility encourages spending on high-quality materials, advanced fixtures, and professional installation services, strengthening market expansion across urban and suburban residential segments.
Increasing Preference for Professional Renovation Services
The growing shift toward professional renovation services is a key driver in the United States Home Improvement Market. Homeowners increasingly select DIFM solutions due to complex project requirements, safety considerations, and limited personal time. Professional contractors offer expertise, regulatory compliance, and warranty-backed services, increasing consumer confidence. Additionally, large retailers and service providers are expanding integrated offerings that combine materials, installation, and post-project support, driving higher project values and sustained demand for professional home improvement services.
- For instance, Lowe's partners with licensed, insured, and background-checked independent installers for projects like kitchen appliances, cabinets, countertops, bathroom fixtures including toilets and vanities, flooring, roofing, siding, and exterior doors, backed by a one-year labor warranty.
Key Trends and Opportunities
Rising Adoption of Smart and Energy-Efficient Home Improvements
Smart home integration and energy-efficient upgrades represent a major trend and opportunity within the United States Home Improvement Market. Homeowners increasingly incorporate smart lighting, thermostats, security systems, and connected appliances during renovation projects. Demand for energy-efficient windows, insulation, HVAC systems, and solar-ready roofing continues to rise due to energy cost concerns and sustainability goals. Incentive programs and utility rebates further accelerate adoption, creating long-term opportunities for manufacturers, contractors, and technology-driven solution providers.
- For instance, Google's Nest Learning Thermostat optimizes heating and cooling by learning user habits and adjusting for weather, delivering 10-15% savings on heating and cooling costs in user studies.
Expansion of Digital Platforms and Omnichannel Retail Models
Digital transformation and omnichannel retail expansion present strong growth opportunities in the United States Home Improvement Market. Consumers rely on online tools for product research, design visualization, cost estimation, and contractor selection. Retailers offering virtual consultations, augmented reality planning tools, and seamless online-to-offline purchasing experiences gain increased customer engagement. These digital capabilities reduce project uncertainty, improve purchasing confidence, and support higher conversion rates, reinforcing long-term market growth.
- For instance, Home Depot's mobile app features augmented reality tools like Project Color, allowing customers to visualize paint shades or place items such as patio furniture in their spaces via smartphone camera.
Key Challenges
Raw Material Price Volatility and Supply Chain Disruptions
The United States Home Improvement Market faces ongoing challenges from volatile raw material prices and supply chain disruptions. Fluctuations in lumber, metals, cement, and insulation costs increase overall project expenses and complicate budgeting for homeowners and contractors. Material shortages and delayed deliveries can extend project timelines and reduce operational efficiency. These constraints limit affordability and may delay discretionary renovation projects, particularly among price-sensitive residential consumers.
Skilled Labor Shortages and Increasing Installation Costs
Skilled labor shortages remain a critical challenge for the United States Home Improvement Market. An aging workforce, limited skilled trade participation, and rising demand for renovation services contribute to higher labor costs and longer project completion times. Shortages are especially pronounced in specialized trades such as electrical, plumbing, and structural remodeling. Increasing labor expenses raise overall project costs, placing pressure on service providers and impacting renovation affordability for homeowners.
Regional Analysis
Northeast
The Northeast accounted for 21.8% market share in 2024 in the United States Home Improvement Market, driven by an aging housing stock and high renovation intensity across urban and suburban areas. Older residential properties in states such as New York, Massachusetts, and Pennsylvania require frequent upgrades in roofing, insulation, plumbing, and electrical systems. Strong demand for interior replacements, kitchen remodeling, and energy-efficient retrofitting supports market growth. High property values and renovation-focused homeownership trends encourage reinvestment rather than relocation, sustaining consistent spending on professional home improvement services across the region.
Midwest
The Midwest held a 23.4% market share in 2024 within the United States Home Improvement Market, supported by widespread single-family housing and steady renovation demand. States including Illinois, Ohio, Michigan, and Minnesota show strong activity in exterior replacements, roofing, siding, and weatherproofing projects due to climatic conditions. Cost-effective remodeling, DIY participation, and essential maintenance upgrades remain prominent across the region. Rising investments in bathroom improvements and interior renovations further strengthen demand, while moderate home prices encourage homeowners to allocate budgets toward functional and value-enhancing upgrades.
South
The South dominated the United States Home Improvement Market with a 34.6% market share in 2024, reflecting high housing activity and population growth across states such as Texas, Florida, Georgia, and North Carolina. Rapid residential construction, frequent remodeling, and strong demand for exterior upgrades drive regional leadership. Climate-related needs boost spending on roofing, windows, HVAC systems, and storm-resistant materials. Rising homeownership rates, suburban expansion, and increasing disposable income further accelerate renovation spending, positioning the South as the largest and fastest-growing regional contributor to market revenues.
West
The West accounted for 20.2% market share in 2024 in the United States Home Improvement Market, driven by premium renovation projects and sustainability-focused upgrades. States such as California, Washington, and Colorado emphasize energy-efficient remodeling, smart home integration, and modern interior replacements. High property values encourage homeowners to invest in kitchen upgrades, bathroom renovations, and outdoor living enhancements. Strong adoption of smart technologies and environmentally compliant materials supports higher project values, while renovation demand remains robust across both coastal and inland residential markets.
United States Home Improvement Market Size Segmentations:
By Project
- DIY
- DIFM
By End Use
- Kitchen improvement & additions
- Bath improvement & additions
- Exterior replacements
- Interior replacements
- Other room additions & alterations
By Geography
- Northeast
- Midwest
- South
- West
Competitive Landscape
The United States Home Improvement Market features a diverse and highly fragmented ecosystem led by key players including Lowe’s Companies, The Home Depot, Masco Corporation, FirstService Corporation, Kohler, Belfor, American Exteriors, DKI Ventures, and Crane Renovation Group. The market structure combines large home improvement retailers, manufacturers, and professional service providers, creating strong competition across product supply, installation services, and end-to-end renovation solutions. Leading retailers strengthen their positions through expansive store networks, private-label brands, and integrated DIFM offerings, while manufacturers focus on innovation in fixtures, cabinetry, and energy-efficient products. Service-oriented companies gain share by expanding contractor networks, restoration capabilities, and bundled service models. Strategic acquisitions, partnerships with local contractors, and digital service platforms enhance customer reach and operational efficiency. Continuous investment in omnichannel retailing, smart home solutions, and sustainable materials remains central to competitive differentiation and long-term market positioning.
Key Player Analysis
- Kohler
- Belfor
- Masco Corporation
- Crane Renovation Group
- Lowe's Companies
- DKI Ventures, LLC
- Henkel Corporation
- FirstService Corporation
- American Exteriors
- Coit Services, Inc.
Recent Developments
- In September 2025, The Home Depot completed the acquisition of GMS Inc. through its subsidiary SRS Distribution, enhancing its multi-category building materials distribution for professional customers.
- In August 2025, Lowe’s Companies, Inc. announced an agreement to acquire Foundation Building Materials, a leading North American distributor of interior building products, strengthening its professional contractor business.
- In December 2025, The Home Depot launched the Home Depot Creator Portal, a new platform engaging influencers and designers to drive home improvement project inspiration and customer engagement.
Report Coverage
The research report offers an in-depth analysis based on Project, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The United States Home Improvement Market will continue to expand as homeowners prioritize renovation over relocation.
- Demand for professional DIFM services will increase due to rising project complexity and time constraints.
- Energy-efficient upgrades will gain stronger adoption driven by sustainability goals and energy cost concerns.
- Smart home integration will become a standard component of major renovation projects.
- Aging housing infrastructure will sustain long-term demand for structural and system upgrades.
- Omnichannel retail models will further reshape purchasing behavior and project planning processes.
- Contractor consolidation and service network expansion will improve service availability and scale.
- Labor productivity improvements through technology adoption will partially offset workforce shortages.
- Exterior renovations will grow steadily due to climate resilience and property value considerations.
- Innovation in materials and installation methods will enhance efficiency and overall project outcomes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Aging Housing Stock and Renovation Demand
A significant portion of U.S. homes are decades old, requiring frequent upgrades to roofing, plumbing, electrical systems, and insulation. This drives sustained investment in both essential repairs and value-enhancing renovations, as homeowners prioritize improving existing properties over moving.
Growth in Home Equity and Consumer Spending Power
Rising home values and increased access to home equity loans enable homeowners to finance larger and more frequent renovation projects. This financial flexibility supports spending on premium upgrades, advanced fixtures, and professional installation services.
Increasing Preference for Professional Renovation Services (DIFM)
Homeowners are increasingly opting for professional contractors due to the complexity of projects, safety regulations, and limited personal time. This shift is reinforced by the need for licensed expertise and warranty-backed services, boosting demand for DIFM solutions.
Rising Adoption of Smart and Energy-Efficient Upgrades
Homeowners are integrating smart technologies and energy-efficient solutions such as connected appliances, smart thermostats, and high-performance insulation to reduce energy costs and meet sustainability goals. Incentives and rebates further accelerate this trend.
Expansion of Digital Platforms and Omnichannel Retail
The growth of digital tools for project planning, visualization, and contractor selection, along with seamless online-to-offline retail experiences, is making home improvement projects more accessible and increasing consumer confidence, thereby driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the United States Home Improvement Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the United States Home Improvement Market projected to grow between 2024 and 2032?
Which United States Home Improvement Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the United States Home Improvement Market?
Who are the leading companies in the United States Home Improvement Market?
Which region commanded the largest share of the United States Home Improvement Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Kitchen improvement & additions
- 1.2.2 Bath improvement & additions
- 1.2.3 Exterior replacements
- 1.2.4 Interior replacements
- 1.2.5 Other room additions & alterations
- 1.3 By Project
- 1.3.1 DIY
- 1.3.2 DIFM (Do-It-For-Me)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 476,918 million → 2032: USD 673,566.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 United States Home Improvement Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 United States Home Improvement Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 United States Home Improvement Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 United States Home Improvement Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 United States Home Improvement Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 United States Home Improvement Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 United States Home Improvement Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 United States Home Improvement Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 476,918 million → 2032: USD 673,566.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 United States Home Improvement Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Kitchen improvement & additions
- 12.3.7.2 Bath improvement & additions
- 12.3.7.3 Exterior replacements
- 12.3.7.4 Interior replacements
- 12.3.7.5 Other room additions & alterations
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Project - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 DIY
- 12.4.7.2 DIFM (Do-It-For-Me)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 United States Home Improvement End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 United States Home Improvement Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 United States Home Improvement Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 United States Home Improvement Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Lowe's Companies
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 The Home Depot
- 18.4 Masco Corporation
- 18.5 FirstService Corporation
- 18.6 Kohler
- 18.7 Belfor
- 18.8 American Exteriors
- 18.9 DKI Ventures
- 18.10 Crane Renovation Group
- 18.11 Henkel Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

