
Market Overview
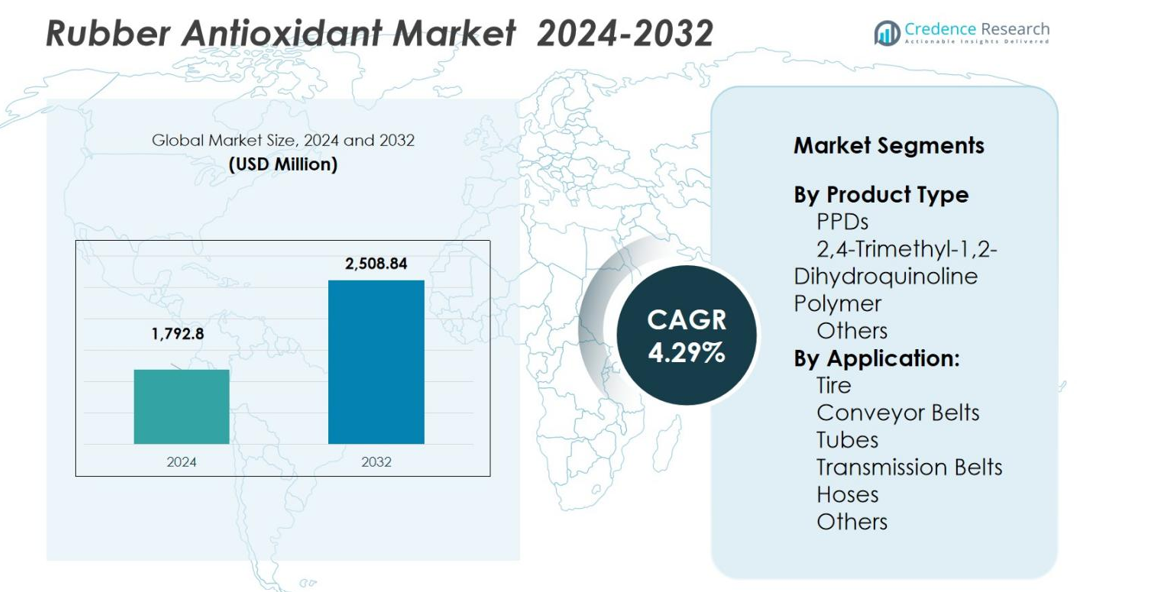
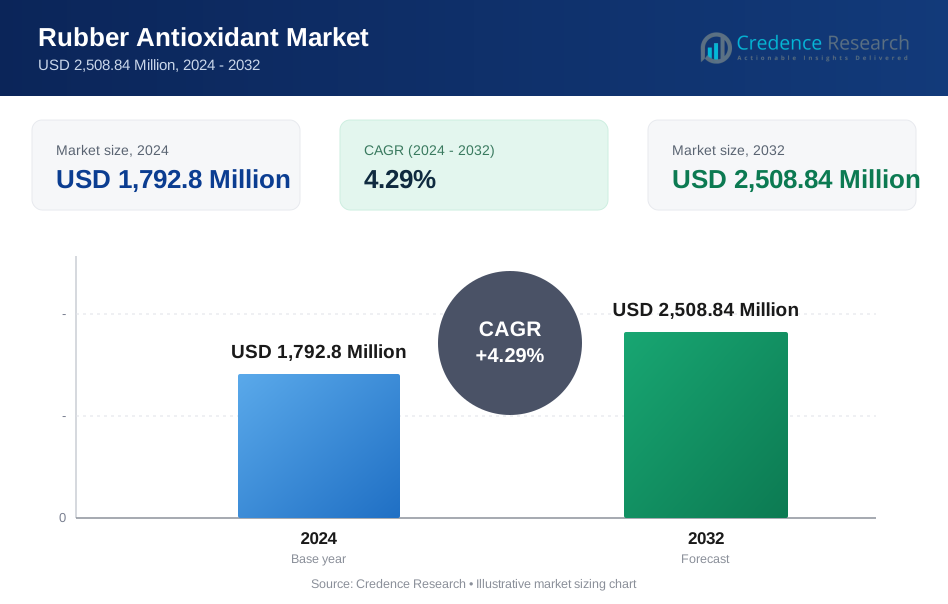
The Rubber Antioxidant Market size was valued at USD 1,792.8 Million in 2024 and is anticipated to reach USD 2,508.84 Million by 2032, at a CAGR of 4.29% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Rubber Antioxidant Market Size 2024 | USD 1,792.8 Million |
| Rubber Antioxidant Market, CAGR | 4.29% |
| Rubber Antioxidant Market Size 2032 | USD 2,508.84 Million |
The Rubber Antioxidant Market involves leading players such as Eastman Chemical Company, Kumho Petrochemical Co., Ltd., Lanxess AG, Agrofert (Duslo) and NOCIL Limited who shape the market through broad product portfolios and global reach. These companies invest heavily in R&D to develop high‑performance antioxidants tailored for tire, hose and tube applications, thereby securing significant market positions. Among regions, the Asia Pacific region leads with 48.3% of the global market share, owing to strong tire manufacturing, industrial rubber production and cost‑effective chemical manufacturing in countries like China and India.
Market Insights
- The Rubber Antioxidant Market size was valued at USD 1,792.8 Million in 2024 and is projected to reach USD 2,508.84 Million by 2032, growing at a CAGR of 4.29% during the forecast period.
- Increasing demand for tires, particularly in the automotive sector, is a primary driver, as antioxidants enhance the durability and performance of rubber products, with the tire segment holding a 45% share in 2024.
- A key trend is the growing shift towards eco-friendly and sustainable rubber antioxidants, driven by rising environmental awareness and regulatory pressures, leading to innovations in biodegradable formulations.
- Competitive dynamics are shaped by key players like Eastman Chemical Company, Kumho Petrochemical, and NOCIL, who maintain strong market presence through R&D, strategic expansions, and tailored product offerings.
- Asia Pacific leads the market with a 48.3% share in 2024, followed by North America and Europe, where automotive and industrial applications are driving substantial demand for high-performance rubber antioxidants.
Market Segmentation Analysis:
By Product Type:
The Rubber Antioxidant Market is segmented into PPDs, 2,4-Trimethyl-1,2-Dihydroquinoline Polymer, and Others. Among these, PPDs (Phenolic Antioxidants) dominate the market, accounting for 55% of the total share in 2024. This dominance is driven by the high demand for PPDs in tire manufacturing due to their superior performance in preventing oxidative degradation. Their widespread use in enhancing the durability and performance of rubber products, especially under extreme conditions, makes them a critical component in the industry.
- For instance,Lanxess introduced Vulkanox HS Scopeblue, a sustainable rubber additive based on TMQ, to help tire manufacturers produce longer-lasting and more eco-friendly tires with low volatility and migration tendencies.
By Application:
The market for Rubber Antioxidants is significantly driven by the Tire segment, which holds a major share of 45% in 2024. Tires require antioxidants to prevent degradation from heat, UV light, and ozone exposure, thereby extending their life and improving performance. The increasing demand for tires, particularly in the automotive sector, is fueling the growth of this segment. Additionally, rising awareness of safety and sustainability standards, alongside advancements in tire technologies, contributes to the ongoing dominance of the tire application within the Rubber Antioxidant Market.
- For instance, Indian startup Biopole introduced Biozone 200, a bio-based antiozonant, and Biovive 300, a bio-based antioxidant, derived from cotton stalks to enhance rubber product durability in the tire industry.
Key Growth Drivers
Increasing Demand for Tires
The Rubber Antioxidant Market is experiencing significant growth due to the rising demand for tires, which constitutes the largest application segment. Tires require antioxidants to improve their performance and longevity by preventing oxidative degradation from heat, ozone, and UV exposure. The global increase in vehicle production, coupled with the growing automotive industry, especially in emerging markets, continues to drive the demand for high-performance tires. This, in turn, fuels the need for effective rubber antioxidants, supporting market growth.
- For instance, Continental has pioneered the use of a certified biocircular antioxidant called TMQ, made from recycled cooking oil, which reduces the carbon footprint of its tires by over 30% while maintaining antioxidant performance.
Advancements in Rubber Industry Technology
Technological advancements in the rubber industry, particularly in the manufacturing of high-performance rubber products, are another key driver. Innovations such as the development of eco-friendly antioxidants and the incorporation of antioxidants in various rubber applications, including industrial hoses and conveyor belts, are boosting market growth. The demand for durable, high-quality rubber products across industries like automotive, manufacturing, and aerospace is pushing the adoption of advanced antioxidant solutions that enhance product performance and durability, further propelling the market.
- For instance, Suzano and Behn Meyer have partnered to incorporate Suzano’s lignin-based bioproduct Ecolig as a multifunctional sustainable additive in Behn Meyer’s rubber portfolio, positioning it as a partial replacement for fossil-based antioxidants to improve oxidation resistance in industrial and tire rubber compounds.
Regulatory and Environmental Initiatives
Environmental regulations that encourage the use of safer, non-toxic chemicals in manufacturing processes are driving the growth of the Rubber Antioxidant Market. As governments worldwide impose stricter regulations to reduce the environmental impact of rubber products, the demand for green antioxidants has increased. Companies are focusing on producing more sustainable rubber antioxidants, which are safer for the environment and comply with global regulatory standards, helping to expand the market share of eco-friendly antioxidant solutions.
Key Trends & Opportunities
Sustainability and Eco-friendly Solutions
A significant trend in the Rubber Antioxidant Market is the shift towards sustainable and eco-friendly products. As consumers and industries become more environmentally conscious, there is a growing preference for rubber antioxidants that are biodegradable, non-toxic, and produced with minimal environmental impact. This trend presents significant opportunities for companies to innovate and develop green antioxidant solutions that meet sustainability standards, opening up new markets and attracting eco-conscious customers.
- For instance, Synthomer established an ISCC PLUS-certified value chain integrating bio-based feedstock materials linked to at least 20% bio content through mass balance approach, manufacturing certified sustainable products at its Pasir Gudang facility in Malaysia while maintaining equivalent quality and performance characteristics as fossil fuel-based alternatives.
Growth in Emerging Markets
Emerging markets, particularly in Asia-Pacific and Latin America, are showing strong growth potential for the Rubber Antioxidant Market. Rapid industrialization, urbanization, and increased demand for vehicles in these regions are driving the demand for rubber products such as tires, belts, and hoses. The expanding manufacturing sector in countries like China and India presents an opportunity for market players to expand their footprint and cater to the growing demand for high-performance rubber antioxidants.
- For instance, LANXESS India completed an expansion of its Rhenodiv® production plant at the Jhagadia site in February 2024. This new production line uses advanced technology to improve efficiency in producing tire release agents, supporting the growing tire and rubber goods market in the region.
Key Challenges
Price Volatility of Raw Materials
One of the major challenges facing the Rubber Antioxidant Market is the price volatility of raw materials. The production of rubber antioxidants depends on various petrochemical derivatives, and fluctuations in the prices of raw materials like petroleum can lead to increased production costs. This uncertainty can affect the profitability of manufacturers and hinder the overall market growth, particularly when raw material prices rise unexpectedly due to geopolitical factors or supply chain disruptions.
Health and Safety Concerns
Health and safety concerns associated with the use of certain rubber antioxidants, especially those containing toxic components, pose a challenge to market growth. Strict health and safety regulations, along with increased scrutiny from regulatory bodies, are pushing manufacturers to shift toward safer alternatives. However, the transition to non-toxic antioxidants requires significant investment in research and development, and any delay in compliance could result in market restrictions, affecting industry growth.
Regional Analysis
Asia Pacific
The Asia Pacific region held 48.3% of the global rubber antioxidant market in 2024, led by high industrial and automotive demand, particularly from countries such as China and India. Rapid expansion in tire manufacturing and rubber goods production underpins this share, while cost-effective chemical manufacturing in the region further strengthens its dominance. The strong growth trajectory in infrastructure, construction, and automotive sectors continues to drive antioxidant uptake in rubber applications across the region.
North America
North America accounted for 20.0% of the global rubber antioxidant market in 2024, supported by a mature automotive industry and robust industrial rubber goods demand. The region’s high standards for performance and durability in rubber products, together with significant replacement tire demand, fuel consistent antioxidant consumption. Innovation in eco-friendly antioxidant solutions and growing usage in high-performance sectors such as electric vehicles also contribute to the region’s stable position in the market.
Europe
Europe held 18.0% of the global rubber antioxidant market in 2024, driven by a strong automotive manufacturing base and stringent environmental and regulatory norms. German, French, and UK tire and industrial rubber manufacturers heavily rely on advanced antioxidant additives to meet longevity and compliance requirements. The transition toward sustainable and green-certified antioxidant formulations is reshaping the region’s product landscape and reinforcing its distinctive market share.
Latin America
Latin America secured 8.0% of the global rubber antioxidant market in 2024. The region’s growth is propelled by rising automotive production and expanding industrial rubber goods manufacturing, especially in Brazil and Mexico. However, lower industrial maturity, supply-chain constraints, and economic instability moderate its share. Chemical suppliers targeting partnership models and capacity expansion stand to capture rising downstream demand in hoses, conveyor belts, and tubes.
Middle East & Africa
The Middle East & Africa region captured 5.7% of the global rubber antioxidant market in 2024. Infrastructure development, construction, and mining-related rubber product requirements drive demand for antioxidant-treated hoses, tubes, and belts. Nonetheless, the region’s fragmented manufacturing base, geopolitical uncertainties, and lower chemical processing capabilities restrain broader growth and limit its share relative to other regions.
Market Segmentations:
By Product Type
- PPDs
- 2,4-Trimethyl-1,2-Dihydroquinoline Polymer
- Others
By Application:
- Tire
- Conveyor Belts
- Tubes
- Transmission Belts
- Hoses
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape in the global rubber antioxidant market is shaped by key players such as Eastman Chemical Company, Kumho Petrochemical Co., Ltd., Lanxess AG, Agrofert (Duslo) and NOCIL Limited who dominate the market through extensive product portfolios and global reach. These firms leverage strong R&D capabilities to develop high‑performance antioxidants tailored for applications in tires, hoses, tubes and conveyor systems, thereby maintaining their leadership. In addition, these enterprises pursue strategic partnerships, capacity expansions and regional manufacturing footprints to secure supply chain resilience and regional responsiveness. Meanwhile, the market also features a fragmented layer of mid‑tier and regional players vying for niche specialty segments and green antioxidant formulations. Competitive pressure from these players exerts downward pricing trends, compelling leaders to focus on operational efficiency, product differentiation and sustainability credentials to preserve margin and market share.
Key Player Analysis
- Kemai Chemical
- Xian Yu-Chem
- Jiangsu Sinorgchem Technology
- Ouchi Shinko Chemical
- Agrofert (Duslo)
- General Quimica
- Shandong Ekesen Chemical
- Lanxess
- Kumho Petrochemical
- NOCIL
Recent Developments
- In February 2025, Lanxess AG launched its sustainable rubber additive Vulkanox HS Scopeblue to support tyre manufacturers in producing longer‑lasting, environmentally‑friendly tyres.
- In November 2025, Safic-Alcan expanded its partnership with SI Group to extend the distribution of SI Group's antioxidant portfolio for various markets starting January 1, 2026. This partnership strengthens their market presence in antioxidant solutions.
- In May 2023, Kumho Petrochemical Co., Ltd. introduced an eco‑friendly antioxidant series compatible with high‑performance synthetic rubber, targeting automotive and industrial applications in Europe and North America.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Growing demand from automotive tire production will continue to drive rubber antioxidant consumption as manufacturers seek longer‑lasting, high‑performance rubber compounds.
- Expansion in electric vehicle (EV) manufacturing will boost need for advanced antioxidants that can withstand higher torque, load and thermal stress in EV tire and rubber applications.
- Rising infrastructure and industrial development, especially in Asia‑Pacific, will increase demand for rubber products such as conveyor belts, hoses and tubes, thereby elevating antioxidant usage.
- Regulatory pressure for low‑toxicity, eco‑friendly additives will push producers to invest in sustainable antioxidant formulations and expand green product portfolios.
- Adoption of smart manufacturing and automation in chemical production will improve efficiency, quality and reliability of antioxidant supply, supporting market growth.
- Raw‑material price volatility and supply‑chain disruptions will encourage manufacturers to optimise sourcing strategies and diversify feedstock origins.
- Emerging economies will present strong growth opportunities as industrialisation, urbanisation and rubber goods manufacturing expand in these regions.
- Formulation innovation will accelerate, with development of synergistic antioxidant blends and bio‑based alternatives that offer improved durability and environmental compliance.
- Competitive pressure will intensify as global leaders and regional players expand capacity, pursue M&A and tailor regionalised manufacturing to capture market share.
- Market expansion may face constraints from regulatory hurdles on chemical usage and disposal, prompting the industry to focus on circular‑economy practices and end‑of‑life rubber product recycling.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for Tires
The surge in global vehicle production and automotive sector growth, especially in emerging markets, is driving demand for tires, which are the largest application for rubber antioxidants. Antioxidants are essential for enhancing tire durability and performance by preventing oxidative degradation from heat, ozone, and UV exposure.
Shift Toward Eco-friendly and Sustainable Antioxidants
Rising environmental awareness and stricter regulatory standards are pushing manufacturers to develop and adopt biodegradable, non-toxic, and sustainable rubber antioxidants. This trend is opening new market opportunities and driving innovation in green formulations.
Technological Advancements in Rubber Manufacturing
Innovations in rubber compounding, such as the development of high-performance and eco-friendly antioxidants, are enabling the production of more durable and reliable rubber products. These advancements are particularly important for demanding applications in automotive, industrial, and infrastructure sectors.
Expansion of Industrial and Infrastructure Sectors in Asia Pacific
Rapid industrialization, urbanization, and infrastructure development in Asia Pacific, especially in China and India, are fueling demand for rubber products like conveyor belts, hoses, and tubes. This, in turn, is boosting the consumption of rubber antioxidants in the region.
Regulatory and Environmental Initiatives
Global regulations mandating the use of safer, low-toxicity chemicals in manufacturing are encouraging the adoption of green antioxidant solutions. Compliance with these standards is driving market growth as companies invest in sustainable product development to meet regulatory requirements.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Rubber Antioxidant Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Rubber Antioxidant Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Rubber Antioxidant Market?
Which are the significant players leveraging the rubber antioxidant market growth?
Who are the leading companies in the Rubber Antioxidant Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Tire
- 1.2.2 Conveyor Belts
- 1.2.3 Tubes
- 1.2.4 Transmission Belts
- 1.2.5 Hoses
- 1.2.6 Others
- 1.3 By Product Type
- 1.3.1 PPDs
- 1.3.2 2,4-Trimethyl-1,2-Dihydroquinoline Polymer
- 1.3.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,792.8 Million → 2032: USD 2,508.84 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Rubber Antioxidant Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Rubber Antioxidant Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Rubber Antioxidant Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Rubber Antioxidant Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Rubber Antioxidant Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Rubber Antioxidant Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Rubber Antioxidant Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Rubber Antioxidant Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,792.8 Million → 2032: USD 2,508.84 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Rubber Antioxidant Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Tire
- 12.3.7.2 Conveyor Belts
- 12.3.7.3 Tubes
- 12.3.7.4 Transmission Belts
- 12.3.7.5 Hoses
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 PPDs
- 12.4.7.2 2,4-Trimethyl-1,2-Dihydroquinoline Polymer
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Rubber Antioxidant End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Rubber Antioxidant Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Rubber Antioxidant Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Rubber Antioxidant Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Eastman Chemical Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Kumho Petrochemical Co., Ltd.
- 18.4 Lanxess AG
- 18.5 Agrofert (Duslo)
- 18.6 NOCIL Limited
- 18.7 Kemai Chemical
- 18.8 Xian Yu-Chem
- 18.9 Jiangsu Sinorgchem Technology
- 18.10 Ouchi Shinko Chemical
- 18.11 General Quimica
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

