
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Tire Market Size 2024 | USD 144,430 million |
| Automotive Tire Market , CAGR | 3.9% |
| Automotive Tire Market Size 2032 | USD 196,147 million |
Market Overview
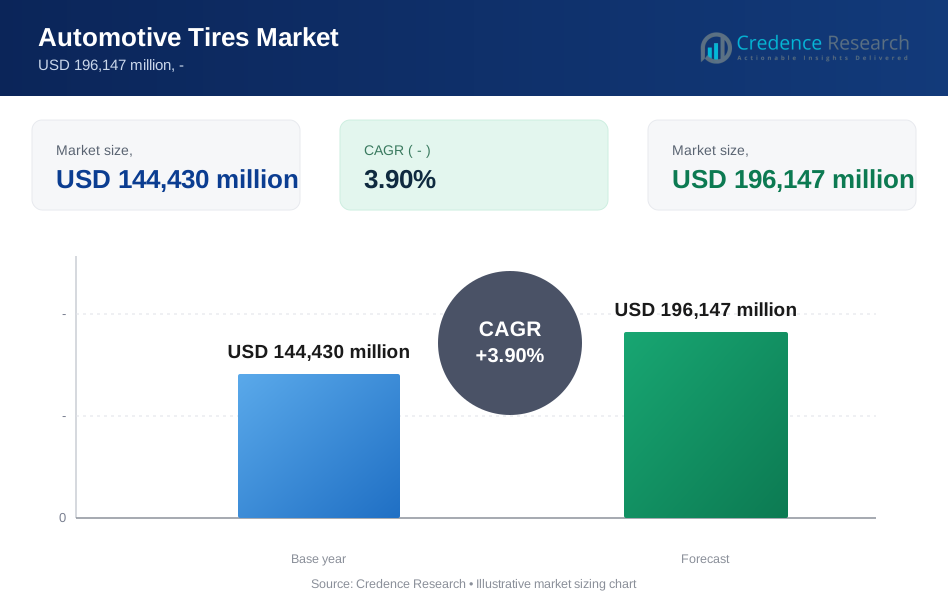
The Global Automotive Tire Market is projected to grow from USD 144,430 million in 2024 to an estimated USD 196,147 million based on 2032, with a compound annual growth rate (CAGR) of 3.9% from 2025 to 2032.
Key drivers influencing market growth include the expanding global automotive fleet, growing focus on fuel economy, and the rising popularity of electric vehicles (EVs) that require specialized tire designs. Consumers are increasingly inclined toward all-season and run-flat tires, driving innovation in tread design and rubber compounds. Additionally, sustainability trends are pushing manufacturers to invest in eco-friendly raw materials and circular tire recycling practices. Smart tire technologies that monitor real-time pressure, wear, and temperature are becoming more prevalent, enhancing safety and performance.
Geographically, Asia Pacific dominates the automotive tire market due to its large vehicle production base and rising consumer demand, particularly in China and India. Europe and North America follow, driven by premium vehicle sales and stringent safety regulations. Leading key players in the global market include Bridgestone Corporation, Michelin Group, Continental AG, Goodyear Tire & Rubber Company, Pirelli & C. S.p.A., Sumitomo Rubber Industries, Hankook Tire & Technology, and Yokohama Rubber Company.
Market Insights
- The Global Automotive Tire Market is projected to grow from USD 144,430 million in 2024 to USD 196,147 million by 2032, registering a CAGR of 3.9% from 2025 to 2032.
- Increasing global vehicle production and ownership, especially in emerging markets, continues to drive steady demand for OEM and replacement tires.
- Consumers are shifting toward low rolling resistance and smart tire technologies to enhance fuel economy, safety, and overall vehicle performance.
- The growing electric vehicle fleet demands specialized tire designs, creating new innovation and revenue opportunities for tire manufacturers.
- Fluctuations in the prices of natural rubber and petroleum-based materials impact production costs and profit margins across the industry.
- Asia Pacific dominates the global market share due to large-scale vehicle production, rising disposable incomes, and expanding road networks.
- Developed markets emphasize high-performance, eco-friendly, and smart tires, backed by stringent regulations and consumer preferences.
Market Drivers
Growth in Global Vehicle Production and Sales is Driving Tire Demand
The Global Automotive Tire Market benefits significantly from the steady growth in global vehicle production and sales. Rising disposable income in developing economies has led to increased vehicle ownership, supporting higher demand for both OEM and replacement tires. Consumer preference is shifting toward personal mobility, pushing automakers to scale up production. It directly translates into a higher volume of tire requirements. The need for frequent tire replacement due to wear, road conditions, and usage patterns further reinforces market momentum. The growing adoption of passenger and commercial vehicles continues to create a stable foundation for tire manufacturers.
- For instance, the adoption of smart tires equipped with sensors for pressure and wear monitoring is rising, enhancing safety and performance in passenger and commercial vehicles.
Rising Focus on Fuel Efficiency and Vehicle Performance
The increasing emphasis on fuel efficiency and vehicle performance is influencing tire design and material innovation. Low rolling resistance tires are gaining traction for their ability to improve fuel economy and reduce emissions. Consumers and regulators are both demanding better energy efficiency, pushing tire manufacturers to develop lightweight, durable, and performance-oriented products. The Global Automotive Tire Market is responding with innovations in tread patterns, rubber compounds, and internal structures. It supports automakers' goals of meeting emission regulations without compromising driving experience. These trends ensure consistent R\&D investment across the industry.
- For instance, Michelin, Bridgestone, and Goodyear collectively hold a significant market share, with Michelin leading at 14-17%, followed by Bridgestone at 13-16%, and Goodyear at 9-11%
Surge in Electric Vehicle Adoption is Creating Specialized Tire Demand
The transition toward electric vehicles is reshaping tire performance requirements. EVs exert different loads and torque compared to conventional vehicles, leading to unique wear patterns and acoustic demands. Tire manufacturers are developing EV-specific tires that offer enhanced grip, noise reduction, and durability. It is helping manufacturers align product portfolios with the evolving vehicle mix. The Global Automotive Tire Market is witnessing growing partnerships between EV makers and tire companies to co-develop optimized solutions. This shift is expected to accelerate as EV penetration rises globally.
Safety Regulations and Technological Advancements Fuel Innovation
Government regulations around road safety and tire labeling standards are pushing the market toward higher-quality, compliant products. It is encouraging tire makers to focus on advanced monitoring technologies, such as smart tires with real-time pressure and temperature sensors. Consumers are also valuing features like puncture resistance and run-flat capabilities. These factors are increasing the adoption of premium tire offerings across vehicle segments. The Global Automotive Tire Market is evolving into a more technology-driven landscape, with product differentiation becoming key to competitive advantage.
Market Trends
Shift Toward Sustainable and Eco-Friendly Tire Materials
Tire manufacturers are increasingly prioritizing the use of sustainable and recyclable materials in tire production. This shift is driven by rising environmental concerns and regulatory pressure to reduce carbon footprints. Companies are exploring bio-based rubbers, silica from rice husk ash, and recycled tire components to improve sustainability. The Global Automotive Tire Market is aligning its innovation strategies with circular economy goals. It is encouraging industry players to invest in green manufacturing processes and closed-loop recycling systems. These trends are gaining traction among environmentally conscious consumers and government bodies alike.
- For instance, in March 2024, GRI introduced its next-generation sustainable specialty tires, including the GREEN XLR EARTH series, featuring up to 93.5% sustainable material content, showcasing the industry's commitment to eco-friendly innovation.
Adoption of Smart Tire Technologies Across Vehicle Segments
Smart tire technology is emerging as a key trend that enhances safety, performance, and vehicle diagnostics. Sensors embedded in tires allow real-time monitoring of parameters such as air pressure, tread depth, and temperature. This data improves vehicle maintenance and reduces the risk of accidents. It is especially relevant for fleet operators and premium vehicle segments seeking enhanced operational efficiency. The Global Automotive Tire Market is integrating digital technologies to meet growing expectations for connected and intelligent mobility solutions. OEMs are beginning to collaborate with tire makers to standardize smart tire systems across new models.
- For instance, the U.S. Department of Transportation reported that 42,915 motor vehicle traffic fatalities occurred in 2021, highlighting the increasing need for smart tire technology to enhance road safety.
Rising Popularity of All-Season and Run-Flat Tires
Consumer preferences are shifting toward tires that offer versatility, reliability, and convenience. All-season tires eliminate the need for seasonal replacements, appealing to drivers in regions with moderate climates. Run-flat tires, which continue functioning after a puncture, are becoming standard in high-end and safety-conscious vehicles. The market is responding with innovations that combine durability with enhanced driving comfort. The Global Automotive Tire Market is seeing growing demand for tire types that reduce maintenance and improve user experience. It is expanding product portfolios to cater to these evolving customer expectations.
Influence of Urbanization and E-Commerce on Replacement Demand
The growth of urban centers and the expansion of e-commerce logistics are driving increased vehicle usage and wear-and-tear cycles. Light commercial vehicles and last-mile delivery fleets require frequent tire replacements due to higher mileage and stop-and-go traffic patterns. It is creating strong demand in the aftermarket segment for cost-effective and performance-based tire solutions. The Global Automotive Tire Market is adapting to this trend with high-durability and quick-installation tire options. It supports the operational needs of logistics providers and urban commuters alike.
Market Challenges
Volatility in Raw Material Prices and Supply Chain Disruptions
The Global Automotive Tire Market faces persistent challenges due to fluctuations in raw material prices, particularly natural rubber, synthetic rubber, and petroleum-based inputs. These materials are subject to geopolitical tensions, climate variability, and regulatory changes, which disrupt procurement strategies and inflate production costs. It creates pricing pressures that affect profit margins and limit manufacturers' ability to invest in R\&D. Supply chain disruptions, including port congestion and shipping delays, further impact the timely delivery of components and finished tires. Smaller manufacturers with limited sourcing flexibility are especially vulnerable. Companies must adopt strategic sourcing and inventory management practices to remain competitive.
- For instance, a total of 2,388 million tire units were produced globally in 2023, reflecting the industry's scale and demand
Environmental Regulations and Waste Management Constraints
Stricter environmental regulations on tire production, disposal, and emissions are creating compliance challenges across regions. Governments are enforcing standards that require manufacturers to reduce pollutants and improve recycling rates. The Global Automotive Tire Market must align with evolving policies while ensuring product performance and durability. It is difficult for companies to balance environmental goals with cost efficiency, particularly in developing markets with limited infrastructure. Tire waste management remains a critical issue, as landfilling and incineration pose long-term ecological risks. Advancing circular economy models and sustainable disposal technologies is essential to address this growing concern.
Market Opportunities
Expansion of Electric and Autonomous Vehicle Segments
The growing adoption of electric and autonomous vehicles presents significant opportunities for tire innovation. These vehicles impose unique performance demands, including low rolling resistance, high load capacity, and noise reduction. Tire manufacturers can capitalize by developing specialized products tailored to the needs of EVs and AVs. The Global Automotive Tire Market is well-positioned to support this transition by investing in advanced materials and design capabilities. It enables firms to establish strategic partnerships with automakers and technology providers. This segment offers high-margin potential due to the premium specifications required for emerging vehicle technologies.
Rising Demand in Emerging Economies and Urban Mobility
Rapid urbanization and economic development in Asia Pacific, Latin America, and Africa are increasing vehicle ownership and mobility needs. Growing middle-class populations and infrastructure development are fueling demand for both new and replacement tires. It creates opportunities for manufacturers to expand distribution networks and introduce affordable, durable tire options. The Global Automotive Tire Market can strengthen its footprint in these regions by offering localized solutions and engaging in capacity-building initiatives. Government investments in road transport and smart city programs also support long-term market expansion. Capturing this demand requires a focus on adaptability, cost-efficiency, and brand trust.
Market Segmentation Analysis
By Season Type
The Global Automotive Tire Market is segmented by season type into summer, all-season, and winter tires. All-season tires dominate the market due to their adaptability in moderate weather conditions and widespread use across North America and Asia Pacific. Consumers prefer all-season variants for their cost-effectiveness and reduced need for seasonal changeovers. Summer tires hold strong demand in performance-oriented and warmer-climate regions where dry traction and handling are critical. Winter tires maintain steady growth in colder geographies, supported by safety regulations and seasonal demand peaks. It enables manufacturers to offer diversified product lines tailored to regional climate needs.
By Rim Size
Segmenting the market by rim size reveals growing traction in the 15 to 20 inches category, driven by increasing sales of SUVs, crossovers, and premium sedans. This segment balances performance and affordability, making it a popular choice among both OEMs and aftermarket consumers. Tires below 15 inches continue to serve compact and budget vehicles, especially in developing markets. Demand for tires above 20 inches is rising due to the growing penetration of luxury vehicles and off-road models. It presents high-margin opportunities for premium tire brands catering to niche performance applications
By Vehicle Type
The vehicle type segment includes passenger vehicles, commercial vehicles, and electric vehicles. Passenger vehicles account for the largest share, supported by high ownership rates and frequent replacement needs. Commercial vehicles generate consistent demand through logistics, construction, and transportation sectors that require durable, high-mileage tires. The electric vehicle segment is emerging as a fast-growing category, prompting tire makers to develop low-noise, energy-efficient designs. It drives innovation and strategic partnerships between tire manufacturers and EV producers.
Segments
Based on Season Type
- Summer
- All-Season and Winter
Based on Rim Size
- Less Than 15 Inches
- 15 to 20 Inches
- More than 20 Inches
Based on Vehicle Type
- Passenger Vehicle
- Commercial Vehicle
- Electric Vehicle
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
Asia Pacific Automotive Tire Market
Asia Pacific holds the largest share of the global Automotive Tire Market, accounting for nearly 42% in 2024. Strong vehicle production volumes in China, India, Japan, and South Korea support this dominance. Rising disposable incomes and rapid urbanization have led to increased vehicle ownership, fueling consistent demand for both OEM and replacement tires. Government infrastructure investments and a growing middle class are also accelerating market expansion. It benefits from the presence of leading manufacturers and cost-effective production facilities. The region remains central to the global supply chain and continues to attract foreign investment in tire manufacturing.
North America Automotive Tire Market
North America commands around 23% of the global Automotive Tire Market, supported by high passenger vehicle ownership and advanced automotive infrastructure. Consumers in the U.S. and Canada show strong preference for all-season and performance tires. The replacement tire segment dominates due to strict safety norms and regular vehicle inspections. It benefits from a mature aftermarket and widespread use of light trucks and SUVs. Innovation in smart tires and EV-compatible designs is gaining traction. Domestic tire makers and premium global brands compete actively in this market.
Europe Automotive Tire Market
Europe represents approximately 20% of the Automotive Tire Market, driven by high automotive standards and stringent environmental regulations. Germany, France, and the UK lead the region in tire consumption, supported by strong OEM presence and export-oriented vehicle production. It faces growing demand for winter and all-season tires due to changing weather patterns and regulatory mandates. Sustainable manufacturing practices and eco-labeled tires are gaining importance. The market is also seeing rising adoption of run-flat and noise-reduction technologies. Tire recycling initiatives are prominent across the region.
Latin America Automotive Tire Market
Latin America accounts for around 7% of the global Automotive Tire Market, with Brazil and Mexico as key contributors. Economic development and industrial growth are supporting vehicle sales across the region. It sees steady demand in both passenger and commercial segments, though pricing sensitivity remains a challenge. Growth opportunities exist in expanding replacement tire networks and local manufacturing capabilities. Government focus on road development and regional logistics enhances commercial vehicle activity. Imported tires continue to make up a large portion of the market share.
Middle East and Africa Automotive Tire Market
The Middle East and Africa hold a combined share of 5% in the Automotive Tire Market. Increasing vehicle imports and infrastructure expansion support long-term growth. The market is largely driven by commercial and off-road vehicle usage due to challenging terrains and construction activity. It faces challenges related to high import dependency and limited local production. Gulf countries like Saudi Arabia and the UAE are showing growing interest in performance and premium tire segments. Seasonal temperature extremes drive demand for durable and heat-resistant tire variants.
Key players
- CEAT Limited
- Nokian Tyres plc.
- Continental AG
- Sailun Group Co., Ltd
- Apollo Tyres Ltd.
- Hankook & Company Co., Ltd
- JK Tyre & Industries Ltd.
- Bridgestone Corporation (Bandag LLC)
- Pirelli & C. S.p.A.
- MRF Limited
Competitive Analysis
The Automotive Tire Market is highly competitive, with global and regional players focusing on product innovation, brand positioning, and strategic distribution. Leading companies such as Bridgestone, Continental, and Pirelli invest in R\&D to enhance performance, durability, and sustainability. Emerging players like Sailun and CEAT are expanding their international presence through cost-effective offerings and regional partnerships. It is characterized by high brand loyalty and strong OEM collaborations, especially in North America, Europe, and Asia Pacific. Competitive advantage depends on technology integration, supply chain strength, and responsiveness to evolving vehicle platforms, including EVs. Manufacturers are also enhancing digital retail networks to capture a larger share of the aftermarket segment.
Recent Developments
- In January 2025, Nokian Tyres plc launched the Surpass™ AS01, a new ultra-high-performance all-season tire featuring puncture-resistant Aramid fibers, enhancing durability and safety.
- In April 2025, Continental AG announced plans to discontinue its agricultural tire segment by the end of 2025, focusing its Commercial Specialty Tires business on material handling, earthmoving, and port operations.
- In May 2025, Sailun Group Co., Ltd introduced "liquid gold" tires utilizing a novel chemical rubber material to reduce rolling resistance and enhance wet skid resistance, aiming to improve driving safety and energy efficiency.
- In April 2025, Apollo Tyres Ltd. expanded its AWE 723+ dual excavator tire range by adding two new sizes, catering to mid-size and compact excavators, and showcased them at Bauma 2025.
- In May 2025, Hankook & Company Co., Ltd reported that electric vehicle tires accounted for 23% of its original equipment tire sales for passenger cars and light trucks, reflecting a 6 percentage point increase year-over-year.
- In March 2025, Bridgestone Corporation unveiled two new tires featuring ENLITEN technology at TMC 2025, aiming to enhance performance and sustainability in commercial applications.
Market Concentration and Characteristics
The Automotive Tire Market exhibits moderate to high market concentration, with a few dominant players controlling a significant global share. It features a blend of multinational corporations and strong regional brands competing on price, performance, and distribution reach. Tier-1 companies focus on innovation, sustainability, and OEM partnerships, while smaller players cater to price-sensitive aftermarket segments. The market is capital-intensive, requiring continual investment in technology, quality control, and regulatory compliance. Product differentiation is achieved through advancements in tread design, materials, and smart tire technology. It remains dynamic, shaped by shifts in mobility trends, electrification, and consumer preferences for performance and durability.
Report Coverage
The research report offers an in-depth analysis based on Season Type, Rim Size, Vehicle Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Smart tires with embedded sensors for real-time monitoring will see wider adoption in both passenger and commercial vehicles to enhance safety and efficiency.
- The rising penetration of electric vehicles will create demand for low-noise, energy-efficient tires specifically designed to withstand higher torque and load characteristics.
- Manufacturers will increasingly use eco-friendly materials and adopt circular economy practices, including tire recycling and green manufacturing processes.
- E-commerce platforms for tire purchases and services will grow as consumers seek convenience, competitive pricing, and access to wider product ranges.
- Consumers will continue to shift toward premium and performance tires, especially in developed markets, where driving comfort, speed, and handling are priorities.
- Tire companies will deepen collaborations with automakers to co-develop tire technologies aligned with emerging vehicle platforms, including autonomous and connected cars.
- The replacement tire segment will maintain strong growth, driven by aging vehicle fleets, increasing mileage, and rising awareness of road safety.
- Asia Pacific will remain the largest and fastest-growing regional market due to strong vehicle production, infrastructure investments, and growing middle-class populations.
- Tire manufacturers will leverage AI and data analytics to optimize product design, predict maintenance needs, and personalize consumer engagement.
- Tighter global regulations on tire performance, emissions, and labeling will push manufacturers to improve durability, fuel efficiency, and environmental compliance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Global Vehicle Production and Sales
Rising disposable incomes and urbanization, especially in emerging economies, are increasing vehicle ownership and production, directly boosting demand for both OEM and replacement automotive tires.
Rising Focus on Fuel Efficiency and Vehicle Performance
Consumers and regulators are prioritizing fuel economy and lower emissions, driving tire manufacturers to innovate with low rolling resistance and performance-oriented designs that support these goals.
Surge in Electric Vehicle Adoption
The growing penetration of electric vehicles is creating demand for specialized tires that address unique EV requirements such as higher torque, increased load, and noise reduction, opening new revenue streams for tire makers.
Stringent Safety Regulations and Technological Advancements
Government regulations on tire safety and labeling are pushing manufacturers to develop advanced products, including smart tires with embedded sensors, enhancing safety and performance and driving market growth.
Shift Toward Sustainable and Eco-Friendly Materials
Environmental concerns and regulatory pressures are encouraging manufacturers to adopt sustainable materials and recycling practices, aligning with consumer preferences and supporting long-term market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Automotive Tires Market?
What factors are driving the growth of the Automotive Tires market?
What are some challenges faced by the Automotive Tires market?
Which segment is leading the market share?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Rim Size
- 1.2.1 Less Than 15 Inches
- 1.2.2 15 to 20 Inches
- 1.2.3 More than 20 Inches
- 1.3 By Season Type
- 1.3.1 Summer
- 1.3.2 All-Season
- 1.3.3 Winter
- 1.4 By Vehicle Type
- 1.4.1 Passenger Vehicle
- 1.4.2 Commercial Vehicle
- 1.4.3 Electric Vehicle
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 144,430 million → 2032: USD 196,147 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Tires Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Tires Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Tires Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Tires Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Tires Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Tires Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Tires Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Tires Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 144,430 million → 2032: USD 196,147 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Tires Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Rim Size - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Less Than 15 Inches
- 12.3.7.2 15 to 20 Inches
- 12.3.7.3 More than 20 Inches
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Season Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Summer
- 12.4.7.2 All-Season
- 12.4.7.3 Winter
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Passenger Vehicle
- 12.5.7.2 Commercial Vehicle
- 12.5.7.3 Electric Vehicle
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Tires Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automotive Tires Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automotive Tires Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Bridgestone Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Michelin Group
- 17.4 Continental AG
- 17.5 Goodyear Tire & Rubber Company
- 17.6 Pirelli & C. S.p.A.
- 17.7 Sumitomo Rubber Industries
- 17.8 Hankook Tire & Technology
- 17.9 Yokohama Rubber Company
- 17.10 Apollo Tyres Ltd.
- 17.11 CEAT Limited
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

